
 Mefentrifluconazole Market | 2026-2036
Mefentrifluconazole Market Size, Share, and Industry Trends Forecast 2026-2036
Mefentrifluconazole Market Analytics
Modular formulation bundling is pivoting how growers purchase fungicide solutions across Europe. BASF SE leverages its integrated R&D pipeline to sustain proprietary formulation advantages. Syngenta AG anchors its position through deep distributor relationships across Mediterranean horticulture markets.
Mefentrifluconazole is a triazole fungicide with a unique isopropanol substituent that inhibits C14-demethylase in fungal ergosterol biosynthesis, delivering broad-spectrum control of Ascomycete and Basidiomycete pathogens in cereal and specialty crops. Formulations dominate value capture due to proprietary adjuvant systems and patent-protected delivery mechanisms, while bulk chemicals occupy thinner margin tiers supplying generic blenders. Crop Protection applications lead volume demand, though Soil Treatment represents the fastest-expanding segment as precision agriculture expands subsurface application methods.
EMA and EFSA frameworks govern residue tolerance thresholds and ecotoxicology benchmarks for mefentrifluconazole approvals across EU member states, while REACH compliance mandates full substance dossiers for import and formulation activities. The EU Green Deal's Farm to Fork strategy tightens allowable chemical inputs, redirecting R&D investment toward reduced-rate formulations and biological combination products. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national derogation requests as sustainability targets tighten.
Market Dynamics
Modular formulation bundling is restructuring fungicide procurement across European specialty crop sectors, compressing traditional distributor margins while elevating integrated solution providers.
Growth Catalysts
- EU Green Deal Farm to Fork targets:The strategy tightens allowable chemical inputs, redirecting R&D investment toward reduced-rate mefentrifluconazole formulations and biological combination products.
- Precision agriculture expansion:Subsurface application methods accelerate soil treatment segment growth as variable-rate technology penetrates Mediterranean horticulture.
- Spain's citrus export sector:Phytosanitary requirements for Asian market access drive fungicide upgrade cycles in Valencia and Murcia growing regions.
Market Restraints
- REACH compliance dossier costs:Full substance documentation mandates for import and formulation activities impose fixed cost burdens on smaller blenders.
- Active ingredient concentration limits:EFSA residue tolerance thresholds cap maximum application rates in cereal protection programs.
- Biological fungicide substitution:Bacillus-based and Trichoderma alternatives gain vineyard share in organic-certified French appellations.
Strategic Opportunities
- Poland's apple orchard modernization:Post-Common Agricultural Policy restructuring drives fungicide upgrade demand in Pomorskie and Mazowieckie provinces.
- Drone-based aerial application:UAV spraying services reduce labor costs in Portuguese and Greek mountainous terrain.
- EMA streamlined assessment pathways:Parallel national evaluation procedures accelerate product authorization timelines for novel formulation submissions.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in triazole-adjuvant compatibility commands premium compensation, constraining mid-tier blender expansion.
- Batch-to-batch residue variability:Climate-driven fungal pressure fluctuations complicate label-rate compliance in field conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mefentrifluconazole Market |
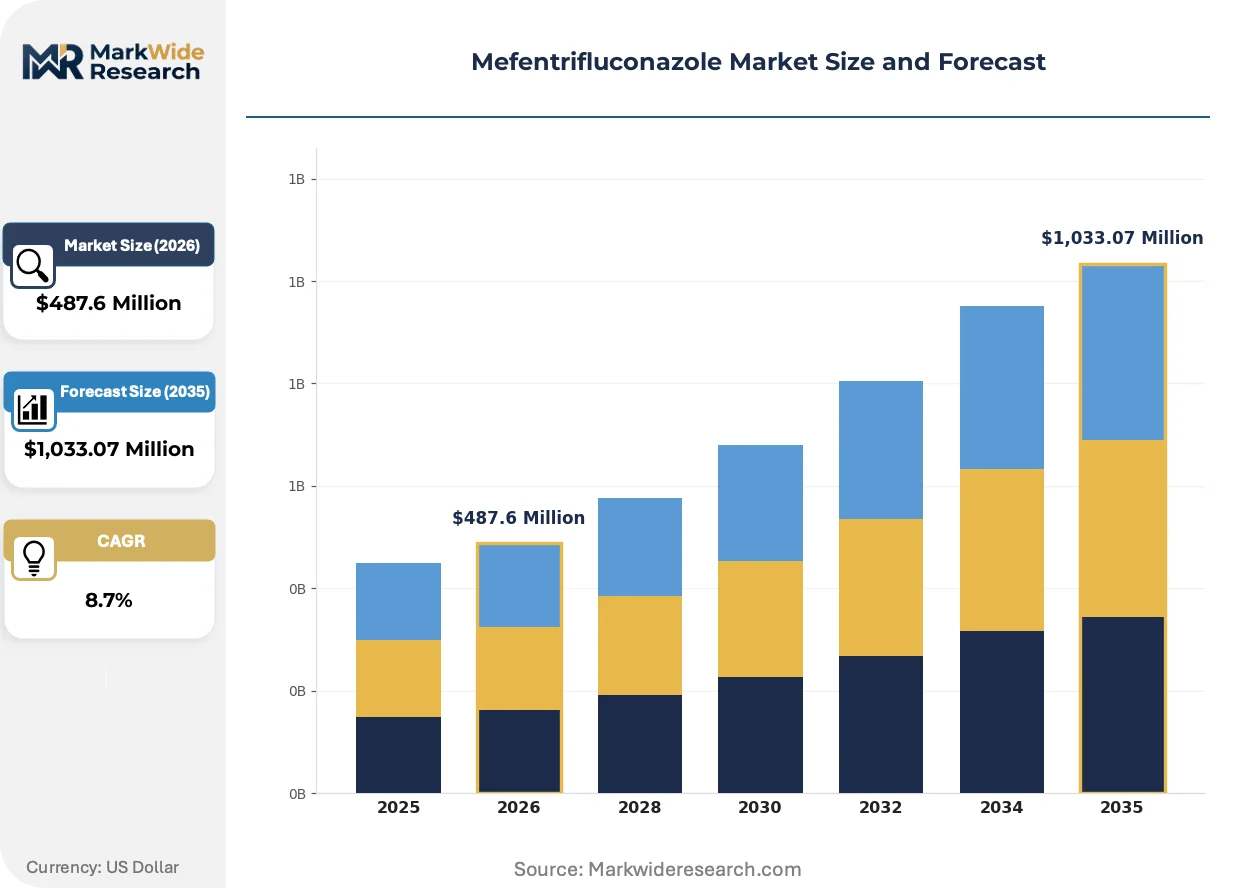
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Formulations, Intermediates, End Products, Bulk Chemicals Application: Agricultural Practices, Crop Protection, Pest Control, Soil Treatment End Use Industry: Agriculture, Horticulture, Forestry, Aquaculture Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | FMC Corporation, Sumitomo Chemical Co., Ltd., BASF SE, Nufarm Limited, ADAMA Agricultural Solutions Ltd., Bayer Aktiengesellschaft, Corteva Agriscience, UPL Limited, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mefentrifluconazole Market Evolving Landscape
Formulation science and application technology are converging to redefine value capture in fungicide markets, with proprietary delivery mechanisms displacing commodity active ingredient trading.
Microencapsulation technology is unifying controlled-release performance with tank-mix compatibility. Specialty grape and stone fruit growers in Italy's Veneto region adopt these formulations at accelerating pace. The technology is unifying previously separate fungicide and plant health product categories into single-application programs.
REACH authorization sunset clause reviews are tightening data requirements for existing registrations. Mefentrifluconazole dossiers face expanded ecotoxicology endpoints for soil macroorganism impacts. Cereal protection applications in Germany's Brandenburg and Saxony-Anhalt regions experience the steepest compliance cost escalation.
Direct-to-grower digital platforms are fragmenting traditional distributor relationships. Younger farm operators in France's Nouvelle-Aquitaine region source fungicides through agronomic decision-support apps rather than cooperative buying groups. The Netherlands' glasshouse vegetable sector exhibits the most advanced platform penetration, with subscription-based crop protection programs replacing per-hectare product purchases.
Mefentrifluconazole Market Segmentation
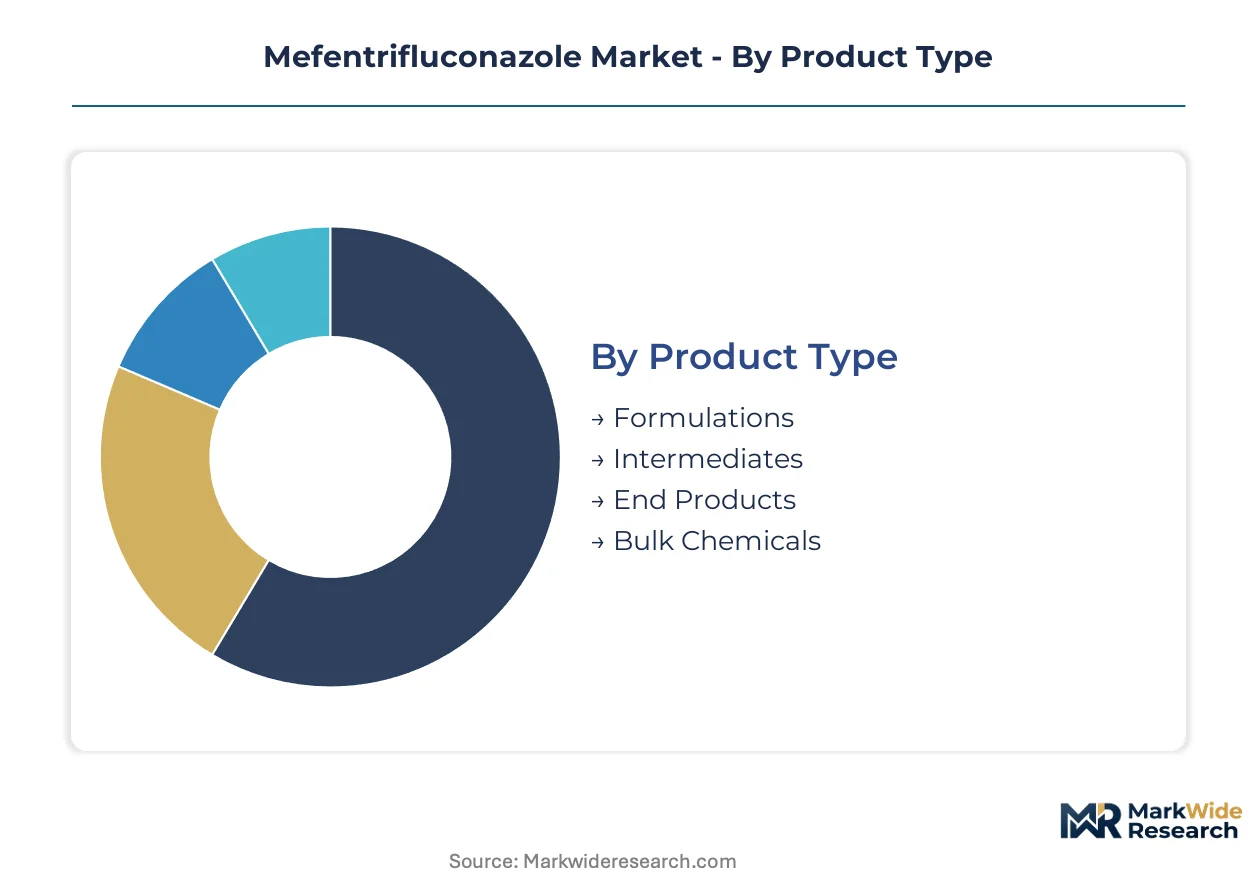
Mefentrifluconazole procurement patterns diverge sharply between proprietary formulation buyers and commodity chemical purchasers. Understanding these splits reveals where margin capture concentrates and which customer profiles drive technology upgrade cycles.
Product Type:
Volume concentrates in commodity tiers while premium capture flows to proprietary delivery systems.
- Formulations:Proprietary adjuvant systems and patent-protected delivery mechanisms command superior margins through enhanced rainfastness and leaf penetration. Specialty grape growers in France's Champagne region and stone fruit operators in Italy's Emilia-Romagna drive concentrated demand for microencapsulated variants.
- End Products:Finished fungicide packages incorporating mefentrifluconazole as the active backbone serve cereal protection programs across Germany's eastern grain belt. EFSA residue tolerance thresholds shape maximum concentration specifications for these ready-to-apply formats.
- Intermediates:Partially processed chemical streams supply captive formulation operations at major agrochemical manufacturers.
- Bulk Chemicals:Generic blenders source technical-grade active ingredient for regional private-label compounding.
Today's leader: Formulations. Tomorrow's challenger: End Products.
Application:
Surface protection dominates current volumes while subsurface methods gain technology traction.
- Crop Protection:Foliar spray applications against Ascomycete and Basidiomycete pathogens anchor demand in cereal and specialty crop sectors. German Brandenburg and Saxony-Anhalt regions exhibit the steepest compliance cost escalation under REACH authorization reviews.
- Soil Treatment:Precision agriculture expansion accelerates variable-rate subsurface application methods across Mediterranean horticulture. Valencia and Murcia citrus operations adopt these protocols fastest for root-zone fungal management.
- Agricultural Practices:Integrated pest management protocols incorporate mefentrifluconazole within rotation strategies against resistance development.
- Pest Control:Non-crop applications in amenity turf and ornamental plantings generate specialized formulation requirements.
Current volume anchor: Crop Protection. Steepest expansion trajectory: Soil Treatment.
End Use Industry:
Field-scale agriculture absorbs bulk volumes while intensive horticulture commands premium positioning.
- Agriculture:Broad-acre cereal and oilseed production across Poland's Pomorskie and Mazowieckie provinces drives post-CAP restructuring upgrade cycles. Large-scale cooperatives negotiate direct procurement contracts with formulation suppliers.
- Horticulture:High-value protected cultivation in the Netherlands' Westland glasshouse cluster and Spain's Almería greenhouse belt prioritizes residue-compliant formulations for export market access.
- Forestry:Nursery stock protection and plantation establishment programs generate seasonal demand spikes.
- Aquaculture:Fungal control in aquatic plant culture represents a niche technical application segment.
Margin concentration: Horticulture. Volume foundation: Agriculture.
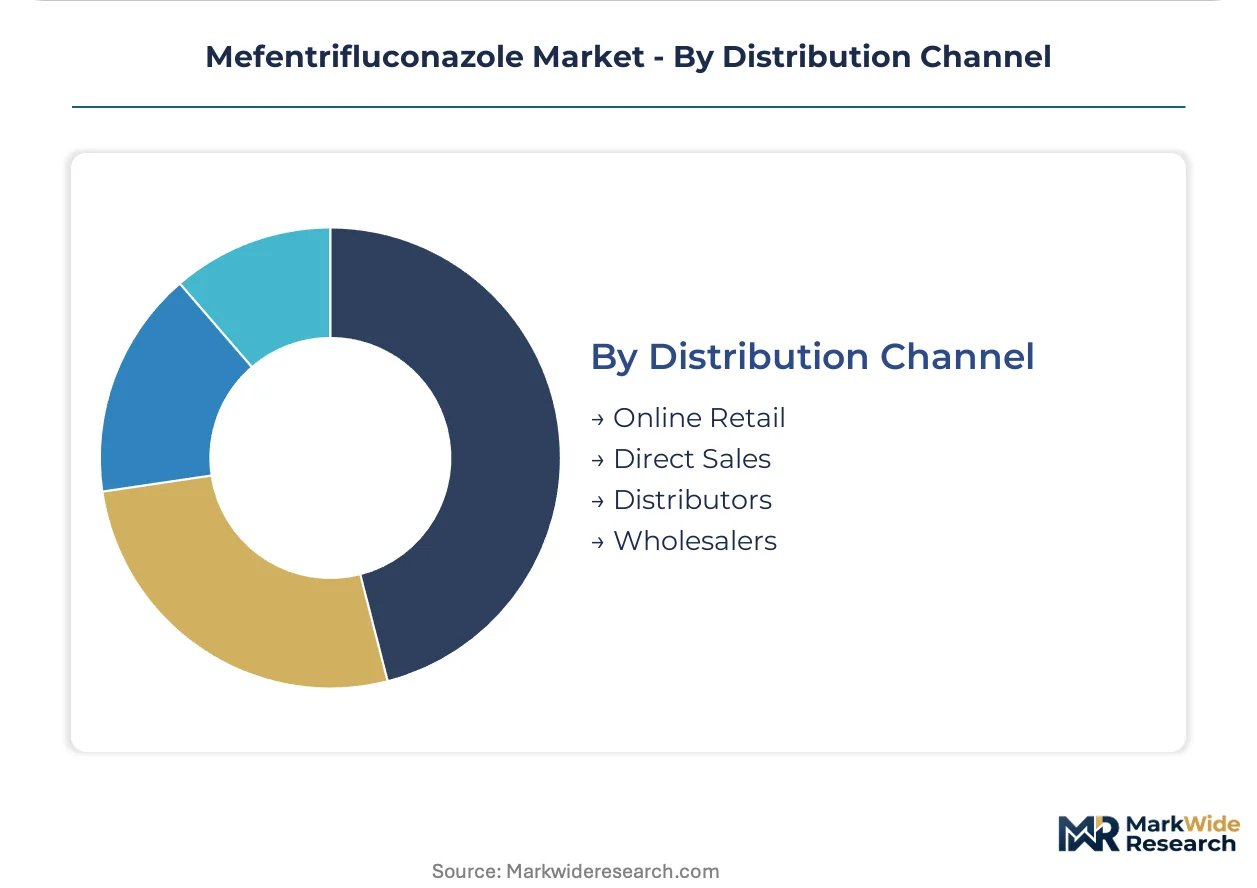
Distribution Channel:
Traditional cooperative relationships fragment as digital procurement platforms penetrate younger operator segments.
- Distributors:Regional agrochemical specialists maintain technical advisory relationships across France's Nouvelle-Aquitaine and Occitanie growing regions. These intermediaries bundle fungicide purchases with agronomic consulting services.
- Direct Sales:Major formulation manufacturers cultivate direct relationships with large-scale farming enterprises and cooperative buying groups exceeding threshold volume commitments.
- Online Retail:Agronomic decision-support apps and subscription-based crop protection programs gain traction among farm operators under 40. The Netherlands exhibits the most advanced platform penetration.
- Wholesalers:Volume aggregators serve smaller blenders and regional retail networks with limited technical service capabilities.
Incumbent dominance: Distributors. Disruption vector: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Triazole fungicide development traces its commercial roots to European cereal protection programs during the 1970s, with subsequent formulation advances scaling through German and Swiss agrochemical research clusters before Mediterranean specialty crop adoption accelerated regional diversification.
Germany
Brandenburg and Saxony-Anhalt grain cooperatives drive cereal protection demand amid post-merger restructuring of eastern German farming enterprises. REACH authorization sunset clause reviews impose expanded ecotoxicology dossier requirements on existing mefentrifluconazole registrations. BASF SE maintains captive formulation operations in Ludwigshafen, supplying proprietary adjuvant systems to large-scale arable operations.
France
Champagne grape growers and Nouvelle-Aquitaine cereal cooperatives anchor procurement volumes for high-value crop protection. ANSM residue monitoring protocols enforce strict maximum residue limits for export-oriented production. Younger farm operators in Occitanie increasingly source fungicides through agronomic decision-support apps rather than traditional cooperative channels.
Spain
Valencia and Murcia citrus export operations generate concentrated demand for phytosanitary-compliant formulations targeting Asian market access. EFSA harmonized residue thresholds shape maximum application rates across protected cultivation in Almería's greenhouse belt. Drone-based aerial application services penetrate steep terrain in Andalusian olive groves.
Italy
Emilia-Romagna stone fruit operators and Veneto specialty grape growers adopt microencapsulated formulations for rainfastness-critical applications. National sustainable use directives under EU Farm to Fork implementation tighten allowable chemical inputs in northern Italian horticulture zones. Integrated pest management protocols in Lombardy incorporate mefentrifluconazole within resistance-management rotation strategies.
Poland
Pomorskie and Mazowieckie apple orchard modernization drives fungicide upgrade cycles following Common Agricultural Policy restructuring. National plant protection office registration procedures align with EMA streamlined assessment pathways for novel formulation submissions. Large-scale cooperatives negotiate direct procurement contracts bypassing traditional distributor intermediaries.
Mefentrifluconazole Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation technology tiers, with proprietary adjuvant systems and patent-protected delivery mechanisms commanding superior pricing power. The vendor base concentrates around integrated agrochemical conglomerates with captive R&D pipelines, while mid-tier blenders face compression from REACH compliance cost burdens. Three archetypes dominate: integrated research-to-retail conglomerates, regional formulation specialists, and generic active ingredient distributors. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing backward integration into technical-grade supply and forward integration into direct-grower digital platforms.
Within the integrated conglomerate tier, BASF SE and Syngenta AG exemplify archetypes built on proprietary formulation advantages and deep distributor relationships respectively. Bayer Aktiengesellschaft occupies a position spanning pharmaceutical and agrochemical research capabilities. These entities represent the premium-capture end of the market structure, sitting above commodity-blend competitors through differentiated delivery technology and regulatory dossier expertise accumulated across multiple active ingredient portfolios.
| Leading Market Players |
|---|
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| Nufarm Limited |
| ADAMA Agricultural Solutions Ltd. |
| Bayer Aktiengesellschaft |
| Corteva Agriscience |
| UPL Limited |
| Syngenta AG |
| Others |
Value Network & Pricing Analysis
Technical-grade triazole feedstock indices cascade through European formulation operations into three distinct procurement tiers serving German cereal cooperatives, French vineyard estates, and Spanish citrus exporters. REACH authorization dossier costs compress margins at the commodity blender level while proprietary adjuvant systems sustain premium capture for integrated manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by formulation complexity and regulatory compliance depth. Premium tiers command superior positioning through EFSA residue-compliant microencapsulation and rainfastness guarantees for Italian stone fruit operators. Cost compression in the economy tier intensifies as generic blenders absorb REACH ecotoxicology endpoint expansion without passing through full cost recovery. Large-scale Polish apple cooperatives exhibit the sharpest price sensitivity, while Dutch glasshouse vegetable producers prioritize residue compliance over unit cost.
Supply Chain Analysis
Freight cost volatility from Ludwigshafen formulation hubs to Mediterranean horticulture markets exerts margin pressure on regional distributors serving fragmented French and Italian grower bases. Active ingredient supply concentrates in German and Swiss research clusters, with technical-grade streams drawing from captive production at BASF Ludwigshafen and Syngenta Basel operations. Single-source vulnerability sits with specialized C14-demethylase inhibitor synthesis capacity. Distribution runs through cooperative buying groups in France's Occitanie and direct-to-grower digital platforms in the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
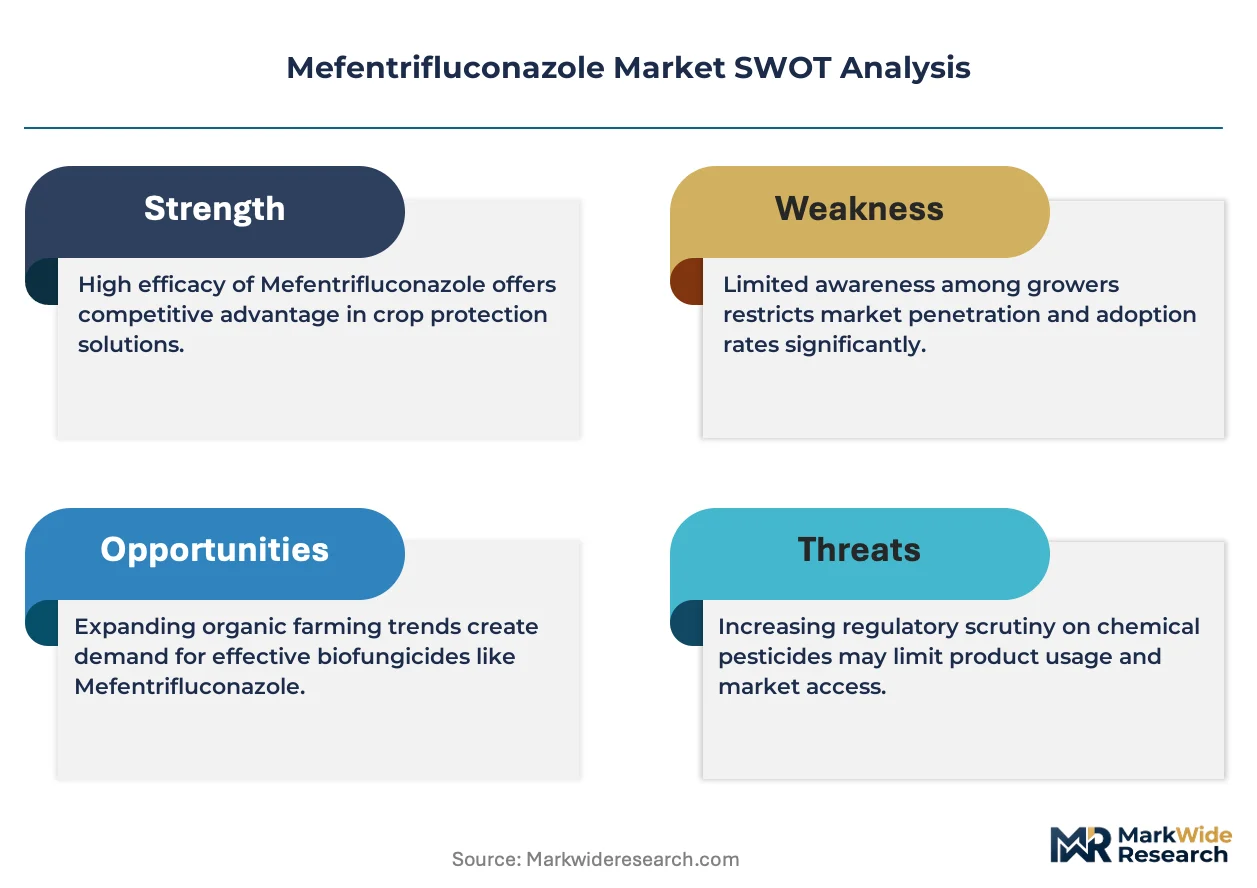
Margin expansion potential concentrates in reduced-rate formulation development and biological combination products as EU Green Deal compliance costs reshape competitive economics.
For Market Incumbents: To counter biological fungicide substitution in French organic-certified appellations, deepen captive R&D pipelines for microencapsulated delivery systems and secure backward integration into technical-grade triazole supply. Channel control through direct-grower digital platforms in the Netherlands and Poland insulates against distributor margin compression. For New Entrants and Emerging Players: Begin with drone-based aerial application services in Portuguese and Greek mountainous terrain where labor cost reduction commands immediate grower attention. Poland's post-CAP apple orchard modernization presents the most penetrable geography for novel formulation submissions through EMA streamlined assessment pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier blenders possessing REACH dossier expertise and regional registration relationships in Mediterranean specialty crop markets. Long-term viability hinges on biological combination product pipelines aligned with Farm to Fork chemical input reduction targets. Watch EFSA residue tolerance threshold tightening as the signal for accelerated consolidation among generic blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Supply | Captive triazole production at Ludwigshafen and Basel insulates margin from feedstock volatility. |
| Microencapsulation Technology Licensing | Controlled-release patents command premium positioning in Italian Veneto grape protection programs. |
| Direct-to-Grower Digital Platform Launch | Subscription crop protection programs displace cooperative buying groups in Dutch Westland glasshouses. |
| Biological Combination Product Development | Farm to Fork compliance redirects R&D investment toward reduced-rate fungicide formulations. |
| EMA Streamlined Assessment Pathway Utilization | Parallel national evaluation accelerates authorization timelines for Polish and Spanish submissions. |
Research Methodology
Bottom-up crop protection modeling reconciled against top-down formulation manufacturing tracking forms the analytical core of this study. Primary interviews with plant protection product managers, regulatory affairs specialists at EMA and national plant protection offices, cooperative procurement directors, and precision agriculture technology vendors combined with secondary validation from EFSA residue monitoring databases, REACH authorization dossier filings, EU customs trade statistics, and agrochemical sector SEC disclosures. Triangulation across these sources ensures segment-level volume and value estimates reflect actual procurement patterns rather than extrapolated assumptions.
Historical trendline analysis of fungicide active ingredient pricing and formulation technology adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, application method, end-use intensity, and regional regulatory cluster. CAGRs derive from curve-fitting observed technology penetration patterns in precision agriculture and biological combination product development. Industry-specific forecast inputs incorporate EMA assessment pathway timelines and EU Green Deal implementation phase impacts on allowable chemical inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory derogations, extreme climate events affecting fungal pressure severity, and breakthrough biological fungicide efficacy improvements. Forecasts reflect documented assumptions about REACH authorization sunset clause progression and EFSA residue threshold stability. Stakeholders should weight assumptions against their own operating context and regional regulatory engagement depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market