
 Insulin Biosimilars Market | 2026-2036
Insulin Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Biosimilars Market Analysis
Recombinant human insulin is rebalancing cost structures as biosimilar manufacturers substitute originator biologics with high-yield microbial expression systems. Eli Lilly and Company leverages its historical insulin manufacturing infrastructure to sustain volume leadership in rapid-acting formulations. Biocon Biologics Ltd. anchors its competitive position through backward integration into active pharmaceutical ingredient production in India. Sandoz Group AG differentiates through broad geographic licensing agreements that control distribution across European and emerging markets.
Insulin biosimilars are recombinant protein therapeutics with amino acid sequences identical or highly similar to reference insulin products, produced via microbial or mammalian cell culture fermentation with purity thresholds typically exceeding 95 percent. Their primary commercial purpose is to deliver equivalent glycemic control at reduced cost for diabetes management. Long-acting insulin biosimilars command the largest revenue pool due to chronic daily dosing requirements and patent expirations on glargine formulations. Pen devices represent the fastest-growing delivery mode segment as homecare settings displace hospital-administered injections. Type 2 diabetes applications generate the deepest volume concentration among therapy areas given the disease's prevalence trajectory.
The FDA's interchangeable biosimilar pathway and EMA's scientific advice procedures create divergent but converging standards for analytical similarity and immunogenicity testing. India's CDSCO aligns with WHO prequalification benchmarks to accelerate domestic approvals while enabling export eligibility. The EU F-Gas Regulation indirectly shapes manufacturing investment by restricting hydrofluorocarbon use in cold-chain infrastructure. Stakeholders must monitor evolving interchangeability substitution laws at the state level in the United States and emerging pharmacovigilance requirements for post-marketing immunogenicity surveillance.
Market Dynamics
Hospital procurement consolidation is compressing margins for insulin biosimilar manufacturers as group purchasing organizations leverage volume concentration to extract price concessions across long-acting formulations.
Growth Catalysts
- FDA Interchangeable Designation:The streamlined approval pathway reduces clinical trial requirements for biosimilar developers seeking automatic substitution rights at US pharmacies, accelerating patient access.
- Reimbursement Expansion:Germany's G-BA and India's NHA are widening coverage for follow-on biologics in public health schemes, shifting prescribing patterns toward cost-equivalent alternatives.
- Microbial Expression Systems:High-yield E. coli and Pichia pastoris platforms are slashing production costs versus mammalian cell culture, enabling price competition with originator insulins.
Market Restraints
- Cold-Chain Infrastructure Costs:The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants, forcing manufacturers to retrofit temperature-controlled logistics networks across European distribution.
- Immunogenicity Surveillance Burden:Post-marketing pharmacovigilance requirements from EMA and FDA demand extended patient monitoring, elevating compliance expenditures for biosimilar sponsors.
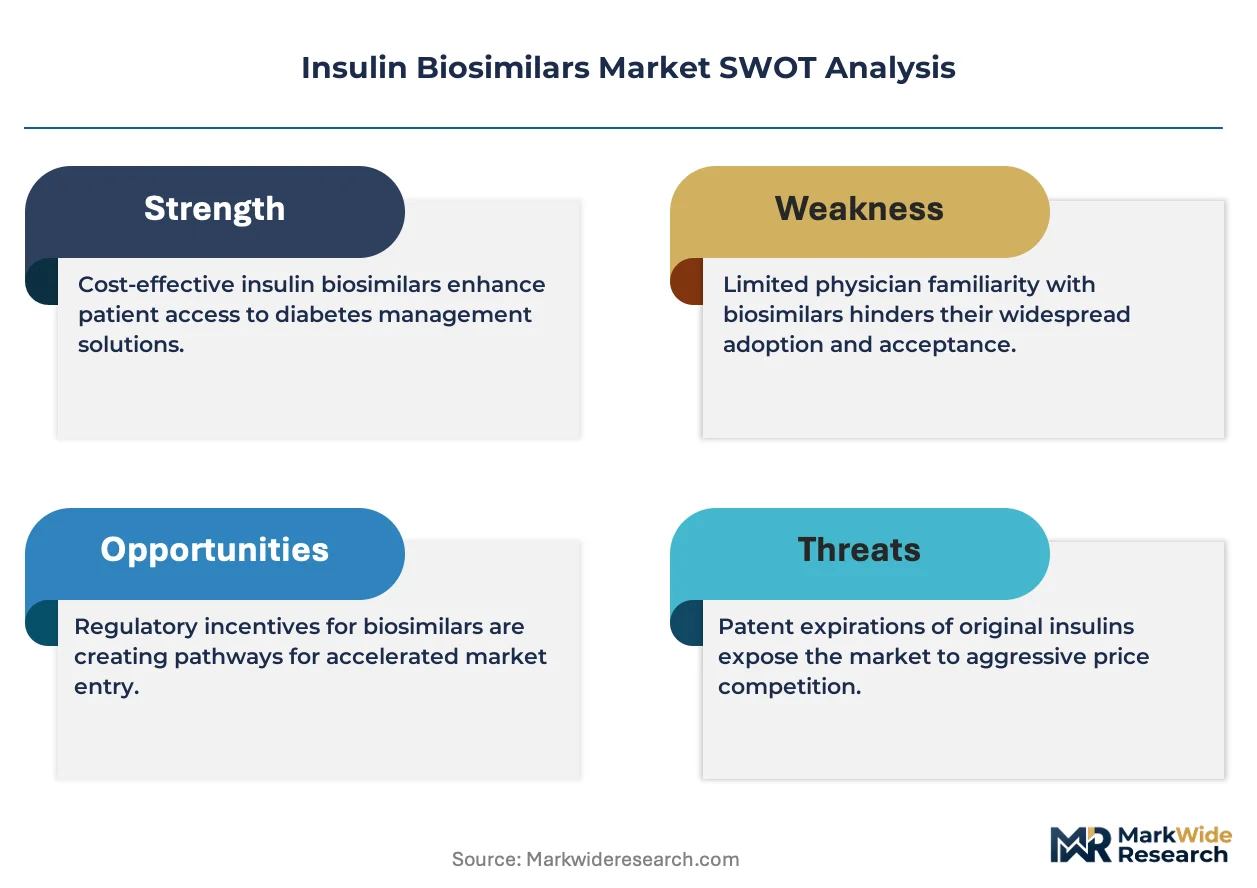
- Reference Product Loyalty:Endocrinologist prescribing inertia and patient brand attachment sustain originator insulin volumes despite equivalent efficacy profiles.
Strategic Opportunities
- Pen Device Formats:Homecare administration systems are capturing share from vial-and-syringe formats as diabetes management shifts from clinical to residential settings.
- Type 2 Diabetes Prevalence:India's expanding diabetic population creates volume concentration in basal insulin demand where biosimilars compete on out-of-pocket affordability.
- CDSCO-WHO Alignment:India's streamlined approval benchmarks enable simultaneous domestic market entry and prequalification for export to African and Southeast Asian procurement pools.
Industry Challenges
- Analytical Similarity Testing:Demonstrating physicochemical equivalence to reference products requires sophisticated mass spectrometry and bioassay capabilities that strain mid-tier development budgets.
- Patent Thicket Navigation:Complex intellectual property layering around insulin formulations and delivery devices extends litigation timelines and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Biosimilars Market |
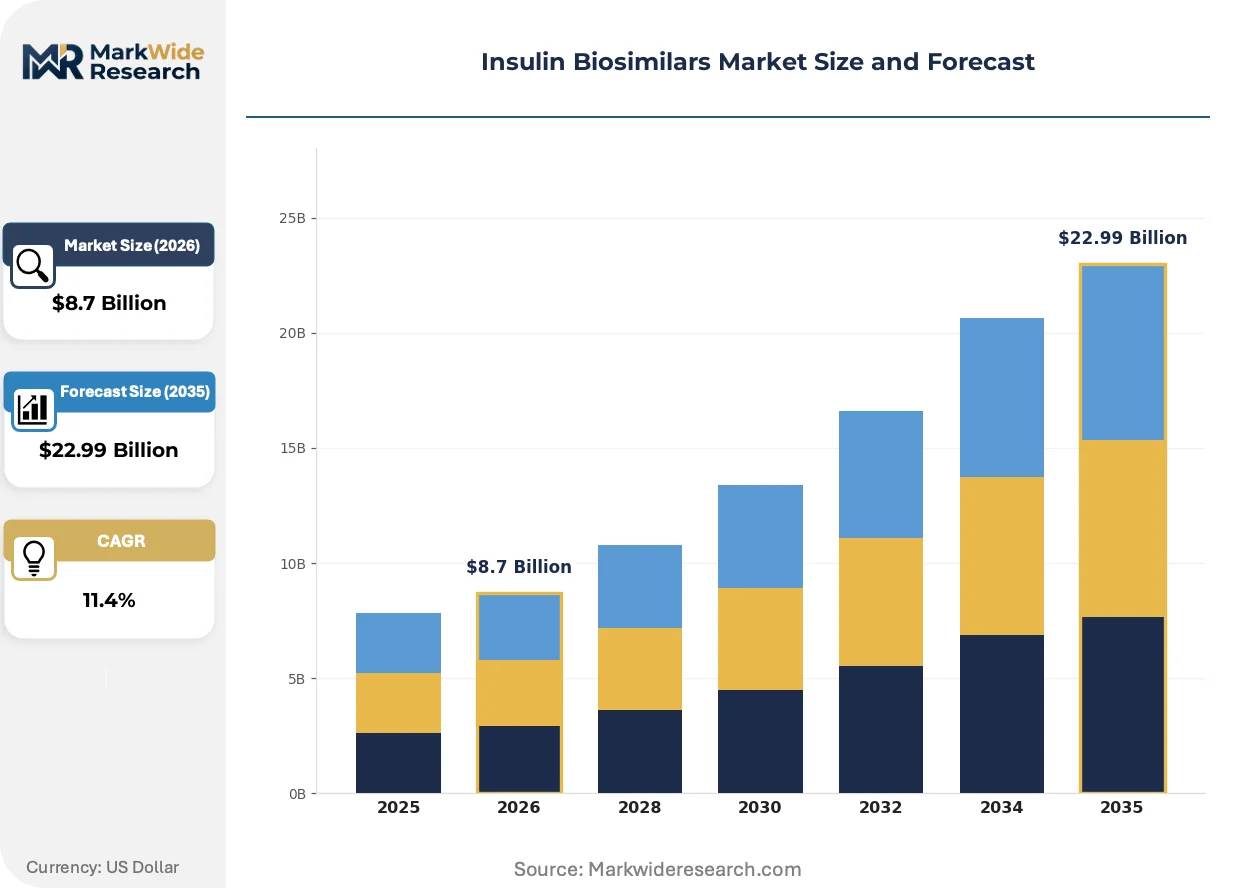
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long-Acting Insulin, Rapid-Acting Insulin, Premixed Insulin, Short-Acting Insulin End User: Hospitals, Clinics, Homecare Settings, Pharmacies Delivery Mode: Pen Devices, Vial and Syringe, Continuous Infusion, Jet Injectors Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Eli Lilly and Company, Viatris Inc., Biocon Biologics Ltd., Celltrion Healthcare Co., Ltd., Samsung Bioepis, Sandoz Group AG, Sanofi, Tonghua Dongbao Pharmaceutical Co., Ltd., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Biosimilars Market Emerging Trajectories
Manufacturing technology substitution and regulatory pathway refinement are compressing development timelines while delivery format preferences reshape competitive differentiation in diabetes therapeutics.
Continuous manufacturing platforms are overtaking batch fermentation as the dominant production architecture for recombinant insulin. Biosimilar developers in India and Germany are retrofitting facilities with integrated bioreactor and downstream processing systems that reduce cycle times and contamination risk. This technology shift is overtaking traditional stainless-steel batch operations by enabling real-time quality monitoring and smaller footprint facilities.
The FDA's interchangeable biosimilar pathway and EMA's scientific advice procedures are converging on standardized immunogenicity assessment frameworks. These regulatory instruments reduce uncertainty for sponsors navigating pre-approval requirements but impose stringent analytical similarity thresholds. Long-acting insulin formulations face the most intensive scrutiny given their chronic dosing profiles and immunogenicity surveillance obligations.
Group purchasing organizations are consolidating hospital procurement decisions across integrated delivery networks in the United States. This buyer concentration displaces individual hospital formulary autonomy with centralized contracting that prioritizes cost-per-dose metrics over brand preference. The shift is most visible in Medicare Advantage plans where capitated reimbursement creates direct financial incentive for biosimilar substitution.
Insulin Biosimilars Market Segmentation
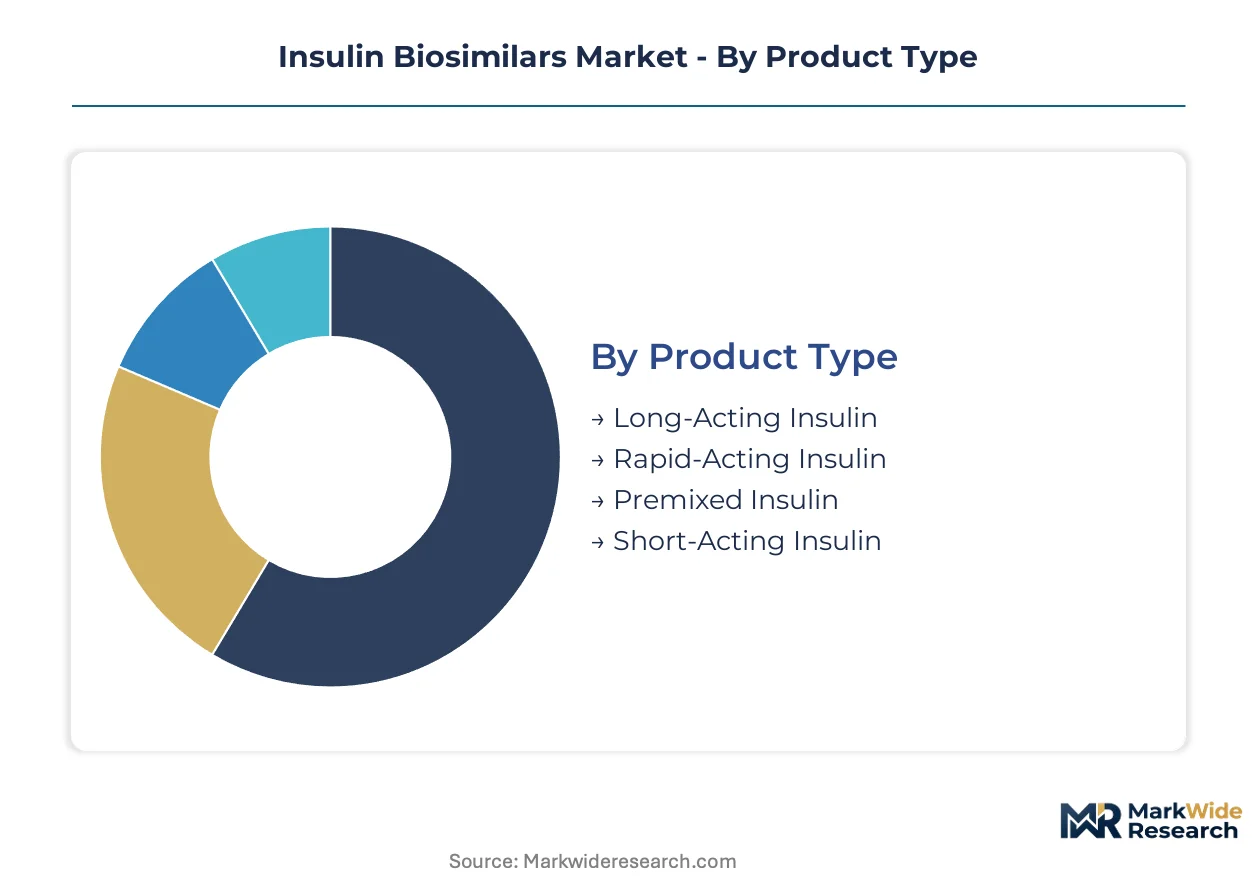
Insulin biosimilar manufacturers compete across distinct therapeutic profiles and administration contexts. Segmentation reveals where formulation chemistry, delivery technology, and care setting intersect to determine commercial viability and pricing power.
Product Type:
Long-acting formulations operate as standalone chronic therapies, while rapid-acting variants embed into multi-dose regimens requiring precise timing coordination.
- Long-Acting Insulin:Basal analogs with extended glucose-lowering profiles support once-daily dosing for Type 2 diabetes maintenance. Demand clusters in Medicare Advantage plans and German statutory health insurance where capitated reimbursement rewards cost-per-dose efficiency. Patent expirations on glargine and detemir formulations have opened concentrated substitution opportunities.
- Rapid-Acting Insulin:Prandial formulations require meal-time coordination with carbohydrate intake, demanding higher patient education investment. Volume concentrates in pediatric Type 1 diabetes and insulin pump integration where pharmacokinetic precision justifies premium positioning against human regular insulin.
- Premixed Insulin:Fixed-ratio basal-bolus combinations simplify dosing for resource-constrained settings with limited endocrinology access.
- Short-Acting Insulin:Human regular insulin serves cost-sensitive markets and inpatient glycemic control where analog precision offers marginal clinical benefit.
Volume placements concentrate in Long-Acting Insulin; the faster expansion belongs to Rapid-Acting Insulin.
End User:
Procurement authority and reimbursement mechanics diverge sharply between institutional buyers and dispersed retail channels.
- Hospitals:Integrated delivery networks and group purchasing organizations centralize formulary decisions, extracting price concessions through volume commitments. EMA pharmacovigilance requirements and FDA interchangeable designation status drive contracting criteria.
- Homecare Settings:Self-administration shifts cost burden to patients and payers through durable medical equipment reimbursement. India's National Health Authority and US Medicare Part B expansion are widening coverage for home delivery systems.
- Clinics:Endocrinology practices balance originator loyalty against payer substitution mandates in managed care environments.
- Pharmacies:Automatic substitution laws at US state level and German pharmacy-level tendering create dispensing-level competition.
Contracting power pools in Hospitals; the steepest patient volume trajectory runs through Homecare Settings.
Delivery Mode:
Device technology determines patient adherence economics and manufacturing complexity for biosimilar sponsors.
- Pen Devices:Disposable and reusable injection systems integrate dose dialing with needle concealment, reducing administration error in elderly populations. Germany's G-BA and US commercial payers increasingly mandate pen coverage over vial-syringe to reduce hypoglycemia-related hospitalization costs.
- Vial and Syringe:Lowest per-dose cost format sustains volume in Medicaid programs and emerging markets where out-of-pocket burden dominates access decisions.
- Continuous Infusion:Pump-compatible formulations require specific excipient compatibility and stability profiles, limiting biosimilar interchangeability.
- Jet Injectors:Needle-free systems address phobia and lipohypertrophy concerns in niche pediatric and needle-averse adult segments.
Cost-sensitive procurement favors Vial and Syringe; Pen Devices are climbing the fastest on patient preference and payer prevention economics.
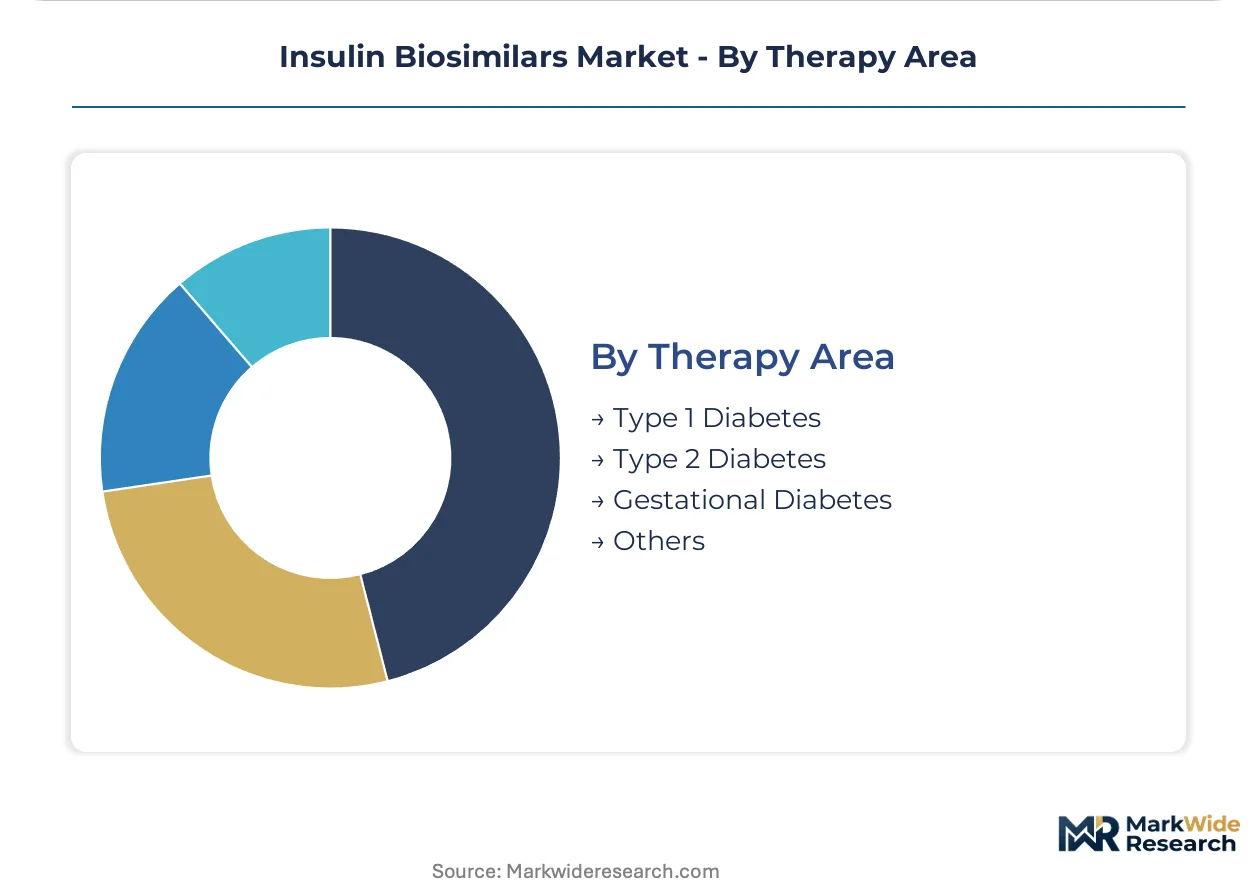
Therapy Area:
Disease pathophysiology dictates insulin dependency patterns and thus biosimilar substitution readiness.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates expanding basal insulin demand as oral agent failure accumulates. India's diabetic population concentration and US Medicare age demographics drive volume geography.
- Type 1 Diabetes:Absolute insulin deficiency requires intensive basal-bolus or pump therapy, generating highest per-patient consumption intensity. Pediatric onset creates decades of treatment duration for lifetime value calculation.
- Gestational Diabetes:Temporary insulin requirements during pregnancy prioritize human insulin safety data over analog biosimilars in many national guidelines.
- Others:Steroid-induced hyperglycemia and cystic fibrosis-related diabetes represent limited off-label utilization.
Absolute patient numbers concentrate in Type 2 Diabetes; Type 1 Diabetes generates the deepest per-capita consumption intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and pharmaceutical clusters in Germany concentrate insulin biosimilar manufacturing investment through tax incentives and streamlined regulatory pathways. These designated zones attract contract manufacturing organizations and originator spin-offs seeking cost-efficient, high-yield production capacity. The geographic distribution reflects deliberate policy engineering rather than organic market evolution.
United States
Medicare Advantage capitation and integrated delivery network consolidation drive hospital procurement of long-acting insulin biosimilars. The FDA's interchangeable designation pathway accelerates pharmacy-level substitution in states with automatic substitution laws. Indianapolis and the Research Triangle Park host manufacturing and regulatory science infrastructure supporting domestic production.
Germany
The G-BA widens reimbursement coverage for follow-on biologics within statutory health insurance, shifting prescribing toward cost-equivalent alternatives. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in cold-chain logistics, forcing distribution network retrofits. The Rhine-Main pharmaceutical corridor concentrates formulation and packaging operations for European supply.
India
The National Health Authority expands reimbursement for biosimilar insulins in public health schemes, targeting out-of-pocket affordability for Type 2 diabetes patients. CDSCO alignment with WHO prequalification benchmarks enables simultaneous domestic approval and export eligibility. Bengaluru and Hyderabad anchor active pharmaceutical ingredient production through backward-integrated biologics facilities.
China
NMPA biosimilar guidelines and volume-based procurement compress prices while expanding access to insulin analogs. Provincial centralized procurement platforms consolidate hospital purchasing decisions across tier-one cities. The Yangtze River Delta biopharma cluster hosts fermentation capacity serving domestic and Southeast Asian markets.
South Korea
MFDS accelerated approval pathways and government R&D funding support biosimilar development for global export. The national health insurance service expands coverage for follow-on biologics in diabetes management. Songdo Bio Cluster houses contract development and manufacturing organizations serving international sponsors.
Insulin Biosimilars Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator-affiliated entities dominating rapid-acting formulations and independent biosimilar developers capturing long-acting volume. Market structure tilts toward consolidation among firms with captive microbial expression capacity and established regulatory filing capabilities. Three archetypes define competitive positioning: vertically integrated originator spin-offs, API-backward-integrated emerging market specialists, and contract manufacturing organizations with platform licensing expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as firms seek to secure fermentation throughput and distribution access across multiple geographies.
Among originator-affiliated entities, Eli Lilly and Company and Sanofi occupy positions reflecting historical insulin manufacturing infrastructure and brand equity in rapid-acting segments. Biocon Biologics Ltd. exemplifies the emerging market specialist archetype through its backward-integrated API production in India. Sandoz Group AG sits within the platform licensing tier, leveraging broad geographic distribution agreements across European and emerging markets.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Viatris Inc. |
| Biocon Biologics Ltd. |
| Celltrion Healthcare Co., Ltd. |
| Samsung Bioepis |
| Sandoz Group AG |
| Sanofi |
| Tonghua Dongbao Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Fermentation media cost indices, particularly yeast extract and soy peptone benchmarks, cascade through insulin biosimilar manufacturing into three distinct pricing tiers that separate originator-affiliated products from emerging market entrants and contract-manufactured alternatives.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with refrigerated inventory positioned near hospital procurement hubs, while spot-market vial purchases trade at discounts reflecting cold-chain risk transfer. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA interchangeable designation status, WHO prequalification tier, and volume commitment scale. Cost compression in the economy tier is intensifying because India's CDSCO-aligned producers are expanding microbial expression capacity. Medicaid programs and cash-pay patients in emerging markets exhibit highest price sensitivity; Medicare Advantage plans with capitated reimbursement show lowest sensitivity due to prevention-economics framing.
Supply Chain Analysis
Warehouse-distribution layers in insulin biosimilars operate through regional distribution centers in Frankfurt, Indianapolis, and Hyderabad that feed hub-and-spoke cold-chain networks compliant with EU F-Gas refrigeration restrictions. Manufacturing concentration rests on India, Germany, and the United States, where microbial fermentation capacity and formulation infrastructure cluster. Active pharmaceutical ingredient production draws from recombinant E. coli and Pichia pastoris cell banks, glass cartridge supply, and needle-safety device components. Single-source vulnerability in lyophilization equipment creates bottleneck exposure. Distribution runs through group purchasing organization contracts for hospital systems and pharmacy benefit manager channels for retail dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insulin biosimilar manufacturing economics favor consolidation as hospital procurement centralization and interchangeable designation requirements force sub-scale developers toward exit or acquisition.
For Market Incumbents: Lock in microbial expression capacity through captive fermentation facilities or exclusive tolling agreements in India and Germany to defend against emerging market API producers. Secure FDA interchangeable designation for long-acting formulations before state-level automatic substitution laws mature, as this certification becomes the priority lever for Medicare Advantage contracting. Reinforce cold-chain partnerships with third-party logistics providers holding EU F-Gas-compliant refrigeration infrastructure. For New Entrants and Emerging Players: The mid-tier price-point gap between premium interchangeable biosimilars and economy vial-syringe products creates white-space opportunity for pen-device formats with abbreviated immunogenicity data packages. Target India's National Health Authority reimbursement expansion for basal insulin demand where out-of-pocket affordability drives prescribing. Enter through CDSCO-WHO alignment pathway enabling simultaneous domestic approval and African export prequalification. For Investors and Strategic Acquirers: The window for entry favors emerging market specialists with backward-integrated API production and established regulatory filing capabilities across FDA, EMA, and WHO frameworks. Five-to-ten-year viability hinges on manufacturing scale rather than brand equity in this substitutable therapeutic category. Monitor state-level interchangeability substitution law adoption rates as the inflection indicator for pharmacy-level volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO-WHO Alignment Pathway | Enables simultaneous Indian domestic approval and export prequalification for African procurement pools. |
| FDA Interchangeable Designation | Unlocks automatic pharmacy substitution in Medicare Advantage and commercial payer contracts. |
| Microbial Expression Scale-Up | Reduces cost per gram through high-yield E. coli and Pichia pastoris platform optimization. |
| Pen Device Manufacturing Partnership | Captures homecare preference shift away from vial-syringe administration in elderly populations. |
| Cold-Chain Infrastructure Retrofit | Ensures EU F-Gas Regulation compliance for hydrofluorocarbon-free temperature-controlled distribution. |
Methodological Framework
Independent corroboration across biosimilar development executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and group purchasing organization contract managers underwrites the qualitative findings. Secondary validation draws from FDA biosimilar approval databases, EMA scientific advice procedural records, ClinicalTrials.gov immunogenicity study registrations, and CMS Medicare Part B reimbursement data. Bottom-up patient volume modeling and top-down pharmaceutical market sizing triangulate demand estimates.
Rate-of-change decomposition separates volume growth from price erosion effects across the projection horizon. Segmentation dimensions include product type (long-acting, rapid-acting, premixed, short-acting), delivery mode (pen device, vial-syringe, pump-compatible), end user (hospital, homecare, clinic, pharmacy), and therapy area (Type 1, Type 2, gestational diabetes). CAGRs derive from patient population epidemiology, patent expiration timelines, and reimbursement expansion trajectories. Forecast inputs incorporate microbial expression yield improvements and cold-chain logistics cost curves.
Inputs from regulatory filing databases and hospital procurement contract repositories were available through the study window; gaps in real-time pharmacy dispensing data introduce uncertainty bands around substitution rate assumptions. Forecasts reflect documented base-case assumptions regarding FDA interchangeable designation adoption and EMA pharmacovigilance requirement stability. Patent litigation outcomes and originator loyalty persistence represent specific revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Imatinib Drug Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Global Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
US Biosimilars Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Herceptin Biosimilar Market