
 Thailand Insulin Drugs and Delivery Devices Market | 2026-2036
Thailand Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Insulin Drugs and Delivery Devices Market Insights
Thailand's updated National List of Essential Medicines criteria is realigning reimbursement thresholds for insulin analogs and delivery devices. Novo Nordisk leverages its integrated insulin and pen-needle portfolio to sustain dominance across Thai public hospital tenders. Eli Lilly anchors its position through biosimilar insulin production partnerships with regional manufacturers. Sanofi competes on basal insulin formulations while navigating price controls imposed by the National Health Security Office.
Insulin drugs and delivery devices comprise biologically active peptide formulations administered via precision-engineered injection systems to regulate blood glucose in diabetic patients. Recombinant human insulin and insulin analogs require cold-chain storage at two to eight degrees Celsius and are delivered through devices calibrated to deliver sub-milliliter doses with high reproducibility. Insulin pens occupy the largest volume share among product types due to patient self-administration preference and reduced needle-phobia incidence, while insulin pumps capture premium margins concentrated in Bangkok's private hospital ecosystem. Home care settings represent the fastest-growing end user channel as Thailand's Ministry of Public Health expands telemedicine-linked diabetes management to reduce tertiary care burden.
Thai FDA registration requirements and ISO 13485 quality system mandates govern device approval timelines and manufacturing audits for imported insulin delivery systems. The National Health Security Office reimbursement catalog and Ministry of Public Health procurement guidelines directly determine market access depth across Thailand's universal coverage scheme. Stakeholders must monitor biosimilar interchangeability rulings and provincial health authority budget allocations to anticipate volume shifts between public tenders and private pharmacy channels.
Market Dynamics
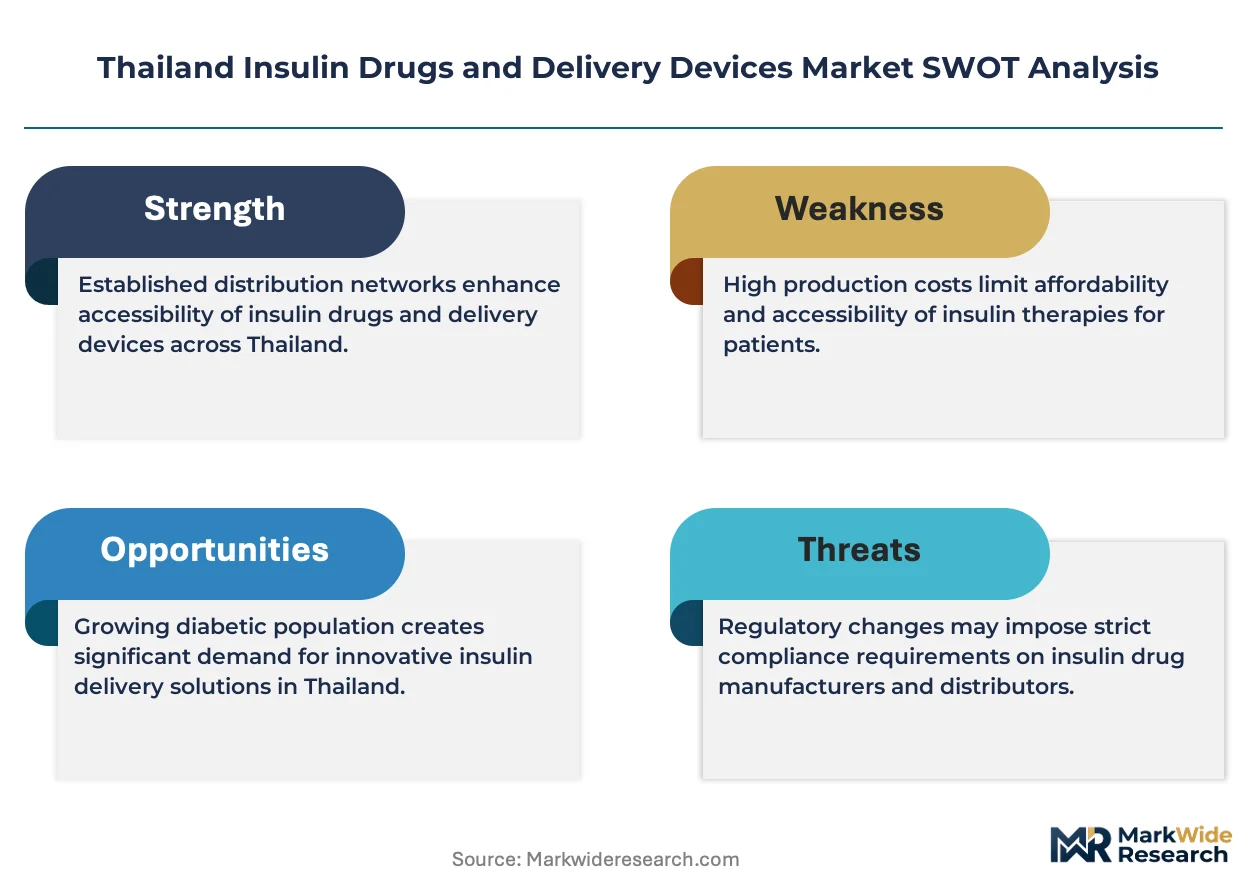
Thailand's universal health coverage expansion is consolidating insulin procurement through the National Health Security Office, compressing margins for multinational suppliers while accelerating biosimilar substitution in public hospital tenders.
Growth Catalysts
- Telemedicine-linked diabetes management:Thailand's Ministry of Public Health deploys remote glucose monitoring platforms across provincial health zones, expanding home-based insulin administration and device volumes.
- National List of Essential Medicines revision:Updated reimbursement criteria broaden insulin analog eligibility, reducing patient out-of-pocket burden and stimulating category penetration.
- Bangkok metropolitan hospital network expansion:Tertiary care cluster consolidation in the capital region concentrates high-acuity diabetes cases requiring advanced delivery systems.
Market Restraints
- Cold-chain infrastructure gaps:Two-to-eight-degree Celsius storage requirements strain provincial distribution networks, particularly in Thailand's northeastern and southern regions.
- Price control compression:National Health Security Office reimbursement ceilings limit premium insulin analog pricing power across public sector tenders.
- Import dependency for precision devices:ISO 13485-certified manufacturing concentrates among European and North Asian suppliers, exposing Thai procurement to currency and logistics volatility.
Strategic Opportunities
- Provincial health zone penetration:Underpenetrated secondary cities in Thailand's northern and northeastern regions present volume expansion potential as diabetes prevalence rises.
- Biosimilar interchangeability rulings:Anticipated Thai FDA guidance on automatic substitution would accelerate generic insulin capture of public hospital formularies.
- Insulin pump-private hospital convergence:Premium device adoption clusters in Bangkok's private hospital ecosystem, where out-of-pocket payment capacity supports margin retention.
Industry Challenges
- Thai FDA registration timeline compression:Device approval cycles for novel delivery systems extend 18-24 months, delaying market entry against evolving patient needs.
- Specialized diabetes educator workforce scarcity:Insulin pump therapy initiation requires certified training capacity that concentrates in Bangkok and major provincial centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Insulin Drugs and Delivery Devices Market |
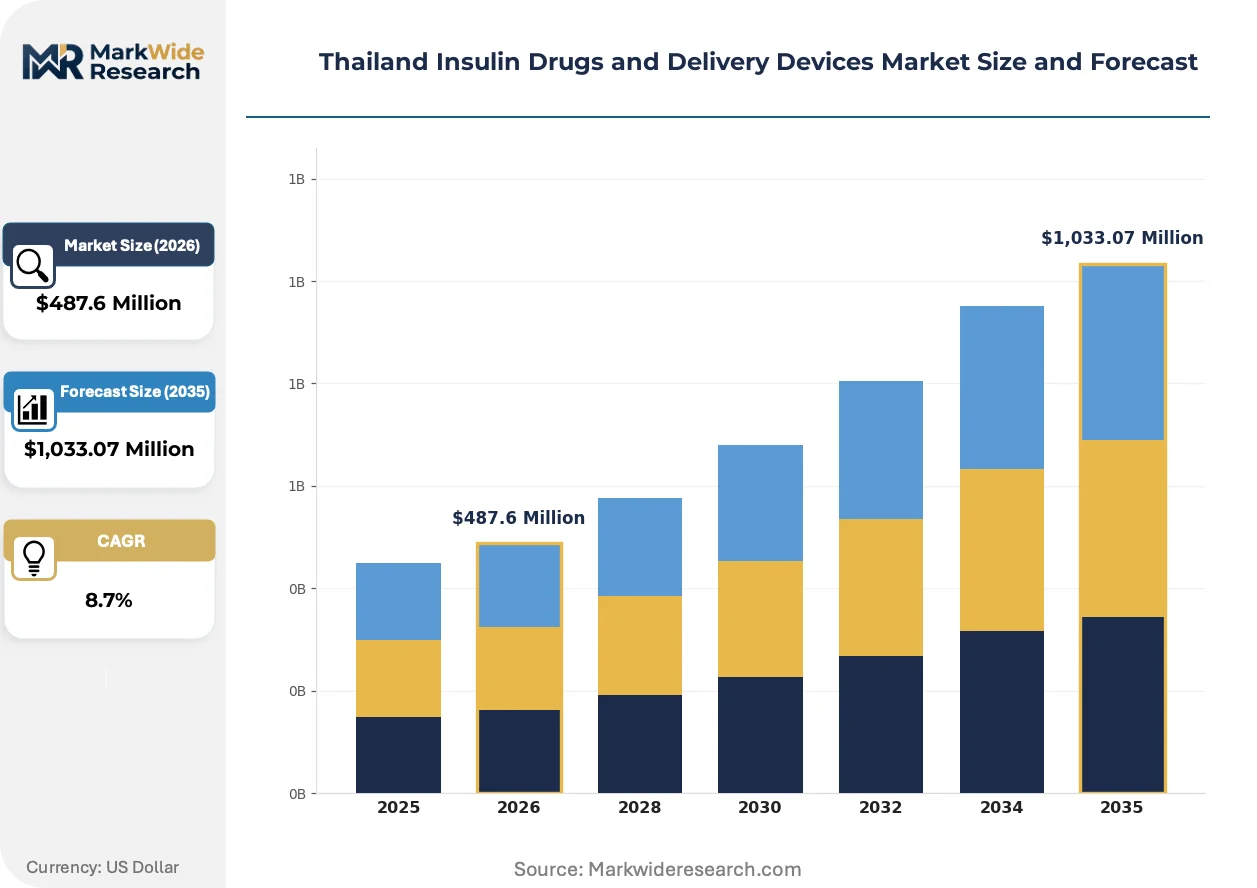
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Insulin Pens, Insulin Pumps, Prefilled Insulin Cartridges Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Inhalation, Transdermal Delivery End User: Hospitals, Clinics, Home Care Settings, Pharmacies Customer Type: Type 1 Diabetics, Type 2 Diabetics, Healthcare Professionals, Caregivers |
| Companies Covered | Novo Nordisk, Sanofi, Medtronic, Eli Lilly, Becton Dickinson, Insulet, Ypsomed, Tandem Diabetes Care, Roche, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Insulin Drugs and Delivery Devices Market Trends and Innovations
Connected delivery systems and biosimilar manufacturing localization are restructuring competitive advantage in Thailand's insulin market, with regulatory data requirements and reimbursement mechanics determining adoption velocity.
Smart insulin pens integrating dose logging and Bluetooth connectivity are unifying glucose management data streams for Thai endocrinologists and patients. Bangkok's private hospital networks pilot these devices for type 1 diabetes cohorts, compressing the gap between injection-based and pump-based therapy monitoring capabilities.
Thai FDA biosimilar interchangeability frameworks are tightening analytical and clinical equivalence standards for insulin copy products. Domestic manufacturers pursuing prequalification must demonstrate pharmacokinetic matching to originator references, accelerating quality system investments across regional production partnerships.
Patient self-administration preference is displacing hospital-based injection services in Thailand's diabetes care pathway. Community pharmacy channels in Bangkok and Chiang Mai expand pen-needle and insulin pen dispensing, unbundling device supply from clinical consultation revenue streams that historically anchored hospital pharmacy economics.
Thailand Insulin Drugs and Delivery Devices Market Segmentation
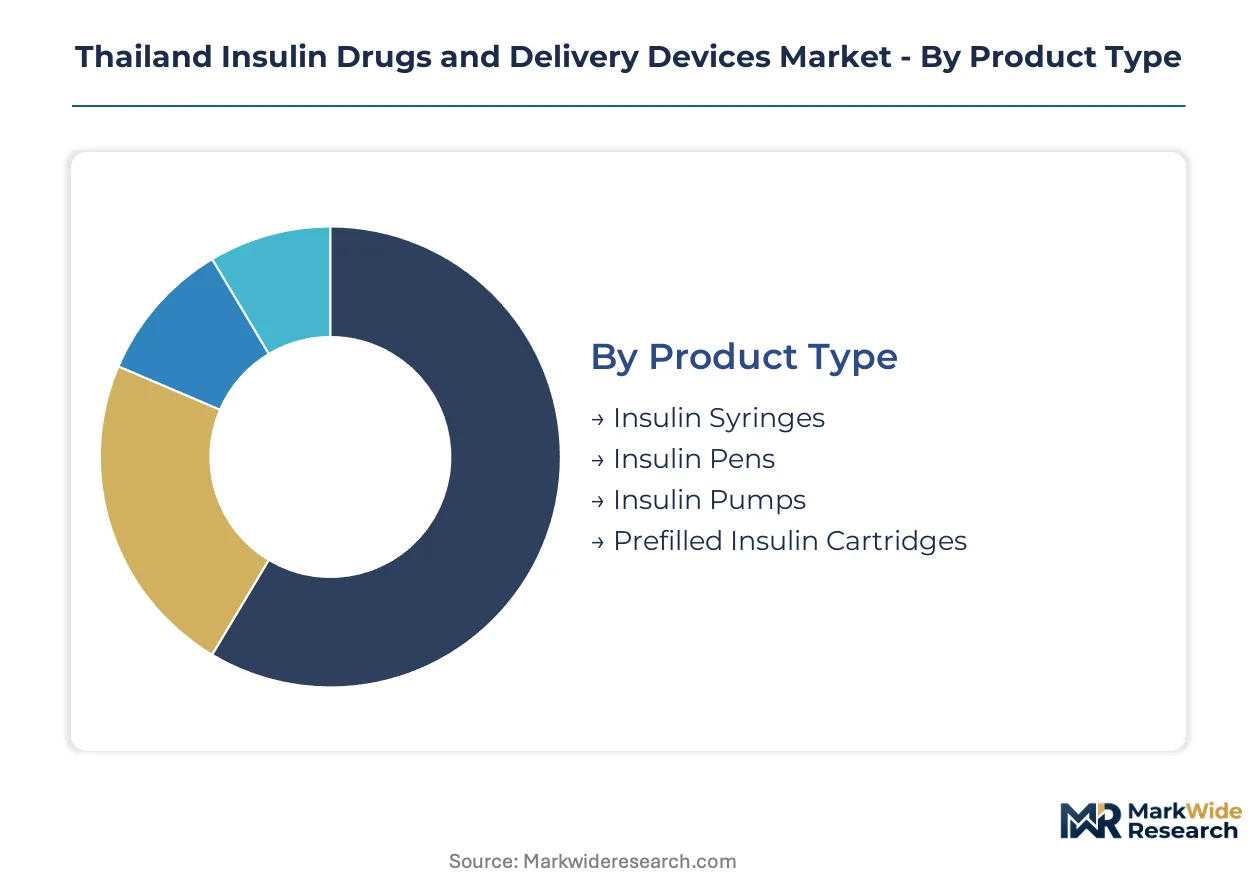
Segmentation in Thailand's insulin market reveals how reimbursement mechanics and patient self-administration preferences allocate volume across device categories. Procurement patterns diverge sharply between Bangkok's tertiary hospitals and provincial health zones, while delivery mode adoption reflects cold-chain reliability and clinical training capacity.
Product Type:
Volume concentrates in disposable injection systems, while premium margins attach to durable electronic devices requiring specialized initiation protocols.
- Insulin Pens:Reusable and disposable pen systems deliver sub-milliliter doses with dose-dial accuracy. Bangkok's metropolitan hospital networks and affiliated provincial health zones drive procurement volume as the National Health Security Office prioritizes pen-based therapy for outpatient diabetes management.
- Insulin Syringes:Conventional vial-and-syringe administration persists in cost-constrained procurement tiers. Demand clusters in Thailand's northeastern and southern regions where cold-chain infrastructure gaps complicate pen and pump inventory management.
- Insulin Pumps:Continuous subcutaneous infusion devices with programmable basal-bolus algorithms. Bangkok's private hospital ecosystem captures premium adoption where out-of-pocket payment capacity supports margin retention.
- Prefilled Insulin Cartridges:Single-use insulin reservoirs compatible with reusable pen bodies. Community pharmacy channels in Chiang Mai and provincial cities expand dispensing as patient self-administration preference strengthens.
Mature deployment sits with Insulin Syringes. Newer deployment is concentrated in Insulin Pens.
Delivery Mode:
Route selection tracks clinical acuity, reimbursement eligibility, and cold-chain reliability across Thailand's universal coverage scheme.
- Subcutaneous Injection:Abdominal, thigh, or arm tissue deposition via pen, syringe, or pump cannula. Home care settings represent the channel expanding most quickly as Thailand's Ministry of Public Health deploys telemedicine-linked glucose monitoring platforms.
- Intravenous Infusion:Hospital-controlled insulin delivery for diabetic ketoacidosis and perioperative glycemic management. Tertiary care clusters in Bangkok concentrate acute utilization requiring intensive monitoring capacity.
- Inhalation:Pulmonary insulin absorption via dry powder or aerosol devices. Thai FDA registration timelines and reimbursement exclusion limit penetration despite patient needle-avoidance preference.
- Transdermal Delivery:Microneedle array or iontophoretic systems for non-invasive insulin absorption. Development-stage positioning with no current commercial availability under Thai medical device regulations.
Established clinical practice centers on Subcutaneous Injection. Experimental uptake clusters in Inhalation.
End User:
Channel economics split between institutional procurement under price controls and retail pharmacy dispensing with higher margin retention.
- Hospitals:Tertiary and secondary care institutions managing acute complications and therapy initiation. National Health Security Office tenders compress pricing power for multinational suppliers while accelerating biosimilar substitution.
- Home Care Settings:Patient-managed insulin administration with remote clinical oversight. Telemedicine platform deployment across provincial health zones is gaining share fastest as the Ministry of Public Health reduces tertiary care burden.
- Clinics:Primary care and endocrinology specialty sites for therapy optimization. Bangkok metropolitan networks and major provincial centers concentrate certified diabetes educator capacity.
- Pharmacies:Community and hospital-based dispensaries for device and consumable resupply. Chiang Mai and secondary city networks expand pen-needle and insulin pen availability unbundled from consultation revenue.
Institutional procurement dominates Hospitals. Dispersion trends favor Home Care Settings.
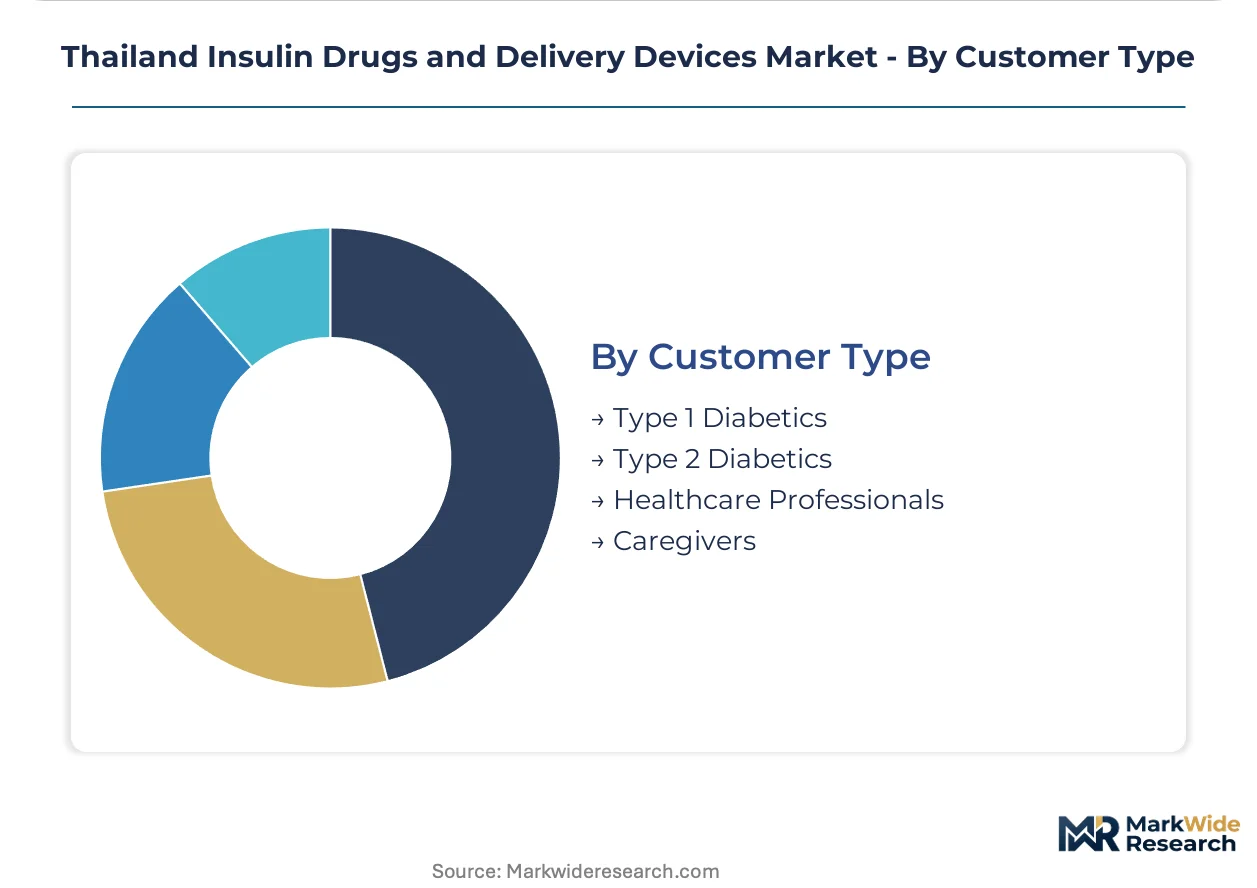
Customer Type:
Disease severity and reimbursement status determine device sophistication and payment responsibility.
- Type 1 Diabetics:Absolute insulin deficiency requiring exogenous replacement therapy. Bangkok's private hospital ecosystem and metropolitan tertiary centers concentrate pump therapy adoption requiring intensive self-management training.
- Type 2 Diabetics:Progressive insulin resistance and beta-cell dysfunction driving escalating insulin requirements. Universal coverage scheme eligibility under the National List of Essential Medicines determines analog access versus human insulin assignment.
- Healthcare Professionals:Endocrinologists, diabetologists, and certified diabetes educators prescribing and initiating therapy. Workforce scarcity concentrates in Bangkok and major provincial centers, limiting pump therapy expansion.
- Caregivers:Family members administering insulin for pediatric, geriatric, or disabled patients. Provincial health zone expansion of diabetes management protocols extends training requirements to non-clinical administrators.
Established demand flows from Type 2 Diabetics. Intensity and premium attachment concentrate with Type 1 Diabetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor's tax incentives for medical device manufacturing are consolidating insulin delivery device production near Bangkok's port infrastructure and cold-chain logistics hubs.
Bangkok Metropolitan Region
Thailand's Ministry of Public Health operates the country's densest network of tertiary diabetes centers here. National Health Security Office procurement tenders concentrate volume in this zone, compressing multinational pricing power while accelerating biosimilar insulin substitution. Rama Hospital and Siriraj Hospital anchor insulin pump therapy initiation capacity.
Northern Thailand
Chiang Mai's provincial health zone is expanding telemedicine-linked diabetes management under Ministry of Public Health directives. Cold-chain gaps between Chiang Mai and remote districts strain insulin analog distribution, preserving human insulin formulary dominance. Community pharmacy networks here are unbundling pen-needle supply from hospital consultation revenue.
Northeastern Thailand
Khon Kaen's regional hospital cluster manages the highest diabetes prevalence rates nationally. Two-to-eight-degree Celsius storage requirements expose distribution vulnerabilities across Isaan's rural road networks. Provincial health authority budget allocations here lag Bangkok's per-capita insulin analog reimbursement rates.
Southern Thailand
Songkhla's border province status creates cross-border procurement complexity with Malaysian health systems. Hat Yai Hospital concentrates the region's certified diabetes educator workforce, limiting pump therapy expansion beyond this node. Monsoon season logistics disruptions periodically interrupt insulin delivery device inventory.
Eastern Seaboard
Rayong and Chonburi provinces host Thailand's expanding medical device free trade zones. Thai FDA registration facilitation for ISO 13485-certified manufacturers accelerates device import processing through Laem Chabang port. Japanese and South Korean precision injection system suppliers cluster warehousing capacity here.
Thailand Insulin Drugs and Delivery Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Thailand's insulin market structure. The competitive terrain splits between multinational pharmaceutical-device integrators commanding public hospital tenders and regional biosimilar manufacturers penetrating provincial formularies. Three archetypes dominate: originator biologic defenders, biosimilar cost leaders, and precision device technology licensors. Strategic moves concentrate on backward integration into pen-needle manufacturing and telemedicine platform partnerships for remote patient monitoring.
Among the originator-integrated tier, Novo Nordisk and Sanofi occupy positions exemplifying portfolio breadth across insulin formulations and delivery systems. Eli Lilly anchors the biosimilar production partnership archetype through regional manufacturing alliances. These three entities collectively represent the competitive spectrum from premium analog defense to cost-optimized substitution strategies shaping National Health Security Office tender outcomes.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Medtronic |
| Eli Lilly |
| Becton Dickinson |
| Insulet |
| Ypsomed |
| Tandem Diabetes Care |
| Roche |
| Others |
Pricing and Supply Chain Analysis
Cold-chain logistics costs cascade through Thailand's insulin market from European and North Asian manufacturing origins to Bangkok's port infrastructure, compressing margins for temperature-sensitive analog formulations while preserving pricing power for originator biologics in premium private hospital channels.
Pricing Analysis
Short lead-time premiums attach to ISO 13485-certified insulin delivery devices held in Eastern Seaboard bonded warehouses, while spot inventory discounts emerge for human insulin vials approaching expiry in provincial health zone tenders. Three-tier pricing structure across premium analog, standard biosimilar, and economy human insulin levels stratifies by Thai FDA registration tier and National Health Security Office reimbursement eligibility. Pricing pressure stems from biosimilar substitution mandates in public hospital procurement, eroding originator margins. Type 2 diabetic patients under universal coverage exhibit highest price sensitivity, while Bangkok private hospital out-of-pocket payers show lowest.
Supply Chain Analysis
Freight costs for temperature-controlled insulin shipments from Denmark, France, and South Korea concentrate supply risk at Laem Chabang port's cold-storage capacity. Recombinant insulin API, precision injection molding components, and lithium-ion pump batteries draw from concentrated upstream sources. Single-source vulnerability sits with European pen-needle manufacturers lacking qualified Asian alternatives. Distribution runs through Ministry of Public Health central procurement for public hospitals, diverging to community pharmacy channels for self-administration resupply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's insulin market operates as a cost-of-compliance arena where Thai FDA biosimilar interchangeability rulings and ISO 13485 quality mandates erect regulatory moats favoring manufacturers with pre-qualified quality systems and established registration track records.
For Market Incumbents: Lock in backward integration into pen-needle manufacturing to defend margin position against Korean and Japanese precision device suppliers. Expand certified diabetes educator training capacity in Khon Kaen and Songkhla to anchor pump therapy initiation beyond Bangkok. Threat from regional biosimilar manufacturers intensifies as Thai FDA tightens analytical equivalence standards. For New Entrants and Emerging Players: Capture volume in Chiang Mai's community pharmacy channel where pen-needle dispensing unbundles from hospital consultation revenue. Target northeastern provincial health zones where cold-chain gaps preserve human insulin formulary dominance and biosimilar penetration lags Bangkok. Go-to-market angle: telemedicine platform partnerships for remote glucose monitoring integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified device manufacturers with Thai FDA registration dossiers in Rayong's Eastern Economic Corridor free trade zones. Long-term viability hinges on biosimilar interchangeability ruling timing and provincial health authority budget expansion. Signal to watch: National List of Essential Medicines revision frequency and analog eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Thai FDA Biosimilar Interchangeability Pathway | Accelerates generic insulin capture of National Health Security Office tenders once prequalified. |
| Provincial Diabetes Educator Training Expansion | Unlocks pump therapy adoption beyond Bangkok's tertiary center concentration. |
| Telemedicine Platform Integration | Links home care glucose monitoring to Ministry of Public Health remote oversight systems. |
| Eastern Seaboard Cold-Chain Warehouse Investment | Reduces lead-time premiums for European and North Asian insulin imports through Laem Chabang. |
| Community Pharmacy Channel Partnership | Unbundles pen-needle and insulin pen supply from hospital pharmacy consultation revenue. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving endocrinologists, hospital procurement managers, National Health Security Office formulary directors, Thai FDA regulatory affairs leads, and community pharmacy operators. Secondary sources included Thai FDA registration databases, Ministry of Public Health procurement bulletins, National List of Essential Medicines revision documents, and ISO 13485 certification records. Bottom-up volume estimates from device shipment data reconciled with top-down expenditure flows from universal coverage scheme reimbursement claims.
Granularity-level modeling operated at insulin formulation type, delivery device category, end-user channel, and provincial health zone dimensions across the projection horizon. CAGRs derived from trend extrapolation of National Health Security Office tender volumes, biosimilar substitution rates, and telemedicine platform deployment schedules. Forecast inputs incorporated diabetes prevalence projections from Thailand's Ministry of Public Health epidemiological surveys and cold-chain infrastructure investment pipelines from Eastern Economic Corridor development authorities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Thai FDA biosimilar interchangeability rulings, National Health Security Office reimbursement ceiling adjustments, and provincial health authority budget allocation shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
HIV Drugs Market