
 Protein Kinase B Inhibitors Market | 2026-2036
Protein Kinase B Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Kinase B Inhibitors Market Analytics
Oncology clinics are redrawing procurement priorities for Protein Kinase B inhibitors as immuno-oncology combination protocols gain protocol share. Pfizer Inc. sustains broad development pipelines across multiple AKT inhibitor candidates. Novartis AG anchors its position through deep expertise in mTOR and PI3K pathway adjacency. Bristol Myers Squibb Company specializes in combination therapy positioning with its existing checkpoint inhibitor infrastructure.
Protein Kinase B inhibitors are small-molecule or biologic agents that selectively block AKT serine/threonine kinase activity, typically functioning through ATP-competitive or allosteric binding mechanisms to interrupt PI3K/AKT/mTOR signaling cascades. Their primary purpose is to induce apoptosis in malignant cells with hyperactivated survival pathways and to restore insulin sensitivity in metabolic disorders driven by AKT dysregulation. The cancer indication segment dominates current clinical utilization, while metabolic disorders represents the fastest-expanding addressable population as non-alcoholic steatohepatitis and type 2 diabetes trials advance. Injectable delivery mode occupies the highest-value hospital channel, though oral formulations are gaining share in outpatient chronic disease management.
FDA accelerated approval and EMA conditional marketing authorization frameworks shape development economics by permitting earlier revenue recognition based on surrogate endpoints. ISO 14155 and ICH-GCP standards govern trial execution integrity across multinational investigator sites. Stakeholders must monitor how evolving FDA Project Optimus dose-optimization mandates reshape Phase II design requirements for kinase inhibitors.
Market Dynamics
FDA Project Optimus dose-optimization mandates are compressing Phase II timelines for AKT inhibitor candidates while forcing sponsors to abandon traditional maximum-tolerated-dose paradigms in favor of mechanistically guided regimen selection.
Growth Catalysts
- FDA Accelerated Approval:The pathway permits oncology sponsors to secure conditional market entry based on progression-free survival or objective response rate surrogates rather than waiting for mature overall survival data.
- Metabolic disorder pipelines:Non-alcoholic steatohepatitis and insulin resistance indications are expanding addressable populations beyond oncology into chronic disease management.
- PI3K/AKT/mTOR pathway adjacency:Cross-platform expertise from mTOR and PI3K inhibitor development is shortening learning curves for AKT-specific drug discovery.
Market Restraints
- Biomarker complexity:PTEN loss and PIK3CA mutation heterogeneity complicate patient stratification and inflate companion diagnostic development costs.
- Cardiotoxicity signals:Hyperglycemia and rash adverse events in early-phase trials trigger protocol amendments and enrollment pauses.
- ATP-binding site competition:High homology across AGC kinase family members produces off-target inhibition and narrow therapeutic indices.
Strategic Opportunities
- Japan's PMDA Sakigake designation:Priority review vouchers for first-in-class AKT inhibitors reduce time-to-market for sponsors with Japanese development presence.
- Allosteric inhibitor modalities:Non-ATP-competitive binding mechanisms circumvent resistance mutations at the active site.
- Outpatient oral formulations:Chronic metabolic indications favor take-home regimens over hospital-administered injectables.
Industry Challenges
- Pharmacodynamic assay standardization:Inconsistent pAKT readout methodologies across academic sites corrupt cross-trial comparability.
- Combination protocol complexity:Checkpoint inhibitor and chemotherapy co-administration escalates safety monitoring infrastructure requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Kinase B Inhibitors Market |
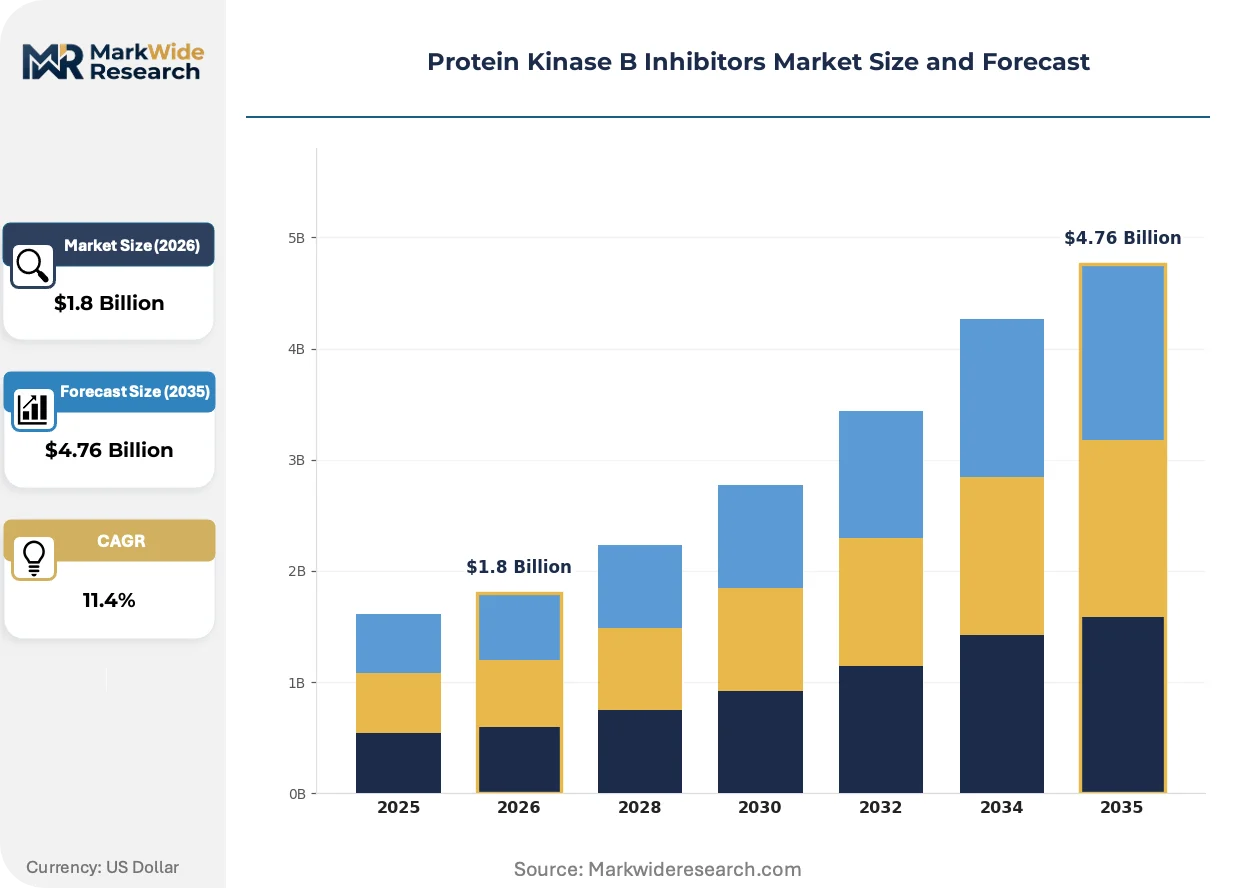
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MK-2206, GSK-690693, ARQ-092, Afuresertib Indication: Cancer, Metabolic Disorders, Inflammatory Diseases, Neurological Disorders Delivery Mode: Injectable, Oral, Infusion, Transdermal End User: Hospitals, Research Institutions, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | AstraZeneca, Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd, Bristol Myers Squibb Company, AbbVie Inc., Taiho Pharma, Johnson & Johnson, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Kinase B Inhibitors Market Evolving Landscape
AKT inhibitor development is pivoting from cytotoxic chemotherapy combinations toward precision immuno-oncology pairings, with biomarker-driven trial designs replacing histology-based enrollment.
Allosteric small-molecule inhibitors targeting the AKT pleckstrin homology domain are miniaturizing the effective dose window by achieving pathway suppression without saturating the ATP pocket. Early-phase units at academic medical centers in Boston and San Francisco are adopting these candidates for basket trials. The shift is compressing differentiation requirements for ATP-competitive programs and forcing sponsors to demonstrate superior resistance profiles.
EMA's revised qualification opinion pathway for novel oncology biomarkers is streamlining companion diagnostic co-development timelines. The framework permits parallel scientific advice for drug and test developers. PI3K/AKT pathway indication sponsors with European headquarters are restructuring regulatory submissions to exploit this alignment.
Site selection for Phase II oncology trials is concentrating at high-volume academic centers with embedded Phase I units, displacing community-based investigator networks. Sponsors now prioritize institutions with real-world data infrastructure and rapid activation capabilities. This consolidation is most visible in the United States, where NCI-designated cancer centers capture an outsized share of AKT inhibitor enrollment.
Protein Kinase B Inhibitors Market Segmentation
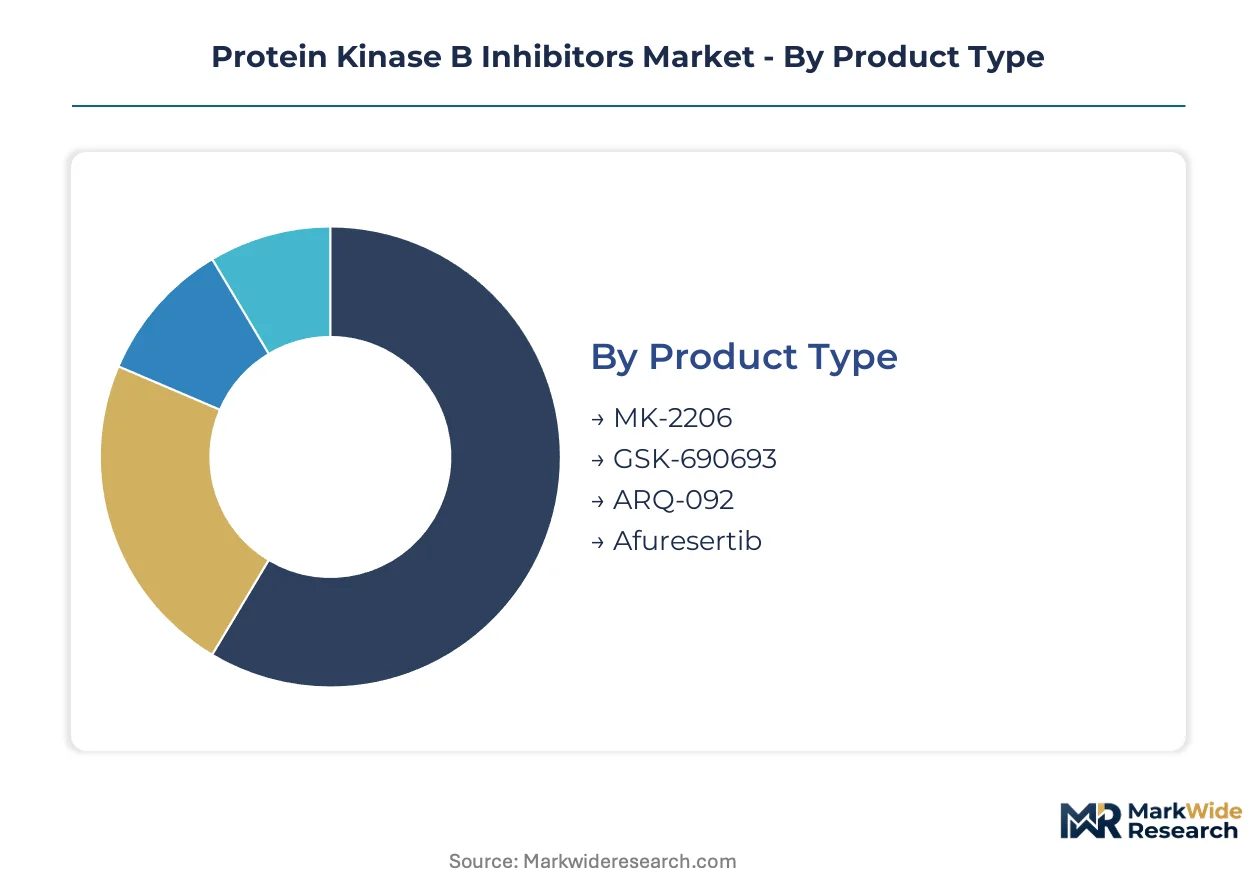
AKT inhibitor procurement patterns diverge sharply across therapeutic settings, with oncology centers prioritizing hospital-administered injectables while metabolic disease programs favor outpatient oral regimens. Understanding these segment boundaries clarifies where development resources generate the highest commercial returns.
Product Type:
Margin pools concentrate in allosteric inhibitors that circumvent ATP-binding site competition, rewarding mechanistic differentiation over incremental potency gains.
- MK-2206:An allosteric inhibitor binding the AKT pleckstrin homology domain, achieving pathway suppression without ATP pocket saturation. Demand clusters at NCI-designated cancer centers running basket trials for PI3K/AKT/mTOR pathway alterations, driven by FDA Project Optimus dose-optimization mandates that favor mechanistically guided regimens.
- Afuresertib:An ATP-competitive pan-AKT inhibitor with established safety profiles in hematologic malignancies. Prescription volume is rising at academic medical centers in Boston and San Francisco pursuing combination protocols with checkpoint inhibitors, constrained by cardiotoxicity monitoring requirements.
- GSK-690693:A potent ATP-competitive inhibitor with broad preclinical validation across solid tumor models.
- ARQ-092:A clinical-stage candidate targeting the AKT1 E17K activating mutation with allele-selective binding properties.
MK-2206 holds installed capacity. Afuresertib is rotating up the share rankings.
Indication:
Revenue concentration tilts toward cancer indications where accelerated approval pathways compress time-to-market, though metabolic disorder pipelines are expanding addressable populations into chronic disease management.
- Cancer:Dominates current clinical utilization across breast, prostate, and hematologic malignancies with hyperactivated PI3K/AKT/mTOR signaling. Oncology clinics at major academic medical centers in the United States are expanding procurement for targeted AKT pathway therapies, supported by FDA accelerated approval frameworks permitting earlier revenue recognition.
- Metabolic Disorders:Non-alcoholic steatohepatitis and insulin resistance indications are gaining protocol share as sponsors pivot from cytotoxic chemotherapy combinations toward precision chronic disease management. Early-phase units are adopting these candidates for outpatient oral regimens, climbing the fastest as type 2 diabetes trials advance.
- Inflammatory Diseases:Emerging applications in autoimmune conditions where AKT signaling modulates immune cell activation and cytokine production.
- Neurological Disorders:Preclinical exploration in neurodegenerative conditions with protein aggregation pathology and synaptic dysfunction.
Cancer commands current revenue. Metabolic Disorders are capturing incremental development allocation.
Delivery Mode:
Hospital channel economics favor injectable formulations with higher reimbursement rates, though oral regimens are displacing infusion requirements in outpatient chronic disease protocols.
- Injectable:Subcutaneous and intramuscular administration dominates oncology settings requiring precise bioavailability control and rapid dose escalation capabilities. Injectable delivery occupies the highest-value hospital channel at NCI-designated cancer centers with embedded Phase I units.
- Oral:Tablet and capsule formulations are gaining share in metabolic disorder management where patient compliance and take-home regimens determine protocol adherence. Outpatient clinics prioritize oral options for chronic disease indications.
- Infusion:Intravenous delivery maintains position in acute oncology settings requiring immediate therapeutic effect.
- Transdermal:Patch-based delivery remains exploratory for sustained-release applications in metabolic and inflammatory indications.
Injectable retains infrastructure investment. Oral is ascending the utilization curve.
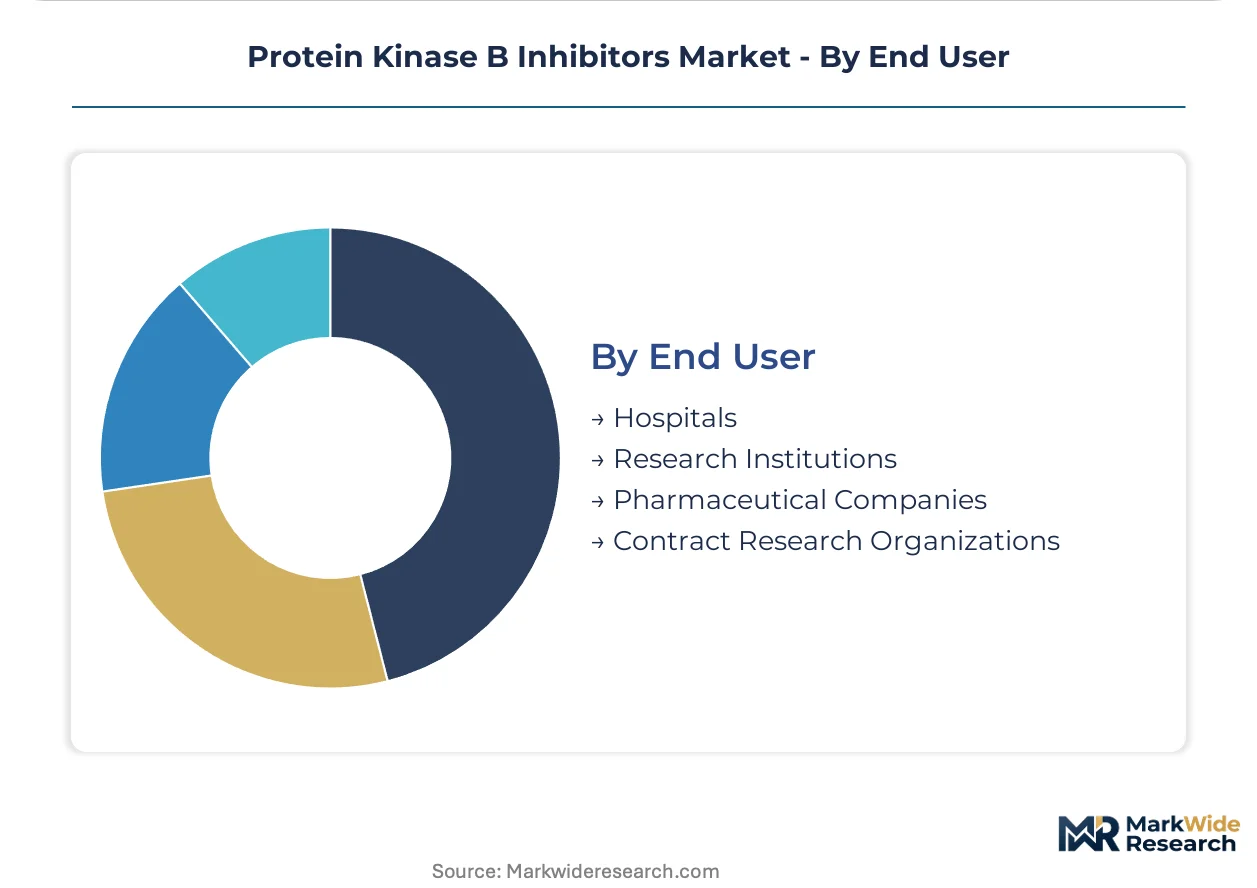
End User:
Procurement authority concentrates at institutions with real-world data infrastructure and rapid trial activation capabilities, displacing community-based investigator networks.
- Hospitals:NCI-designated cancer centers and major academic medical centers capture outsized enrollment share for AKT inhibitor trials. Site selection is concentrating at high-volume institutions with embedded Phase I units and biomarker assay standardization.
- Research Institutions:Early-phase units at Boston and San Francisco academic medical centers are adopting allosteric inhibitor candidates for basket trials, prioritizing institutions with pharmacodynamic assay capabilities.
- Pharmaceutical Companies:Sponsors with cross-platform PI3K/AKT/mTOR expertise are shortening learning curves for AKT-specific drug discovery through internal development pipelines.
- Contract Research Organizations:Multinational CROs with ISO 14155 and ICH-GCP compliance are executing trial integrity across investigator sites.
Hospitals anchor site selection. Research Institutions are expanding enrollment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial infrastructure and regulatory pathway efficiency concentrate development activity in specific national markets. Sponsors prioritize jurisdictions with accelerated approval frameworks and established PI3K/AKT/mTOR expertise clusters.
United States
FDA accelerated approval pathways and Project Optimus dose-optimization mandates compress Phase II timelines for AKT inhibitor candidates. NCI-designated cancer centers in Boston, San Francisco, and Research Triangle Park capture outsized enrollment share through embedded Phase I units and biomarker assay standardization.
Germany
EMA conditional marketing authorization frameworks and the revised qualification opinion pathway for novel oncology biomarkers streamline companion diagnostic co-development. Heidelberg and Munich academic medical centers anchor early-phase trial activity with pharmacodynamic assay capabilities.
Japan
PMDA Sakigake designation priority review vouchers reduce time-to-market for first-in-class AKT inhibitors with Japanese development presence. Tokyo and Osaka oncology centers adopt allosteric inhibitor candidates for basket trials targeting PI3K/AKT/mTOR pathway alterations.
Switzerland
Swissmedic alignment with EMA procedures permits parallel regulatory submissions for precision oncology drugs. Basel and Zurich host cross-platform PI3K/AKT/mTOR expertise clusters that shorten learning curves for AKT-specific drug discovery programs.
United Kingdom
Medicines and Healthcare products Regulatory Agency early access schemes enable conditional market entry based on surrogate endpoints. London and Cambridge academic medical centers prioritize institutions with real-world data infrastructure for site selection consolidation.
Protein Kinase B Inhibitors Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing cross-platform PI3K/AKT/mTOR pathway expertise. The competitive structure rewards mechanistic differentiation through allosteric binding modalities and combination therapy positioning with existing checkpoint inhibitor infrastructure. Three archetypes dominate: ATP-competitive specialists, allosteric mechanism innovators, and immuno-oncology integrators. Capacity expansion into outpatient oral formulations and strategic partnerships for biomarker companion diagnostic co-development represent the dominant competitive vectors.
Within the diversified pharmaceutical tier, AstraZeneca, Pfizer Inc., and Novartis AG exemplify archetype positioning. AstraZeneca represents the ATP-competitive specialist vector with established oncology infrastructure. Pfizer Inc. occupies a position across multiple AKT inhibitor candidates through broad development pipelines. Novartis AG anchors the allosteric mechanism and pathway adjacency expertise cluster.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Bristol Myers Squibb Company |
| AbbVie Inc. |
| Taiho Pharma |
| Johnson & Johnson |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Manufacturing scale economies in active pharmaceutical ingredient synthesis concentrate production among facilities with FDA and EMA certification, compressing price floors for ATP-competitive inhibitors while elevating premiums for allosteric mechanisms with limited supplier bases. This concentration grants certified manufacturers pricing power in hospital procurement channels.
Pricing Analysis
Volume-discount tiering structures separate list pricing for NCI-designated cancer centers from community oncology networks, with price differentiation driven by trial enrollment commitments and pharmacodynamic assay standardization. ATP-competitive inhibitors face cost compression as biosimilar pathways mature, while allosteric candidates command brand premiums due to mechanistic scarcity. Research institutions exhibit lowest price sensitivity; contract research organizations face tightening procurement budgets.
Supply Chain Analysis
Strategic stockpiling of critical starting materials dominates inventory strategy among API manufacturers serving AKT inhibitor programs, contrasting with just-in-time preferences for finished dose formulations. Supply concentration centers on Switzerland, Germany, and the United States for high-purity chemical intermediates. Key inputs include piperazine derivatives, fluorinated aromatics, and chiral resolution agents. Single-source vulnerability persists for pleckstrin homology domain-targeting building blocks. Distribution runs through specialized pharmaceutical wholesalers with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from biomarker stratification delays, with FDA Project Optimus dose-optimization mandates compressing Phase II timelines and accelerating revenue recognition cycles.
For Market Incumbents: Consolidate control over pharmacodynamic assay standardization to defend against emerging allosteric mechanism innovators. Secure backward integration into chiral intermediate manufacturing to reduce exposure to Swiss and German supplier concentration. Prioritize companion diagnostic co-development partnerships that lock in biomarker-defined patient populations.
For New Entrants and Emerging Players: Outpatient oral formulation capabilities represent a service-layer gap where incumbents under-serve metabolic disorder protocols. Target non-alcoholic steatohepatitis indications with take-home regimens, as this segment shows lowest competitive density. Pursue Japanese PMDA Sakigake designation as a differentiated go-to-market pathway.
For Investors and Strategic Acquirers: Clinical-stage allosteric inhibitor platforms with allele-selective binding properties offer the strongest long-term viability through the patent cliff window. Monitor pAKT readout methodology standardization progress as the critical inflection signal; cross-trial comparability breakthroughs would reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Basket trial designs at Boston and San Francisco academic centers accelerate enrollment for PI3K/AKT/mTOR pathway alterations. |
| Regulatory Approval Pathway | FDA accelerated approval based on progression-free survival surrogates compresses time-to-market versus traditional endpoints. |
| Licensing Agreement | Cross-platform PI3K/AKT/mTOR expertise licenses shorten learning curves for AKT-specific drug discovery programs. |
| Manufacturing Scale-Up | Capacity expansion into oral formulation suites captures outpatient chronic disease management demand. |
| Pipeline Diversification | Metabolic disorder indications expand addressable populations beyond oncology into insulin resistance and NASH protocols. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary intelligence combined with secondary validation through SEC 10-K disclosures and investigator site surveys. Bottom-up prescription volume modeling and top-down market sizing triangulated segment estimates.
Variance decomposition across product type, indication, delivery mode, and end user dimensions structured the analytical framework over the projection horizon. CAGRs derived from patent expiration schedules, biosimilar entry assumptions, and pathway adjacency migration rates. Forecast inputs included biomarker prevalence epidemiology and accelerated approval pathway utilization trends.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA regimes; material policy shifts would require re-modeling. Revision becomes warranted when pharmacodynamic assay standardization crosses implementation thresholds or when cardiotoxicity signals trigger class-wide protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Drug Discovery Outsourcing Market