
 Global Biopharma Buffer Market | 2026-2036
Global Biopharma Buffer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biopharma Buffer Market Foresight
The biopharma buffer supply base is pivoting between premium-grade GMP-certified formulations and commodity chemical alternatives. Thermo Fisher Scientific leverages its upstream raw material sourcing to sustain cost advantages across both tiers. Merck KGaA anchors its position through deep specialization in high-purity cell culture buffers. Avantor competes by controlling distribution networks for just-in-time delivery to biologics manufacturers.
Biopharma buffers are aqueous solutions of weak acids and their conjugate bases, formulated to resist pH changes within narrow ranges typically spanning 6.8 to 7.4 for mammalian cell culture applications, with osmolality adjusted to 280-320 mOsm/kg to maintain protein stability during purification and formulation. Phosphate and acetate buffers dominate current procurement volumes due to their established compatibility with downstream chromatography steps, while pre-mixed kits are gaining fastest traction as biotech firms outsource buffer preparation to reduce in-house validation burdens. Protein formulation and cell culture applications together occupy the largest margin pools, reflecting the complexity of stabilizing large-molecule therapeutics.
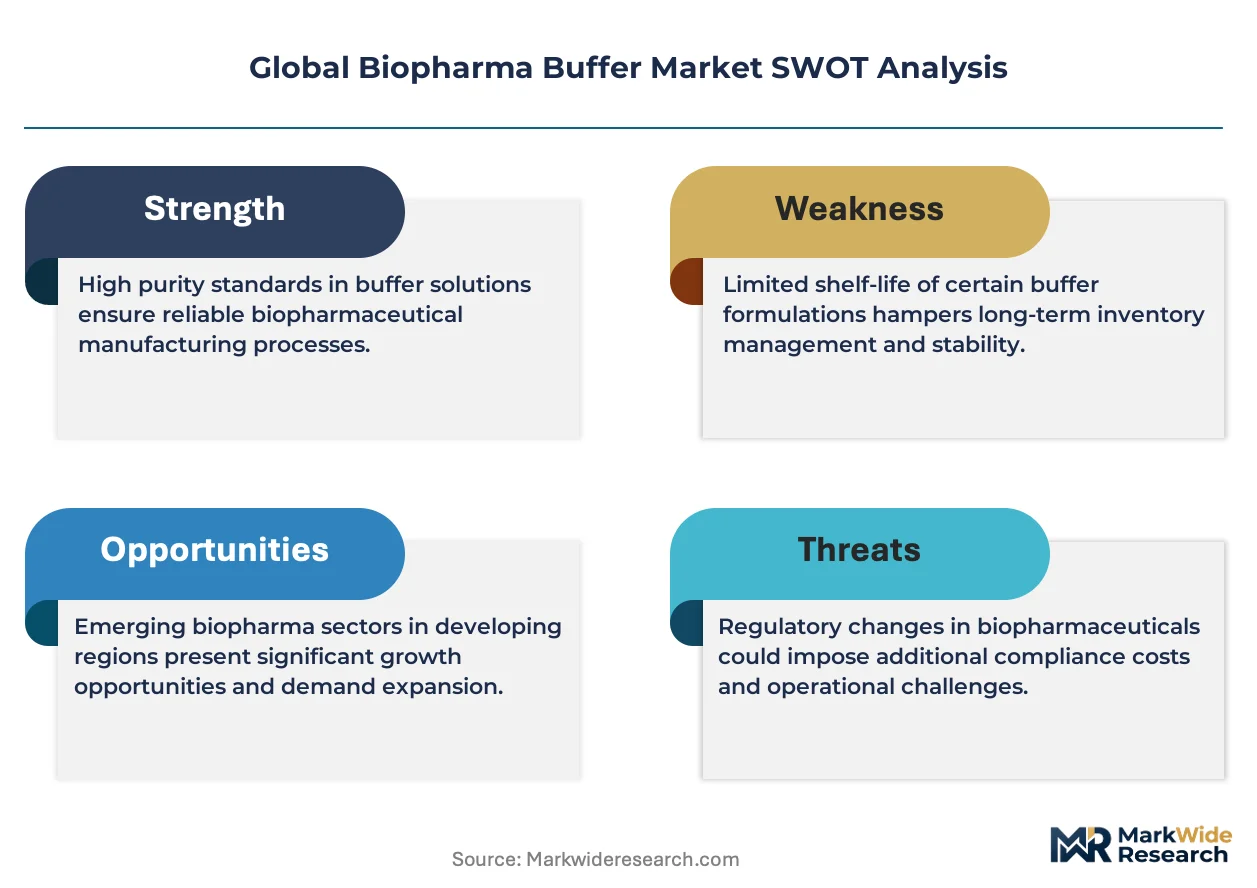
FDA Current Good Manufacturing Practice guidelines and EMA's Annex 1 revisions on sterile manufacturing compel buffer suppliers to demonstrate endotoxin levels below 0.25 EU/mL and implement enhanced particulate monitoring. ISO 13485 quality management standards further constrain market access for uncertified producers. Stakeholders must weigh backward integration into buffer manufacturing against the capital efficiency of contract supply agreements as biologics capacity expands.
Market Dynamics
Monoclonal antibody manufacturing expansion is compressing buffer preparation timelines while elevating endotoxin specifications, forcing suppliers to choose between capital-intensive in-house production networks or validated contract partnerships.
Growth Catalysts
- EMA Annex 1 revisions:Sterile manufacturing mandates for particulate monitoring below 10 microns are accelerating demand for pre-validated buffer kits among European biologics manufacturers.
- Cell therapy manufacturing clusters:Concentrated buildouts in the United States, Germany, and China are multiplying buffer consumption volumes per production site.
- Single-use bioprocessing technologies:Disposable mixing systems eliminate stainless steel cleaning validation, reducing cross-contamination risks during buffer preparation.
Market Restraints
- Raw material cost volatility:Pharmaceutical-grade phosphate and acetate salts face price swings tied to agricultural fertilizer demand cycles and energy-intensive purification.
- Supply concentration risk:High-purity acid and base production concentrates among specialty chemical producers in Germany and China, creating single-source vulnerabilities.
- ISO 13485 certification barriers:Quality management system requirements exclude uncertified regional chemical distributors from sterile buffer supply chains.
Strategic Opportunities
- India biologics manufacturing:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting contract development organizations requiring GMP-certified buffer supply.
- Pre-mixed buffer kits:Outsourced preparation reduces in-house validation burdens for emerging biotech firms with limited analytical capabilities.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with inline buffer dilution systems enables real-time pH adjustment without batch hold tanks.
Industry Challenges
- Analytical method transfer:Biologics manufacturers struggle to validate supplier-provided endotoxin and bioburden test methods against internal quality standards.
- Cold chain integrity:Temperature-sensitive buffer concentrates require validated shipping containers for just-in-time delivery to cell therapy facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biopharma Buffer Market |
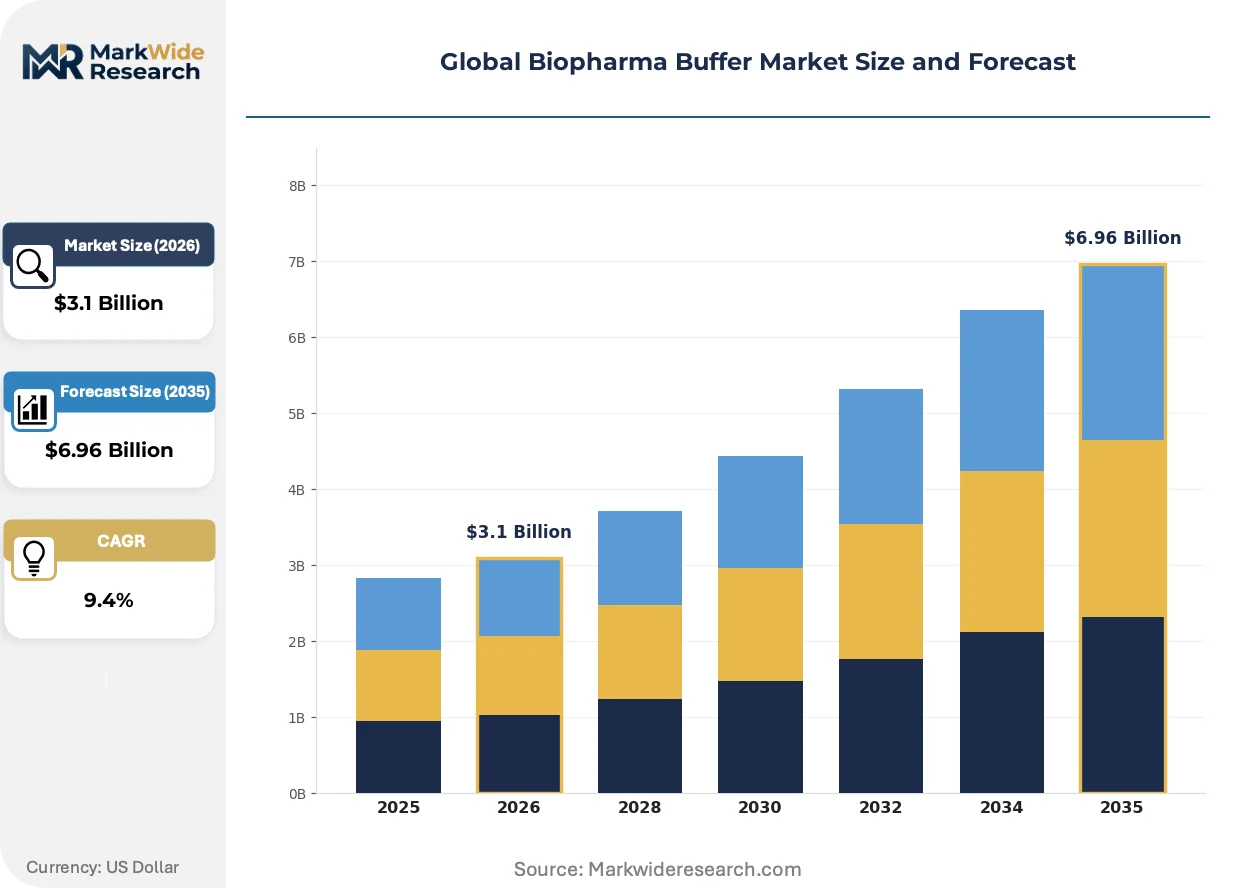
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.96 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Buffers, Citrate Buffers, Acetate Buffers, Tris Buffers, Bicarbonate Buffers Application: Protein Formulation, Cell Culture, Chromatography, pH Adjustment, Enzyme Stabilization End User: Biotech Firms, Pharmaceutical Manufacturers, Contract Research Organizations, Academic Institutions Packaging Type: Bulk Containers, Bottled Solutions, Powdered Form, Pre-Mixed Kits |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc., Avantor, Inc., Lonza Group Ltd., Bio-Rad Laboratories, Inc., GE Healthcare, Sartorius, F. Hoffmann-La Roche Ltd., Santa Cruz Biotechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biopharma Buffer Market Shifts & Advancements
Buffer formulation is pivoting from commodity chemical sourcing toward integrated supply partnerships that bundle raw material qualification, sterile filtration, and regulatory documentation.
Automated buffer dilution systems are electrifying upstream bioprocessing workflows by eliminating manual pH adjustment steps. Contract manufacturers in the United States and Switzerland are deploying these skid-mounted units to support multi-product facilities. The technology is electrifying competitive differentiation among suppliers capable of delivering concentrated stock solutions with guaranteed dilution accuracy.
FDA's evolving stance on real-time release testing for in-process buffer parameters is compressing analytical timelines for monoclonal antibody producers. Manufacturers must now demonstrate continuous pH and conductivity monitoring rather than end-point testing. Mammalian cell culture applications face the steepest compliance burden as FDA inspectors prioritize buffer hold-time studies during pre-approval inspections.
Biologics procurement teams are consolidating supplier relationships to reduce qualification overhead, favoring distributors with multi-site stocking agreements over spot-market chemical purchases. Large-cap pharmaceutical firms now mandate single-source contracts covering phosphate, acetate, and histidine buffer families. This concentration is most visible in Germany's Rhine-Main biotechnology corridor, where three manufacturers have shifted to sole-supplier arrangements since 2024.
Global Biopharma Buffer Market Segmentation
Buffer selection in biopharma manufacturing hinges on compatibility with specific unit operations, endotoxin specifications, and supply chain reliability. Segmentation reveals how procurement priorities diverge between high-volume monoclonal antibody producers and emerging cell therapy developers with limited in-house formulation capabilities.
Product Type:
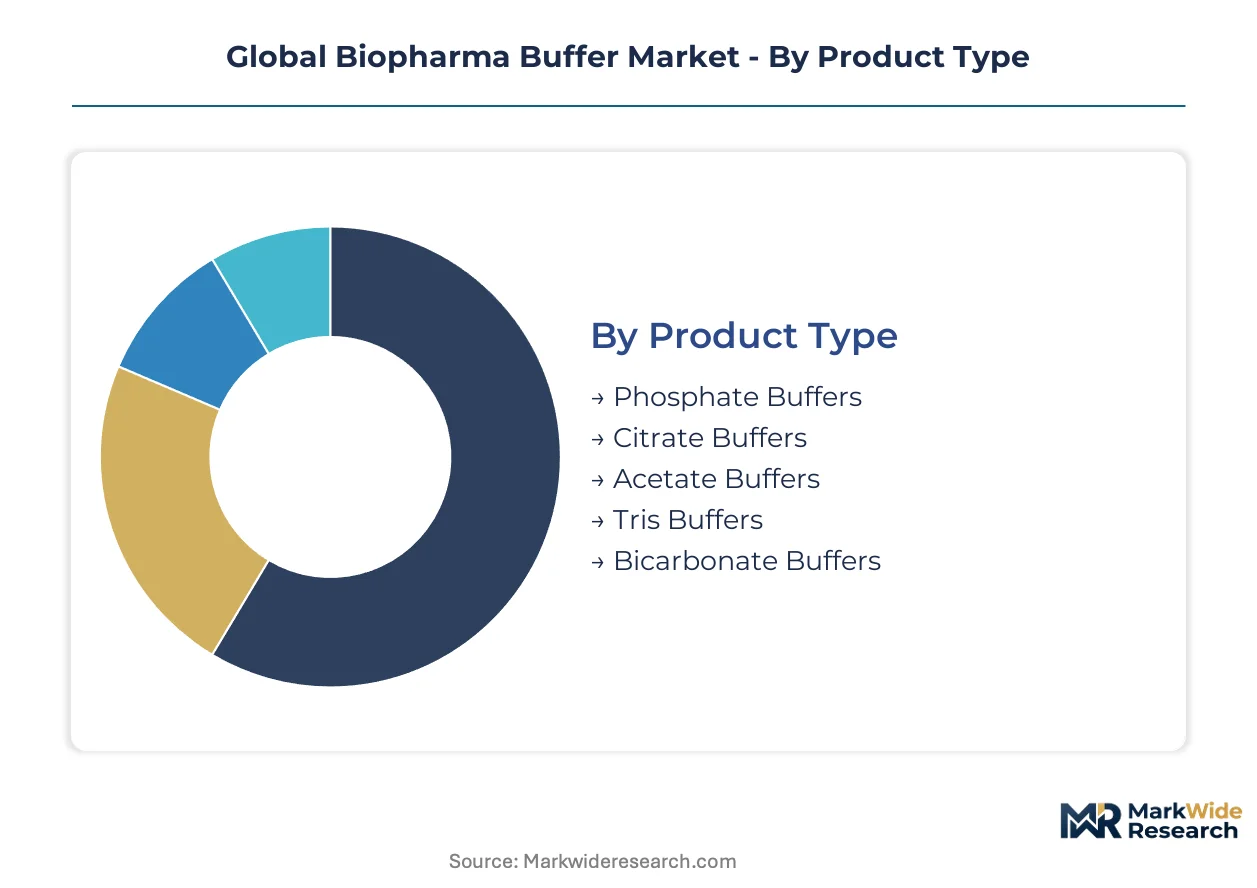
Phosphate and citrate buffers dominate standalone procurement for downstream purification, while acetate and tris formulations increasingly embed into pre-mixed kits for upstream cell culture applications.
- Phosphate Buffers:Combinations of sodium or potassium phosphates maintain pH 6.8-7.4 with excellent protein solubility. Mammalian cell culture facilities in the United States and Germany specify pharmaceutical-grade monobasic and dibasic salts for chromatography equilibration and wash steps. EMA Annex 1 particulate limits are compressing supplier qualification timelines for phosphate buffer concentrates.
- Citrate Buffers:Trisodium citrate and citric acid systems span pH 3.0-6.2, ideal for viral inactivation and protein stabilization during low-pH hold steps. Chinese biologics manufacturers are expanding citrate buffer consumption fastest as local biosimilar pipelines mature.
- Acetate Buffers:Sodium acetate-acetic acid pairs serve ion exchange chromatography and protein formulation at pH 3.6-5.6.
- Tris Buffers:Tris(hydroxymethyl)aminomethane systems buffer at pH 7.0-9.0 for nucleic acid applications and certain cell culture media.
- Bicarbonate Buffers:Sodium bicarbonate-carbon dioxide equilibria maintain physiological pH in CO₂-incubated cell culture vessels.
Phosphate buffers lead volumes today; pre-mixed kits across all chemistries are gaining share fastest.
Application:
Protein formulation and chromatography absorb the highest per-unit buffer costs, while cell culture applications drive absolute volume expansion as perfusion bioreactors multiply buffer turnover rates.
- Protein Formulation:Final drug product buffers must demonstrate 24-month stability with pH drift below 0.3 units and subvisible particle counts meeting USP <788>. FDA pre-approval inspections prioritize formulation buffer hold-time studies.
- Cell Culture:Media and feed buffers require endotoxin levels below 0.25 EU/mL and osmolality 280-320 mOsm/kg. Manufacturing clusters in Boston, Basel, and Shanghai are concentrating demand for large-volume phosphate and bicarbonate systems.
- Chromatography:Equilibration, wash, and elution buffers demand precise conductivity control for resin binding optimization.
- pH Adjustment:Concentrated acid and base solutions enable real-time bioreactor pH correction.
- Enzyme Stabilization:Specialized buffers preserve activity during bioconjugation and biocatalytic synthesis steps.
Cell culture dominates absolute consumption; protein formulation commands the steepest premium pricing.
End User:
Pharmaceutical manufacturers maintain captive buffer preparation capabilities, while biotech firms and contract research organizations increasingly outsource to reduce validation overhead.
- Biotech Firms:Emerging developers with limited analytical infrastructure favor pre-mixed kits and contract supply agreements. CDSCO's streamlined biosimilar pathways in India are attracting biotech entrants requiring GMP-certified buffer sourcing.
- Pharmaceutical Manufacturers:Large-cap firms like those in Germany's Rhine-Main corridor consolidate to single-source contracts across phosphate, acetate, and histidine buffer families.
- Contract Research Organizations:Multi-product facilities demand flexible buffer supply with rapid lot release.
- Academic Institutions:Research-grade buffers for preclinical studies operate outside GMP compliance requirements.
Pharmaceutical manufacturers anchor procurement volumes; biotech firms are expanding contract buffer consumption most rapidly.
Packaging Type:
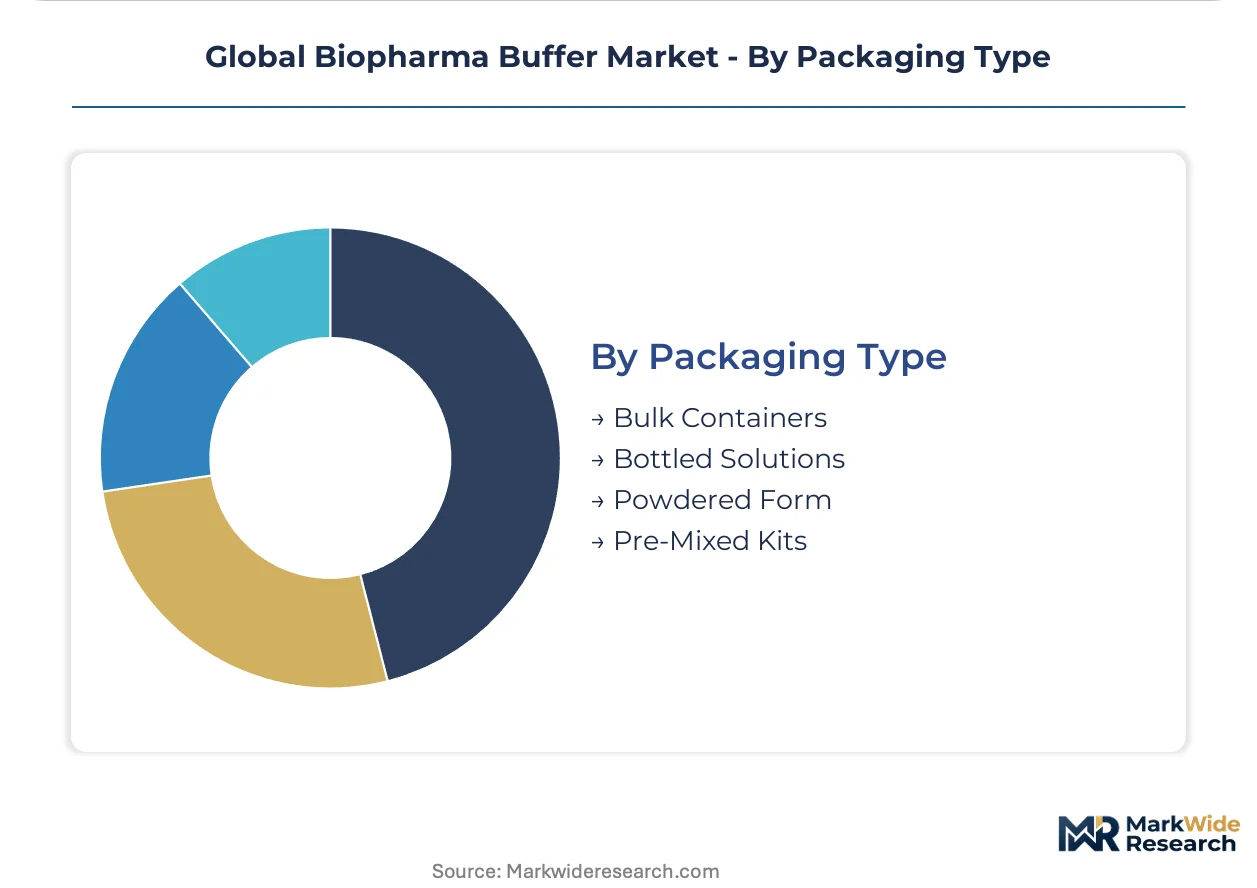
Bulk containers suit high-volume monoclonal antibody facilities with automated dilution skids, while pre-mixed kits address cell therapy sites lacking sterile formulation infrastructure.
- Pre-Mixed Kits:Sterile-filtered, pre-qualified buffer concentrates eliminate in-house validation and reduce contamination risk. Cell therapy manufacturing in the United States and Switzerland is driving fastest adoption for just-in-time delivery models.
- Bulk Containers:Tote systems and tanker deliveries minimize per-liter packaging costs for chromatography operations consuming thousands of liters weekly.
- Bottled Solutions:Laboratory-scale volumes support analytical method development and small-batch clinical manufacturing.
- Powdered Form:Dry blends reduce shipping weight and enable on-site dissolution for facilities with validated water-for-injection systems.
Bulk containers retain volume leadership; pre-mixed kits are climbing the fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and bioprocess engineers cluster in the United States, Germany, and China, anchoring the three dominant biopharma buffer demand centers worldwide.
United States
Monoclonal antibody manufacturing expansion in Massachusetts and California multiplies buffer consumption volumes per production site. FDA Current Good Manufacturing Practice guidelines compel endotoxin levels below 0.25 EU/mL and enhanced particulate monitoring protocols. The Boston-Cambridge biotechnology corridor concentrates demand for large-volume phosphate and bicarbonate systems as perfusion bioreactor adoption accelerates.
Germany
EMA Annex 1 revisions on sterile manufacturing drive fastest adoption of pre-validated buffer kits among European biologics manufacturers. The country's national pharmaceutical regulator mandates particulate monitoring below 10 microns for all sterile buffer preparations. The Rhine-Main biotechnology corridor has shifted three major manufacturers to sole-supplier arrangements since 2024, consolidating procurement relationships.
China
Cell therapy manufacturing clusters in Shanghai and Suzhou expand buffer consumption as local biosimilar pipelines mature. NMPA regulatory harmonization with international standards elevates quality benchmarks for imported and domestically produced buffer formulations. The Yangtze River Delta region anchors fastest-growing citrate buffer demand for viral inactivation and protein stabilization applications.
Switzerland
Contract manufacturers deploy automated buffer dilution systems to support multi-product facilities serving global pharmaceutical clients. Swissmedic quality requirements align buffer qualification timelines with EU regulatory standards. Basel's biologics manufacturing hub drives premium-grade GMP-certified buffer procurement for protein formulation applications.
India
CDSCO streamlined biosimilar approval pathways and PLI scheme incentives attract contract development organizations requiring GMP-certified buffer supply. The central government's production-linked incentive scheme reduces import dependency for pharmaceutical-grade raw materials. Maharashtra and Karnataka biotech clusters expand pre-mixed kit consumption as emerging developers outsource buffer preparation.
Global Biopharma Buffer Market Competitive Landscape
Top-tier vendors anchor premium-grade GMP-certified formulations, while commodity chemical alternatives compete on cost efficiency across high-volume chromatography applications. The supply base pivots between backward integration into raw material sourcing and validated contract manufacturing partnerships. Three strategic archetypes dominate: diversified life science conglomerates with upstream chemical control, specialized high-purity buffer formulators, and distribution-centric suppliers prioritizing just-in-time logistics. Capacity expansion and strategic partnerships represent the dominant competitive moves as biologics manufacturing scales globally.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify contrasting approaches to market positioning. Thermo Fisher leverages integrated raw material sourcing across both premium and standard buffer tiers, while Merck KGaA occupies a position emphasizing deep specialization in high-purity cell culture formulations. Avantor, Inc. represents the distribution-centric archetype, anchoring competitive differentiation through controlled logistics networks rather than captive manufacturing.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Avantor, Inc. |
| Lonza Group Ltd. |
| Bio-Rad Laboratories, Inc. |
| GE Healthcare |
| Sartorius |
| F. Hoffmann-La Roche Ltd. |
| Santa Cruz Biotechnology, Inc. |
| Others |
Supply & Pricing Matrix
Agricultural phosphate and acetate salt indices cascade through biopharma buffer supply chains, compressing margins on commodity-grade formulations while elevating premiums for GMP-certified alternatives. Pharmaceutical-grade purification costs and endotoxin testing burdens stratify pricing tiers between validated contract supply and spot-market chemical sourcing.
Pricing Analysis
Pre-mixed buffer kits versus bulk concentrate procurement splits the market into service-bundled and unbundled pricing models. Premium-mid-economy pricing differentiation rests on ISO 13485 certification status and lot-release documentation depth. Cost compression in standard-grade phosphate buffers is intensifying because agricultural fertilizer demand cycles spike raw material volatility. Emerging biotech firms with limited analytical infrastructure exhibit highest price sensitivity, while large-cap pharmaceutical manufacturers prioritize supply security over per-liter cost.
Supply Chain Analysis
Direct-to-biomanufacturer channels handle high-volume monoclonal antibody facility demand, while distribution partners serve cell therapy sites requiring just-in-time delivery. High-purity acid and base production concentrates in Germany and China, creating single-source vulnerabilities for Western biologics manufacturers. Supply chains draw from pharmaceutical-grade phosphate salts, acetate precursors, and WFI-grade water systems. Tariff exposure on Chinese-sourced raw materials threatens cost stability for non-vertically integrated formulators. Distribution runs through specialized chemical distributors with cold-chain capabilities and multi-site stocking agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biopharma buffer market functions as a stable compounder anchored by irreversible biologics capacity expansion and deepening regulatory quality mandates.
For Market Incumbents: Lock in sole-supplier arrangements across phosphate, acetate, and histidine buffer families to preempt qualification overhead consolidation by large pharmaceutical manufacturers. Defend margin position through backward integration into pharmaceutical-grade raw material sourcing, insulating against agricultural commodity price swings. Prioritize EMA Annex 1-compliant particulate monitoring infrastructure to capture European pre-validated kit demand. For New Entrants and Emerging Players: Mid-size Indian biotech firms represent the most penetrable buyer archetype, underserved by incumbent distributors focused on US and European clusters. CDSCO's streamlined biosimilar pathways and PLI scheme incentives create white-space demand for GMP-certified pre-mixed kits. Contract development organizations with limited sterile formulation infrastructure offer second entry point through outsourced buffer preparation services. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification barriers exclude regional chemical distributors from sterile supply chains. Five-to-ten year viability favors specialized high-purity formulators with captive raw material qualification capabilities over commodity chemical traders. Acquisition target archetype: mid-cap buffer formulators with validated endotoxin testing infrastructure and existing pharmaceutical manufacturer relationships. Monitor NMPA regulatory harmonization progress as inflection signal for Chinese domestic supplier quality upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Thermo Fisher Scientific's upstream phosphate control insulates margin against agricultural commodity cycles. |
| Pre-Mixed Buffer Kit Expansion | Merck KGaA's high-purity cell culture formulations reduce validation burdens for emerging biotech clients. |
| Multi-Site Distribution Network Buildout | Avantor's just-in-time logistics capabilities anchor competitive differentiation in cell therapy corridors. |
| Automated Buffer Dilution System Deployment | Swiss contract manufacturers deploy skid-mounted units to support multi-product facility flexibility. |
| EMA Annex 1 Compliance Infrastructure Investment | European biologics manufacturers accelerate pre-validated kit adoption under particulate monitoring mandates. |
Research Methodology
Coverage spans the United States, Germany, China, Switzerland, and India, with primary inputs from each market cluster. The research combines structured interviews with bioprocess engineers, regulatory affairs leads, procurement managers at biologics manufacturers, and quality control directors at buffer formulators with secondary validation. Secondary sources include FDA Current Good Manufacturing Practice guidelines, EMA Annex 1 revision documents, NMPA regulatory harmonization notices, CDSCO biosimilar pathway publications, and SEC filings from publicly traded life science conglomerates. Bottom-up buffer consumption estimates triangulate against top-down biologics manufacturing capacity projections.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. The analytical framework models segmentation across buffer chemistry type, application endpoint, end-user archetype, and packaging format, with regional regulatory cluster as an overlay dimension. CAGRs derive from regression analysis against biologics pipeline depth and manufacturing capacity buildout rates. Forecast inputs incorporate perfusion bioreactor adoption curves and single-use technology penetration by facility type.
Inputs from regulatory filings and manufacturer disclosures were available through the study window; gaps in real-time buffer consumption telemetry at contract manufacturing organizations introduce uncertainty bands around quarterly estimates. Forecasts reflect assumptions regarding EMA Annex 1 implementation timelines and NMPA inspection intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Tetracycline Market