
 Generic Drugs Market | 2026-2036
Generic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Generic Drugs Market Intelligence
The growing prevalence of complex chronic conditions, particularly in oncology, is repositioning the generic drugs market away from simple, high-volume small molecules. This shift creates opportunities in higher-value therapeutic segments. Teva Pharmaceutical Industries leverages its extensive portfolio to compete in both specialty and traditional generics. Sandoz Group specializes in complex generics and biosimilars, targeting these higher-margin therapeutic areas. Sun Pharmaceutical Industries sustains a strong position in key emerging markets through its large-scale manufacturing capabilities.
Generic drugs are pharmaceutical products designed to be bioequivalent to an originator brand-name drug, containing the same active pharmaceutical ingredient. They must match the innovator product in dosage, safety, strength, and intended use to gain regulatory approval. While the cardiovascular therapy area represents a mature and high-volume segment, oncology generics offer significant growth potential due to patent expirations on complex biologics. Tablet and capsule product types continue to dominate production volume, but injectable generics are gaining share, especially within hospital settings.
Regulatory frameworks established by agencies like the US FDA and the EMA create abbreviated pathways for generic drug approval, such as the Abbreviated New Drug Application (ANDA) process. In parallel, bodies like India's CDSCO enforce quality standards for active pharmaceutical ingredients supplied to manufacturers. Stakeholders must now navigate the strategic choice between pursuing high-volume, low-margin tenders and investing in the complex manufacturing required for next-generation biosimilars.
Market Dynamics
The generic drugs market is defined by the strategic tension between producing high-volume, low-margin small molecules and investing in the complex capabilities for higher-value biosimilars. This bifurcation is driven by a wave of patent expirations on complex biologic drugs.
Growth Catalysts
- Government Cost-Containment Initiatives:Healthcare systems worldwide, particularly in Europe and North America, are implementing policies that favor generic substitution to manage budgets, creating a sustained demand pull for affordable alternatives to branded drugs.
- Digital Pharmacy Expansion:The proliferation of online pharmacies improves patient access and convenience, creating a powerful new distribution channel that accelerates volume sales for over-the-counter and prescription generic medications.
- Demographic Shifts in Emerging Markets:China's large and aging population, coupled with healthcare reforms aimed at affordability, is creating a massive patient base seeking cost-effective treatments for chronic conditions, driving significant market growth.
Market Restraints
- Intense Price Erosion:In mature therapeutic categories like cardiovascular drugs, fierce competition among numerous manufacturers leads to aggressive pricing strategies and tender-based procurement, severely compressing profit margins for commodity generics.
- Stringent Regulatory Hurdles:While pathways like the US FDA's Abbreviated New Drug Application (ANDA) exist, the process remains lengthy and costly, creating a significant barrier for smaller firms and delaying market entry.
- API Supply Chain Concentration:Heavy reliance on a few countries, primarily China and India, for Active Pharmaceutical Ingredients (APIs) exposes the entire market to risks from geopolitical instability, trade disputes, and localized quality control failures.
Strategic Opportunities
- Complex Generics and Biosimilars:The upcoming patent cliff for major biologic drugs, especially in oncology and immunology, presents a significant opportunity for manufacturers capable of developing and scaling production of biosimilars.
- Injectable and Alternative Dosage Forms:Moving beyond traditional tablets and capsules into more complex delivery systems like long-acting injectables, transdermal patches, or inhalers offers a path to product differentiation and higher value.
- Geographic Expansion into Underserved Markets:Markets across Latin America and Southeast Asia represent substantial growth potential as healthcare spending and infrastructure improve, opening new territories for established generic products.
Industry Challenges
- Complex Manufacturing Investment:The production of biosimilars requires substantial capital expenditure in advanced bioprocessing technologies and specialized scientific talent, posing a high barrier to entry compared to small molecule synthesis.
- Aggressive Patent Litigation:Originator pharmaceutical companies frequently use defensive patenting strategies, known as patent thickets, to extend market exclusivity, forcing generic challengers into costly and prolonged legal disputes.
- Global Quality Compliance:Ensuring consistent quality and purity of APIs sourced from a fragmented global supplier base, while adhering to the strict cGMP standards of the EMA and FDA, is a persistent operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generic Drugs Market |
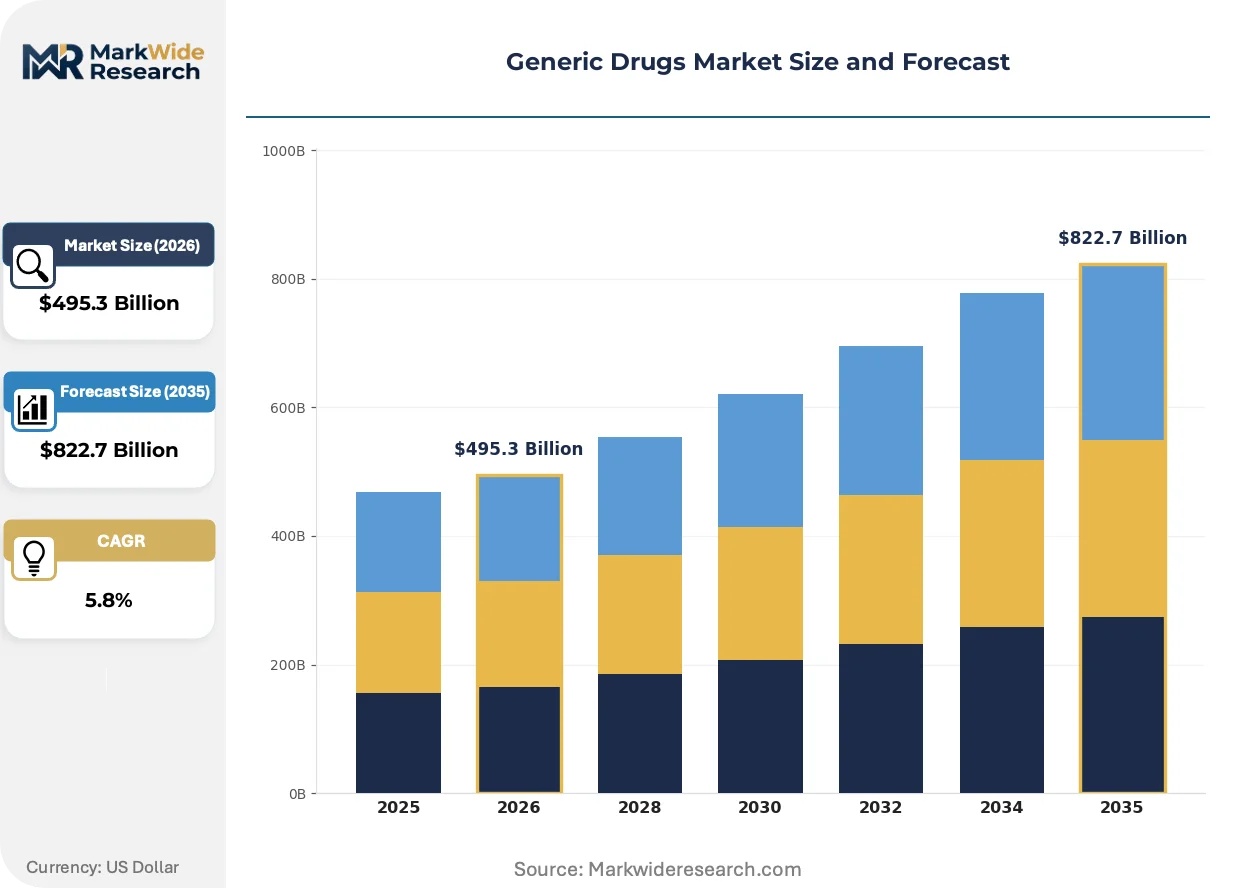
| Market Size in 2026 | $495.3 Billion |
| Market Size in 2035 | $822.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Topical, Injectable Therapy Area: Cardiovascular, Oncology, Antibiotics, Antidepressants End User: Hospitals, Retail Pharmacies, Online Pharmacies, Clinics Distribution Channel: Direct Sales, Wholesalers, Distributors, Pharmacy Chains |
| Companies Covered | Teva Pharmaceutical Industries, Viatris, Sandoz Group, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, Aurobindo Pharma, Cipla, Lupin, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generic Drugs Market Strategic Shifts & Innovations
The market is evolving from a focus on simple chemical copies to a more sophisticated model integrating advanced manufacturing, digital patient access, and specialized product development. This transition is creating distinct competitive arenas for commodity and complex generic producers.
Continuous manufacturing is an advanced production method that integrates multiple synthesis and finishing steps into a single, uninterrupted process flow. Major generic manufacturers are adopting this technology to enhance efficiency, reduce waste, and improve quality consistency for high-volume products. This technology is modularizing production lines, enabling more rapid changeovers between different drug formulations and increasing overall plant flexibility.
Harmonization of international regulatory standards, driven by bodies like the ICH, is streamlining the global drug approval process. This alignment allows manufacturers to use a single set of clinical and quality data for submissions to multiple agencies, such as the US FDA, Europe's EMA, and Japan's PMDA. Generic firms with global ambitions are the most affected, as they can significantly reduce the time and cost associated with duplicative testing for market entry.
Consolidated purchasing by large healthcare buyers is altering demand patterns for many generic categories. Centralized procurement by Group Purchasing Organizations (GPOs) and Pharmacy Benefit Managers (PBMs) favors large-scale, tender-based contracts over direct sales to individual hospitals or pharmacies. This dynamic is most visible in the United States, where it intensifies price competition for widely used generics in therapeutic areas like diabetes and hypertension.
Generic Drugs Market Segmentation
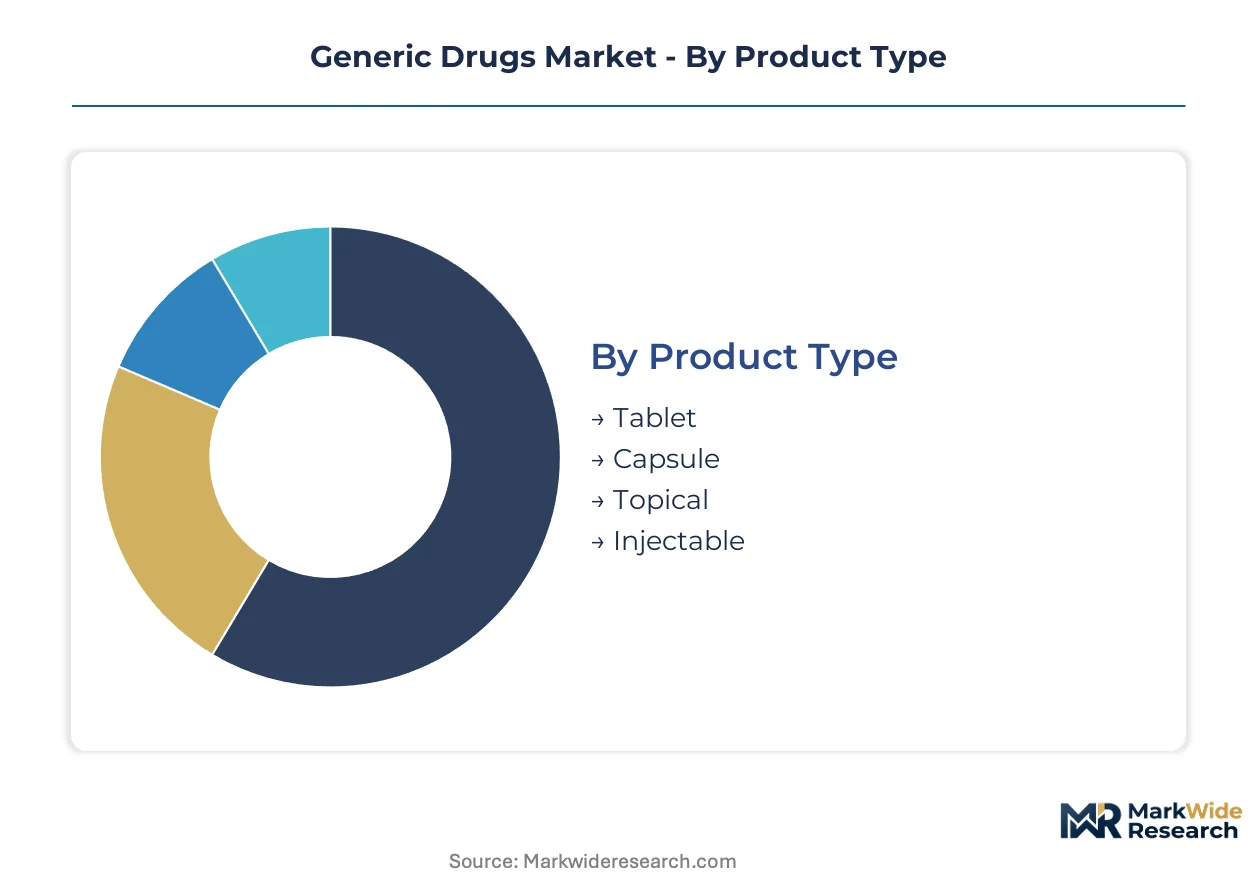
The generic drugs market is fundamentally shaped by how different product forms, therapeutic applications, and distribution channels evolve. Understanding these distinct segments helps manufacturers align their production capabilities with shifting demand patterns and emerging patient needs across various healthcare settings.
Product Type:
The generic drug market's product type segmentation reflects the ongoing upgrade cycle from traditional oral solids to more complex delivery systems.
- Injectable:These sterile preparations are administered via injection, often requiring specialized manufacturing and cold chain logistics. Demand for injectables is concentrating in hospital settings, driven by the need for high-potency drugs and an increasing prevalence of chronic conditions requiring parenteral administration.
- Tablet:Solid dosage forms containing active pharmaceutical ingredients with excipients, typically taken orally. Tablet production dominates volume due to established manufacturing processes and patient familiarity, especially for high-volume small molecule generics in primary care.
- Capsule:Oral dosage forms where the drug is enclosed within a soluble shell, often preferred for taste masking or controlled release. Capsule generics maintain a consistent demand in various therapeutic areas, offering an alternative to tablets for patient compliance.
- Topical:These formulations are applied to the skin or mucous membranes for localized or systemic effects, including creams, gels, and patches. Topical generics serve specific dermatological and pain management needs, offering non-invasive treatment options.
Volume placements concentrate in Tablet formulations; the faster expansion belongs to Injectable products.
Therapy Area:
Therapy area segmentation highlights differing margin profiles and regulatory pathways, influencing strategic investment decisions for generic manufacturers.
- Oncology:Generic versions of cancer treatments, including small molecules and biosimilars for complex biologics. This area offers substantial growth potential due to numerous upcoming patent expirations and the high cost of originator oncology drugs.
- Cardiovascular:Generic drugs treating heart and circulatory conditions, such as hypertension, cholesterol, and arrhythmias. This represents a mature, high-volume segment with intense price competition among numerous generic suppliers.
- Antibiotics:Generic anti-infective agents used to treat bacterial infections. Demand for these generics remains robust globally, particularly in emerging markets where infectious diseases are prevalent.
- Antidepressants:Generic medications for mood disorders, including selective serotonin reuptake inhibitors (SSRIs) and tricyclic antidepressants. These generics provide affordable treatment options for a widespread chronic mental health condition.
Oncology presents the steepest expansion trajectory, while Cardiovascular maintains a consistent, high-volume presence.
End User:
The end-user segmentation illustrates how different healthcare providers influence generic drug procurement and patient access.
- Online Pharmacies:Digital platforms that dispense prescription and over-the-counter generic medications directly to patients. This channel is experiencing accelerated demand due to enhanced patient convenience and improved digital accessibility.
- Hospitals:Healthcare institutions that procure and administer generic drugs for inpatient and outpatient care. Hospitals often rely on bulk purchasing and tenders for essential generic medications, particularly injectables.
- Retail Pharmacies:Traditional brick-and-mortar pharmacies that dispense generic drugs directly to patients. These pharmacies serve as a primary access point for prescription refills and over-the-counter generic purchases.
- Clinics:Smaller healthcare facilities, including physician offices and specialized treatment centers, that administer or dispense generic medications. Clinics typically purchase generics in smaller volumes compared to hospitals or large pharmacy chains.
Hospitals drive significant volume, with Online Pharmacies emerging as a critical growth channel.
Distribution Channel:
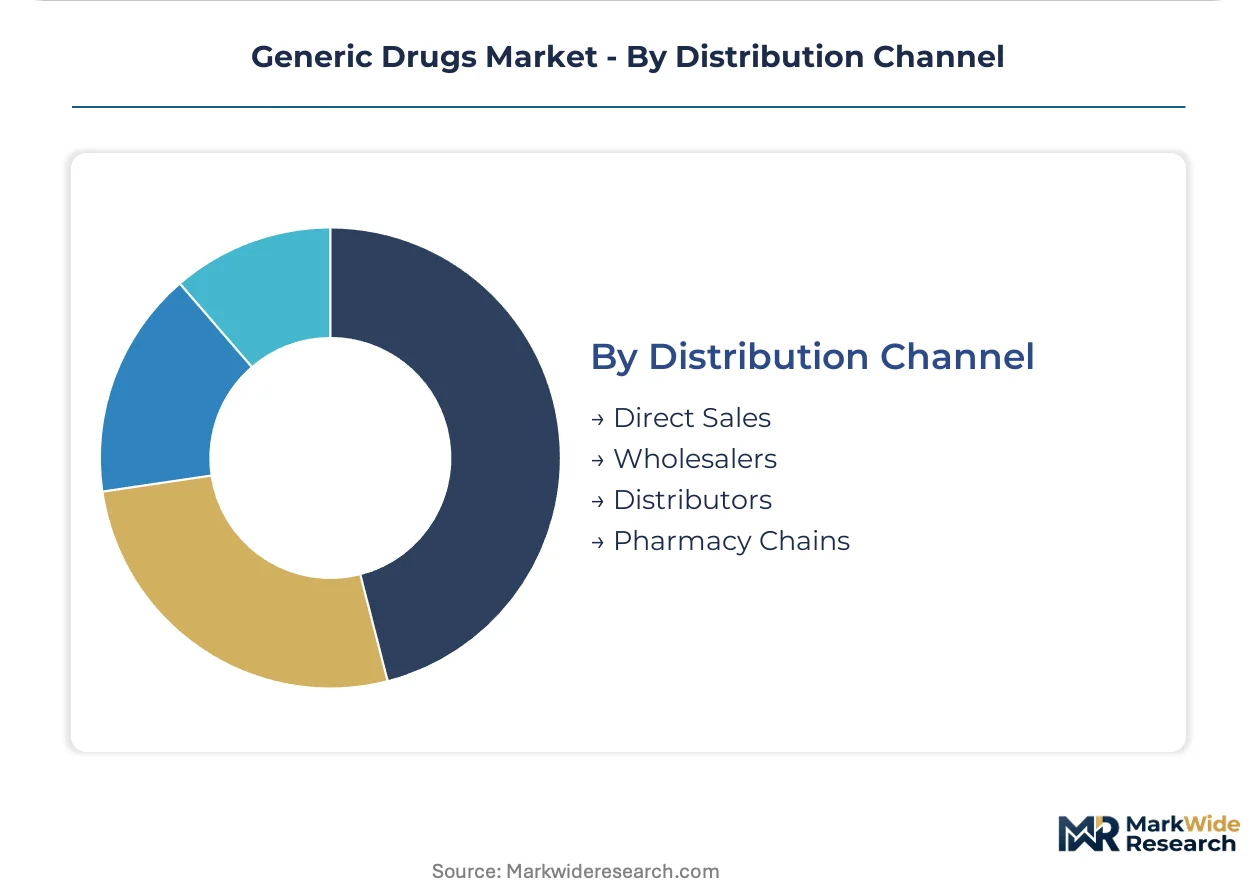
Distribution channel dynamics reflect the complex supply chain mechanisms through which generic drugs reach end-users.
- Wholesalers:Large-scale distributors that purchase generic drugs from manufacturers and supply them to pharmacies, hospitals, and clinics. Wholesalers play a central role in consolidated purchasing and tender-based contracts across many regions.
- Pharmacy Chains:Networks of multiple retail pharmacies operating under a single brand, often with centralized procurement. These chains leverage their scale to negotiate favorable terms for generic drug purchases, intensifying price competition.
- Direct Sales:Generic manufacturers selling products directly to large institutional buyers or government agencies. This channel bypasses intermediaries, often used for specialized or high-volume contracts.
- Distributors:Intermediaries that manage the logistics and delivery of generic drugs from manufacturers to various healthcare providers. Distributors facilitate market access, especially for smaller manufacturers or niche products.
Wholesalers remain fundamental for broad reach; Pharmacy Chains are gaining strategic importance in procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hyderabad Pharma City in India exemplifies a concentrated zone for pharmaceutical manufacturing and research, attracting substantial investment in generic drug production. This dedicated industrial park streamlines regulatory processes and provides infrastructure, fostering a competitive ecosystem. Such specialized zones are crucial for scaling up generic drug output and reducing costs globally.
United States
United States demand for generic drugs is driven by extensive government cost-containment initiatives and an expanding aging population. The US FDA's Abbreviated New Drug Application (ANDA) process provides an abbreviated pathway for generic drug approval. The Greater Philadelphia region maintains a robust biopharmaceutical cluster, fostering innovation in generic drug development and manufacturing.
Germany
Germany's generic drug market benefits from healthcare system reforms prioritizing affordable treatment options for its stable population. The Federal Institute for Drugs and Medical Devices (BfArM) oversees national drug approvals and quality control. The Rhine-Main region hosts a significant pharmaceutical industry cluster, concentrating research and production facilities for various generic manufacturers.
India
India's market for generic drugs is propelled by its vast patient population and a national focus on accessible, cost-effective treatment solutions. The Central Drugs Standard Control Organization (CDSCO) rigorously enforces quality standards for active pharmaceutical ingredients. Manufacturing hubs in Hyderabad and Gujarat produce a substantial volume of generic drugs for both domestic and international markets.
China
China's generic drug expansion is fueled by ongoing healthcare system reforms and a substantial aging patient population seeking affordable medications. The National Medical Products Administration (NMPA) streamlines regulatory pathways for generic drug market entry. The Yangtze River Delta region serves as a key pharmaceutical manufacturing base, integrating advanced production technologies.
Japan
Japan's generic drug adoption is increasing due to government initiatives promoting their use and a wave of recent patent expirations. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures the safety and efficacy of generic medications. Major pharmaceutical companies have research and development centers in the Tokyo metropolitan area, focusing on biosimilar development.
Generic Drugs Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the generic drugs market. The market structure exhibits a tiered consolidation, with large multinational players dominating high-volume, small-molecule generics, while specialized firms target complex biosimilars. Two primary strategic archetypes emerge: commodity generic producers focusing on scale and efficiency, and complex generic developers investing in advanced manufacturing. Portfolio diversification and strategic partnerships represent dominant competitive moves for market participants.
At the scale-driven end, Teva Pharmaceutical Industries and Sun Pharmaceutical Industries exemplify multinational corporations with extensive portfolios across various therapeutic areas. These firms leverage their global manufacturing capabilities and broad distribution networks to maintain strong positions in both traditional and emerging markets, often competing on price and volume for commodity products. Sandoz Group occupies a position as a specialized player, focusing on complex generics and biosimilars, targeting higher-margin therapeutic segments that require advanced development and production expertise and significant capital investment.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Viatris |
| Sandoz Group |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Aurobindo Pharma |
| Cipla |
| Lupin |
| Fresenius Kabi |
| Others |
Cost & Logistics Intelligence
Group Purchasing Organizations and Pharmacy Benefit Managers significantly influence generic drug pricing. These concentrated buyers enforce tender-based procurement, driving aggressive price competition for high-volume products.
Pricing Analysis
Reliable, just-in-time delivery for essential injectables commands a premium for hospitals, while commodity generics face immediate price erosion. The dominant pricing model for generics combines contract-based long-term offtake with intense commodity spot competition. Price differentiation stems from regulatory quality certifications like US FDA or EU EMA approval, alongside the volume scale a manufacturer can achieve. Pricing pressure intensifies for mature small molecules due to fierce competition, making large institutional buyers highly price-sensitive.
Supply Chain Analysis
Active Pharmaceutical Ingredient (API) supply heavily relies on manufacturers concentrated in India and China, creating significant input dependency for generic drug production. This geographic concentration creates single-source vulnerability and exposes the entire market to risks from geopolitical instability or trade disputes. Key raw material dependencies extend beyond APIs to specialized excipients and sterile packaging components. Distribution runs through large-scale wholesalers, who manage logistics and consolidate purchasing for diverse healthcare providers across regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The generic drugs market presents a supply-constrained landscape, particularly for complex therapeutics. Specialized manufacturing infrastructure for biosimilars represents a significant capacity bottleneck, which props up pricing for these advanced products.
For Market Incumbents: Anticipate continued intense price erosion within the commodity generics segment. Incumbents must diversify portfolios into complex generics and biosimilars to mitigate this threat, leveraging advanced bioprocessing technologies. Strategic partnerships with biopharmaceutical firms can accelerate development and regulatory certification for these higher-value products. Capacity expansion in specialized manufacturing facilities, particularly in India and China, also strengthens market position.
For New Entrants and Emerging Players: Enter via underserved markets in Latin America and Southeast Asia, where healthcare infrastructure is improving. Focus on niche complex generics or alternative dosage forms that require specialized manufacturing but offer higher margins. The most penetrable segment involves regional markets with less established generic competition. A compelling go-to-market angle includes forming partnerships with online pharmacies to leverage digital distribution channels for direct patient access.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers targeting specialized manufacturers with advanced bioprocessing capabilities. This market demonstrates significant growth viability over the next decade, driven by evolving patient needs and cost-containment initiatives. Acquisition targets should include firms proficient in biosimilar development or complex injectable production. A key signal to watch is the schedule of upcoming patent expirations for major biologic drugs in oncology and immunology, indicating future market opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Biosimilar R&D | Accelerates market entry for high-value biologics post-patent expiry, capturing oncology and immunology segments. |
| Implement Continuous Manufacturing | Enhances efficiency and quality consistency for high-volume small molecule generics, reducing production costs. |
| Expand Online Pharmacy Partnerships | Leverages digital distribution to improve patient access and accelerate volume sales for prescription generics. |
| Diversify API Sourcing Geographies | Mitigates supply chain risks from geopolitical instability and reduces reliance on single-country suppliers. |
| Acquire Complex Injectable Facilities | Strengthens position in hospital settings by offering high-potency parenteral formulations for chronic conditions. |
Research Approach
Document review covered US FDA filings, EMA submissions, and customs/trade data, complemented by interviews with industry stakeholders. Primary research involved discussions with regulatory affairs leads, hospital procurement managers, and R&D executives. This approach ensured bottom-up data collection and top-down validation. Secondary sources, including company 10-K filings, further supported the analysis.
Volume and value outputs reflect a triangulated approach, integrating quantitative modeling with qualitative market insights. The framework modeled segmentation by product type, therapy area, end user, and distribution channel. Compound Annual Growth Rates were derived from historical trends and projected market dynamics over the projection horizon. Patent expiration schedules and R&D pipeline data served as crucial industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or geopolitical events. Forecasts reflect underlying assumptions regarding market evolution and API supply stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market