
 Biologic Response Modifiers Market | 2026-2036
Biologic Response Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Biologic Response Modifiers Market Analysis
CE marking under the EU MDR is rotating manufacturer priorities toward post-market surveillance and clinical evidence maintenance. AbbVie Inc. leverages its immunology franchise depth to sustain Humira biosimilar defense strategies. Amgen anchors its position through in-house biologics manufacturing scale across multiple therapeutic areas. Bristol-Myers Squibb competes via checkpoint inhibitor specialization in oncology, differentiating its portfolio from autoimmune-focused rivals.
Biologic response modifiers are protein-based therapeutics derived from living cells, engineered through recombinant DNA technology to modulate immune signaling pathways with precise molecular targeting. These agents function by binding specific cytokines, receptors, or cell surface markers to suppress or activate immune responses for therapeutic effect. Monoclonal antibodies command the largest revenue pool due to established manufacturing infrastructure and broad oncology labeling. Cytokines represent the fastest-expanding category as interleukin inhibitors gain traction across dermatology and gastroenterology indications. Intravenous delivery dominates hospital-based administration, though subcutaneous formulations are capturing share in homecare settings where patient convenience drives formulary decisions.
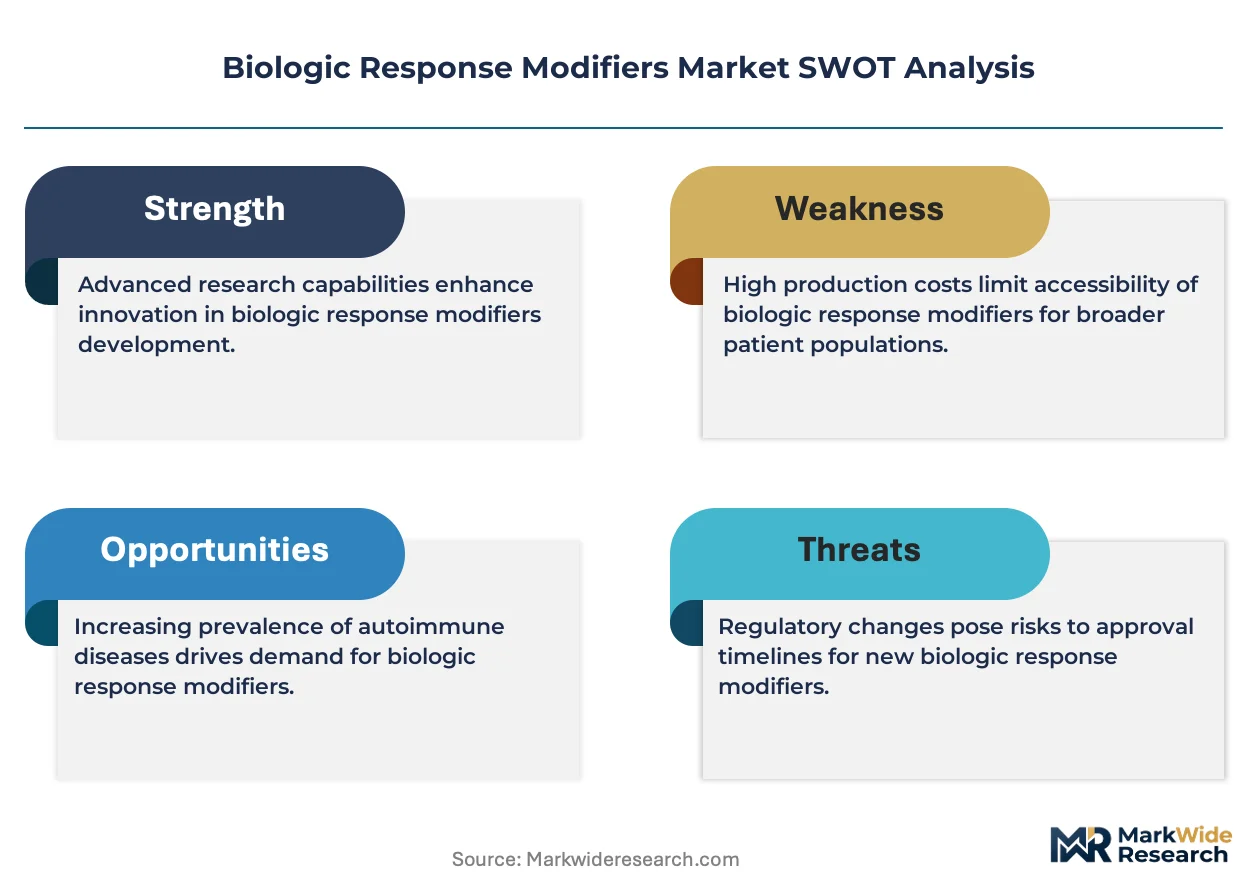
FDA biosimilar guidance and EMA MDR requirements collectively elevate barriers to market entry while compressing pricing power for originator molecules. The EPA and OSHA frameworks governing biologics manufacturing facilities impose environmental and worker-safety compliance costs that concentrate production among capital-intensive operators. Stakeholders must monitor pipeline shifts toward oral biologic formulations and cell therapy convergence that could redefine competitive boundaries without warning.
Market Dynamics
The biologic response modifiers market is being restructured by the convergence of biosimilar pathway maturation and manufacturing scale concentration, where FDA and EMA regulatory refinements have compressed originator pricing power while elevating capital barriers for new entrants.
Growth Catalysts
- FDA Biosimilar Guidance:Streamlined approval pathways accelerate market entry for follow-on biologics, expanding patient access to TNF-alpha inhibitors and interleukin blockers.
- Subcutaneous Formulation Engineering:Advances in protein stabilization enable self-administration outside hospital settings, capturing homecare demand clusters in the United States and Germany.
- Autoimmune Prevalence:Rising diagnosed cases of rheumatoid arthritis and psoriasis across Japan and South Korea drive sustained volume pull for cytokine-targeting therapies.
Market Restraints
- Cell Culture Input Volatility:Serum and media supply disruptions from Chinese contract manufacturers create batch-to-batch yield inconsistency and cost pressure.
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution limitations in India and Brazil restrict market penetration for intravenous biologics requiring strict handling protocols.
- EMA MDR Clinical Evidence Burden:Post-approval surveillance mandates under EU MDR extend compliance timelines and inflate maintenance costs for CE-marked products.
Strategic Opportunities
- Oral Biologic Formulation White Space:Protein engineering platforms enabling gastrointestinal stability could unlock patient adherence advantages over injectable standards.
- Cell Therapy Convergence:CAR-T manufacturing infrastructure repurposing creates shared production networks for next-generation immune modulators.
- Japan PMDA Sakigake Pathway:Expedited review designation for innovative biologics offers first-mover positioning in Asia-Pacific's second-largest market.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Shortage of mammalian cell culture specialists and CMC regulatory scientists constrains capacity expansion timelines.
- Single-Use System Integration:Legacy stainless-steel facilities face retrofit complexity when adopting disposable bioreactor technology for multi-product flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologic Response Modifiers Market |
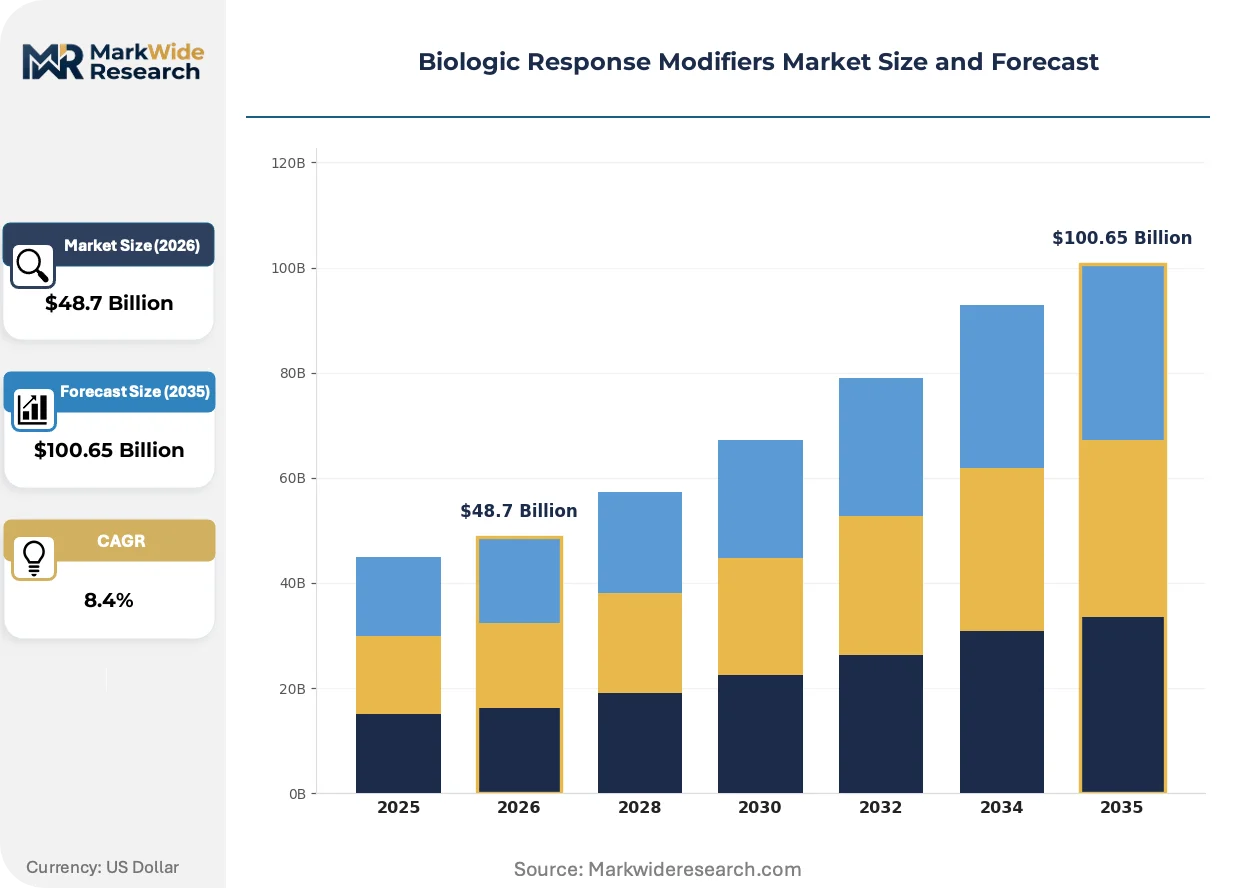
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Interferons, Cytokines, Vaccines Application: Autoimmune Disorders, Cancer Treatment, Infection Control, HIV Therapy End User: Hospitals, Research Laboratories, Specialty Clinics, Homecare Settings Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | AbbVie Inc., Amgen, Bristol-Myers Squibb, Novartis AG, Roche Holding AG, Merck & Co., Inc., Biogen, Janssen Inc., Swedish Orphan Biovitrum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologic Response Modifiers Market Emerging Trajectories
Bispecific antibody architectures and continuous bioprocessing are redefining manufacturing economics while regulatory convergence around real-world evidence is compressing development-to-commercialization cycles.
Continuous manufacturing technology is fragmenting traditional batch-based production paradigms. Perfusion bioreactor systems from Sartorius and Thermo Fisher enable higher cell densities with smaller facility footprints. Contract development organizations in Switzerland and Singapore are adopting these platforms to serve multiple originator clients simultaneously, eroding the scale advantage of legacy blockbuster-dedicated plants.
EMA's evolving stance on real-world evidence integration into label extensions is altering post-market study design. Sponsors now incorporate electronic health record data from Germany's disease registries to support indication expansions. This shift most directly impacts oncology monoclonal antibodies seeking rapid broadening beyond initial approvals.
Hospital buying consortiums in the United States are consolidating formulary decision authority, displacing individual physician preference as the primary demand determinant. Integrated delivery networks now negotiate multi-year biologic supply agreements with rebate structures tied to patient outcome metrics. This concentration is most visible in Texas and Florida health systems where CVS Health and OptumRx manage specialty pharmacy distribution.
Biologic Response Modifiers Market Segmentation
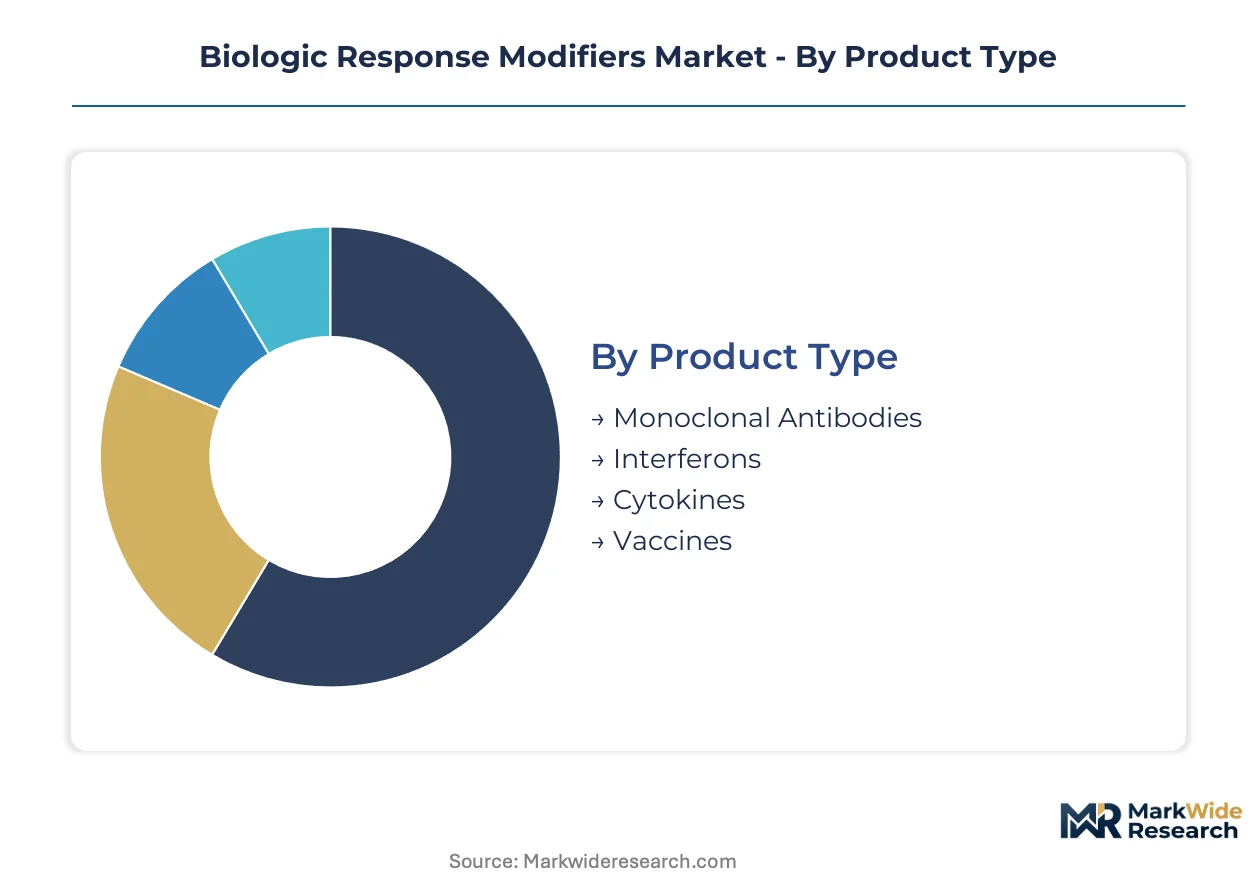
Biologic response modifiers fragment across therapeutic mechanism, clinical setting, and administration pathway. Each dimension carries distinct regulatory, reimbursement, and manufacturing implications that shape competitive positioning.
Product Type:
Monoclonal antibodies concentrate production in the United States and Switzerland for domestic consumption and export to Japan. Cytokines and interferons increasingly originate from South Korean and Singaporean contract manufacturers serving European and Asian markets.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific cell surface antigens or soluble cytokines with high binding affinity. Demand clusters in oncology infusion centers across Germany and the United States, driven by checkpoint inhibitor expansion into adjuvant settings. Manufacturing scale and biosimilar defense investments by originators elevate capital barriers for new entrants.
- Cytokines:Soluble signaling proteins including interleukins and colony-stimulating factors that modulate immune cell differentiation and activation. South Korean dermatology and gastroenterology practices are driving volume for IL-17 and IL-23 inhibitors, with reimbursement pathways under Japan's MHLW accelerating patient access.
- Interferons:Glycoprotein cytokines with antiviral and immunomodulatory properties, now largely superseded by direct-acting antivirals in hepatitis C but retained in multiple sclerosis protocols.
- Vaccines:Prophylactic and therapeutic immunization products leveraging recombinant protein subunits or viral vectors, with production concentrated in Belgium and India for tropical disease indications.
Monoclonal antibodies command the established base. The steepest expansion runs through cytokines.
Application:
Cost tier stratification separates hospital-administered cancer biologics from self-injectable autoimmune therapies reimbursed through pharmacy benefit managers.
- Autoimmune Disorders:TNF-alpha inhibitors and interleukin blockers for rheumatoid arthritis, psoriasis, and inflammatory bowel disease. German rheumatology practices and Japanese dermatology clinics are the primary demand anchors, with biosimilar penetration compressing net pricing while expanding treated populations.
- Cancer Treatment:Checkpoint inhibitors, antibody-drug conjugates, and bispecific T-cell engagers. United States academic medical centers and French comprehensive cancer centers concentrate procurement authority through integrated delivery network contracts tied to outcome metrics.
- Infection Control:Monoclonal antibodies targeting resistant bacterial and fungal pathogens, with procurement concentrated in tertiary hospitals in Italy and Spain facing antimicrobial stewardship mandates.
- HIV Therapy:Long-acting injectable integrase inhibitors and broadly neutralizing antibodies, with Brazil and South Africa representing volume markets through pooled procurement mechanisms.
Autoimmune applications generate the deepest revenue pool. Oncology represents the highest-margin expansion corridor.
End User:
Patient volume concentrates in hospital outpatient departments, though reimbursement shifts are accelerating specialty clinic and homecare migration for subcutaneous formulations.
- Hospitals:Inpatient and infusion center administration of intravenous biologics requiring monitoring for infusion reactions. Texas and Florida health systems negotiate multi-year supply agreements with CVS Health and OptumRx managing specialty pharmacy distribution.
- Specialty Clinics:Rheumatology, dermatology, and gastroenterology practices administering subcutaneous injections. German ambulatory care centers and Japanese clinic chains are capturing volume as reimbursement migrates from facility to professional fee schedules.
- Research Laboratories:Preclinical and clinical trial supply for investigator-sponsored studies, with demand concentrated in Boston-Cambridge and Basel-Rotterdam corridor institutions.
- Homecare Settings:Self-administration of prefilled syringes and auto-injectors, expanding fastest in the Netherlands and United Kingdom where nursing support infrastructure enables remote monitoring.
Hospitals retain the volume anchor position. Homecare settings are climbing the fastest as formulation engineering enables patient-controlled administration.
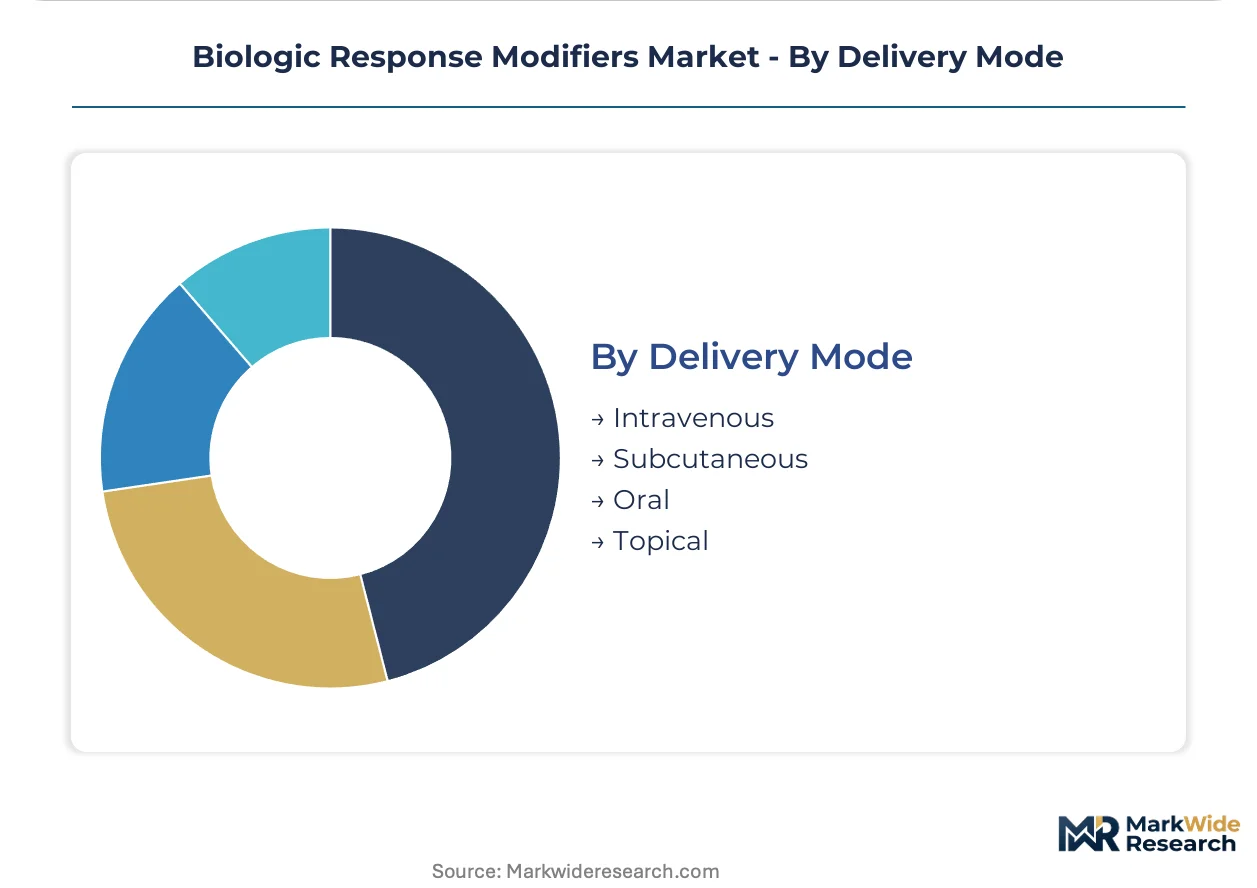
Delivery Mode:
Supply chain configuration separates cold-chain-dependent intravenous products from room-temperature-stable subcutaneous and oral candidates.
- Intravenous:Hospital-based infusion requiring temperature-controlled distribution and pharmacy compounding. Brazilian and Indian market penetration faces infrastructure constraints for strict handling protocols.
- Subcutaneous:Prefilled syringes and pen devices enabling outpatient and home administration. Protein stabilization advances from Sartorius and Thermo Fisher platforms are extending shelf life and reducing cold chain dependency.
- Oral:Experimental biologic formulations targeting gastrointestinal stability through encapsulation or chemical modification, with no approved products currently but multiple candidates in Swiss and United States development pipelines.
- Topical:Localized delivery for dermatologic conditions, with cytokine inhibitors in cream and foam formulations gaining formulary placement in French and Italian pharmacy networks.
Intravenous delivery holds the installed base. Subcutaneous formulations are gaining share fastest through patient convenience and total cost-of-care advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biosimilar pathway refinements and EMA MDR compliance mandates are redistributing manufacturing investment across concentrated production clusters. Germany, the United States, Japan, Switzerland, and South Korea anchor distinct competitive positions shaped by regulatory specialization and therapeutic demand density.
United States
Integrated delivery networks in Texas and Florida consolidate formulary authority through CVS Health and OptumRx specialty pharmacy contracts. FDA streamlined approval pathways accelerate TNF-alpha inhibitor biosimilar entry, compressing originator pricing while expanding treated populations. Massachusetts and California biotech corridors concentrate checkpoint inhibitor development infrastructure.
Germany
Rheumatology practices and comprehensive cancer centers drive volume for monoclonal antibody infusions under statutory health insurance reimbursement. EMA MDR post-approval surveillance mandates extend compliance timelines for CE-marked products, elevating maintenance costs. The Rhine-Main and Munich clusters host contract manufacturing organizations serving European distribution networks.
Japan
Dermatology clinics and gastroenterology practices generate sustained demand for IL-17 and IL-23 inhibitors. PMDA Sakigake expedited review designation offers first-mover positioning for innovative biologics in Asia-Pacific's second-largest market. The Kanto and Kansai regions concentrate hospital outpatient departments administering intravenous formulations.
Switzerland
Basel-Rotterdam corridor institutions anchor preclinical and clinical trial supply chains for investigator-sponsored studies. Swissmedic regulatory alignment with EMA procedures enables synchronized EU market entry strategies. Continuous bioprocessing platform adoption by contract development organizations erodes scale advantages of legacy blockbuster-dedicated plants.
South Korea
Contract manufacturers in Seoul and Busan supply cytokine and interferon production for European and Asian markets. MFDS biosimilar approval frameworks mirror FDA pathways, accelerating follow-on biologic commercialization. Domestic dermatology and gastroenterology practices drive regional volume for interleukin inhibitors.
Biologic Response Modifiers Market Vendor Landscape
Listed leaders compete with private specialists across immunology franchise depth and manufacturing scale dimensions. The market structure concentrates revenue among vertically integrated originators defending blockbuster positions against biosimilar entrants. Three archetypes dominate: immunology franchise incumbents with biosimilar defense capabilities, oncology checkpoint specialists with infusion center relationships, and contract manufacturers with multi-product flexibility. Competitive moves center on M&A for pipeline acquisition and capacity expansion for bioprocess scale.
Within the immunology franchise tier, AbbVie Inc. and Amgen exemplify originator archetypes with established manufacturing infrastructure and therapeutic area concentration. Bristol-Myers Squibb occupies a distinct position through oncology specialization, differentiating portfolio composition from autoimmune-focused rivals. These three entities represent the competitive spectrum from small-molecule legacy defense to biologic manufacturing scale to checkpoint inhibitor development depth.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen |
| Bristol-Myers Squibb |
| Novartis AG |
| Roche Holding AG |
| Merck & Co., Inc. |
| Biogen |
| Janssen Inc. |
| Swedish Orphan Biovitrum |
| Others |
Supply Flow & Price Mechanics
Perfusion bioreactor scale economies at Sartorius and Thermo Fisher platforms compress unit production costs while elevating capital barriers for batch-based competitors, concentrating supply among operators capable of continuous manufacturing and establishing price floors tied to facility amortization schedules rather than variable input costs.
Pricing Analysis
Certification level (FDA-grade versus EMA CE-marked versus MFDS-registered) creates the primary spread between originator monoclonal antibodies and follow-on biologics. Three-tier pricing structure across premium originator, authorized biosimilar, and economy non-comparable biologic levels reflects reimbursement pathway differentiation under US Medicare Part B, German GKV, and Japan MHLW. Cost compression in the economy tier is intensifying because South Korean contract manufacturers are capturing European volume with 15-20% undercuts on reference pricing. Hospital buying consortiums in Texas and Florida demonstrate highest price sensitivity through outcome-tied rebate negotiations, while Japanese dermatology clinics show lowest sensitivity due to Sakigake premium positioning.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore biologics terminals elevates inbound logistics costs for serum and cell culture media originating from Chinese contract manufacturers. Supply concentrates in the United States, Switzerland, and South Korea for active pharmaceutical ingredient production, with fill-finish capacity clustering in Germany and Japan. Raw material dependencies rest on fetal bovine serum from Australia and New Zealand, single-use bioreactor bags from US and German suppliers, and recombinant protein expression vectors from Boston-Cambridge corridor institutions. Single-source vulnerability pervades the serum supply base following Australian drought conditions. Distribution runs through cold-chain logistics networks managed by CVS Health and OptumRx specialty pharmacy operations for US hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biologic response modifiers market is recovering from biosimilar-induced pricing cyclicality as formulation innovation and indication expansion create new revenue baselines. Autoimmune prevalence trajectories in Japan and South Korea provide volume anchors for this recovery phase.
For Market Incumbents: Consolidate manufacturing scale through perfusion bioreactor retrofitting at legacy stainless-steel facilities to match Sartorius platform economics. Lock in multi-year serum supply agreements with Australian and New Zealand collectors before drought-driven scarcity intensifies. Channel control through integrated delivery network sole-source contracts in Texas and Florida defends against biosimilar entrants capturing hospital formulary slots.
For New Entrants and Emerging Players: Anchor in oral biologic formulation development where gastrointestinal stability engineering remains unsolved and no approved products currently compete. Target Japanese dermatology clinics through PMDA Sakigake pathway submissions, exploiting first-mover positioning in IL-17 and IL-23 inhibitor adjacencies. Go-to-market through Swiss contract development organizations enables shared manufacturing infrastructure without captive facility investment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cytokine-focused specialists with subcutaneous formulation portfolios and Japanese reimbursement access. Five-to-ten year viability favors operators with backward integration into cell culture media production or captive bioreactor technology. Acquisition target archetype: mid-scale CDMOs with continuous processing platforms and EMA MDR compliance infrastructure. Signal to watch is FDA biosimilar interchangeability designation frequency, which would accelerate substitution rates and compress originator valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Perfusion bioreactor adoption at Sartorius platforms reduces facility footprint while doubling cell density output. |
| Regulatory Approval Pathway | FDA biosimilar interchangeability designation unlocks automatic substitution at pharmacy level without prescriber intervention. |
| Pipeline Diversification | IL-23 inhibitor expansion into psoriatic arthritis captures rheumatology volume beyond dermatology anchoring. |
| Licensing Agreement | Japanese pharma partnerships through PMDA Sakigake accelerate Asia-Pacific market entry for cytokine platforms. |
| Clinical Trial Advancement | Real-world evidence integration from German disease registries supports EMA label expansion without new pivotal studies. |
Methodological Framework
Desk research of FDA biosimilar guidance documents, EMA MDR technical specifications, and ClinicalTrials.gov investigator protocols preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, SEC 10-K biologics revenue disclosures, and CMS Medicare Part B spending data. Bottom-up patient volume modeling by indication and top-down manufacturer revenue triangulation were cross-checked for consistency.
Variance decomposition across therapeutic mechanism, administration route, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from patient population epidemiology, treated prevalence assumptions, and pricing trajectory scenarios. Forecast inputs incorporated biosimilar penetration curves by molecule class and Japanese MHLW reimbursement revision schedules.
Decision-makers should treat outputs as directional under base assumptions of stable autoimmune diagnosis rates and continued FDA-EMA regulatory convergence; material deviation would warrant model refresh. Specific risks include cell culture input supply disruptions, abrupt EMA MDR enforcement tightening, and oral biologic formulation breakthroughs disrupting injectable standards. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market