
 Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market | 2026-2036
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market Analytics
Project finance for late-stage clinical trials is fragmenting competitive access to pivotal cardiovascular outcomes studies. AstraZeneca leverages its EMPEROR program data to sustain formulary preference across integrated health networks. Boehringer Ingelheim International GmbH anchors the European market through established payer contracts and localized manufacturing. Johnson & Johnson Services, Inc. competes on renal protection positioning with differentiated physician education.
Sodium-dependent glucose co-transporter 2 proteins reside in renal proximal tubules and mediate glucose reabsorption via active transport against sodium gradients; pharmacologic inhibition promotes glucosuria and osmotic diuresis at plasma glucose thresholds below renal transport capacity. Empagliflozin and dapagliflozin dominate the product type landscape, with empagliflozin holding the broadest FDA-approved label spanning diabetes, heart failure with reduced ejection fraction, and chronic kidney disease. Cardiovascular health application represents the fastest-expanding demand pool as prescribing shifts from glycemic control to organ protection, while diabetes management remains the volume base with thinning margins due to generic entry timelines.
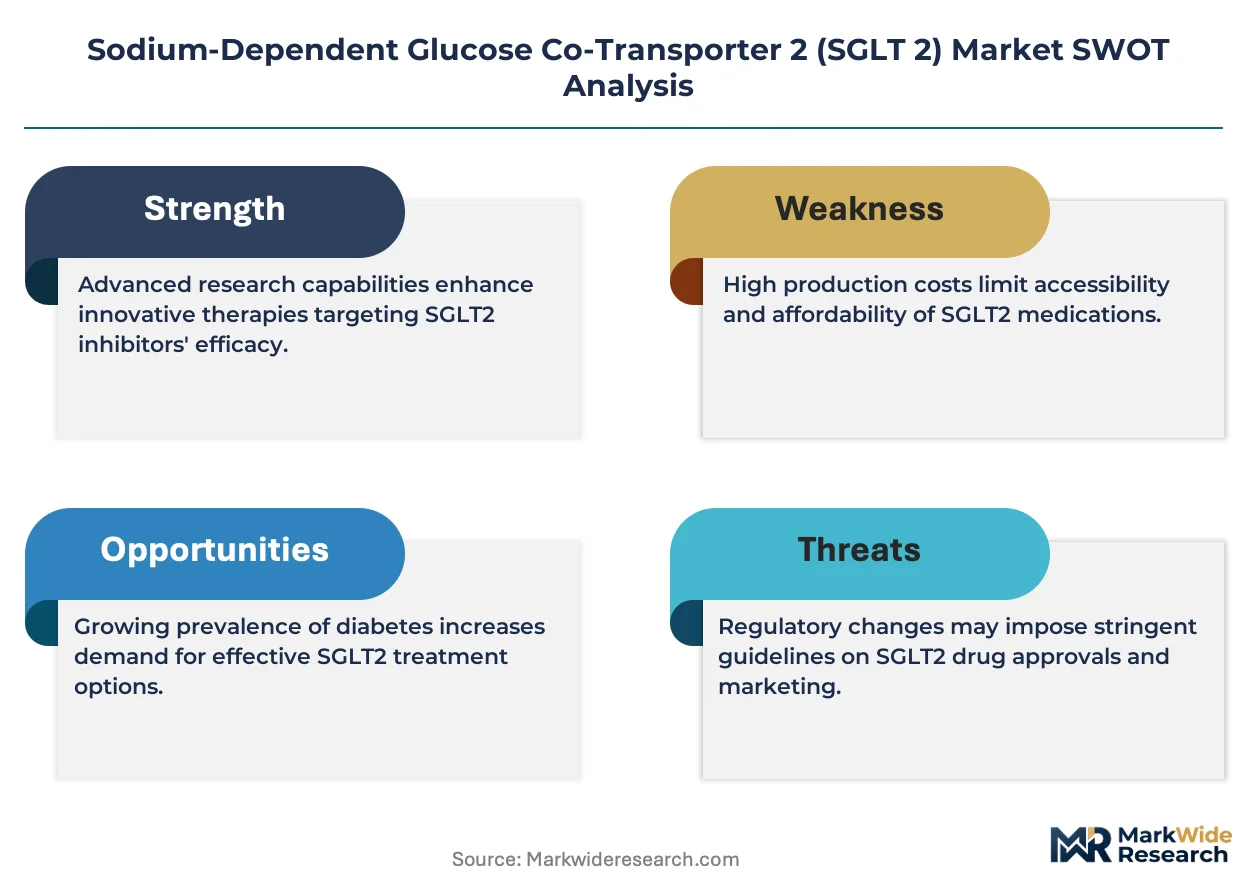
FDA, EMA, and national health technology assessment bodies shape market access through indication-specific value frameworks and incremental cost-effectiveness thresholds. The FDA's breakthrough therapy designations for heart failure indications accelerated trial timelines, while EMA's parallel scientific advice process harmonizes evidence requirements across member states. Stakeholders must monitor evolving cardiovascular outcomes data requirements from HTA agencies and prepare for indication-specific pricing negotiations that separate premium positioning for heart failure and renal protection from commoditized diabetes management.
Market Dynamics
Hospital formulary adoption for cardiovascular risk reduction is pulling prescribing decisions away from endocrinology into cardiology and nephrology, fragmenting the traditional prescriber base and forcing manufacturers to rebuild physician education infrastructure around organ protection rather than glycemic control.
Growth Catalysts
- Heart Failure Label Expansions:FDA breakthrough therapy designations for heart failure indications accelerated pivotal trial timelines and opened Medicare reimbursement pathways that previously required lengthy coverage determination processes.
- Chronic Kidney Disease Indications:EMA parallel scientific advice harmonized evidence requirements across member states, reducing regulatory friction for renal protection claims and enabling faster national pricing negotiations.
- Integrated Delivery Networks:United States-based IDNs are consolidating formularies around cardiovascular outcomes data, creating volume concentration that rewards manufacturers with robust EMPEROR-style evidence packages.
Market Restraints
- Generic Entry Timelines:Patent cliffs for dapagliflozin and empagliflozin in diabetes management are compressing margins in the volume base indication ahead of heart failure and renal protection exclusivity periods.
- Reimbursement Fragmentation:Medicare Part D coverage decisions vary across regional carriers for heart failure versus diabetes indications, creating prescribing friction that slows prescriber base expansion.
- Sodium-Glucose Transport Biology Limits:SGLT2 inhibition efficacy plateaus at estimated glomerular filtration rates below 30 mL/min/1.73m², restricting addressable population in advanced chronic kidney disease.
Strategic Opportunities
- Underpenetrated Asian Markets:Japan's PMDA accelerated approval pathways for cardiovascular outcomes data create first-mover positioning for manufacturers with existing EMPEROR or DECLARE trial datasets.
- Fixed-Dose Combinations:SGLT2 inhibitor plus GLP-1 receptor agonist combinations address residual cardiovascular risk in high-risk diabetes populations, opening premium pricing corridors beyond monotherapy commoditization.
- Digital Therapeutic Integration:Remote patient monitoring platforms for heart failure decompensation signals enable value-based contracting with Medicare Advantage plans that capture shared savings from reduced hospitalizations.
Industry Challenges
- Cardiovascular Outcomes Trial Complexity:Recruitment for heart failure with preserved ejection fraction studies requires specialized sites with echocardiography core lab capabilities, stretching clinical operations infrastructure.
- Cross-Functional Medical Education:Field medical teams must simultaneously engage endocrinologists, cardiologists, and nephrologists with indication-specific messaging, fragmentating resource allocation and complicating key opinion leader mapping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market |
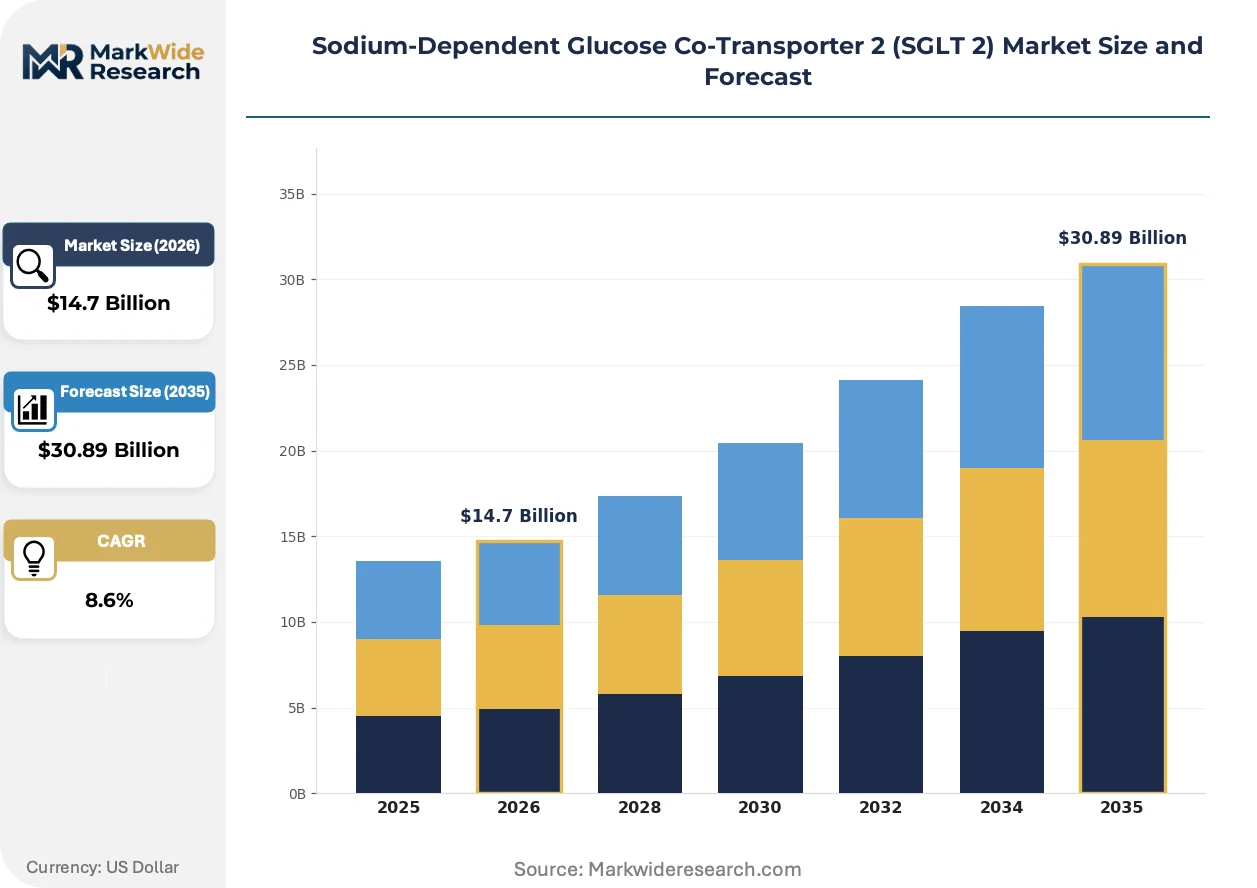
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dapagliflozin, Canagliflozin, Empagliflozin, Ertugliflozin Application: Diabetes Management, Cardiovascular Health, Weight Loss, Renal Protection End User: Hospitals, Clinics, Home Care, Telehealth Services Delivery Mode: Oral Tablets, Injectable Solutions, Pre-filled Pens, Others |
| Companies Covered | Johnson & Johnson Services, Inc., Lexicon Pharmaceuticals, Inc., AstraZeneca, Bristol-Myers Squibb Company, TheracosBio, LLC, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Glenmark Pharmaceuticals Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market Evolving Landscape
Prescribing logic is migrating from glucose-centric algorithms to organ-protection frameworks, compressing the traditional diabetes drug lifecycle and rewarding manufacturers who can generate cardiovascular and renal outcomes data ahead of competitors.
Biomarker-guided patient selection is rendering obsolete the empiric prescribing model that treated all type 2 diabetes patients as candidates for SGLT2 inhibition regardless of baseline cardiovascular risk. Cardiology practices in the United States are adopting NT-proBNP and UACR thresholds to prioritize therapy initiation, concentrating volume in high-risk cohorts where outcomes data is strongest. This risk-stratification approach is compressing commercialization timelines for manufacturers without broad-label cardiovascular outcomes data.
The FDA's indication-specific value framework for heart failure therapies is forcing manufacturers to separate evidence packages by clinical endpoint rather than submitting pooled cardiovascular outcomes data across heterogeneous populations. This regulatory granularity is extending pre-submission meeting timelines but reducing complete response letter risk for sponsors who invest in dedicated heart failure with reduced ejection fraction and preserved ejection fraction trials. European HTA bodies are following this segmentation logic, with NICE and IQWiG now requiring indication-specific cost-effectiveness analyses that distinguish diabetes management from heart failure prevention.
Hospital pharmacy and therapeutics committees are consolidating formularies around single SGLT2 inhibitors with broadest-label cardiovascular protection, displacing the previous multi-product contracting model that accommodated endocrinology preference diversity. This concentration dynamic favors manufacturers with earliest heart failure approvals and most comprehensive renal outcomes data. The shift is most visible in United States-based integrated delivery networks where pharmacy benefit managers are negotiating indication-based rebates that penalize non-preferred products across all therapeutic uses.
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market Segmentation
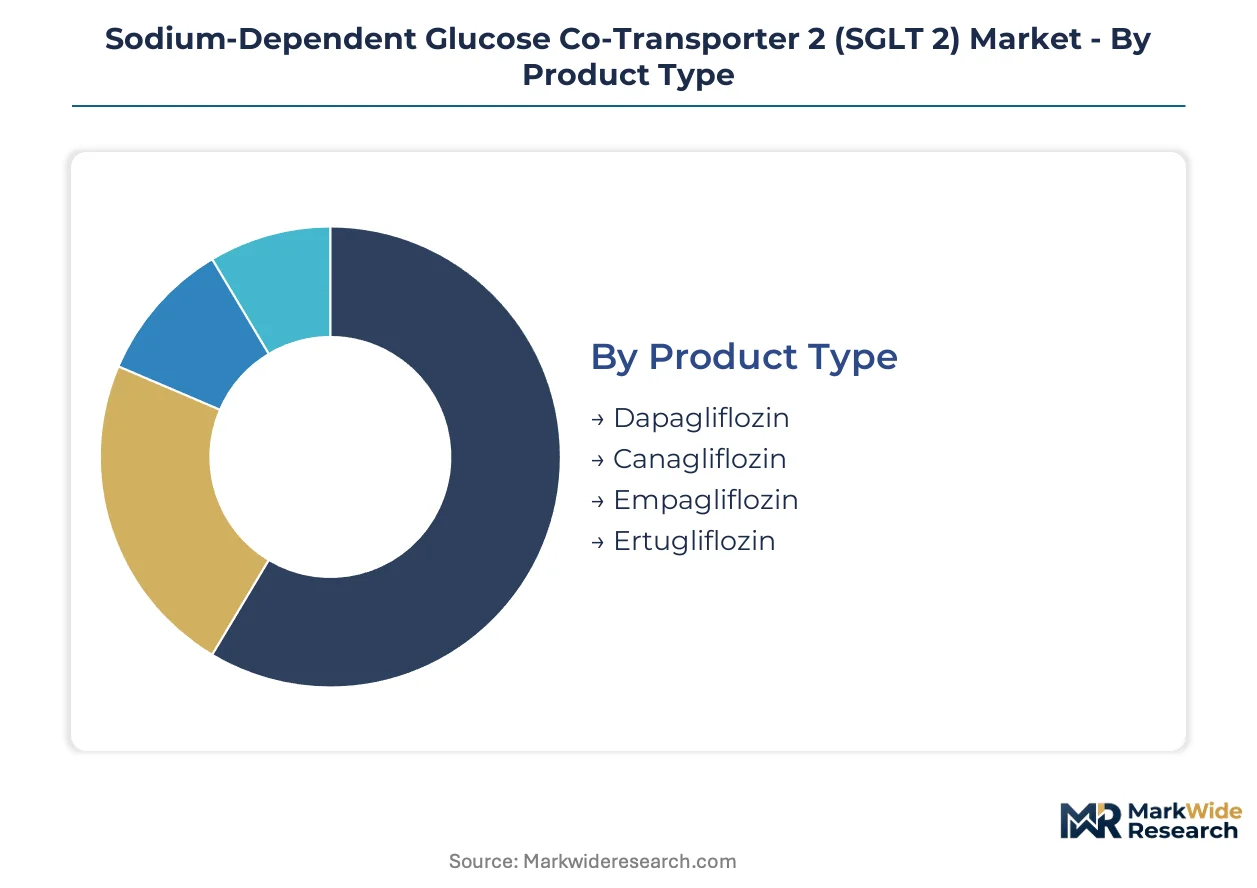
SGLT2 inhibitor commercialization requires precise segment targeting as prescribing shifts from diabetes-centric to organ-protection frameworks. Manufacturers must align formulation development, clinical trial design, and field medical deployment with indication-specific demand pools and delivery preferences.
Product Type:
After-sales service intensity varies sharply across molecules, with cardiovascular outcomes data packages and renal protection dossiers demanding specialized medical affairs support and formulary defense resources.
- Empagliflozin:Broadest FDA-approved label spanning diabetes, heart failure with reduced ejection fraction, and chronic kidney disease. United States integrated delivery networks concentrate volume here due to EMPEROR program evidence depth and Medicare Advantage contracting advantages.
- Dapagliflozin:DECLARE-TIMI 58 cardiovascular outcomes data supports heart failure with preserved ejection fraction positioning. European payer contracts anchor market presence through EMA harmonized labeling and localized manufacturing infrastructure.
- Canagliflozin:Established renal protection claims with dedicated nephrology education requirements.
- Ertugliflozin:Narrower label confines prescribing to diabetes management with thinner margin profiles.
Empagliflozin holds the largest share; momentum sits with dapagliflozin as heart failure with preserved ejection fraction approvals expand prescriber access.
Application:
Cost tier stratification separates premium-priced organ protection indications from commoditized diabetes management as generic entry timelines approach.
- Cardiovascular Health:Fastest-expanding demand pool driven by FDA breakthrough therapy designations and Medicare reimbursement pathway acceleration. Hospital pharmacy and therapeutics committees consolidate formularies around agents with dedicated heart failure trials.
- Renal Protection:EMA parallel scientific advice harmonized evidence requirements enable faster national pricing negotiations. Chronic kidney disease indications command premium positioning separate from diabetes management.
- Diabetes Management:Volume base with compressing margins as patent cliffs approach for leading molecules.
- Weight Loss:Emerging off-label utilization with limited formal indication support and reimbursement uncertainty.
Cardiovascular health commands premium pricing; renal protection exhibits steepest expansion trajectory as HTA bodies adopt indication-specific value frameworks.
End User:
Customer type fragmentation demands rebuilt physician education infrastructure as prescribing decisions migrate from endocrinology to cardiology and nephrology.
- Hospitals:Formulary consolidation around single preferred agents with broadest-label cardiovascular protection. Pharmacy benefit managers negotiate indication-based rebates penalizing non-preferred products.
- Clinics:Outpatient cardiology practices adopt NT-proBNP and UACR biomarker thresholds to prioritize therapy initiation in high-risk cohorts.
- Home Care:Oral tablet formulations enable patient self-administration with remote monitoring integration for heart failure decompensation signals.
- Telehealth Services:Digital therapeutic platforms facilitate value-based contracting with Medicare Advantage plans capturing shared savings.
Hospitals dominate volume concentration; telehealth services are gaining share fastest through remote patient monitoring and outcomes-based reimbursement models.
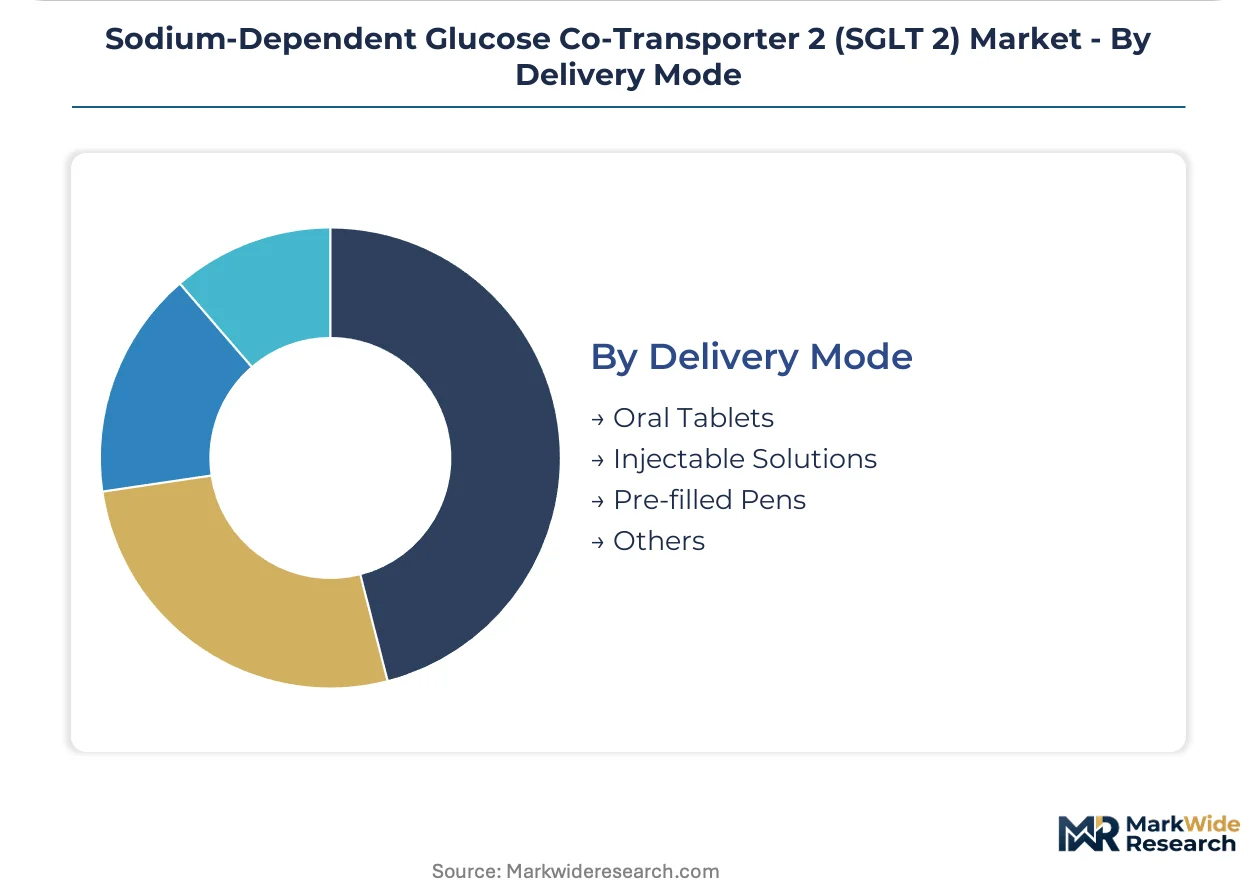
Delivery Mode:
Supply concentration favors oral solid dosage forms with established manufacturing scale and distribution efficiency.
- Oral Tablets:Dominant format with immediate-release and extended-release variants supporting once-daily dosing compliance.
- Pre-filled Pens:Emerging fixed-dose combination formats with GLP-1 receptor agonists addressing residual cardiovascular risk.
- Injectable Solutions:Limited commercial presence due to SGLT2 inhibitor pharmacokinetics favoring oral bioavailability.
- Others:Novel formulations in development including orodispersible tablets for dysphagia populations.
Oral tablets hold the largest share; pre-filled pens are climbing the fastest as combination therapy development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital pharmacy and therapeutics committees concentrate purchasing power in integrated delivery networks across five countries where cardiovascular outcomes data determines formulary access. Medicare Advantage plans in the United States negotiate indication-based rebates that cascade through regional carrier decisions. European HTA bodies apply parallel scientific advice to harmonize renal protection evidence requirements.
United States
Medicare Part D regional carriers and integrated delivery networks drive volume concentration through cardiovascular risk reduction contracts. The FDA's breakthrough therapy designation for heart failure indications accelerated Medicare reimbursement pathways. Hospital systems in the Northeast Corridor consolidate formularies around agents with EMPEROR-program evidence depth.
Germany
IQWiG and G-BA cost-effectiveness thresholds separate premium positioning for heart failure from commoditized diabetes management. EMA parallel scientific advice harmonizes renal protection claims across member states. The Rhine-Ruhr industrial cluster anchors Boehringer Ingelheim's European manufacturing and payer contracting infrastructure.
Japan
PMDA accelerated approval pathways for cardiovascular outcomes data create first-mover positioning for manufacturers with existing trial datasets. METI reimbursement pricing reforms favor organ-protection indications over glycemic control. Tokyo-based cardiology practices adopt NT-proBNP biomarker thresholds to prioritize high-risk patient initiation.
United Kingdom
NICE indication-specific value frameworks distinguish diabetes management from heart failure prevention in pricing negotiations. The NHS England specialized commissioning process concentrates hospital formulary decisions around single preferred agents. The Greater London integrated care systems pilot value-based contracting for heart failure hospitalization reduction.
India
CDSCO regulatory pathways for fixed-dose combinations with GLP-1 receptor agonists address residual cardiovascular risk in high-risk diabetes populations. The PLI scheme for active pharmaceutical ingredients reduces import dependency for SGLT2 inhibitor manufacturing. Maharashtra's pharmaceutical corridor concentrates generic formulation capacity for export to Southeast Asian markets.
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented prescriber bases that span endocrinology, cardiology, and nephrology. Hospital formulary consolidation rewards manufacturers with broadest-label cardiovascular protection data and integrated health network contracting scale. Three archetypes dominate: large-cap pharmaceutical conglomerates with cross-therapeutic cardiovascular portfolios, mid-cap specialists with dedicated renal outcomes capabilities, and regional generic manufacturers with cost-positioned diabetes formulations. Competitive moves center on M&A to acquire cardiovascular outcomes trial datasets and strategic partnerships with integrated delivery networks for indication-based rebate contracting.
Among large-cap pharmaceutical conglomerates, AstraZeneca and Johnson & Johnson Services, Inc. exemplify the channel-control archetype through integrated health network penetration and Medicare Advantage contracting scale. Boehringer Ingelheim International GmbH occupies a differentiated position within the European specialist tier, leveraging localized manufacturing and established payer relationships. These three entities represent the competitive structure where evidence depth and formulary access determine market position rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Lexicon Pharmaceuticals, Inc. |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| TheracosBio, LLC |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Glenmark Pharmaceuticals Ltd. |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Maharashtra's pharmaceutical corridor concentrates active pharmaceutical ingredient capacity for SGLT2 inhibitors, and this supply concentration translates directly into pricing leverage for integrated manufacturers with captive synthesis capabilities. Generic entry timelines for empagliflozin and dapagliflozin are compressing margins in diabetes management faster than heart failure and renal protection indications can offset.
Pricing Analysis
Indication-specific FDA labeling creates the primary spread between premium cardiovascular protection tiers and commoditized diabetes management. Three-tier pricing structure across organ-protection premium, standard diabetes, and economy generic levels dominates contracting. Price erosion runs through the diabetes base as patent cliffs approach, while Medicare Advantage plans show lowest price sensitivity for heart failure hospitalization reduction claims.
Supply Chain Analysis
Tariff exposure between India and China dominates pharmaceutical intermediate sourcing risk for Western manufacturers. Active pharmaceutical ingredient production concentrates in India, China, and Germany, with formulation finishing anchored in the United States and European Union. Supply chains draw from gliflozin precursor chemicals, sodium co-transporter assay reagents, and cardiovascular outcomes trial biomarker kits. Distribution runs through hospital pharmacy and therapeutics committees and integrated delivery network procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SGLT2 inhibitor market rewards manufacturers who attach medical affairs and formulary defense services to molecule supply, as cardiovascular outcomes data packages and renal protection dossiers expand faster than pure product revenue.
For Market Incumbents: Build cardiovascular outcomes data moats through dedicated heart failure with preserved ejection fraction trial investments before generic entry erodes diabetes margins. Consolidate manufacturing scale in Maharashtra and the Rhine-Ruhr corridor to defend cost position against emerging API suppliers. Anchor payer contracts through Medicare Advantage heart failure hospitalization reduction guarantees. For New Entrants and Emerging Players: Fixed-dose combination development with GLP-1 receptor agonists represents the most penetrable entry point for bypassing entrenched monotherapy formularies. Target Japan's PMDA accelerated approval pathway for cardiovascular outcomes data to establish first-mover positioning ahead of European and United States filings. Pursue digital therapeutic integration partnerships with remote patient monitoring platforms for value-based contracting credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cardiovascular outcomes trial dataset acquisitions over late-stage molecule licensing. Long-term viability rests on indication expansion breadth rather than diabetes volume scale. Watch for FDA breakthrough therapy designation signals in heart failure with preserved ejection fraction as inflection indicators for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcomes Trial Advancement | EMPEROR-style evidence packages secure Medicare Advantage contracting advantages across United States integrated delivery networks. |
| Regulatory Approval Pathway | PMDA accelerated approval in Japan creates first-mover positioning for manufacturers with existing DECLARE or EMPEROR datasets. |
| Fixed-Dose Combination Development | SGLT2 inhibitor plus GLP-1 receptor agonist combinations open premium pricing corridors beyond monotherapy commoditization. |
| Digital Therapeutic Integration | Remote patient monitoring platforms enable value-based contracting with Medicare Advantage plans capturing shared savings. |
| Manufacturing Scale-Up | Maharashtra API capacity expansion under India's PLI scheme reduces import dependency for Western formulation sites. |
Research Methodology
Cross-validation between primary interviews with formulary directors, cardiology key opinion leaders, nephrology medical affairs specialists, and payer access strategists anchors the qualitative findings. Secondary sources include FDA approval documents, EMA parallel scientific advice records, ClinicalTrials.gov cardiovascular outcomes study registries, and Medicare Part D coverage determination databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation calibrate market size estimates.
Calibration against historical cardiovascular outcomes trial enrollment timelines and regulatory approval lags refines the analytical framework across the projection horizon. Segmentation dimensions include product molecule, indication tier, prescriber specialty, and integrated delivery network concentration. CAGRs derive from indication-specific volume trajectories and pricing elasticity assumptions tied to generic entry timelines and Medicare reimbursement pathway expansion.
Macroeconomic conditions sit as an overlay; deviation in Medicare Advantage penetration rates, hospital system consolidation velocity, or pharmaceutical trade policy would shift the trajectory. Forecasts reflect documented assumptions about cardiovascular outcomes data requirements and HTA body value framework evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market