
 US Generator Sales Market | 2026-2036
US Generator Sales Market Size, Share, and Industry Trends Forecast 2026-2036
US Generator Sales Market Analysis
Hybridization of generator sets with battery storage is fragmenting traditional product architectures across the US power equipment sector. Cummins Inc. anchors its position through in-house production of integrated power systems for data center clients. Generac Holdings Inc. dominates residential standby installations through installer channel control in hurricane-exposed states. Caterpillar Inc. competes in the high-capacity industrial tier where mining and oilfield operators demand 500 kW-plus continuous-duty units.
US generator sales encompass the commercial distribution of engine-driven electromechanical devices that convert chemical fuel energy into alternating-current electricity, with standby units typically incorporating automatic transfer switches rated for sub-20-second load acceptance. The primary purpose spans emergency backup for critical infrastructure, prime power for off-grid operations, and peak shaving for demand-charge reduction at commercial facilities. Diesel-gasoline fuel type splits are shifting as natural gas standby units capture share in urban commercial buildings where pipeline access eliminates on-site fuel storage burdens. Portable product types face margin compression from lithium-ion inverter alternatives, while solar-hybrid configurations represent the fastest-growing capacity class among federal and state government procurement channels.
EPA Tier 4 Final emissions standards govern non-road diesel engines above 25 horsepower, compelling manufacturers to deploy selective catalytic reduction and diesel particulate filter technologies that add cost and service complexity. FERC Order 2222 enables distributed generator aggregation into wholesale markets, reshaping revenue models for commercial and industrial fleet operators in restructured states. OSHA lockout-tagout and noise exposure standards influence enclosure design and site placement protocols for industrial installations. Stakeholders must monitor state-level building code amendments that increasingly mandate natural gas or battery-ready standby provisions in new commercial construction across California, Florida, and Texas.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing diesel generator margins while accelerating natural gas and hybrid alternatives across the US backup power sector. Data center operators in Texas and Virginia are expanding fleet orders faster than manufacturers can reconfigure engine platforms.
Growth Catalysts
- FERC Order 2222:Distributed generator aggregation into wholesale markets creates new revenue streams for commercial and industrial fleet operators in restructured states. Aggregators now monetize standby capacity as grid resources.
- Data center construction:Hyperscale facilities across Northern Virginia and Dallas-Fort Worth require multi-megawatt backup power blocks with sub-10-second transfer specifications. Generator OEMs are scaling modular architectures to match this demand.
- Natural gas infrastructure:Pipeline network expansion in urban commercial corridors eliminates on-site fuel storage burdens. Building codes in Florida and California increasingly mandate gas-ready standby provisions for new construction.
Market Restraints
- SCR and DPF cost burden:Selective catalytic reduction and diesel particulate filter technologies add 15-25% to engine package costs. Service intervals compress from 500 to 250 hours, raising total cost of ownership for diesel standby fleets.
- Lithium-ion substitution:Portable inverter generators face margin compression from battery-electric alternatives with silent operation and zero emissions. Camping and residential light-duty segments show fastest displacement.
- Emissions compliance timeline:EPA enforcement of Tier 4 Final for engines above 25 horsepower forces premature retirement of pre-compliant inventory. Smaller rental fleet operators struggle with capital refresh requirements.
Strategic Opportunities
- Solar-hybrid configurations:Federal and state government procurement channels favor PV-generator-battery integrated systems. GSA schedules and state RFPs specify renewable-ready backup power for critical facilities.
- Texas petrochemical corridor:Gulf Coast industrial operators seek 500 kW-plus continuous-duty units for process-critical applications. Prime power demand exceeds standby growth in this sub-region.
- Installer channel capture:Residential standby penetration remains below 5% in non-hurricane states. Direct-to-contractor programs and financing partnerships unlock underpenetrated Midwest and Mountain West markets.
Industry Challenges
- Emissions technician shortage:Tier 4 Final servicing requires specialized training in aftertreatment diagnostics. OEM field service networks compete for scarce SCR/DPF-certified technicians.
- Hybrid integration complexity:Battery-generator control systems demand software competency foreign to traditional engine manufacturers. Firmware conflicts between power electronics and engine governors delay commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Generator Sales Market |
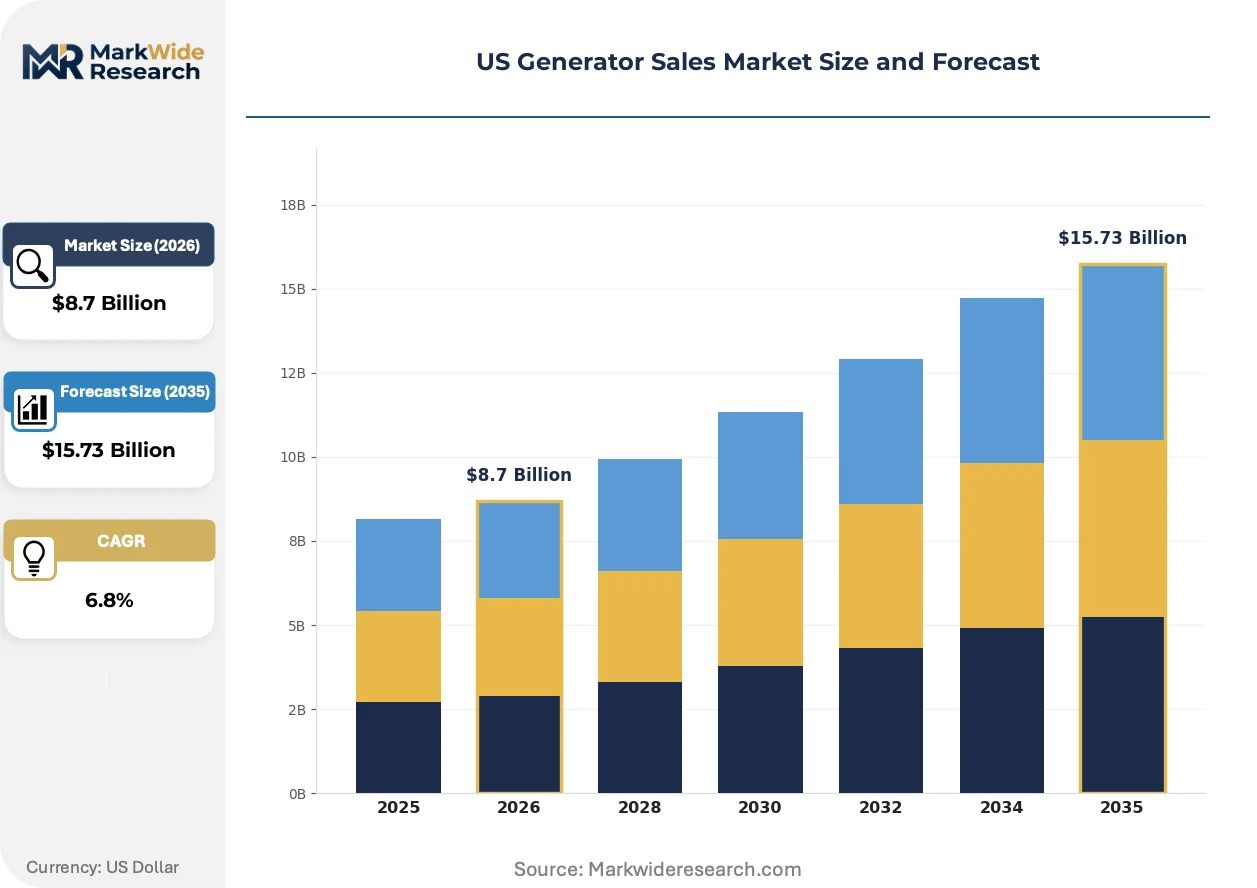
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Inverter, Solar Fuel Type: Gasoline, Diesel, Propane, Natural Gas End User: Residential, Commercial, Industrial, Emergency Services Capacity: 5 kW, 10 kW, 20 kW, 50 kW |
| Companies Covered | Caterpillar Inc., Generac Holdings Inc., Cummins Inc., Kohler Co., American Honda Motor Corp., Briggs & Stratton Corporation, Rolls-Royce plc, Mitsubishi Heavy Industries Ltd., Wärtsilä Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Generator Sales Market Emerging Trajectories
Digital twin architectures are virtualizing generator performance optimization before physical deployment. Three technology trajectories are compressing traditional product lifecycles and reshaping buyer specifications.
Power system simulation software is virtualizing commissioning and load-bank testing protocols. Data center engineers now model transient response and harmonic distortion in cloud environments before equipment arrival. This compression of physical validation cycles accelerates procurement timelines while reducing site integration risk.
EPA enforcement patterns are tightening stationary engine permitting in non-attainment zones. The agency's Good Neighbor Rule and regional haze programs extend Tier 4 Final logic to stationary applications previously exempt. California Air Resources Board reciprocates with in-use fleet rules that force early retirement of pre-2007 engines in backup fleets.
Specification authority is migrating from facilities managers to sustainability officers with carbon accounting mandates. Fortune 500 procurement teams now weight lifecycle emissions alongside capital cost in RFP scoring. This preference shift favors natural gas and hybrid configurations in corporate headquarters and healthcare campus deployments across the Northeast and West Coast.
US Generator Sales Market Segmentation
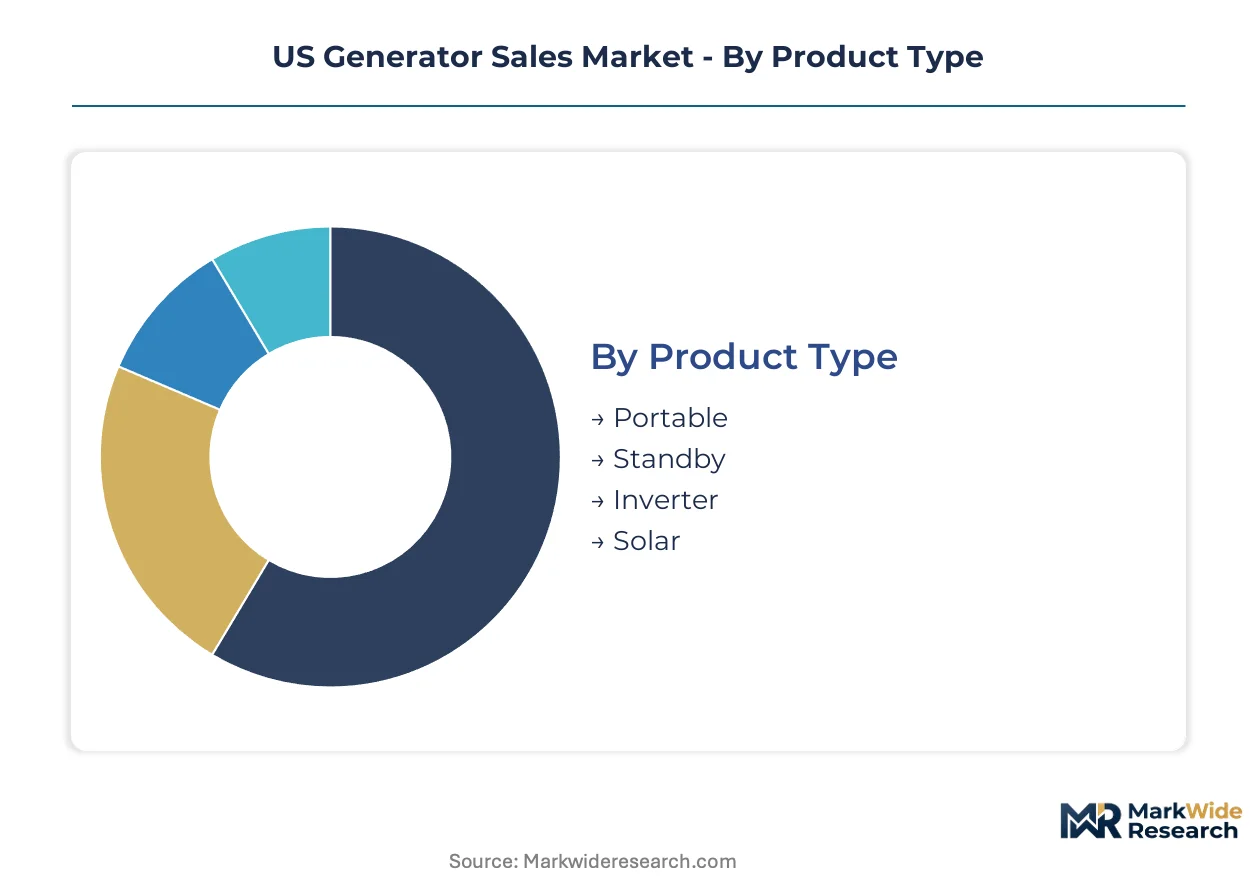
Generator purchasing decisions in the US market bifurcate sharply between emergency backup specifications and continuous-duty industrial requirements. Product architecture, fuel infrastructure availability, and transfer-time tolerances create distinct competitive arenas with minimal overlap in vendor positioning.
Product Type:
Application context determines which product architecture delivers economic value — mobility versus automatic transfer speed versus fuel flexibility versus renewable integration.
- Standby:Permanently installed automatic units with sub-20-second load acceptance and ATS integration. Data center clusters in Northern Virginia and Dallas-Fort Worth specify these for Tier III compliance, with modular megawatt blocks now standard for hyperscale deployments.
- Portable:Mobile frame-mounted units ranging from recreational inverter models to construction-site workhorses. Lithium-ion alternatives from battery OEMs are compressing margins in camping and light residential segments where silent operation outweighs runtime duration.
- Inverter:Microprocessor-controlled units with <3% total harmonic distortion for sensitive electronics. RV parks and telemedicine field stations in hurricane-exposed states favor these for clean power delivery without voltage fluctuation damage.
- Solar:PV-integrated hybrid configurations with battery buffering and generator backup. Federal GSA procurement schedules and state emergency management RFPs specify these for critical facility resilience mandates across California and Florida.
Standby holds installed capacity. Solar is rotating up the share rankings.
Fuel Type:
Pipeline access and emissions compliance timelines reshape fuel selection economics across commercial and industrial deployments.
- Diesel:Energy-dense fuel with established supply chains and 500 kW-plus continuous-duty capability. EPA Tier 4 Final aftertreatment requirements add 15-25% to package costs, compressing margins for rental fleet operators with pre-compliant inventory.
- Natural Gas:Pipeline-delivered fuel eliminating on-site storage burdens and satisfying urban air quality restrictions. Building codes in Florida and California increasingly mandate gas-ready standby provisions for new commercial construction.
- Gasoline:Widely distributed retail fuel suited to portable recreational and light commercial applications. Price volatility and storage degradation limit deployment beyond 10 kW residential units and emergency responder quick-response trailers.
- Propane:Stored liquid fuel with indefinite shelf stability and cold-weather starting reliability. Off-grid residential installations in Mountain West states and food truck operators favor these where natural gas pipelines terminate.
Diesel retains prime power dominance. Natural gas is climbing the fastest in standby specifications.
End User:
Customer type dictates specification authority, procurement channel, and service contract structure.
- Industrial:Process-critical operations requiring 500 kW-plus continuous-duty units with 99.999% availability guarantees. Gulf Coast petrochemical corridor operators specify these for flare gas recovery and emergency process shutdown power.
- Commercial:Retail, healthcare, and office facilities seeking demand-charge reduction and code-compliant backup. Sustainability officers now weight lifecycle emissions alongside capital cost in corporate headquarters RFP scoring across the Northeast.
- Residential:Single-family and multi-family installations for outage protection and insurance premium reduction. Penetration remains below 5% in non-hurricane Midwest and Mountain West markets, creating installer channel expansion opportunity.
- Emergency Services:Hospital, fire station, and 911 center deployments with sub-10-second transfer mandates. State emergency management agencies specify solar-hybrid configurations for resilience against extended grid failures.
Industrial anchors revenue per unit. Commercial is expanding most quickly in unit volume.
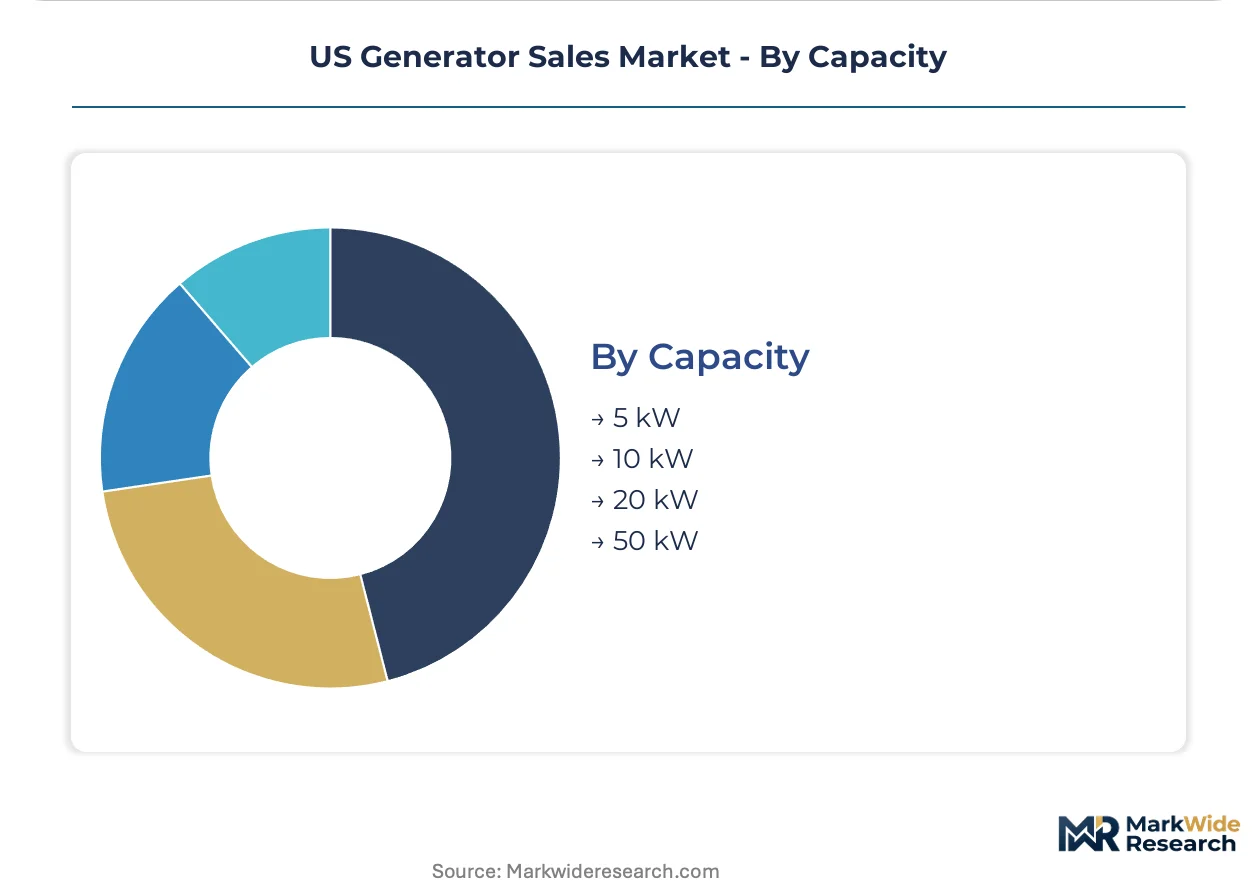
Capacity:
Power output tiers align with load profiles from residential appliance circuits to industrial motor starting requirements.
- 50 kW:Three-phase commercial units serving small retail centers and restaurant chains. Natural gas configurations dominate this tier where pipeline access eliminates diesel fuel storage compliance burdens.
- 20 kW:Large residential and small commercial standby threshold with automatic transfer switch integration. Whole-house coverage for 4,000-plus square foot homes and professional office suites drives installer channel volume.
- 10 kW:Mid-size residential and portable commercial segment with partial-home or essential-circuit coverage. Camping enthusiasts and mobile food vendors split demand between recreational inverter and light construction specifications.
- 5 kW:Entry-level residential and recreational portable segment. Battery-electric alternatives with silent operation are displacing gasoline units in tailgating and light camping applications fastest.
50 kW commands premium pricing. 20 kW is gaining share fastest in absolute unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US generator manufacturers export standby power systems to Canadian oil sands operators and Mexican industrial parks along the border manufacturing corridor. Cross-border trade flows concentrate on natural gas configurations for urban commercial deployment and diesel prime power units for remote resource extraction.
Texas
Hyperscale data centers in Dallas-Fort Worth and Austin drive multi-megawatt backup power procurement with sub-10-second transfer specifications. EPA regional haze programs tighten stationary engine permitting in Houston-Galveston non-attainment zones. Gulf Coast petrochemical operators in Beaumont-Port Arthur specify 500 kW-plus continuous-duty units for process-critical flare gas recovery applications.
Virginia
Northern Virginia's data center alley consumes modular generator blocks faster than OEMs can reconfigure engine platforms for Tier III compliance. FERC Order 2222 enables distributed generator aggregation into wholesale markets for commercial fleet operators. Loudoun County and Prince William County host the densest concentration of hyperscale backup power deployments in the Eastern US.
California
CARB in-use fleet rules force early retirement of pre-2007 diesel engines in backup fleets across Los Angeles Basin and San Joaquin Valley. State building codes mandate natural gas or battery-ready standby provisions for new commercial construction in San Francisco Bay Area. Solar-hybrid configurations dominate federal and state procurement for critical facility resilience mandates.
Florida
Hurricane exposure drives residential standby penetration above national averages in Miami-Dade and Broward counties. State building codes increasingly mandate gas-ready standby provisions for new commercial construction in Tampa-Orlando corridor. Generac Holdings Inc. dominates installer channel control through direct-to-contractor programs in hurricane-exposed coastal markets.
Illinois
Chicago metro commercial facilities seek demand-charge reduction through peak-shaving generator deployments. EPA Good Neighbor Rule extends Tier 4 Final logic to stationary applications in Lake Michigan airshed. Industrial operators in Rockford and Peoria manufacturing corridors specify natural gas units where pipeline access eliminates on-site fuel storage burdens.
US Generator Sales Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct installation and specification tiers. The market structures around three dominant archetypes: integrated power system manufacturers with in-house engine production, residential standby specialists with installer network control, and industrial prime power fabricators with continuous-duty engineering heritage. Competitive moves concentrate on strategic partnerships for hybrid integration and geographic expansion into underpenetrated Midwest and Mountain West markets.
Within the integrated power system tier, Caterpillar Inc., Cummins Inc., and Generac Holdings Inc. exemplify divergent strategic positions. Caterpillar Inc. anchors the high-capacity industrial segment where mining and oilfield operators demand 500 kW-plus continuous-duty units. Cummins Inc. occupies a position in data center backup power through in-house production of integrated power systems. Generac Holdings Inc. represents the residential standby archetype with installer channel control in hurricane-exposed states.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Generac Holdings Inc. |
| Cummins Inc. |
| Kohler Co. |
| American Honda Motor Corp. |
| Briggs & Stratton Corporation |
| Rolls-Royce plc |
| Mitsubishi Heavy Industries Ltd. |
| Wärtsilä Corporation |
| Others |
Supply Flow & Price Mechanics
Dallas-Fort Worth data center clusters concentrate multi-megawatt generator procurement, concentrating OEM bargaining power and compressing delivery premiums for hyperscale contracts. Tier 4 Final aftertreatment complexity feeds cost inflation through diesel standby fleets while natural gas configurations capture price premiums in urban corridors with pipeline access.
Pricing Analysis
Pre-Tier 4 Final diesel platforms trade at 15-25% discounts to EPA-compliant configurations, creating a two-tier pricing structure across rental fleet inventories. Three-tier pricing stratifies across premium natural gas hybrids with battery integration, standard diesel standby with SCR/DPF aftertreatment, and economy gasoline portable units facing lithium-ion displacement. Pricing pressure stems from battery-electric alternatives in sub-10 kW recreational segments where silent operation commands buyer preference. Residential standby buyers show highest price sensitivity in non-hurricane Midwest markets, while data center operators demonstrate lowest sensitivity given Tier III compliance mandates.
Supply Chain Analysis
Engine block castings and alternator laminations draw from foundry capacity concentrated in Mexico, China, and domestic Rust Belt manufacturing corridors. Aftertreatment catalysts source from South Korean and German chemical processors, while power electronics for hybrid controls rest on Taiwanese semiconductor fabrication. Single-source vulnerability concentrates in selective catalytic reduction substrate supply, where two global suppliers dominate stationary engine certification. Distribution runs through authorized dealer networks for industrial tier, direct-to-contractor channels for residential standby, and big-box retail for portable recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US generator sales fragment across fuel type, capacity tier, and end-use specification, creating niches as sustainability officers displace facilities managers in procurement authority. This demand-side shift rewards players with carbon-accounting competencies and hybrid integration capabilities.
For Market Incumbents: Build certification moats around EPA Tier 4 Final and CARB in-use fleet compliance to lock out pre-compliant inventory holders. Defensive consolidation should prioritize captive aftertreatment servicing networks in Texas and Virginia data center corridors, where SCR/DPF technician scarcity threatens uptime guarantees. Capacity addition in Gulf Coast petrochemical clusters captures prime power demand exceeding standby growth. For New Entrants and Emerging Players: Mountain West residential markets below 5% standby penetration offer installer channel white space without hurricane-driven incumbent saturation. Solar-hybrid configurations for federal GSA procurement channels represent the most penetrable product architecture, given renewable-ready resilience mandates in California and Florida. Go-to-market execution should anchor on state emergency management RFP relationships rather than OEM dealer networks. For Investors and Strategic Acquirers: Long-term, this sits as a grid-resilience infrastructure play because FERC Order 2222 monetization and data center construction cycles extend replacement demand beyond traditional backup power cycles. Acquisition targets should emphasize software-defined power electronics competency for battery-generator hybrid control. The signal to watch is state building code amendments mandating natural gas or battery-ready standby provisions in new commercial construction.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Integration Partnership | Battery-generator control firmware development accelerates commissioning timelines for data center Tier III compliance. |
| Aftertreatment Servicing Network | SCR/DPF-certified technician training programs lock in recurring revenue from EPA Tier 4 Final fleet maintenance. |
| Installer Channel Financing | Direct-to-contractor programs unlock residential standby penetration in underpenetrated Midwest and Mountain West markets. |
| Solar-Hybrid Certification | Federal GSA schedule qualification captures renewable-ready backup power procurement for critical facility resilience mandates. |
| Natural Gas Infrastructure Alignment | Pipeline access partnerships in Florida and California building code corridors eliminate on-site fuel storage compliance burdens. |
Methodological Framework
The analysis maps standby, portable, inverter, and solar-hybrid product architectures, each validated through OEM product managers, rental fleet operators, data center facilities engineers, and electrical contractor installers. Primary fieldwork combined with secondary validation from EPA engine certification databases, FERC Order 2222 implementation filings, EIA generator survey data, and state building code amendment records. Bottom-up unit shipment estimates triangulate against top-down capacity installation values across the projection horizon.
Forecast assumptions hold fixed EPA Tier 4 Final enforcement timelines and state renewable portfolio standard trajectories while varying data center construction permitting and natural gas pipeline expansion rates. Segmentation dimensions modeled include product type, fuel source, end-user category, and capacity tier across regional grid reliability clusters. CAGRs derive from installation trend extrapolation moderated by substitution elasticity estimates for battery-electric alternatives. Industry-specific inputs incorporate CARB in-use fleet rule retirement schedules and hyperscale data center power density specifications.
Practitioners should monitor EPA regional haze program enforcement and state-level building code amendment calendars for early signals of demand inflection. Forecasts reflect assumptions about battery cost decline curves and natural gas infrastructure buildout that could revise materially. Cross-checking against EIA generator survey benchmarks and FERC interconnection queue data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Tri Fuel Generators Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Europe Diesel Generator Market
Generators
Turbo Generator Market
Generators
North America Gasoline Gensets Market
Generators
Generator Belt Market
Generators
Generator Rental Market
Generators
United States Portable Generator Market
Generators
North America Diesel Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Portugal Gas Generator Market
Generators
India Portable Generator Market
Generators
Power Generator for Military Market
Generators
Nuclear Turbine Generators Market
Generators
Portable Inverter Generators Market
Generators
Home Standby Gensets Market