
 Complement-Targeted Therapeutics Market | 2026-2036
Complement-Targeted Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Complement-Targeted Therapeutics Market Outlook
Recombinant protein engineering is realigning manufacturing economics for complement-targeted biologics, replacing traditional hybridoma-dependent production with mammalian cell culture platforms that yield higher specific activity. AstraZeneca leverages its rare disease infrastructure to anchor European distribution of complement inhibitors. Alexion Pharmaceuticals sustains pipeline momentum through specialized development in paroxysmal nocturnal hemoglobinuria and atypical hemolytic uremic syndrome. Novartis competes on manufacturing scale, operating multi-product biologics facilities that serve both monoclonal antibody and small molecule complement programs.
Complement-targeted therapeutics comprise biologic and small-molecule modalities engineered to modulate the complement cascade, a proteolytic immune defense system involving over 30 plasma and membrane-bound proteins that opsonize pathogens, amplify inflammatory signals, and lyse target cells through membrane attack complex formation. These interventions primarily serve to treat rare autoimmune and inflammatory conditions where complement dysregulation drives tissue damage, including paroxysmal nocturnal hemoglobinuria, atypical hemolytic uremic syndrome, and geographic atrophy. Monoclonal antibodies capture the dominant share of current revenue due to validated clinical outcomes and established reimbursement pathways, while small molecules represent the fastest-expanding development category as oral bioavailability promises to shift administration from infusion centers to homecare settings. Complement inhibitors command premium positioning within hospital formularies, though intravenous delivery modes constrain expansion into outpatient clinics where subcutaneous alternatives are gaining preference.
FDA accelerated approval pathways and EMA adaptive licensing frameworks compress development timelines for complement inhibitors, while FDA orphan drug designations secure extended exclusivity periods that shape investment allocation across indication selection. The country's national pharmaceutical regulator in Japan, PMDA, maintains distinct stability requirements for biologics that influence formulation decisions for Asia-Pacific market entry. Stakeholders must monitor evolving payer evidence requirements for complement therapies, as health technology assessment bodies in Germany and France tighten cost-effectiveness thresholds for ultra-rare disease indications.
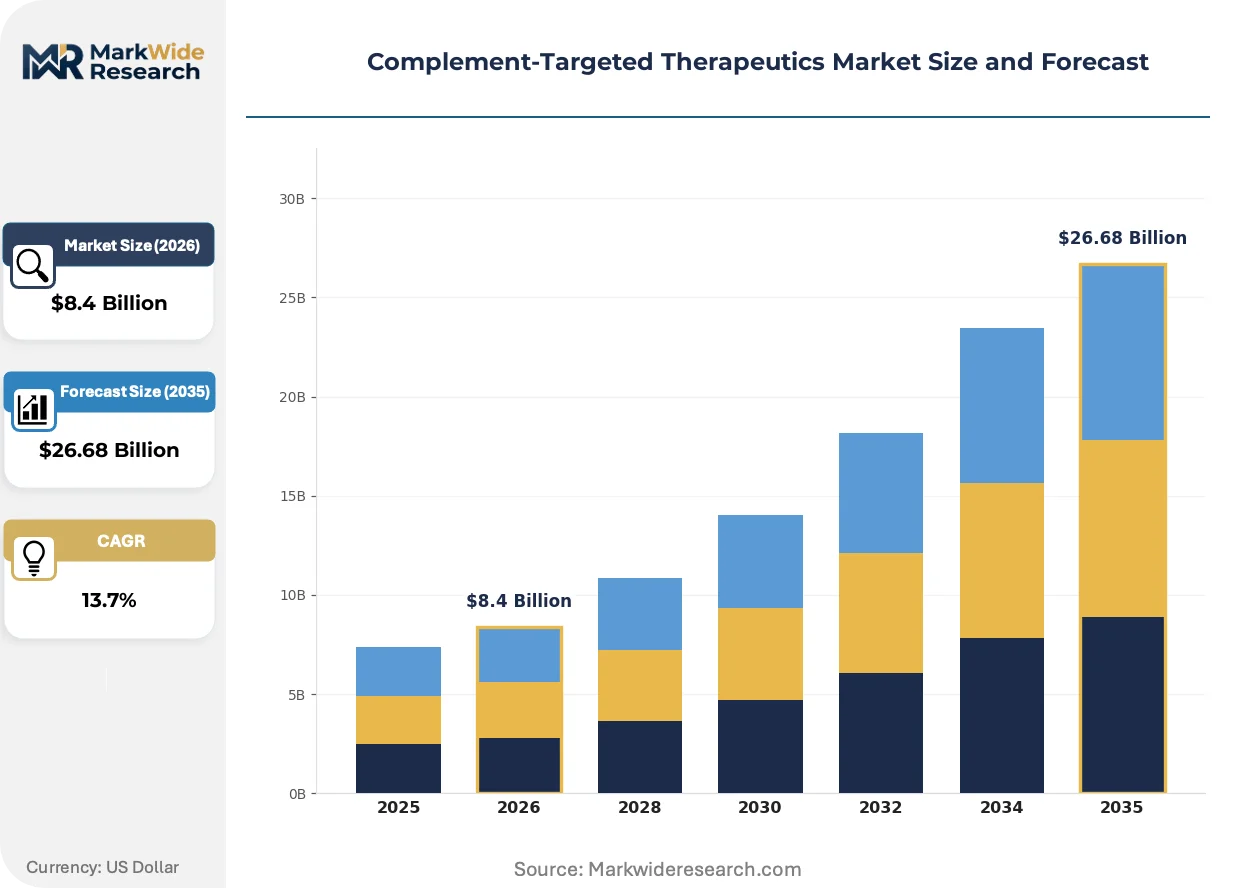
Market Dynamics
Recombinant protein engineering is compressing manufacturing costs for complement-targeted biologics, shifting production economics away from hybridoma-dependent platforms toward mammalian cell culture systems that yield higher specific activity at commercial scale.
Growth Catalysts
- FDA accelerated approval pathways:These frameworks compress development timelines for complement inhibitors targeting rare autoimmune conditions, reducing the interval between Phase II evidence and commercial availability.
- Paroxysmal nocturnal hemoglobinuria treatment centers:Specialized hospital infrastructure in the United States, Germany, and Japan is expanding payer coverage for high-cost biologics and anchoring demand concentration.
- Subcutaneous formulation platforms:Delivery technology advances are shifting administration from infusion centers toward homecare settings, expanding addressable patient populations.
Market Restraints
- Plasma protein supply volatility:Raw material sourcing for complement cascade components faces concentration risk from limited qualified suppliers in North America and Europe.
- EMA adaptive licensing friction:Conditional approval frameworks require extensive post-authorization evidence generation, creating reimbursement uncertainty across European markets.
- Small molecule substitution pressure:Oral bioavailability in emerging non-biologic programs threatens to displace intravenous monoclonal antibodies in maintenance therapy segments.
Strategic Opportunities
- Geographic atrophy in Japan:The country's aging demographic and expanded PMDA reimbursement for ophthalmic biologics creates underpenetrated demand for complement C5 inhibitors.
- Home infusion channel development:Specialty pharmacy networks are building cold-chain infrastructure that enables direct-to-patient delivery of subcutaneous complement therapies.
- EU orphan drug incentives:Extended market exclusivity provisions and protocol assistance programs reduce regulatory risk for developers targeting ultra-rare indications.
Industry Challenges
- Bioprocess engineering talent scarcity:Mammalian cell culture optimization for complement protein production requires specialized expertise concentrated among limited contract development organizations.
- Multi-region stability compliance:PMDA maintains distinct formulation requirements for biologics that force separate development tracks for Asia-Pacific market entry.
- Health technology assessment divergence:Germany's IQWiG and France's HAS apply divergent cost-effectiveness thresholds for ultra-rare disease therapies, fragmenting pricing strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complement-Targeted Therapeutics Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Complement Inhibitors, Small Molecules, Biologics Indication: Autoimmune Diseases, Neurological Disorders, Cardiovascular Conditions, Inflammatory Diseases Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Institutions, Homecare Settings |
| Companies Covered | AstraZeneca, UCB, Alexion Pharmaceuticals, ChemoCentryx, Regeneron, Novartis, Apellis Pharmaceuticals, Genentech, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complement-Targeted Therapeutics Market Strategic Shifts
Automation platforms and adaptive regulatory frameworks are converging to reshape how complement-targeted therapeutics progress from discovery to commercial scale, with particular pressure on manufacturing throughput and evidence-generation models.
Continuous bioprocessing technology is automating upstream cell culture operations for complement protein production. Contract manufacturers in Switzerland and Ireland are adopting perfusion-based systems that reduce facility footprint while maintaining glycosylation profiles critical for C5 inhibitor activity. This automation is compressing batch cycle times from weeks to days, enabling capacity expansion without greenfield construction.
EMA's adaptive licensing frameworks are accelerating conditional approvals for complement inhibitors in atypical hemolytic uremic syndrome. The policy permits marketing authorization based on surrogate endpoints, contingent on post-market confirmatory trials. Pediatric nephrology centers in France and Germany are prioritizing enrollment in these studies to secure early access, reshaping trial design across European development programs.
Hospital procurement consortia are consolidating purchasing power for high-cost biologics. Integrated delivery networks in the United States are negotiating indication-based contracts that tie reimbursement to patient response metrics, displacing traditional volume-based purchasing. This behavioral shift is most visible in hematology-oncology departments where complement inhibitors compete for limited formulary slots against established immunotherapies.
Complement-Targeted Therapeutics Market Segmentation
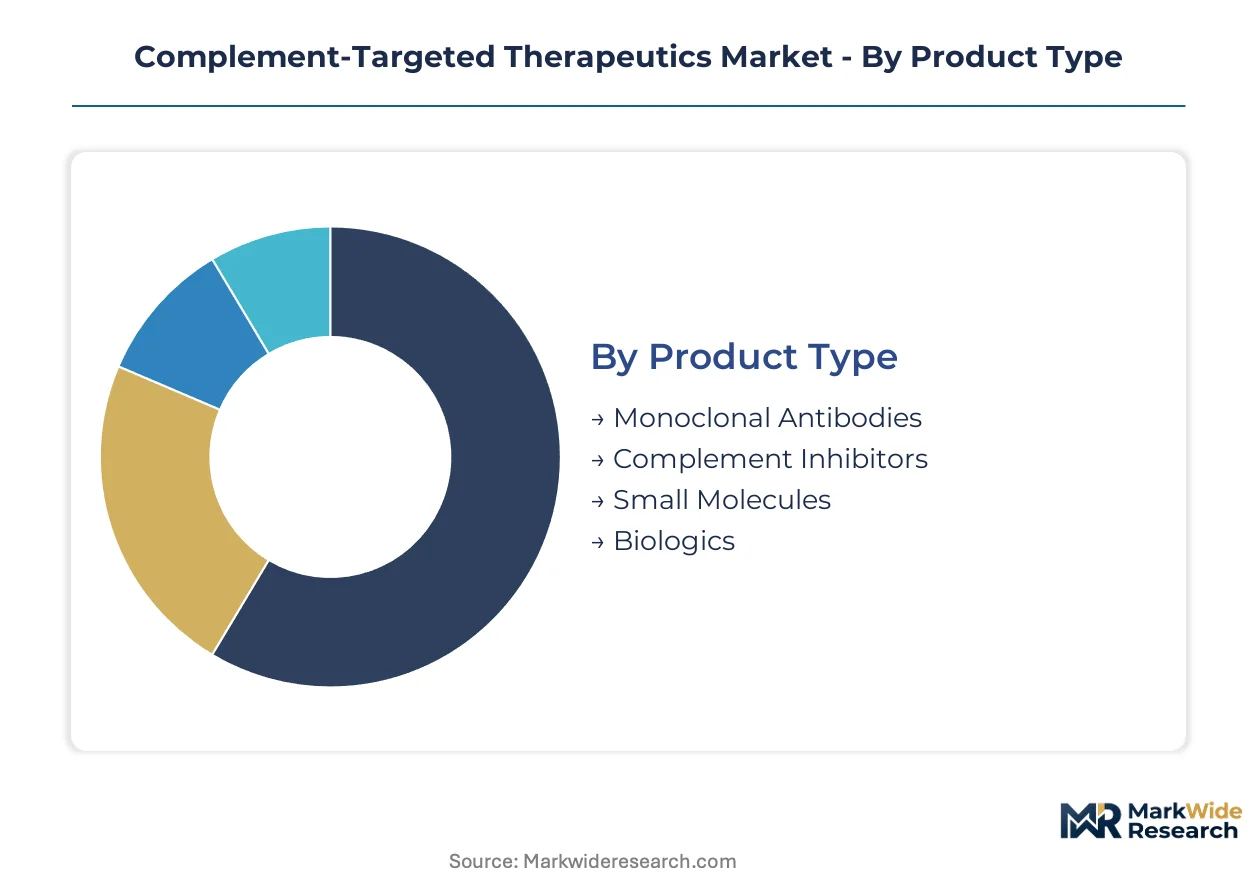
Complement-targeted therapeutics fragment across four critical dimensions that determine reimbursement pathways, manufacturing scale, and patient access. Product type dictates regulatory strategy and production economics. Indication selection shapes clinical trial design and payer negotiation leverage. Delivery mode and end-user channel determine distribution infrastructure requirements and pricing power.
Product Type:
Cost tier separates developers pursuing premium biologic positioning from those targeting volume markets through synthetic chemistry.
- Monoclonal Antibodies:Engineered immunoglobulins that bind complement cascade proteins with high specificity. Infusion center networks in the United States and Germany anchor demand for intravenous formulations, though cold-chain logistics constrain expansion into outpatient settings. Volume sits with monoclonal antibodies; growth tilts toward subcutaneous formulation platforms.
- Small Molecules:Synthetic compounds with oral bioavailability that inhibit complement proteases or receptor signaling. Japan's PMDA has streamlined review pathways for ophthalmic small molecules, accelerating geographic atrophy programs toward market entry.
- Complement Inhibitors:Targeted biologics engineered to block specific cascade activation points, including C3 and C5 convertases.
- Biologics:Recombinant proteins and fusion constructs manufactured through mammalian cell culture systems with defined glycosylation profiles.
Manufacturing scale concentrates among monoclonal antibodies; oral bioavailability in small molecules is expanding most quickly.
Indication:
Application severity determines pricing tolerance and regulatory urgency across autoimmune, neurological, cardiovascular, and inflammatory categories.
- Autoimmune Diseases:Conditions where complement dysregulation drives tissue destruction, including paroxysmal nocturnal hemoglobinuria and atypical hemolytic uremic syndrome. Specialized treatment centers in France and Germany generate concentrated demand for chronic maintenance therapies.
- Neurological Disorders:Emerging applications in myasthenia gravis and neuromyelitis optica spectrum disorder where complement-mediated synaptic damage accelerates functional decline. FDA breakthrough therapy designations have compressed development timelines for C5 inhibitors in these indications.
- Cardiovascular Conditions:Ischemia-reperfusion injury and complement-mediated thrombotic microangiopathies where acute intervention windows demand rapid-acting formulations.
- Inflammatory Diseases:Broad category spanning ocular, renal, and dermatologic conditions with complement-driven pathogenesis.
Revenue concentrates in autoimmune diseases; neurological applications are climbing the fastest.
Delivery Mode:
Patient convenience and healthcare resource requirements divide administration between facility-based and self-managed settings.
- Intravenous:Infusion-dependent delivery requiring clinical supervision and vascular access. Hospital procurement consortia in the United States negotiate indication-based contracts that tie reimbursement to hematologic response metrics.
- Subcutaneous:Self-administered injection platforms enabled by formulation advances in high-concentration protein solutions. Specialty pharmacy networks are building cold-chain infrastructure for direct-to-patient distribution in Germany and Japan.
- Oral:Small-molecule tablets and capsules eliminating infusion center dependency for maintenance therapy segments.
- Topical:Localized delivery for ophthalmic and dermatologic applications with limited systemic exposure.
Facility utilization clusters around intravenous delivery; patient preference is shifting fastest toward subcutaneous alternatives.
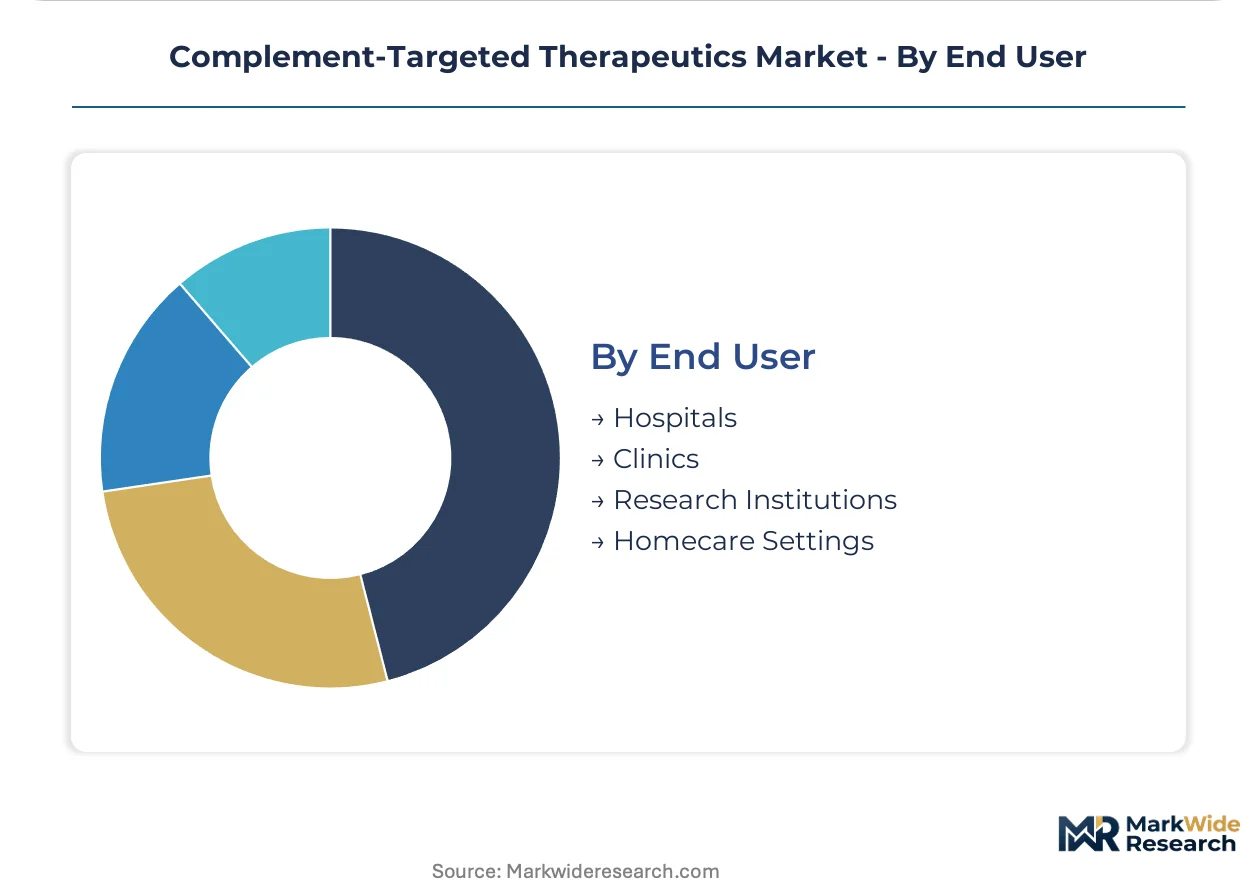
End User:
Channel type determines reimbursement complexity, clinical decision-making authority, and inventory management requirements.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees controlling formulary access for high-cost biologics. Hematology-oncology departments in the United States compete for limited slots against established immunotherapies.
- Clinics:Outpatient specialty settings where nephrology and ophthalmology practices manage chronic complement-mediated conditions. EMA adaptive licensing frameworks enable early access programs through French and German pediatric nephrology centers.
- Research Institutions:Academic medical centers conducting investigator-sponsored trials and post-authorization evidence generation.
- Homecare Settings:Direct-to-patient delivery models supported by nursing services and remote monitoring infrastructure.
Purchasing power aggregates through hospitals; patient volume is migrating fastest toward homecare channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hospital infrastructure for rare disease biologics concentrates demand in the United States, Germany, and Japan, where expanded payer coverage for complement inhibitors anchors regional market expansion.
United States
Integrated delivery networks in Massachusetts and North Carolina negotiate indication-based contracts for C5 inhibitors, tying reimbursement to hematologic response metrics. FDA accelerated approval pathways compress development timelines for paroxysmal nocturnal hemoglobinuria therapies. Boston's rare disease treatment cluster generates concentrated demand through specialized hematology-oncology departments competing for limited formulary slots.
Germany
Pediatric nephrology centers in Munich and Heidelberg prioritize enrollment in post-authorization studies for atypical hemolytic uremic syndrome therapies. IQWiG applies tightening cost-effectiveness thresholds for ultra-rare disease indications, creating reimbursement uncertainty. The country's EMA adaptive licensing framework enables early access programs through university hospital networks.
Japan
PMDA maintains distinct stability requirements for biologics that influence formulation decisions for complement inhibitor market entry. Tokyo's aging demographic and expanded ophthalmic biologics reimbursement create underpenetrated demand for geographic atrophy treatments. The Kanto region's specialty pharmacy networks are building cold-chain infrastructure for direct-to-patient delivery.
Switzerland
Contract manufacturers in Basel and Zurich adopt perfusion-based continuous bioprocessing systems for complement protein production. Swissmedic coordinates with EMA on adaptive licensing frameworks while maintaining separate pediatric investigation plans. The country's multi-product biologics facilities serve both monoclonal antibody and small molecule complement programs.
United Kingdom
London's academic medical centers conduct investigator-sponsored trials for emerging neurological applications in myasthenia gravis. The MHRA operates post-Brexit recognition procedures with FDA and EMA that streamline complement inhibitor approvals. Cambridge's recombinant protein engineering specialists concentrate bioprocess optimization expertise for mammalian cell culture platforms.
Complement-Targeted Therapeutics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with large-cap pharmaceutical companies commanding hospital formulary access while biotechnology developers anchor innovation in rare disease niches. The vendor base concentrates around three strategic archetypes: integrated rare disease platforms, multi-product biologics operators, and specialized complement-focused developers. Competitive dynamics center on manufacturing scale advantages and regulatory pathway expertise rather than price competition. M&A activity targets pipeline assets in neurological and ophthalmic indications, while strategic partnerships secure mammalian cell culture capacity.
Within the integrated rare disease platform tier, AstraZeneca and Alexion Pharmaceuticals exemplify infrastructure-heavy positioning that leverages specialized distribution networks. Among multi-product biologics operators, Novartis occupies a scale-driven position serving diverse modality requirements. Apellis Pharmaceuticals represents the specialized complement-focused archetype, concentrating development resources on C3 and C5 inhibition pathways. These three companies collectively illustrate how competitive positioning depends on manufacturing depth and regulatory navigation capability rather than therapeutic specialization alone.
| Leading Market Players |
|---|
| AstraZeneca |
| UCB |
| Alexion Pharmaceuticals |
| ChemoCentryx |
| Regeneron |
| Novartis |
| Apellis Pharmaceuticals |
| Genentech |
| Roche |
| Others |
Value Chain & Pricing Dynamics
Mammalian cell culture media costs cascade through three pricing tiers for complement-targeted biologics, with serum-free formulations commanding premium positioning against hybridoma-derived alternatives in hospital procurement negotiations. This input cost structure concentrates pricing power among manufacturers operating multi-product biologics facilities in Switzerland and Ireland, while Japanese PMDA stability requirements force separate formulation tracks that fragment regional price bands.
Pricing Analysis
Volume concentrates with intravenous monoclonal antibodies in infusion center networks, while margins expand fastest in subcutaneous and oral small-molecule segments shifting toward homecare administration. Price differentiation hinges on glycosylation profile consistency and cold-chain reliability certification, with FDA orphan drug exclusivity periods enabling premium positioning for ultra-rare indications. Cost compression in standard-tier biologics is intensifying as hospital procurement consortia negotiate indication-based contracts tied to hematologic response metrics. Academic medical centers exhibit highest price sensitivity due to constrained formulary budgets, while integrated delivery networks in Massachusetts and North Carolina absorb premium positioning for C5 inhibitors through specialized rare disease infrastructure.
Supply Chain Analysis
Qualification gating through FDA Current Good Manufacturing Practice and EMA GMP certification limits contract manufacturing organization participation to facilities with demonstrated complement protein production history. Supply concentrates in Switzerland, Ireland, and the United States, with perfusion-based continuous bioprocessing systems reducing batch cycle times while maintaining glycosylation critical for C5 inhibitor activity. Raw material dependencies include recombinant protein expression vectors, chemically defined cell culture media, and single-use bioreactor components. Single-source vulnerability runs through limited qualified suppliers of complement cascade plasma proteins in North America and Europe. Distribution runs through hospital centralized pharmacies and specialty pharmacy networks building cold-chain infrastructure for direct-to-patient delivery in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways and EMA adaptive licensing frameworks erect substantial cost-of-compliance barriers that protect entrenched players with established regulatory affairs infrastructure and rare disease commercialization expertise. These frameworks compress development timelines only for developers capable of generating surrogate endpoint evidence and managing post-authorization confirmatory trial obligations.
For Market Incumbents: Anticipate substitution pressure from oral small-molecule programs by anchoring market position through backward integration into mammalian cell culture capacity and securing exclusive channel arrangements with pediatric nephrology centers in France and Germany. Prioritize formulation investments in subcutaneous delivery platforms to defend against homecare channel displacement, while monitoring EMA post-authorization evidence requirements that threaten reimbursement continuity for atypical hemolytic uremic syndrome therapies. For New Entrants and Emerging Players: Subcutaneous formulation technology offers the most penetrable entry point for developers lacking established infusion center relationships, with geographic atrophy in Japan presenting underexploited demand given PMDA's streamlined ophthalmic small-molecule review pathways. Target white-space opportunities in neurological applications including myasthenia gravis where FDA breakthrough therapy designations compress competitive timelines. Pursue go-to-market strategies anchored by specialty pharmacy partnerships rather than hospital formulary competition. For Investors and Strategic Acquirers: FDA breakthrough therapy designation for C5 inhibitors in neurological indications is the leading indicator that pipeline assets in this category warrant premium valuation multiples. Long-term viability across the analysis window rests on manufacturing scale advantages and regulatory pathway expertise rather than therapeutic specialization alone. Acquisition focus should concentrate on biotechnology developers with demonstrated mammalian cell culture optimization capabilities and active pediatric investigation plans. Monitor EMA conditional approval conversions as the critical signal for portfolio rebalancing toward confirmed commercial assets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses Phase II-to-commercial intervals for rare disease biologics. |
| Manufacturing Scale-Up | Perfusion-based continuous bioprocessing reduces facility footprint while maintaining C5 inhibitor glycosylation profiles. |
| Pipeline Diversification | Neurological indications in myasthenia gravis expand addressable populations beyond hematologic anchors. |
| Hospital System Partnership | Integrated delivery network contracts in Massachusetts tie reimbursement to patient response metrics. |
| Reimbursement Strategy | EMA adaptive licensing enables early access through French and German pediatric nephrology enrollment. |
Study Parameters
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists underwrites the qualitative findings presented in this analysis. Primary interviews with hospital procurement managers in the United States, Germany, and Japan were cross-referenced against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population estimates and top-down market sizing approaches were reconciled through iterative triangulation.
Comparable historical performance across prior complement inhibitor launches anchored the forecast window, with projections developed over the analysis window through segmented modeling across product type, indication severity, delivery mode, and end-user channel dimensions. CAGRs were derived from growth rate convergence analysis applied to penetration curves in paroxysmal nocturnal hemoglobinuria and atypical hemolytic uremic syndrome. Forecast inputs incorporated treatment center expansion rates, PMDA reimbursement trajectory for ophthalmic biologics, and health technology assessment evolution in Germany and France.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA adaptive licensing conversion failures or IQWiG cost-effectiveness threshold tightening. Model assumptions reflect documented regulatory pathway timelines, manufacturing capacity expansion plans, and payer evidence requirements. A model refresh is warranted upon material change in FDA breakthrough therapy designation patterns or PMDA stability requirement revisions affecting Asia-Pacific formulation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Loxoprofen Market