
 Hyoscine-N-Butyl Bromide Market | 2026-2036
Hyoscine-N-Butyl Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Hyoscine-N-Butyl Bromide Market Foresight
Indian API manufacturers is broadening output of hyoscine-N-butyl bromide active pharmaceutical ingredient to serve rising formulation demand across regulated and emerging markets. Boehringer Ingelheim leverages its heritage brand position in European hospital channels to sustain premium positioning against generic entrants. Alkaloid Skopje anchors supply security through captive cultivation of Datura stramonium, the botanical source of tropane alkaloid precursors.
Hyoscine-N-butyl bromide is a quaternary ammonium antimuscarinic compound with molecular formula C21H30BrNO4, synthesized via esterification of scopolamine with n-butyl bromide to yield a peripherally acting spasmolytic that does not cross the blood-brain barrier. Tablet formulations dominate volume consumption in ambulatory settings where oral administration suffices for irritable bowel syndrome management, while ampoule and injection formats command higher unit economics in perioperative and emergency applications where rapid onset is clinically essential. Extended release formulations represent a developing margin pool as manufacturers seek to differentiate beyond immediate-release commoditization.
FDA bioequivalence standards govern generic substitution in US channels, while EMA's quality guidelines for chemically synthesized APIs shape import acceptance criteria for European hospital pharmacies. India's CDSCO manufacturing licensing and the country's PLI scheme for bulk drugs influence domestic capacity investment and export competitiveness. Stakeholders must monitor evolving pharmacopeial monograph revisions and botanical sourcing sustainability as dual pressures on quality assurance and supply chain resilience intensify.
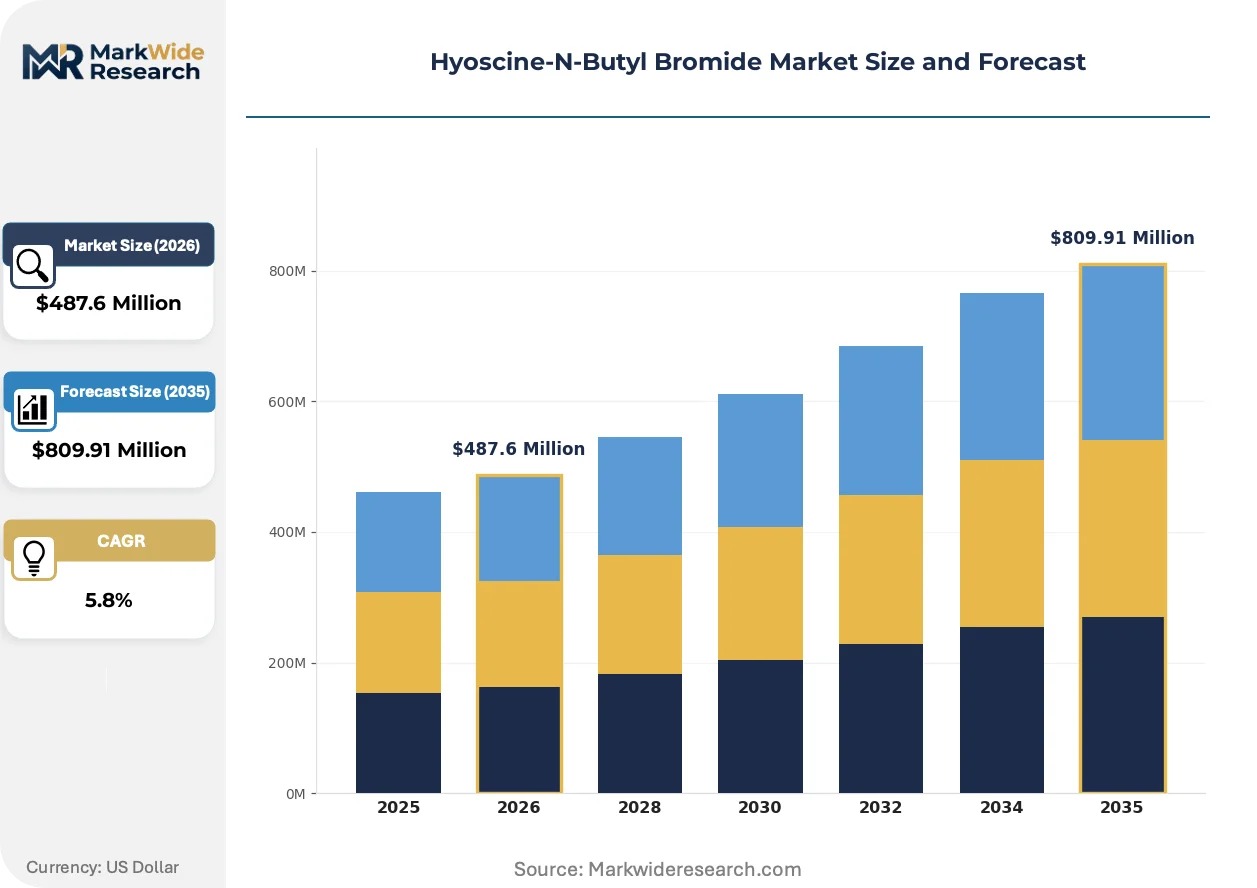
Market Dynamics
FDA bioequivalence requirements for generic antispasmodics are compressing formulation differentiation windows while Indian API output expansion reshapes supply economics across regulated and emerging channels.
Growth Catalysts
- Ambulatory surgical volume expansion:Rising day-case procedures in US and European hospital systems sustain injectable hyoscine-N-butyl bromide procurement for perioperative spasmolysis.
- CDSCO manufacturing licensing:India's streamlined bulk drug licensing under the PLI scheme accelerates domestic API capacity additions serving export markets.
- Extended-release formulation development:Pharmaceutical manufacturers are investing in modified-release tablet technologies to escape immediate-release commoditization.
Market Restraints
- Datura stramonium cultivation concentration:Captive botanical sourcing in Balkan and Indian agricultural zones creates weather-dependent supply vulnerability for tropane alkaloid precursors.
- Generic substitution pressure:FDA bioequivalence standards enable rapid therapeutic substitution, eroding brand premium persistence in US pharmacy channels.
- Quaternary ammonium synthesis complexity:Esterification of scopolamine with n-butyl bromide requires specialized equipment and handling protocols that constrain batch scale-up.
Strategic Opportunities
- Underpenetrated Latin American hospital sectors:Brazilian ANVISA registration pathways for imported injectable antispasmodics remain less contested than US or EU channels.
- EMA quality guideline alignment:Chemically synthesized API certification to European pharmacopeial standards opens hospital pharmacy tenders in Germany, France, and Italy.
- Telemedicine-integrated IBS management:Remote diagnostic platforms in Indian urban centers are creating direct-to-patient oral formulation channels bypassing traditional wholesale distribution.
Industry Challenges
- Pharmacopeial monograph revision tracking:Manufacturers must maintain simultaneous compliance with USP, EP, and IP standards as botanical sourcing specifications tighten.
- Specialized chemical engineering talent scarcity:Quaternary ammonium synthesis expertise concentrates in legacy European and Indian facilities, constraining new entrant technical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyoscine-N-Butyl Bromide Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Ampoules, Injections, Oral Solutions End User: Hospitals, Clinics, Homecare, Pharmacies Formulation: Immediate Release, Extended Release, Combination Formulations, Liquid Formulations Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Wholesalers |
| Companies Covered | Boehringer Ingelheim, Alkaloid Skopje, Caleb Pharmaceuticals, ALPS Pharmaceutical Ind. Co. Ltd., Alchem International, Linnea SA, Biotechnica Pharma Global, Pfizer, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyoscine-N-Butyl Bromide Market Shifts & Advancements
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times for antispasmodic APIs while regulatory data integrity requirements reshape quality assurance investments.
Continuous flow chemistry for scopolamine esterification is automating temperature and pH control in quaternary ammonium synthesis, reducing batch-to-batch variability. European contract manufacturers are adopting these skid-mounted systems fastest. The technology is automating quality assurance labor previously dedicated to offline chromatographic verification.
EMA's revised guideline on elemental impurities in chemically synthesized APIs is forcing manufacturers to install ICP-MS detection capacity for heavy metal screening. Indian API exporters to European hospital pharmacies face capital equipment decisions. Injectable formulation suppliers in Italy and Spain are consolidating testing to centralized laboratories to amortize compliance costs.
Hospital group purchasing organizations in the US are consolidating antispasmodic procurement into bundled perioperative pharmaceutical contracts. Independent surgical centers are losing direct supplier relationships as integrated delivery networks centralize purchasing. This concentration is most visible in Texas and Florida ambulatory surgery markets where health system consolidation has accelerated post-IRA implementation.
Hyoscine-N-Butyl Bromide Market Segmentation
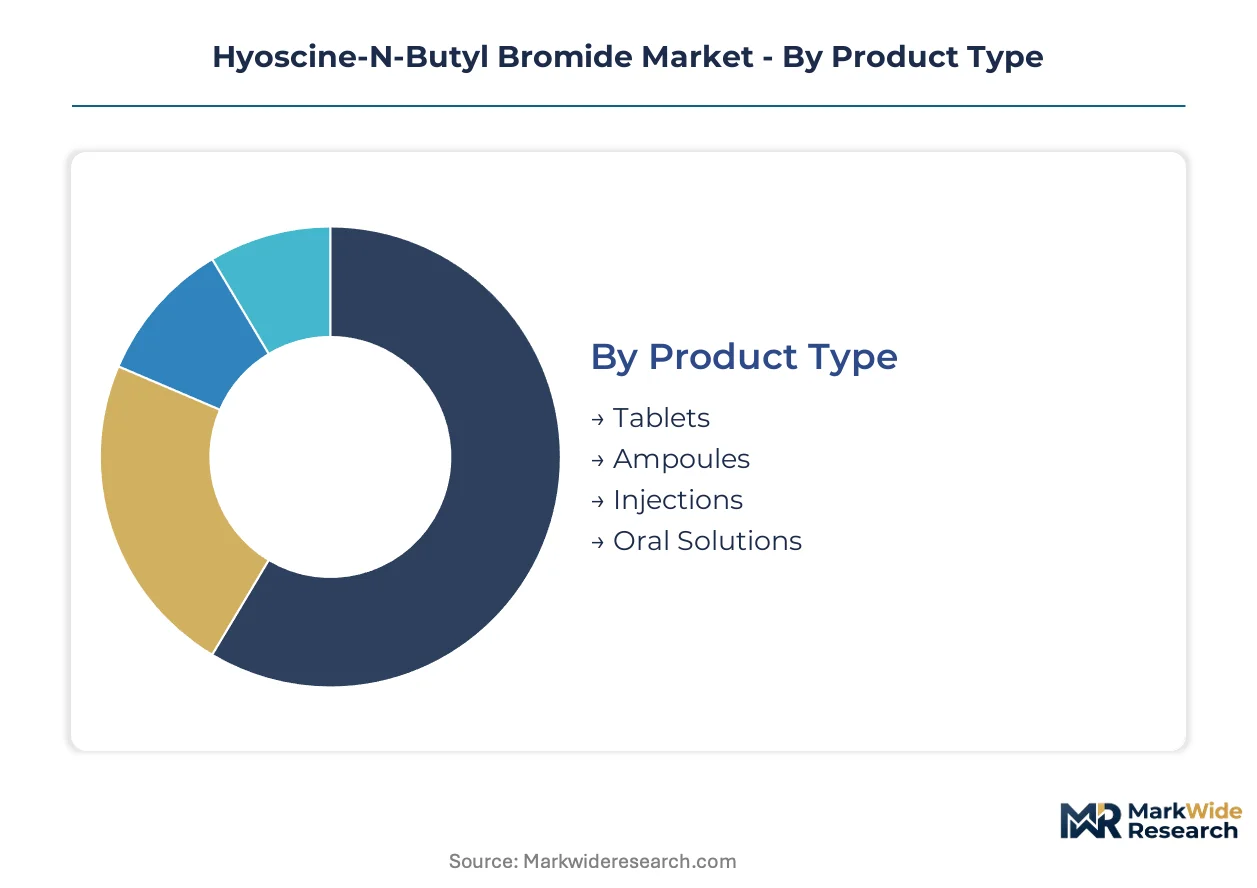
Hyoscine-N-butyl bromide demand fragments across administration routes and care settings that impose distinct technical specifications, regulatory burdens, and margin structures on manufacturers. Understanding where volume concentrates versus where premium pricing persists guides portfolio allocation between commoditized oral formats and specialized injectable lines.
Product Type:
Tablet formats dominate ambulatory volume, while ampoules and injections extract premium economics from acute care settings where rapid onset commands priority.
- Tablets:Solid oral dosage containing 10mg hyoscine-N-butyl bromide serves irritable bowel syndrome management in outpatient settings. Indian domestic manufacturers supply price-sensitive local channels alongside regulated export markets where bioequivalence documentation determines tender eligibility.
- Ampoules:Sterile glass containers holding injectable solution for perioperative spasmolysis command higher unit economics in European hospital procurement. Boehringer Ingelheim leverages heritage brand positioning to sustain premium placement against generic entrants in German and French acute care channels.
- Injections:Parenteral formulations for emergency and surgical applications require aseptic manufacturing compliance that concentrates supply among established European and Indian facilities with validated sterilization infrastructure.
- Oral Solutions:Liquid presentations for pediatric and geriatric patients unable to swallow solid dosage forms occupy niche positioning with limited competition from standardized tablet supply chains.
Mature deployment sits with tablets. Newer deployment is concentrated in ampoules as ambulatory surgical volumes expand day-case procedure requirements.
End User:
Procurement authority and reimbursement pathways separate institutional buyers from retail channels, reshaping how manufacturers configure sales coverage and pricing architecture.
- Hospitals:Integrated delivery networks in Texas and Florida consolidate antispasmodic purchasing into bundled perioperative pharmaceutical contracts, stripping independent surgical centers of direct supplier relationships.
- Clinics:Outpatient facilities in Indian urban centers are adopting telemedicine-integrated IBS management platforms that create direct-to-patient oral formulation channels bypassing traditional wholesale distribution.
- Homecare:Self-administered oral regimens for chronic functional gastrointestinal disorders concentrate demand in retail pharmacy and online channels where patient cost sensitivity shapes generic substitution patterns.
- Pharmacies:Community dispensaries remain the dominant fulfillment node for tablet formulations, though hospital pharmacy centralization is eroding their role in injectable antispasmodic access.
Institutional procurement concentrates in hospitals. Patient-directed acquisition is expanding fastest through homecare as remote diagnostic platforms proliferate.
Formulation:
Release kinetics and combination strategies differentiate margin pools, with immediate-release formats facing commoditization pressure while modified-release development absorbs R&D investment.
- Immediate Release:Rapid-disintegration tablets and standard injectable solutions face intense generic competition where FDA bioequivalence standards enable rapid therapeutic substitution.
- Extended Release:Modified-release tablet technologies represent a developing margin pool as manufacturers invest to escape immediate-release commoditization through differentiated pharmacokinetic profiles.
- Combination Formulations:Fixed-dose pairing with analgesics or antacids targets specific procedural protocols in European hospital formularies where clinical pathway standardization drives procurement decisions.
- Liquid Formulations:Oral solutions and reconstitutable suspensions serve pediatric populations and dysphagic patients with specialized stability requirements that limit competitive entry.
Immediate-release formats anchor current revenue. Extended-release development absorbs disproportionate formulation investment as manufacturers seek differentiation.
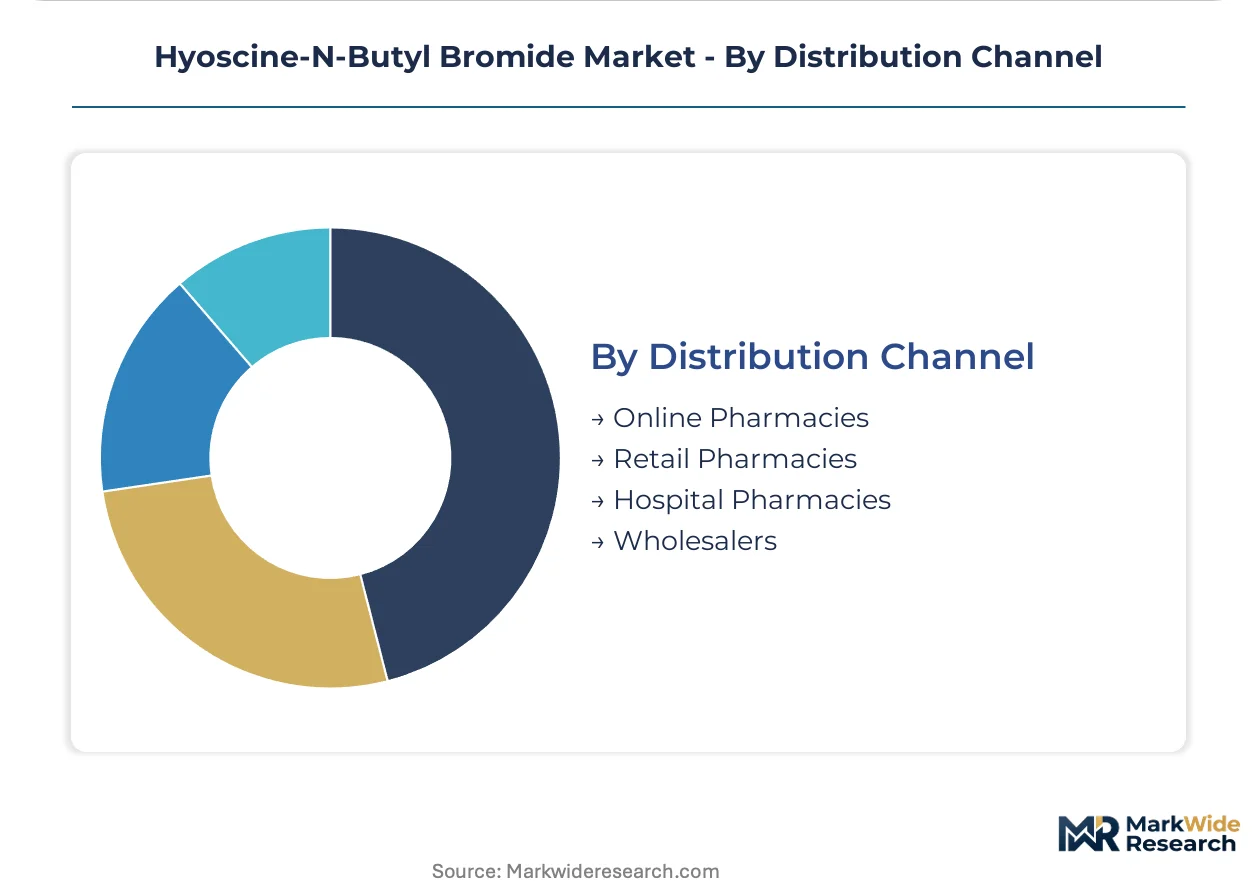
Distribution Channel:
Channel selection determines regulatory exposure and working capital intensity, with hospital direct contracting demanding specialized compliance infrastructure distinct from retail logistics.
- Online Pharmacies:E-commerce fulfillment of oral formulations is gaining share in Indian metropolitan markets where digital health platform integration enables prescription-to-delivery automation.
- Retail Pharmacies:Brick-and-mortar dispensaries remain the volume foundation for tablet distribution, though margin compression from generic substitution limits profitability.
- Hospital Pharmacies:Centralized procurement within integrated delivery networks concentrates injectable demand under group purchasing organization contracts that favor suppliers with validated cold chain and sterile manufacturing credentials.
- Wholesalers:Distributors serving fragmented retail and clinic channels absorb inventory risk and provide credit extension that manufacturers prefer to outsource in price-competitive oral segments.
Established volume flows through retail pharmacies. Digital channel development is climbing the fastest as telemedicine prescribing normalizes post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Datura stramonium cultivation clusters in Balkan agricultural zones and Indian plains anchor the botanical supply base for tropane alkaloid precursors. Hospital procurement patterns diverge sharply between mature regulated markets and price-sensitive emerging channels. Regulatory fragmentation across FDA, EMA, and CDSCO jurisdictions shapes where manufacturers concentrate formulation investment.
United States
Ambulatory surgical centers in Texas and Florida sustain injectable demand as integrated delivery networks consolidate perioperative purchasing. FDA bioequivalence requirements for generic antispasmodics compress differentiation windows for domestic formulation suppliers. Hospital group purchasing organizations in these Sun Belt states increasingly bundle antispasmodic procurement into broader pharmaceutical contracts.
Germany
European hospital pharmacy tenders favor suppliers with validated sterile manufacturing credentials for parenteral formulations. EMA quality guidelines for chemically synthesized APIs determine import acceptance criteria for non-European manufacturers. The Rhine-Ruhr industrial corridor hosts contract manufacturers adopting continuous flow chemistry for quaternary ammonium synthesis automation.
India
Domestic manufacturers supply both regulated export markets and price-sensitive local channels through divergent quality tiers. CDSCO manufacturing licensing under the PLI scheme for bulk drugs accelerates API capacity additions in Gujarat and Maharashtra. Hyderabad and Ahmedabad clusters concentrate formulation expertise for oral dosage export to African and Latin American markets.
Brazil
ANVISA registration pathways for imported injectable antispasmodics remain less contested than US or EU channels, attracting Asian API suppliers. Hospital sectors in São Paulo and Rio de Janeiro drive demand for perioperative spasmolysis as surgical volumes expand. Local distributors absorb inventory risk for foreign manufacturers navigating complex import documentation requirements.
Japan
PMDA regulatory standards for quaternary ammonium compounds maintain high barriers to generic entry in hospital channels. Aging demographics sustain demand for antispasmodic formulations in both acute and chronic gastrointestinal indications. The Kansai region around Osaka retains specialized chemical engineering talent for tropane alkaloid processing.
Hyoscine-N-Butyl Bromide Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and botanical sourcing integration. The market structure tilts toward heritage brand persistence in European hospital channels against price-driven generic substitution in retail pharmacy markets. Three archetypes dominate: integrated botanical-to-formulation operators, API-specialist exporters, and hospital-focused injectable suppliers. Capacity expansion in Indian API manufacturing and EMA certification investments for European market access represent the primary competitive vectors.
Among heritage pharmaceutical operators, Boehringer Ingelheim exemplifies sustained premium positioning through hospital channel relationships. Alkaloid Skopje occupies a distinctive position as a vertically integrated botanical cultivator controlling Datura stramonium supply security. Indian manufacturers Caleb Pharmaceuticals and Alchem International represent the API-export archetype serving price-competitive emerging markets alongside regulated channel qualification efforts.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Alkaloid Skopje |
| Caleb Pharmaceuticals |
| ALPS Pharmaceutical Ind. Co. Ltd. |
| Alchem International |
| Linnea SA |
| Biotechnica Pharma Global |
| Pfizer |
| Baxter International |
| Others |
Supply & Pricing Matrix
Quaternary ammonium synthesis expertise concentrated in legacy European and Indian facilities creates labor-cost differentials that widen pricing-tier spreads between sterile injectable and oral tablet formats. CDSCO manufacturing licensing under India's PLI scheme compresses API production costs while EMA certification investments for European hospital access sustain premium positioning for parenteral suppliers.
Pricing Analysis
Warranty and batch-certification bundling separates premium parenteral suppliers from unbundled oral tablet commodity tiers. Three-tier pricing structure across heritage-branded injectables, certified generic ampoules, and price-competitive tablets reflects quality-grade differentiation and sterilization validation levels. Cost compression in immediate-release oral segments intensifies as Indian API output expansion feeds formulation oversupply. Hospital procurement managers exhibit lowest price sensitivity for perioperative injectables where rapid onset commands clinical priority, while retail pharmacy channels show highest substitution elasticity for chronic IBS management tablets.
Supply Chain Analysis
Regional distribution centers in Ahmedabad and Hyderabad anchor hub-and-spoke patterns for oral formulation export to African and Latin American markets. API production concentrates in India, China, and select Balkan facilities where Datura stramonium cultivation feeds tropane alkaloid precursor supply. Raw material dependencies span botanical sourcing for scopolamine, n-butyl bromide for esterification, and specialized sterile packaging for injectable formats. Single-source vulnerability in captive agricultural zones creates weather-dependent supply risk for alkaloid precursors. Distribution runs through hospital group purchasing organizations in US and European acute care channels alongside fragmented wholesale networks for retail pharmacy fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chemical engineering talent scarcity props pricing for validated sterile manufacturing capacity, constraining supply expansion and sustaining margin pools for incumbent parenteral suppliers.
For Market Incumbents: Extend backward integration into Datura stramonium cultivation or secure long-term botanical supply agreements to defend against weather-driven precursor volatility. Invest in continuous flow chemistry automation at European contract manufacturing sites to compress batch cycle times and offset generic substitution pressure in injectable segments. For New Entrants and Emerging Players: Hospital distributors in Brazilian and Mexican markets offer partnership pathways into underpenetrated Latin American acute care sectors where ANVISA registration remains less contested than FDA or EMA channels. Target telemedicine-integrated clinic networks in Indian urban centers for direct-to-patient oral formulation channels that bypass traditional wholesale markups. For Investors and Strategic Acquirers: Re-rating potential sits with API-specialist exporters given CDSCO licensing acceleration and PLI scheme capacity additions serving regulated export markets. Acquisition focus should center on Indian manufacturers with simultaneous USP and EP pharmacopeial compliance infrastructure. Monitor EMA elemental impurities guideline enforcement as inflection signal for capital equipment investment cycles among European hospital pharmacy suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Automated quaternary ammonium synthesis reduces batch variability for European contract manufacturers. |
| EMA Quality Guideline Alignment | ICP-MS detection capacity installation opens German and French hospital pharmacy tenders. |
| Captive Botanical Sourcing | Backward integration into Datura stramonium cultivation secures tropane alkaloid precursor supply. |
| Telemedicine Channel Development | Direct-to-patient platforms in Indian urban centers bypass traditional wholesale distribution layers. |
| Extended-Release Formulation R&D | Modified-release tablet technologies escape immediate-release commoditization through pharmacokinetic differentiation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with API manufacturing executives, hospital procurement managers, regulatory affairs specialists, and formulary directors combined with FDA bioequivalence documentation, EMA quality guidelines, CDSCO licensing records, and Indian PLI scheme disclosures. Bottom-up volume modeling across administration routes and care settings triangulated against top-down value estimates from hospital pharmaceutical expenditure databases.
Granularity-level framing applied treatment line, dosage form, and regional regulatory cluster dimensions at the SKU level across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration. Forecast inputs incorporated ambulatory surgical volume expansion rates, CDSCO licensing velocity, and EMA elemental impurities compliance investment cycles without specifying period endpoints.
Caveats apply where pharmacopeial monograph revisions, weather events affecting Datura cultivation, or sudden regulatory enforcement shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding surgical volume growth and API capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market