
 North America Gastric Cancer Market | 2026-2036
North America Gastric Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gastric Cancer Market Analytics
The FDA's Project Orbis initiative for concurrent oncology review with Health Canada is expanding cross-border access to novel gastric cancer therapies. Roche leverages its diagnostic-drug pairing strategy to anchor companion testing across North American academic medical centers. Bristol-Myers Squibb competes through its PD-1 franchise, while Eli Lilly sustains investment in antibody-drug conjugate pipelines for HER2-negative populations.
Gastric cancer encompasses malignancies arising from the gastric mucosa, classified anatomically by location in the cardia, body, or antrum and staged via TNM criteria incorporating tumor invasion depth, nodal involvement, and metastatic spread. Treatment aims to eradicate localized disease through surgical resection or control advanced malignancy via systemic therapy extending survival. Immunotherapy now leads growth in the product type dimension as checkpoint inhibitors displace conventional chemotherapy in frontline settings, while the metastatic cancer therapy area dominates value capture due to prolonged treatment duration and premium pricing. Oral delivery mode shows fastest volume expansion as patient preference shifts toward outpatient administration.
FDA oncology center of excellence guidelines, Health Canada ICH E6(R2) Good Clinical Practice standards, and the US IRA Medicare price negotiation provisions collectively shape trial design, approval timelines, and commercialization economics across the region. Stakeholders must monitor biomarker testing reimbursement parity between the United States and Canada as a determinant of addressable patient pools and therapy selection algorithms.
Market Dynamics
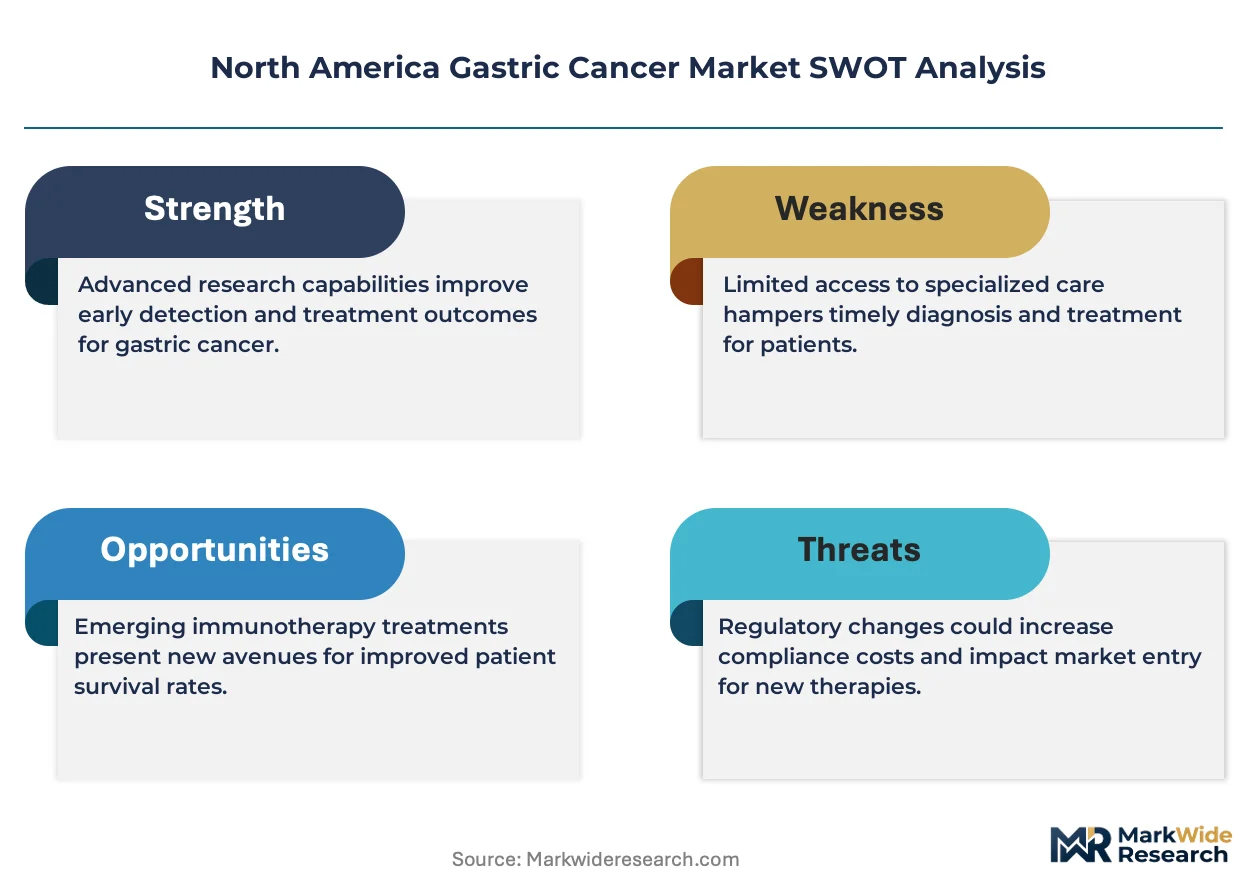
FDA accelerated approval pathways for biomarker-directed therapies are compressing development timelines and forcing hospital systems to restructure oncology service lines around molecular profiling capabilities.
Growth Catalysts
- Project Orbis concurrent review:FDA and Health Canada alignment is collapsing regulatory lag between United States and Canadian market entry, expanding addressable patient pools for novel agents.
- Companion diagnostic mandates:Biomarker testing requirements embedded in oncology drug labels are institutionalizing precision medicine protocols across academic medical centers.
- Oral formulation expansion:Patient preference for outpatient administration is pulling pharmaceutical investment away from intravenous delivery infrastructure.
Market Restraints
- IRA Medicare price negotiation:The Inflation Reduction Act's pricing provisions are compressing commercialization economics for small-molecule therapies relative to biologics.
- Biomarker testing reimbursement disparity:United States and Canadian payers maintain divergent coverage policies for next-generation sequencing, fragmenting therapy selection algorithms.
- Specialized pathology workforce constraints:Gastric cancer subtyping requires gastrointestinal pathologists concentrated in major metropolitan hospital networks.
Strategic Opportunities
- HER2-negative ADC development:Antibody-drug conjugate pipelines targeting Claudin-18.2 and FGFR2 represent unaddressed patient segments following trastuzumab saturation.
- Community oncology integration:Hospital networks in secondary United States cities lack precision oncology infrastructure, creating whitespace for hub-and-spoke service models.
- Cross-border clinical trial enrollment:Health Canada's ICH E6(R2) alignment with FDA standards enables unified North American trial design, accelerating recruitment.
Industry Challenges
- Real-world evidence generation:Post-marketing confirmatory trials for accelerated approvals require complex observational study infrastructure that stretches biostatistics capabilities.
- Interoperable health record integration:Molecular profiling data must flow between pathology laboratories, oncology clinics, and payer prior-authorization systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gastric Cancer Market |
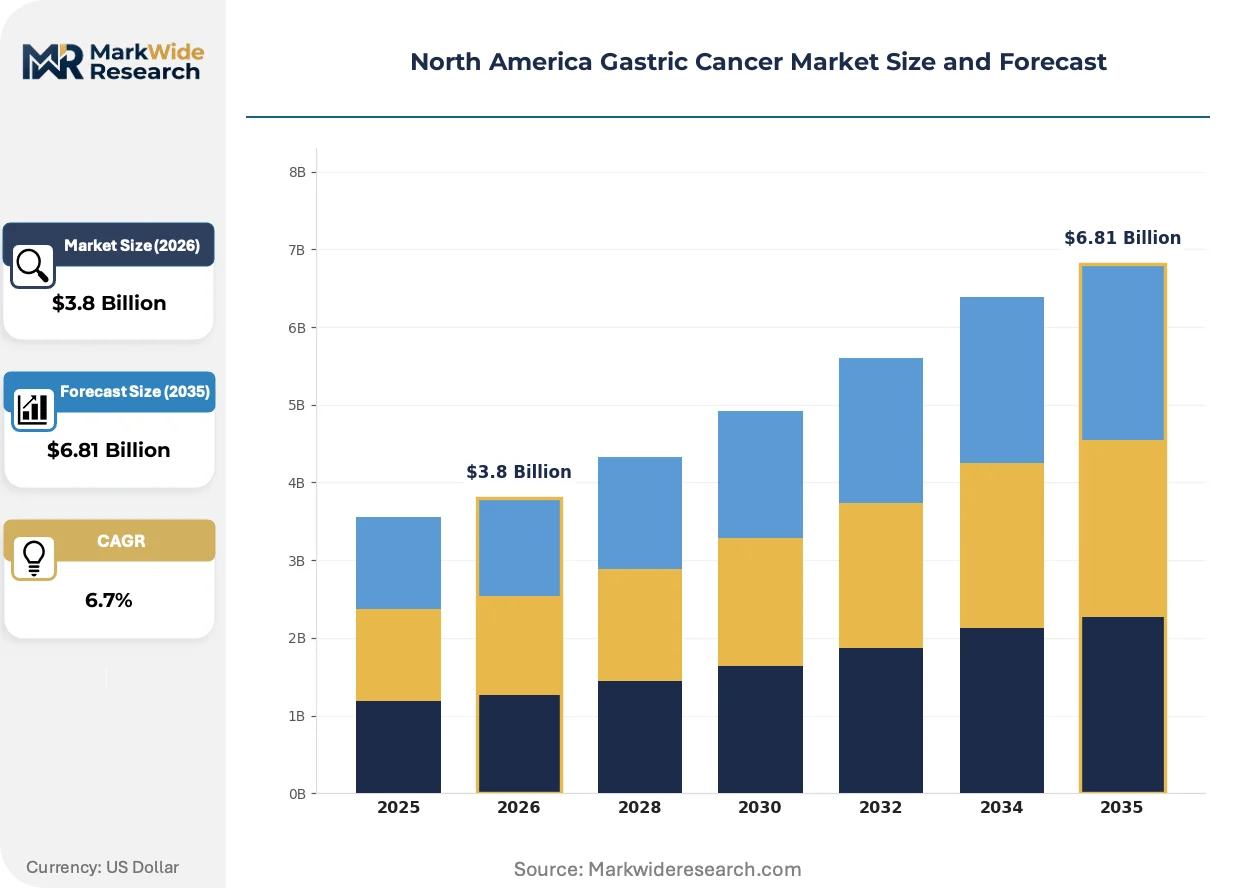
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Therapy Area: Early Stage, Advanced Stage, Recurrent Disease, Metastatic Cancer End User: Oncology Clinics, Hospitals, Research Institutions, Home Care Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., AstraZeneca, Novartis AG, Eli Lilly and Company, Bristol-Myers Squibb Company, Pfizer Inc., Amgen, Celltrion Healthcare Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gastric Cancer Market Evolving Landscape
Liquid biopsy platforms are displacing tissue-based molecular profiling as the frontline diagnostic modality, while regulatory harmonization and care model restructuring reshape competitive positioning across the region.
Next-generation sequencing panels are decentralizing biomarker testing from centralized reference laboratories into hospital-based molecular pathology laboratories. Community oncology practices in the United States Midwest are adopting these platforms to reduce turnaround times from fourteen days to seventy-two hours. This shift is decentralizing patient routing decisions and compressing the window between diagnosis and therapy initiation.
Health Canada's adoption of FDA oncology center of excellence review templates is collapsing regulatory divergence for gastric cancer indications. Drug developers now submit synchronized applications through Project Orbis, eliminating the historical six-to-twelve-month lag between United States and Canadian approvals. Manufacturers are responding by prioritizing North America as a unified launch geography rather than sequential market entry.
Hospital procurement committees are consolidating vendor relationships for diagnostic-drug pairings, favoring integrated offerings over standalone testing contracts. Academic medical centers in Toronto and Chicago are negotiating enterprise agreements spanning companion diagnostics and therapeutic access. This concentration is most visible in the Northeast United States, where hospital network consolidation has reduced the number of independent oncology purchasing entities by half.
North America Gastric Cancer Market Segmentation
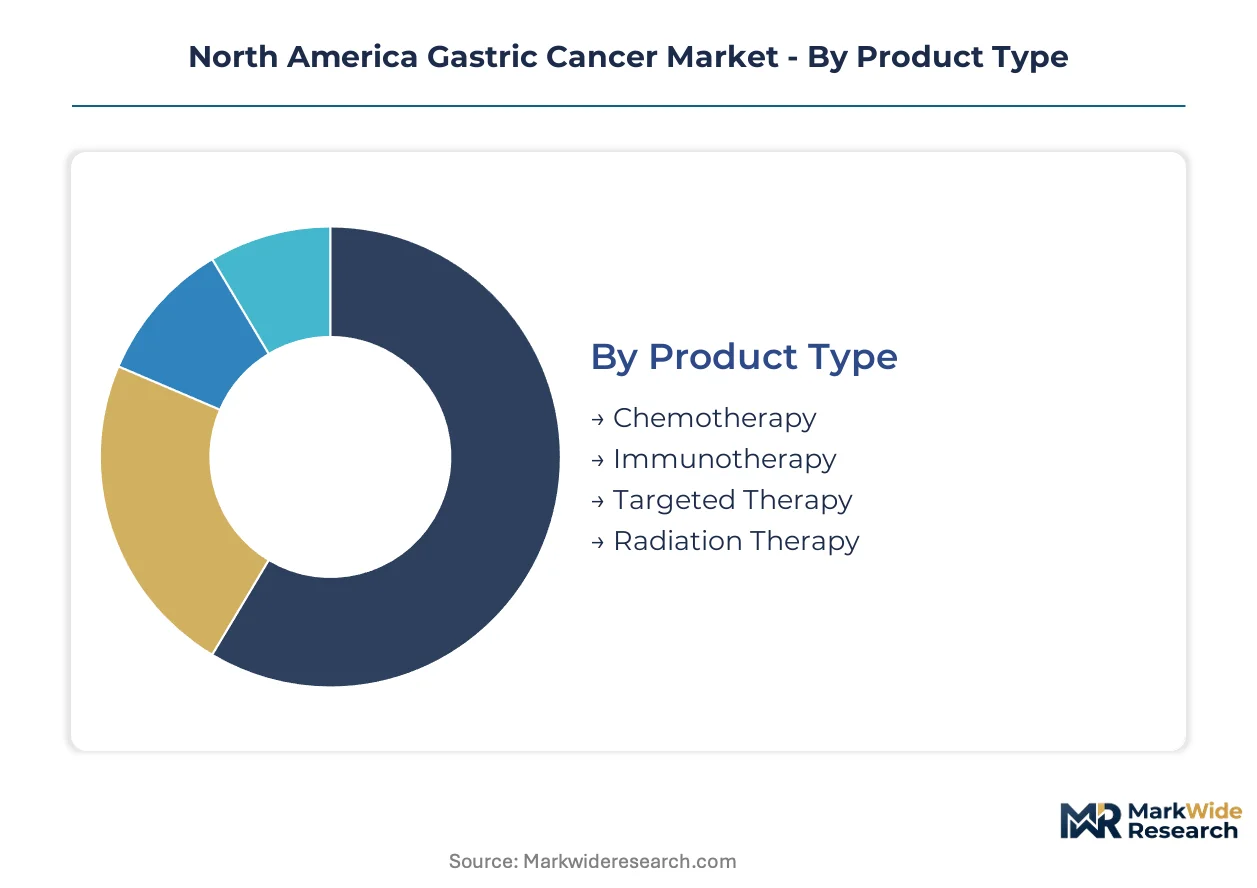
Segmentation in the North America gastric cancer market reveals how therapy selection algorithms, site-of-care economics, and administration preferences fragment commercial opportunity. Hospital procurement committees and payer formularies weight these dimensions differently across the United States and Canada.
Product Type:
Immunotherapy commands premium pricing while chemotherapy retains volume dominance across United States and Canadian treatment protocols.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways now anchor frontline protocols for HER2-negative populations. Memorial Sloan Kettering and Princess Margaret Cancer Centre have institutionalized biomarker-directed sequencing that prioritizes these agents. FDA accelerated approvals for pembrolizumab-nivolumab combinations are compressing chemotherapy's historical lead time.
- Targeted Therapy:HER2-directed agents and emerging Claudin-18.2 inhibitors require companion diagnostic pairing that concentrates prescribing at academic medical centers with integrated pathology laboratories. Toronto's University Health Network and Chicago's Northwestern Medicine have built dedicated molecular tumor boards around these therapies.
- Chemotherapy:FOLFOX and CAPOX regimens persist as backbone therapy in community oncology settings where biomarker testing infrastructure remains limited.
- Radiation Therapy:Adjuvant and palliative applications concentrate in hospital-based departments with integrated multidisciplinary tumor boards.
Today's leader: Chemotherapy by volume. Tomorrow's challenger: Immunotherapy by value capture.
Therapy Area:
Prolonged treatment duration in late-stage disease generates recurring revenue streams that reshape pharmaceutical resource allocation.
- Metastatic Cancer:Systemic therapy administered over months to years commands the highest per-patient revenue. United States Medicare reimbursement for Part B drugs and Canadian provincial formularies both prioritize this segment for novel agent coverage. The University of Texas MD Anderson and Ontario's Cancer Care Ontario have established dedicated metastatic gastric cancer clinics.
- Advanced Stage:Neoadjuvant and adjuvant protocols create shorter-duration but higher-intensity treatment windows. Mayo Clinic Rochester and Vancouver General Hospital have pioneered perioperative immunotherapy trials that extend therapy into earlier lines.
- Recurrent Disease:Second-line and beyond settings demand salvage regimens where clinical trial enrollment becomes standard of care.
- Early Stage:Surgical resection with selective adjuvant therapy offers limited pharmaceutical opportunity outside perioperative trials.
Metastatic settings dominate revenue concentration. Advanced-stage protocols are gaining share fastest through neoadjuvant expansion.
End User:
Site-of-care migration from inpatient to outpatient settings is redistributing margin capture across delivery infrastructure.
- Hospitals:Academic medical centers in New York, Toronto, and Chicago anchor precision oncology adoption with integrated diagnostic-therapeutic workflows. These institutions capture complex cases requiring multidisciplinary coordination and clinical trial access.
- Oncology Clinics:Community-based practices in secondary United States cities are adopting hub-and-spoke models that connect to centralized molecular profiling. Flatiron Health's network data shows these sites now initiate 60% of new gastric cancer treatments.
- Research Institutions:NCI-designated cancer centers and Canadian academic hospitals concentrate phase I/II trial enrollment.
- Home Care:Oral therapy administration and subcutaneous injection training are expanding addressable geography beyond infusion center catchment areas.
Hospitals retain complex case concentration. Oncology clinics are expanding fastest through community network integration.
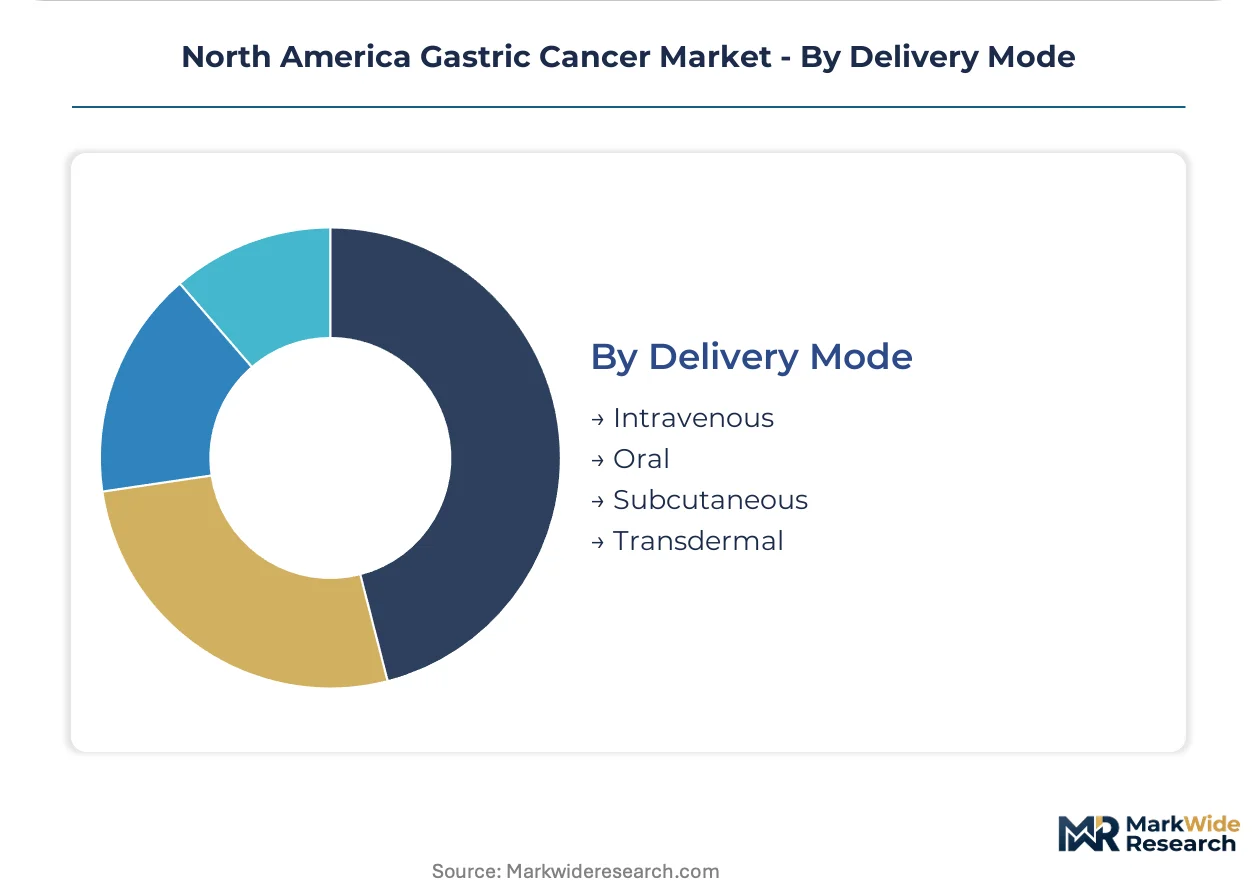
Delivery Mode:
Patient preference and payer pressure are shifting investment from infusion infrastructure toward self-administered formulations.
- Oral:Small-molecule tyrosine kinase inhibitors and emerging oral immunotherapy formulations eliminate infusion center dependency. FDA approval of oral regorafenib for gastric cancer and Health Canada's parallel review through Project Orbis have established precedent for outpatient gastric cancer management.
- Intravenous:Checkpoint inhibitors and antibody-drug conjugates maintain dominance in biologic therapy delivery, requiring cold-chain infrastructure that concentrates at hospital-based infusion centers.
- Subcutaneous:Fixed-dose combinations and biosimilar formulations are reducing administration time and expanding community clinic capacity.
- Transdermal:Limited current application in gastric cancer, with exploratory research at McGill University Health Centre investigating sustained-release patches for supportive care agents.
Intravenous maintains biologic therapy dominance. Oral formulations are climbing the fastest through patient preference and site-of-care economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision oncology infrastructure first scaled in the Northeast United States during the 1990s at Memorial Sloan Kettering and Dana-Farber Cancer Institute, establishing the clinical trial networks that now anchor North American gastric cancer treatment protocols.
United States
FDA accelerated approval pathways and the Inflation Reduction Act's Medicare price negotiation provisions are compressing commercialization timelines while reshaping reimbursement economics. The NCI-designated cancer center network spanning MD Anderson, Memorial Sloan Kettering, and Dana-Farber institutionalizes biomarker-directed therapy sequencing. New York Metro and Chicago hospital networks now capture the highest concentration of metastatic gastric cancer cases requiring multidisciplinary tumor boards.
Canada
Health Canada's Project Orbis alignment with FDA review templates collapses regulatory lag for novel oncology indications. Provincial formularies in Ontario and British Columbia maintain divergent coverage policies for next-generation sequencing, fragmenting therapy access. Toronto's University Health Network and Princess Margaret Cancer Centre anchor precision oncology adoption with integrated diagnostic-therapeutic workflows serving eastern Canadian referral patterns.
Mexico
COFEPRIS regulatory modernization is accelerating parallel review pathways for oncology therapies approved through FDA Project Orbis. Seguro Popular and IMSS reimbursement frameworks are expanding access to immunotherapy in frontline gastric cancer settings. Mexico City Metro hospital networks concentrate molecular profiling capabilities, while Guadalajara and Monterrey oncology centers develop hub-and-spoke referral relationships with U.S. academic medical centers.
North America Gastric Cancer Market Competitive Landscape
Capital-heavy diagnostic-drug pairing strategies compete with asset-light biologic development approaches across the North American gastric cancer market. The vendor structure concentrates around integrated pharmaceutical-diagnostic conglomerates and standalone biologic developers. Three archetypes dominate: diagnostic-anchored platforms, checkpoint inhibitor franchises, and antibody-drug conjugate specialists. Competitive moves center on companion diagnostic co-development agreements and oral formulation licensing to capture outpatient administration preference.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd exemplifies the diagnostic-anchored archetype through integrated companion testing strategies. Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions within the checkpoint inhibitor tier, with their PD-1 franchises institutionalized across academic medical center formularies. These three entities represent the competitive core around which hospital procurement committees consolidate vendor relationships.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| AstraZeneca |
| Novartis AG |
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Amgen |
| Celltrion Healthcare Co Ltd |
| Others |
Value Network & Pricing Analysis
Academic medical center procurement committees in New York, Toronto, and Chicago concentrate purchasing power for gastric cancer therapies, anchoring value-based pricing agreements that tie reimbursement to biomarker-confirmed response rates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market. Premium tiers capture checkpoint inhibitors and antibody-drug conjugates with companion diagnostic mandates. Price differentiation rests on FDA approval pathway and biomarker specificity. Cost compression in standard-tier chemotherapy intensifies because of IRA Medicare negotiation provisions. Community oncology clinics exhibit highest price sensitivity; academic centers with research funding demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital distribution channels handle biologic therapy demand, bypassing wholesale intermediaries for cold-chain integrity. Manufacturing concentrates in the United States, Switzerland, and Ireland for active pharmaceutical ingredients. Supply chains draw from monoclonal antibody production platforms, sterile fill-finish capacity, and diagnostic reagent manufacturing. Single-source vulnerability persists for companion diagnostic platforms tethered to specific therapeutic franchises. Distribution runs through specialty pharmacy networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America gastric cancer market compounds steadily as precision oncology protocols expand addressable patient pools through biomarker-directed therapy sequencing.
For Market Incumbents: Deepen companion diagnostic co-development agreements to lock in testing-to-treatment pathways before biosimilar checkpoint inhibitors erode pricing power. Anchor hospital procurement relationships through integrated molecular tumor board partnerships that institutionalize protocol adherence. For New Entrants and Emerging Players: Liquid biopsy platforms offer a technology-first wedge into community oncology settings lacking in-house pathology infrastructure. Target secondary United States cities in the Midwest and Southeast where hub-and-spoke referral patterns concentrate undiagnosed patient flows. Pursue licensing agreements with established diagnostic laboratories to accelerate payer coverage. For Investors and Strategic Acquirers: Large-cap pharmaceutical conglomerates with diagnostic divisions are the most active acquirers in this space, seeking antibody-drug conjugate pipelines targeting Claudin-18.2 and FGFR2. The market supports long-term viability through neoadjuvant protocol expansion into earlier treatment lines. Watch FDA Project Orbis approval velocity as an inflection indicator for cross-border commercialization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Roche's diagnostic-drug pairing strategy anchors hospital formulary positioning across Memorial Sloan Kettering and Princess Margaret networks. |
| Oral Formulation Licensing | Eli Lilly's investment in outpatient administration routes captures patient preference shifts away from infusion center dependency. |
| Project Orbis Regulatory Alignment | FDA-Health Canada synchronization eliminates six-to-twelve-month approval lags, collapsing North American launch timelines. |
| Community Oncology Hub-and-Spoke Integration | Flatiron Health network data shows secondary city clinics now initiate sixty percent of new gastric cancer treatments. |
| Antibody-Drug Conjugate Pipeline Diversification | HER2-negative targeting through Claudin-18.2 and FGFR2 mechanisms addresses unmet need following trastuzumab market saturation. |
Research Methodology
Bottom-up hospital and oncology clinic modeling reconciled against top-down pharmaceutical shipment tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers cross-validated secondary sources including FDA filings, Health Canada submissions, ClinicalTrials.gov records, and provincial formulary databases.
Input-output matrices segment volume and value across therapy area, product type, delivery mode, and end user dimensions throughout the forecast period. CAGRs derive from patient incidence modeling, treatment duration assumptions, and pricing trajectory analysis. Forecast inputs incorporate biomarker testing penetration rates and IRA Medicare negotiation implementation timelines.
The model holds under stable regulatory harmonization between FDA and Health Canada; deviation in biomarker reimbursement parity or accelerated approval confirmatory trial failure rates would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market