
 Esophageal Atresia Treatment Market | 2026-2036
Esophageal Atresia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Esophageal Atresia Treatment Market Foresight
Buyer concentration among pediatric tertiary hospitals is recalibrating procurement patterns across the esophageal atresia treatment landscape. Medtronic Plc leverages its broad surgical portfolio to maintain supply relationships with high-volume neonatal centers. Cook Medical LLC anchors its position through specialized enteral feeding devices tailored to postoperative esophageal reconstruction. Boston Scientific Corporation competes via endoscopic platforms that support minimally invasive approaches in pediatric anatomy.
Esophageal atresia treatment encompasses surgical correction, endoscopic intervention, device-assisted anastomosis, and nutritional management for congenital discontinuity of the esophagus, typically requiring primary repair with or without tracheoesophageal fistula ligation within 72 hours of birth. The procedure demands microsurgical precision given neonatal tissue fragility and the frequent association with VACTERL syndrome comorbidities. Surgical intervention and medical devices command the dominant share of current revenue, reflecting the irreplaceable role of operative repair and the recurring need for replacement stents and feeding tubes. Endoscopic procedures represent the fastest-expanding category as thoracoscopic and robotic-assisted techniques diffuse from academic centers to regional children's hospitals, though nutritional support retains durable margin pools through long-term enteral dependency in complex cases.
The FDA's Humanitarian Device Exemption pathway and the European Medicines Agency's pediatric investigation plans jointly shape development incentives and market access conditions for congenital anomaly technologies. ISO 13485 quality management standards and the EU Medical Device Regulation impose manufacturing rigor that filters out undercapitalized entrants. Stakeholders must monitor how reimbursement alignment between neonatal DRG codes and prolonged ICU stays influences hospital willingness to adopt premium technologies.
Market Dynamics
Thoracoscopic repair platforms are compressing operative timelines for neonatal esophageal reconstruction, forcing device manufacturers to recalibrate training and service models around single-incision workflows.
Growth Catalysts
- FDA Pediatric Device Consortia:The pathway accelerates premarket review for congenital anomaly technologies, reducing time-to-revenue for anastomotic device developers targeting neonatal populations.
- Neonatal ICU bed expansion:Tertiary hospitals in the United States are adding dedicated congenital surgery units, creating captive demand for minimally invasive repair instruments.
- Tracheoesophageal fistula ligation:Advances in simultaneous airway-esophageal repair are expanding the addressable surgical population beyond isolated atresia cases.
Market Restraints
- Silicone stent raw material concentration:Medical-grade silicone supply clusters among three specialty chemical producers in Germany and Japan, exposing device makers to input bottlenecks.
- EU MDR recertification burden:The Medical Device Regulation's enhanced clinical evidence requirements are delaying market entry for legacy enteral feeding tube portfolios.
- Open thoracotomy persistence:Low-resource surgical centers in rural India and Brazil continue relying on conventional repair techniques, limiting premium device penetration.
Strategic Opportunities
- Robotic-assisted neonatal surgery:Convergence of miniaturized robotic arms with 3mm instrument channels is expanding into academic medical centers seeking to differentiate pediatric surgical programs.
- Home enteral nutrition services:Post-discharge feeding tube management represents an underpenetrated channel, with third-party suppliers capturing recurring revenue from complex VACTERL cases.
- Japanese pediatric surgical robotics:METI's healthcare technology adoption subsidies are creating regulatory tailwinds for manufacturers establishing presence in Asia-Pacific neonatal centers.
Industry Challenges
- Pediatric microsurgical training pipelines:Fellowship programs produce fewer than 50 congenital esophageal surgeons annually in the United States, constraining procedure volume growth.
- ISO 13485 quality system capex:Small device developers face capital intensity from cleanroom manufacturing requirements for neonatal-scale instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophageal Atresia Treatment Market |
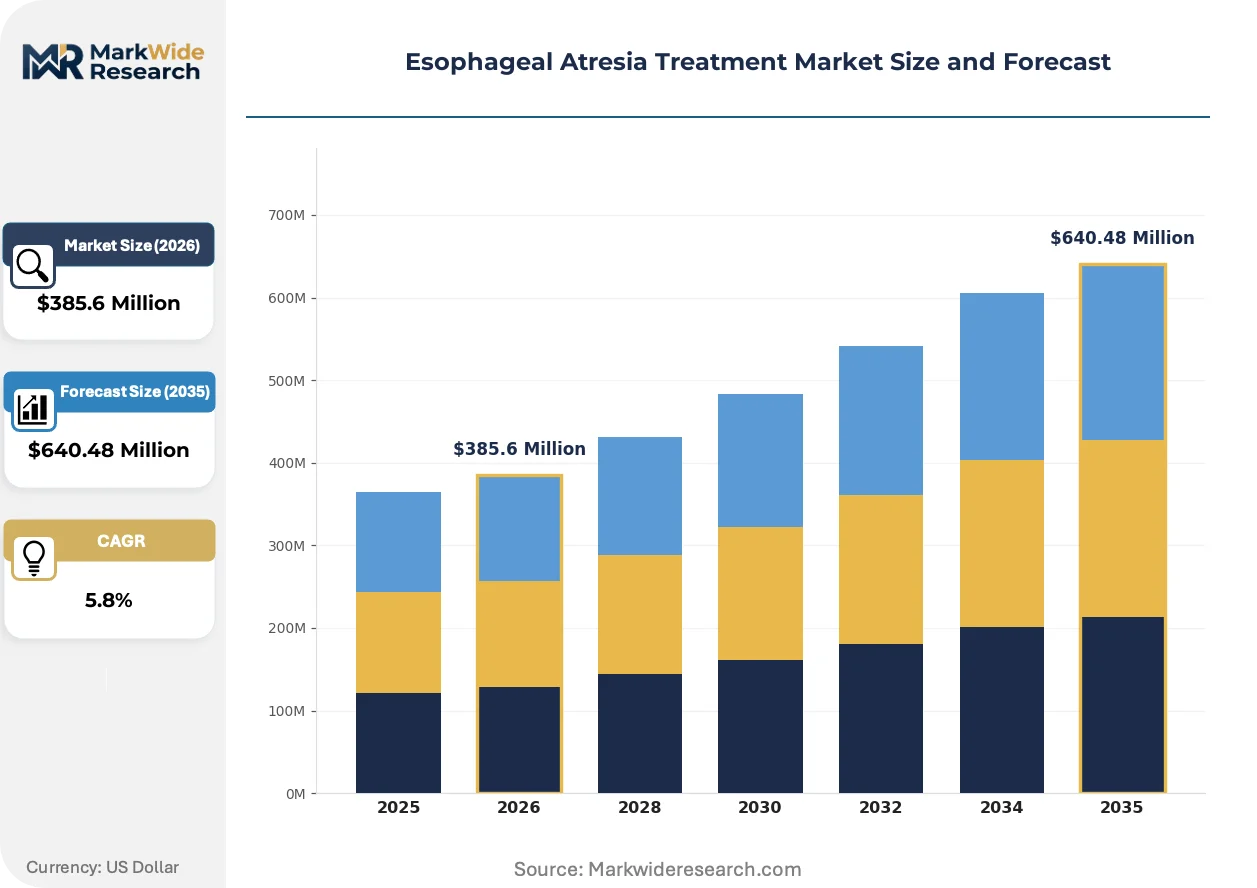
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Intervention, Endoscopic Procedures, Medical Devices, Nutritional Support Delivery Mode: Hospital, Outpatient Clinic, Home Care, Telehealth Services Age Group: Infants, Children, Adolescents, Adults Therapy Area: Cardiovascular, Gastrointestinal, Respiratory, Others |
| Companies Covered | Teleflex Incorporated, Johnson & Johnson, Cook Medical LLC, Taewoong Medical, Applied Medical Resources Corporation, Medtronic Plc, Olympus Corporation, Harvard Apparatus Regenerative Technology, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophageal Atresia Treatment Market Shifts & Advancements
Neonatal surgical practice is pivoting toward single-incision thoracoscopic platforms, compressing recovery timelines and redefing device form-factor requirements across the treatment pathway.
Magnetic compression anastomosis is expanding into high-volume pediatric centers as an alternative to traditional sutured repair. The technique employs paired magnetic stents to achieve esophageal continuity without open thoracotomy. Cincinnati Children's Hospital and Great Ormond Street Hospital have established dedicated programs, compressing operative time and reducing ventilator dependence in preterm infants.
The FDA's Humanitarian Device Exemption pathway is reshaping commercialization economics for ultra-orphan neonatal devices. Manufacturers can now secure market access with smaller clinical cohorts, though post-market surveillance obligations have tightened. European developers are responding by bifurcating regulatory strategies, prioritizing US entry before tackling EMA pediatric investigation plans.
Hospital purchasing committees are consolidating vendor relationships around full-procedure bundles rather than discrete device procurement. Children's Hospital of Philadelphia and Texas Children's have moved to single-source contracts covering thoracoscopes, anastomotic devices, and postoperative stents. This behavioral shift is most visible in US academic medical centers, where supply chain rationalization now overrides individual surgeon preference.
Esophageal Atresia Treatment Market Segmentation
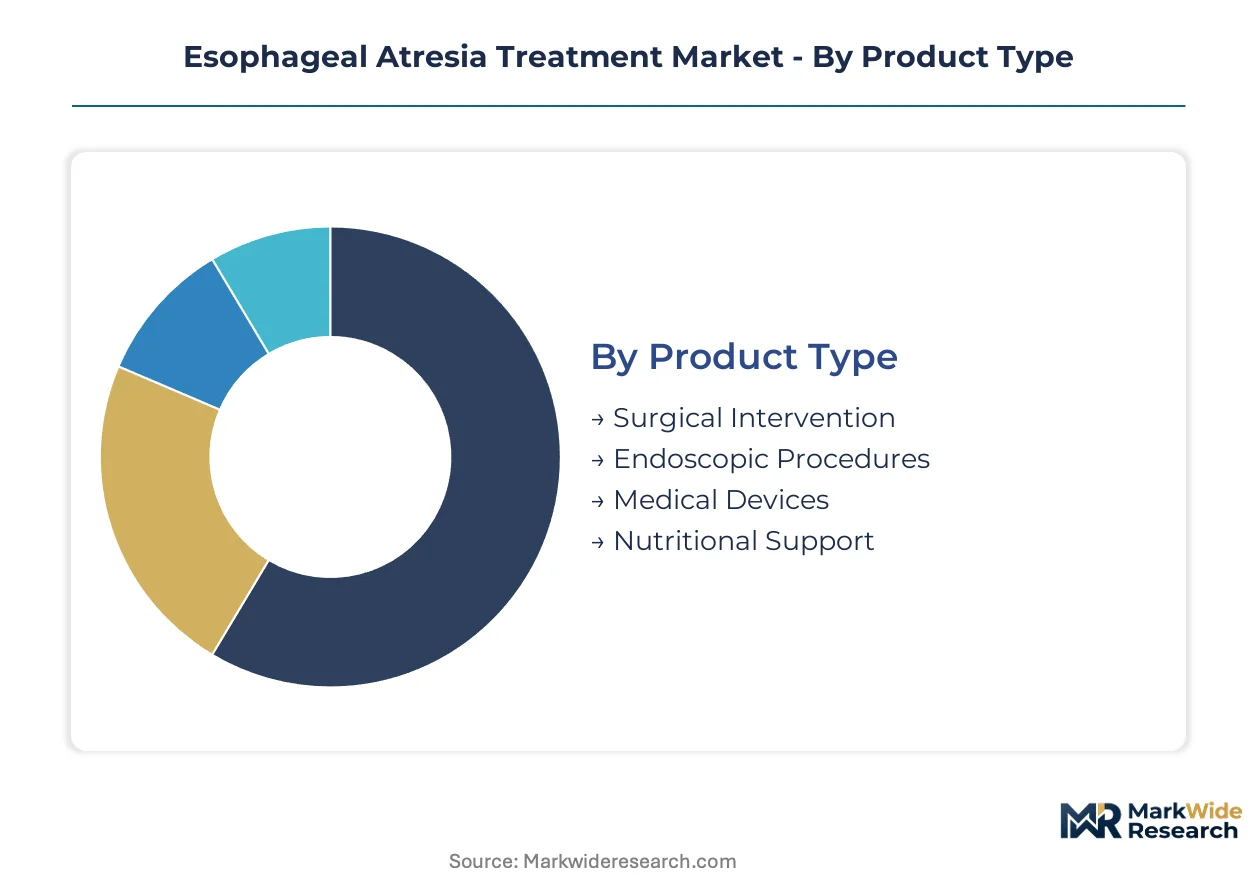
Treatment modality selection for esophageal atresia hinges on anatomical classification, birth weight thresholds, and associated VACTERL anomalies. Segmentation reveals how neonatal surgical centers allocate capital across operative platforms, postoperative support systems, and long-term nutritional infrastructure.
Product Type:
Technology sophistication separates segments with acute surgical requirements from those supporting chronic management.
- Surgical Intervention:Open thoracotomy and thoracoscopic repair constitute the definitive treatment, with primary anastomosis performed within 72 hours of birth. Tertiary pediatric centers in the United States concentrate demand here, driven by expanding NICU capacity and fellowship-trained congenital surgeons. Magnetic compression anastomosis is gaining traction at Cincinnati Children's Hospital and Great Ormond Street Hospital as a suture-sparing alternative.
- Endoscopic Procedures:Thoracoscopic platforms with 3mm instrument channels enable single-incision reconstruction in preterm infants. Academic medical centers in Japan and Germany are deploying these systems fastest, supported by METI healthcare subsidies and EU MDR fast-track pathways for pediatric innovation.
- Medical Devices:Anastomotic stents, feeding tubes, and tracheoesophageal fistula occlusion devices address immediate postoperative maintenance.
- Nutritional Support:Enteral feeding formulations and gastrostomy tube systems manage the prolonged esophageal dysmotility common in complex repairs.
Mature deployment sits with Surgical Intervention. Newer deployment is concentrated in Endoscopic Procedures.
Delivery Mode:
Site-of-care economics reshape procurement patterns across the treatment continuum.
- Hospital:Neonatal intensive care units and dedicated congenital surgery wards handle acute repair and immediate stabilization. Children's Hospital of Philadelphia and Texas Children's have consolidated vendor contracts around full-procedure bundles covering operative instruments and postoperative devices.
- Home Care:Post-discharge enteral feeding tube management and stent replacement cycles generate recurring revenue. Third-party suppliers are capturing this channel in complex VACTERL cases requiring multiyear nutritional support.
- Outpatient Clinic:Follow-up anastomotic dilation and endoscopic surveillance occur at interval schedules.
- Telehealth Services:Remote feeding consultation and parental training expand access for rural populations.
Acute care concentration remains with Hospital settings. Home Care represents the steepest expansion trajectory as payors push for earlier discharge.
Age Group:
Physiological maturity dictates repair complexity and device sizing requirements.
- Infants:Neonates under 30 days constitute the primary surgical population, with repair timing contingent on birth weight and pulmonary maturity. Preterm infants below 1500g require staged procedures with delayed primary anastomosis.
- Children:Delayed diagnosis cases and revision surgeries for anastomotic stricture fall into this category.
- Adolescents:Long-term esophageal dysmotility and gastroesophageal reflux disease management dominate.
- Adults:Historical repair patients require surveillance for anastomotic malignancy risk.
Procedure volume concentrates in Infants. Revision burden is shifting toward Children.
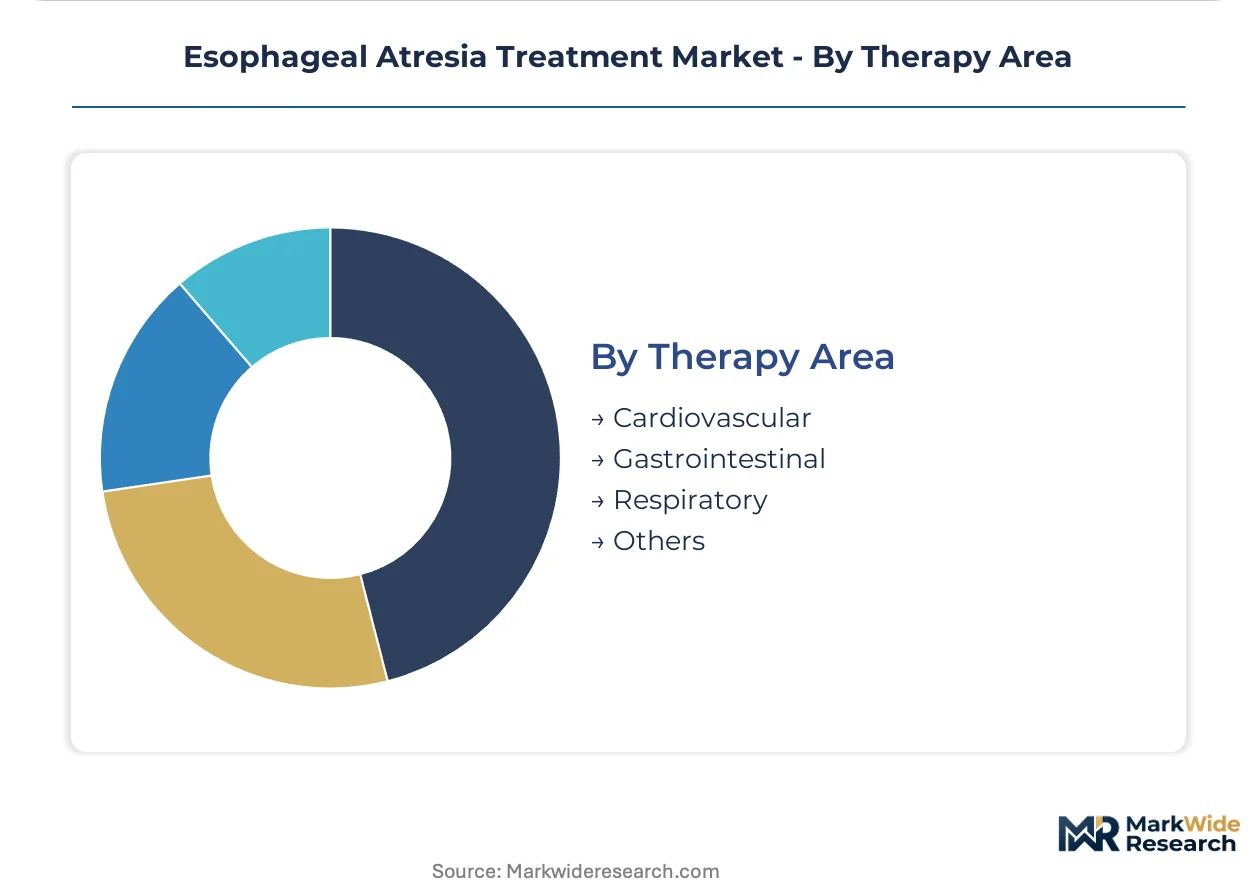
Therapy Area:
Comorbidity profiles determine multidisciplinary resource allocation.
- Gastrointestinal:Primary esophageal reconstruction and postoperative motility disorders command the central clinical focus.
- Respiratory:Tracheoesophageal fistula ligation and subsequent airway management require concurrent thoracic surgery expertise.
- Cardiovascular:VACTERL-associated cardiac defects necessitate staged or simultaneous intervention.
- Others:Renal and limb anomalies in the VACTERL spectrum trigger nephrology and orthopedic consultations.
Core investment sits with Gastrointestinal. Respiratory integration is deepening fastest as simultaneous airway-esophageal repair protocols diffuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric tertiary hospitals in the United States concentrate the highest procedure volumes for neonatal esophageal reconstruction. Academic medical centers in Boston, Philadelphia, and Houston anchor specialized congenital surgery networks that drive procurement of minimally invasive repair platforms.
United States
Children's Hospital of Philadelphia and Texas Children's Hospital have consolidated vendor contracts around full-procedure bundles covering thoracoscopes and anastomotic devices. The FDA's Humanitarian Device Exemption pathway accelerates premarket review for congenital anomaly technologies. Cincinnati Children's Hospital has established a dedicated magnetic compression anastomosis program, compressing operative time for preterm infants.
Germany
Academic centers in Heidelberg and Berlin deploy thoracoscopic platforms with 3mm instrument channels for single-incision reconstruction. The EU Medical Device Regulation's fast-track pathway for pediatric innovation supports faster market entry for neonatal-scale instruments. Medical-grade silicone supply from specialty chemical producers in the Rhine-Ruhr region feeds device manufacturing clusters.
Japan
METI healthcare technology adoption subsidies are creating regulatory tailwinds for manufacturers establishing presence in Asia-Pacific neonatal centers. National centers in Tokyo and Osaka are deploying miniaturized robotic arms with 3mm instrument channels. The PMDA's streamlined review for pediatric devices aligns with government priorities to reduce infant mortality from congenital anomalies.
United Kingdom
Great Ormond Street Hospital has established a dedicated magnetic compression anastomosis program as an alternative to traditional sutured repair. The EMA's pediatric investigation plans shape development incentives for congenital anomaly technologies. London-based academic medical centers cluster specialized pediatric surgical expertise that attracts complex VACTERL cases from across Europe.
India
Low-resource surgical centers in rural regions continue relying on conventional open thoracotomy techniques, limiting premium device penetration. The CDSCO's regulatory framework for pediatric devices remains under development compared to Western markets. Tertiary hospitals in Delhi and Mumbai are gradually adopting thoracoscopic repair platforms through academic partnerships with US congenital surgery programs.
Esophageal Atresia Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue robotic-assisted and magnetic anastomosis technologies. The market structures around three archetypes: diversified surgical portfolio holders, specialized enteral feeding device makers, and endoscopic platform specialists. Consolidation pressure intensifies as hospital purchasing committees demand full-procedure bundles rather than discrete device procurement. Competitive moves center on single-source contract capture and training-and-service model recalibration around single-incision workflows.
Within the diversified surgical portfolio tier, Medtronic Plc and Johnson & Johnson occupy positions anchored by broad supply relationships with high-volume neonatal centers. Cook Medical LLC exemplifies the specialized enteral feeding device archetype, with its LLC structure indicating US-based organization. Boston Scientific Corporation represents the endoscopic platform specialist tier, competing through minimally invasive technologies. Olympus Corporation, with its corporate suffix indicating Japanese origin, sits within the visualization and surgical instrument segment.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Johnson & Johnson |
| Cook Medical LLC |
| Taewoong Medical |
| Applied Medical Resources Corporation |
| Medtronic Plc |
| Olympus Corporation |
| Harvard Apparatus Regenerative Technology |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Medical-grade silicone feedstock originating from specialty chemical producers in Germany and Japan flows through three pricing tiers before reaching neonatal surgical centers, with raw material concentration upstream translating into premium capture for anastomotic device manufacturers and cost compression pressure on enteral feeding tube suppliers.
Pricing Analysis
Volume concentration in standard enteral feeding tubes competes with margin pools in magnetic anastomosis systems and robotic-assisted platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA Humanitarian Device Exemption-tier innovations from ISO 13485-certified conventional instruments and unbranded emerging-market alternatives. Pricing pressure stems from hospital purchasing committees consolidating around single-source contracts covering full-procedure bundles. Community hospitals and rural surgical centers exhibit highest price sensitivity, while academic medical centers in Boston and Philadelphia prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Domestic-content mandates under the FDA's pediatric device consortia pathway are reshaping sourcing patterns for congenital anomaly technologies, incentivizing US-based cleanroom manufacturing for neonatal-scale instruments. Medical-grade silicone production clusters in Germany and Japan, with secondary molding capacity in the United States and China. Supply chain risk centers on single-source vulnerability for specialty polymer feedstock from Rhine-Ruhr chemical producers. Distribution runs through GPO contracts with tertiary pediatric hospitals, bypassing traditional distributor markups for high-volume academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained congenital esophageal surgeon output—fewer than 50 annually in the United States—constitutes the binding capacity constraint propping pricing for minimally invasive repair platforms and associated device bundles.
For Market Incumbents: Anticipate compression in enteral feeding tube margins as third-party home care suppliers capture post-discharge revenue cycles. Defensive consolidation around magnetic anastomosis training programs at Cincinnati Children's Hospital and Great Ormond Street Hospital protects premium positioning. Backward integration into medical-grade silicone compounding mitigates raw material bottleneck exposure from German and Japanese specialty chemical producers. For New Entrants and Emerging Players: Rural Indian surgical centers relying on open thoracotomy represent the most penetrable buyer archetype for cost-engineered thoracoscopic platforms. Home enteral nutrition services for complex VACTERL cases offer recurring revenue white space currently fragmented among third-party suppliers. Go-to-market through academic partnership programs with US congenital surgery networks accelerates clinical validation without direct hospital sales infrastructure. For Investors and Strategic Acquirers: FDA Humanitarian Device Exemption approvals for neonatal-scale instruments are the leading indicator that commercialization timelines—and associated valuation multiples—are compressing for congenital anomaly device developers. Five-to-ten-year viability favors platform companies with reimbursement strategy integration and GPO contract penetration. Watch for METI subsidy announcements in Japan as signal of Asia-Pacific regulatory tailwinds accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pediatric Device Consortia Pathway | Accelerates premarket review timelines for congenital anomaly technologies targeting neonatal populations. |
| Hospital System Partnership | Children's Hospital of Philadelphia and Texas Children's consolidated vendor contracts around full-procedure bundles. |
| CE Marking Pathway | EU MDR fast-track for pediatric innovation supports market entry for miniaturized robotic instruments. |
| Software Companion Development | Remote feeding consultation platforms expand telehealth services for rural post-discharge populations. |
| Reimbursement Strategy | Alignment between neonatal DRG codes and prolonged ICU stays influences premium technology adoption. |
Research Methodology
Document review covered FDA 510(k) and Humanitarian Device Exemption filings, EMA pediatric investigation plans, hospital procurement databases, and GPO contracts, complemented by interviews with congenital surgeons, neonatal intensive care unit directors, biomedical engineers, and hospital purchasing committee members. Secondary validation drew from ISO 13485 certification records, CMS Medicare reimbursement data, and METI healthcare technology adoption disclosures. Bottom-up procedure volume estimates triangulated against top-down market sizing from device shipment records and enteral feeding tube utilization patterns.
Cross-referencing historical adoption curves for thoracoscopic platforms with panel input from pediatric surgical fellowship program directors anchored the forecast framework. Segmentation dimensions modeled include treatment modality, delivery mode, age group, and therapy area across the analysis window. CAGRs derived from weighted average of technology diffusion rates and capacity expansion timelines for neonatal ICU beds. Industry-specific inputs incorporated magnetic anastomosis program establishment rates and robotic-assisted surgery training pipeline throughput.
Revisions become necessary when FDA regulatory pathway modifications, EU MDR recertification delays, or raw material supply disruptions from German and Japanese specialty chemical producers materialize. Forecasts reflect assumptions about surgeon training output, hospital capital expenditure cycles, and reimbursement alignment stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Immunology Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market