
 Pigmentosa Treatment Market | 2026-2036
Pigmentosa Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pigmentosa Treatment Market Analytics
Subretinal delivery of AAV-based gene therapies is reconfiguring surgical workflows and reimbursement structures across retinal practices. Spark Therapeutics leverages its pioneering regulatory experience in inherited retinal diseases to sustain first-mover advantages in vector manufacturing. Novartis anchors its position through integrated ophthalmology networks that control patient access pathways. ProQR Therapeutics differentiates via its proprietary Axiomer RNA editing platform, which navigates mutation-agnostic treatment strategies.
Pigmentosa treatment encompasses therapeutic interventions targeting retinitis pigmentosa, a progressive inherited retinal degeneration characterized by photoreceptor loss and progressive visual field constriction, typically addressed through gene supplementation, neuroprotection, or optogenetic approaches designed to preserve or restore visual function. Gene therapy commands the highest development investment intensity due to curative intent and premium pricing potential, while ocular implants represent the most mechanically complex segment with concentrated manufacturing expertise. Intravitreal delivery methods are expanding fastest as clinicians seek less invasive alternatives to subretinal surgery, though topical formulations remain marginal given the blood-retinal barrier constraints.
The FDA's orphan drug designation and breakthrough therapy programs compress development timelines and extend market exclusivity for qualifying pigmentosa therapies, while the EMA's PRIME scheme accelerates European access pathways for similarly innovative modalities. REACH compliance governs vector manufacturing materials and reagent sourcing across European supply chains, creating differentiated regulatory burdens versus US-centric development programs. Stakeholders must monitor emerging reimbursement decisions from CMS and national health technology assessment bodies, as these will determine commercial viability irrespective of clinical efficacy demonstrations.
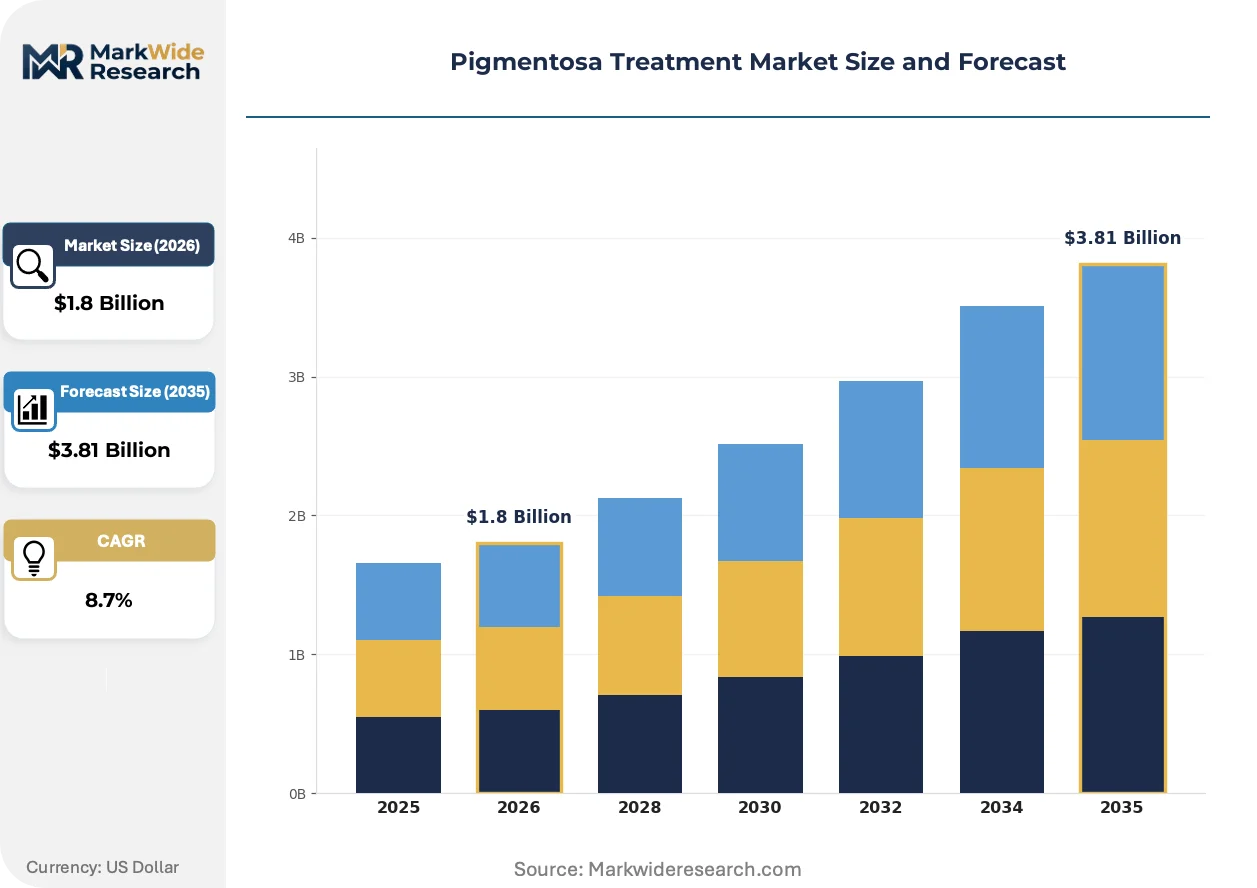
Market Dynamics
Gene therapy platforms are compressing traditional therapeutic development cycles while subretinal surgical delivery methods demand specialized retinal surgical infrastructure that concentrates treatment capacity within academic medical centers.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated approval pathways compress clinical trial timelines and extend market exclusivity for qualifying rare disease therapies targeting inherited retinal degenerations.
- AAV Vector Manufacturing Scale-Up:Advances in suspension-based bioreactor production are reducing per-dose manufacturing costs for ocular gene therapies and expanding treatment accessibility.
- Retinal Specialist Clustering:Concentrated patient populations around major US academic hubs—Boston, Philadelphia, and San Francisco—create efficient referral networks for complex subretinal procedures.
Market Restraints
- Vector Manufacturing Bottlenecks:Plasmid DNA supply constraints and limited contract development and manufacturing organization capacity create 18-24 month production backlogs for AAV-based therapies.
- Blood-Retinal Barrier Pharmacokinetics:Topical and intravitreal delivery methods face fundamental physiological limits in reaching outer retinal photoreceptors, restricting non-surgical therapeutic options.
- Reimbursement Uncertainty:CMS and commercial payers have not established durable payment mechanisms for single-administration curative therapies priced above traditional chronic treatment paradigms.
Strategic Opportunities
- Mutation-Agnostic RNA Editing:Proprietary RNA editing platforms enable therapeutic development without patient-specific genetic screening, expanding addressable populations beyond currently defined gene therapy targets.
- Optogenetic Sensory Substitution:Light-sensing protein engineering creates treatment pathways for late-stage patients with extensive photoreceptor loss who fall outside gene supplementation eligibility.
- European PRIME Scheme Access:The EMA's PRIority MEdicines designation offers accelerated assessment timelines and enhanced regulatory support for innovative ocular therapies entering European markets.
Industry Challenges
- Vitreoretinal Surgical Training Capacity:Subretinal injection procedures require specialized fellowship-trained surgeons, and current training pipeline output limits scalable treatment delivery.
- Long-Term Durability Surveillance:Gene therapy developers must maintain 15-year post-marketing follow-up registries to satisfy FDA requirements for delayed adverse event detection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigmentosa Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ocular Implants, Medications, Gene Therapy, Nutritional Supplements Delivery Method: Topical, Injectable, Oral, Intravitreal End User: Hospitals, Clinics, Research Institutes, Home Care Settings Treatment Stage: Preventive, Curative, Supportive, Palliative |
| Companies Covered | Spark Therapeutics, Novartis, ProQR Therapeutics, Gensight Biologics, Beacon Therapeutics, Nanoscope Therapeutics, Ocugen, 4D Molecular Therapeutics, Aldeyra Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigmentosa Treatment Market Evolving Landscape
RNA-based therapeutic modalities are challenging DNA-centric gene therapy dominance while regulatory frameworks adapt to single-administration curative pricing models that break traditional pharmaceutical reimbursement structures.
CRISPR-based gene editing is collapsing the distinction between corrective and replacement strategies in inherited retinal disease. Academic medical centers in the United States are establishing dedicated ocular gene therapy suites to accommodate the specialized instrumentation and surgical workflows required. This infrastructure concentration is compressing patient access timelines for approved therapies while creating geographic treatment deserts outside major metropolitan corridors.
REACH compliance mandates now govern vector manufacturing materials and reagent sourcing across European supply chains, imposing differentiated regulatory burdens versus US-centric development programs. EMA's evolving advanced therapy medicinal product classification framework is reshaping how developers structure pivotal trial designs and manufacturing quality agreements. European gene therapy sponsors are responding by establishing dedicated EU manufacturing footprints rather than relying on US-based supply with import logistics.
Retinal specialists are consolidating referral patterns around centers with established gene therapy programs and dedicated surgical scheduling capacity. Hospital-based ophthalmology departments are displacing independent retinal practices as primary access points for complex inherited disease management. This channel concentration is most visible in the United States, where integrated delivery networks control patient pathways through prior authorization requirements and specialist network exclusions.
Pigmentosa Treatment Market Segmentation
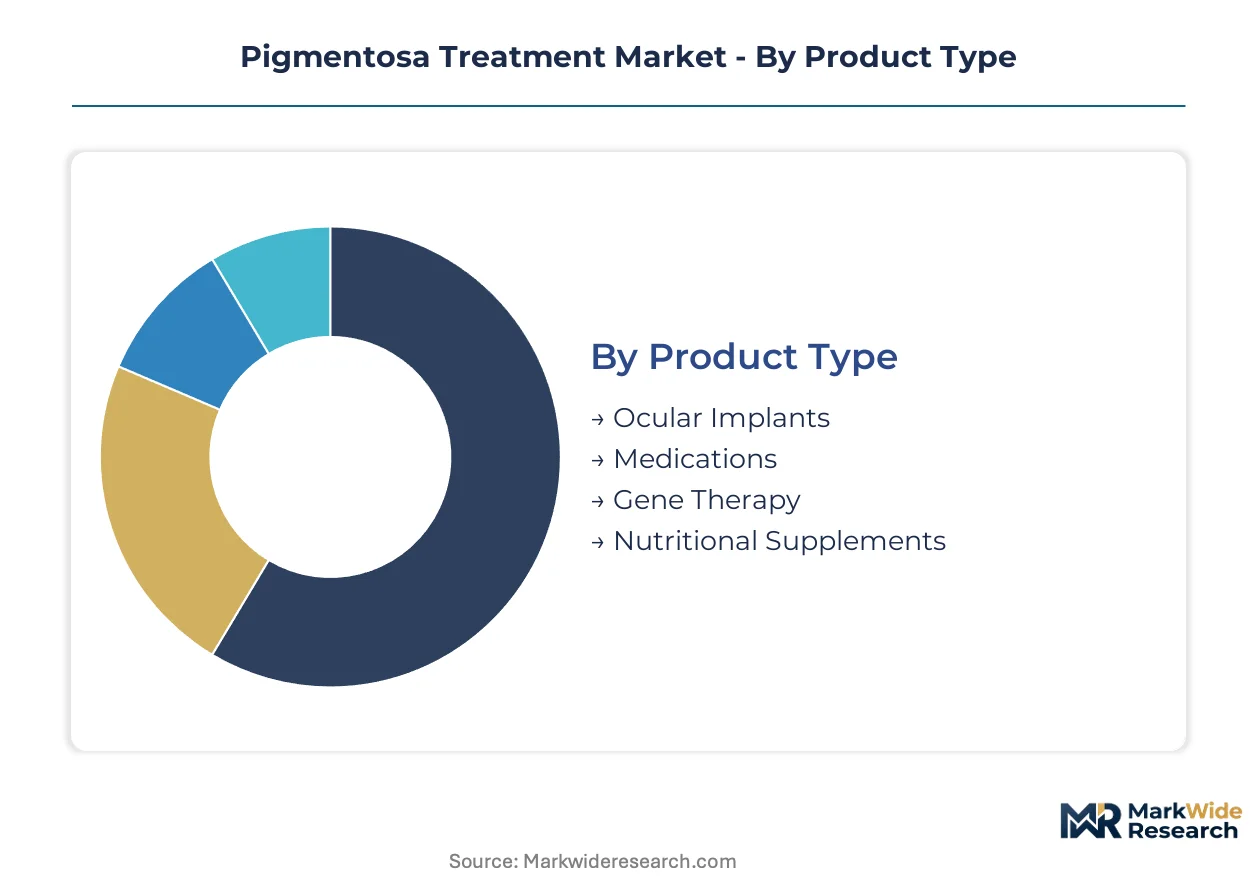
Treatment modality selection in retinitis pigmentosa hinges on disease stage, genetic profile, and surgical accessibility. Segmentation reveals how curative versus palliative approaches command fundamentally different development investments and reimbursement frameworks.
Product Type:
Product portfolios span implantable hardware through biologic interventions, with development risk and manufacturing complexity varying by an order of magnitude across categories.
- Gene Therapy:AAV-based vectors deliver functional gene copies to retinal pigment epithelium or photoreceptors, requiring subretinal surgical delivery. Spark Therapeutics and Novartis concentrate hospital-based demand in Boston and Philadelphia corridors where specialized surgical infrastructure exists. FDA breakthrough therapy designations compress development timelines but impose 15-year post-marketing surveillance obligations.
- Ocular Implants:Subretinal microelectrode arrays and sustained-release devices address late-stage photoreceptor degeneration through neurostimulation or drug elution. Manufacturing demands cleanroom fabrication and biocompatible materials expertise that concentrates supply among three contract manufacturers. Second Sight Medical and Pixium Vision anchor European development activity.
- Medications:Small-molecule neuroprotective agents target oxidative stress pathways and inflammatory cascades. Oral carbonic anhydrase inhibitors and antioxidant formulations serve broader patient populations with less invasive administration.
- Nutritional Supplements:Vitamin A palmitate, lutein, and omega-3 formulations address nutritional deficiencies linked to retinal degeneration progression. Over-the-counter distribution through retail pharmacy channels keeps pricing accessible but limits clinical evidence requirements.
The dominant share belongs to Gene Therapy, while Ocular Implants is closing the gap fastest.
Delivery Method:
Route of administration determines treatment setting, specialist training requirements, and patient compliance profiles across the disease continuum.
- Intravitreal:Trans-scleral injection into the vitreous cavity permits office-based administration by trained retinal specialists. Anti-VEGF and emerging gene therapy payloads reach inner retinal layers without surgical theater requirements. Demand clusters in United States metropolitan markets where ophthalmology networks maintain high injection volumes.
- Injectable:Subcutaneous and intramuscular routes support systemic biologic delivery and depot formulations. Manufacturing scale advantages reduce per-dose costs compared with ocular-specific delivery systems.
- Oral:Tablet and capsule formulations enable home-based chronic administration for neuroprotective regimens. Blood-retinal barrier penetration limits efficacy for outer retinal targets.
- Topical:Eye drops and ointments face fundamental pharmacokinetic constraints reaching photoreceptor layers. Development programs emphasize corneal penetration enhancers and nanoparticle carriers to overcome anatomical barriers.
Intravitreal administration captures the highest procedure volume, though Injectable formats are expanding most quickly as sustained-release platforms mature.
End User:
Care setting selection reflects procedure complexity, reimbursement infrastructure, and patient acuity requirements.
- Hospitals:Academic medical centers house specialized vitreoretinal surgical suites, gene therapy infusion centers, and multidisciplinary inherited retinal disease clinics. Prior authorization requirements and specialist network exclusions steer complex cases toward integrated delivery networks.
- Clinics:Independent and hospital-affiliated ophthalmology practices manage stable patients on chronic therapies and post-surgical monitoring. Intravitreal injection volumes sustain practice economics.
- Research Institutes:Clinical trial sites at Massachusetts Eye and Ear, Scheie Eye Institute, and University of Iowa drive pipeline advancement through natural history studies and pivotal trials.
- Home Care Settings:Oral medications and nutritional supplements shift administration burden to patients and caregivers, with telemedicine monitoring reducing clinic visit frequency.
Hospitals retain the dominant patient share, while Research Institutes are gaining footprint fastest through expanded gene therapy trial networks.
Treatment Stage:
Intervention timing determines therapeutic goal, patient eligibility, and regulatory pathway selection.
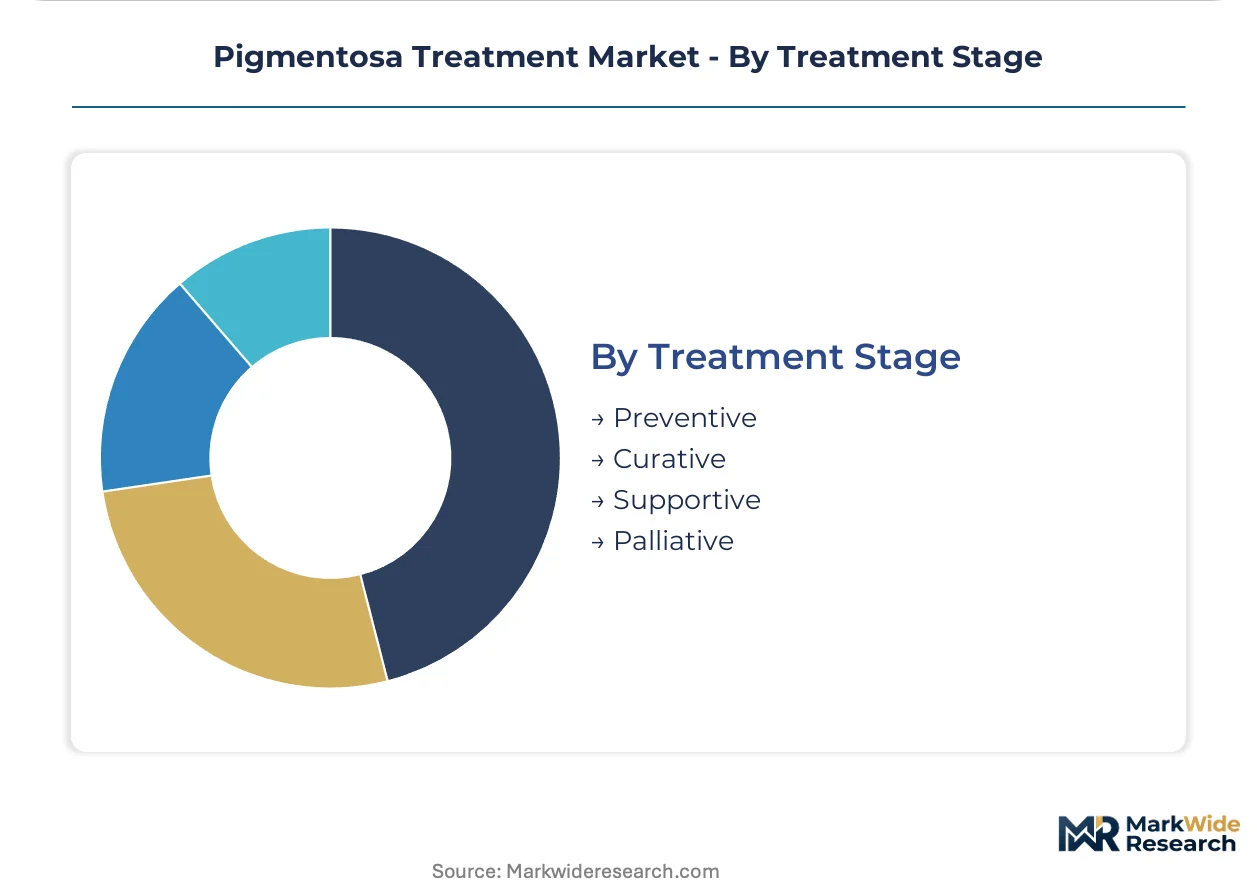
- Curative:Gene supplementation and gene editing aim to halt or reverse photoreceptor loss in patients with viable retinal structure. Single-administration pricing models challenge traditional reimbursement mechanics.
- Preventive:Early-stage interventions target at-risk carriers and pre-symptomatic individuals with neuroprotective regimens. Genetic screening expansion in Ashkenazi Jewish and other founder populations identifies candidates.
- Supportive:Low vision aids, orientation training, and psychological services maintain functional independence as visual field constriction progresses. Medicare coverage for vision rehabilitation services varies by state.
- Palliative:End-stage interventions address complete photoreceptor loss through optogenetic sensory substitution and cortical visual prosthetics. Argus II and Orion systems serve this population.
Curative approaches command the dominant development investment, while Palliative solutions are climbing the fastest as optogenetic platforms advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-based retinal specialists concentrate demand in the United States, Germany, Japan, United Kingdom, and Switzerland, where academic medical centers anchor gene therapy delivery infrastructure and regulatory pathways for rare disease treatments.
United States
FDA breakthrough therapy designations compress clinical timelines for inherited retinal disease programs, while CMS reimbursement decisions determine commercial viability for single-administration curative therapies. Massachusetts Eye and Ear in Boston and Scheie Eye Institute in Philadelphia house dedicated ocular gene therapy suites that concentrate surgical capacity.
Germany
EMA's PRIME scheme accelerates European access pathways for innovative ocular therapies, while REACH compliance mandates govern vector manufacturing materials across German supply chains. Heidelberg University Hospital and University Hospital Tübingen anchor inherited retinal disease clinical trial networks.
Japan
PMDA's Sakigake designation system fast-tracks regenerative medicine products including ocular gene therapies, while METI funding supports domestic AAV manufacturing scale-up. University of Tokyo Hospital and Osaka University Hospital concentrate retinal surgical expertise for subretinal delivery procedures.
United Kingdom
NICE health technology assessments determine NHS reimbursement for high-cost rare disease therapies, while MHRA post-Brexit regulatory autonomy enables accelerated access schemes. Moorfields Eye Hospital in London and University of Oxford drive natural history studies and pivotal gene therapy trials.
Switzerland
Swissmedic's streamlined advanced therapy medicinal product procedures attract European headquarters for gene therapy developers, while federal rare disease program funding supports patient registry infrastructure. University Hospital of Basel and University Hospital Zurich maintain specialized vitreoretinal surgical fellowship programs.
Pigmentosa Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where hospital network integration determines patient access. Large pharmaceutical incumbents anchor positions through ophthalmology service line partnerships, while biotechnology specialists concentrate on vector engineering and surgical delivery innovation. Three archetypes dominate: integrated delivery network partners, platform-technology licensors, and surgical workflow enablers. Competitive moves center on academic medical center exclusivity arrangements and manufacturing capacity reservations.
Among gene therapy platform developers, Spark Therapeutics, Novartis, and ProQR Therapeutics occupy distinct strategic positions. Spark Therapeutics exemplifies the regulatory-first archetype through its pioneering FDA experience in inherited retinal diseases. Novartis represents the integrated network model with established ophthalmology service line control. ProQR Therapeutics anchors the RNA-editing specialization tier with mutation-agnostic platform positioning.
| Leading Market Players |
|---|
| Spark Therapeutics |
| Novartis |
| ProQR Therapeutics |
| Gensight Biologics |
| Beacon Therapeutics |
| Nanoscope Therapeutics |
| Ocugen |
| 4D Molecular Therapeutics |
| Aldeyra Therapeutics |
| Others |
Value Network & Pricing Analysis
Plasmid DNA supply constraints determine both pricing tier spreads and supply chain shape in ocular gene therapy manufacturing, forcing developers to reserve capacity years ahead or absorb spot-market premiums that compress margins across standard-tier products.
Pricing Analysis
Cost-plus contracts with plasmid suppliers index to raw material spot markets and bioreactor utilization rates. Pricing stratifies across premium, standard, and economy tiers based on vector purity grades and FDA breakthrough therapy certification status. Cost compression in standard-tier AAV manufacturing is intensifying because suspension-based production platforms are democratizing access. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement, while independent retinal clinics face acute margin pressure from prior authorization delays.
Supply Chain Analysis
Export-control restrictions on gene synthesis equipment and viral vector production technology limit flows from United States and European suppliers to emerging manufacturing hubs. Plasmid DNA production concentrates in United States, Germany, and Switzerland, while AAV fill-finish capacity clusters in United States and Ireland. Manufacturing rests on HEK293 cell banks, cationic lipid transfection reagents, and serialized cold-chain logistics. Single-source vulnerability pervades plasmid supplier relationships. Distribution runs through hospital-based specialty pharmacies and integrated delivery network infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity abounds as mutation-agnostic RNA editing platforms fragment the addressable patient population beyond single-gene therapy targets, creating niches for specialized surgical workflow providers and regional vector manufacturing facilities.
For Market Incumbents: Build regulatory-data moats through 15-year post-marketing surveillance registries that satisfy FDA requirements and deter competitor entry. Anchor capacity reservations with plasmid suppliers and CDMOs to lock out emerging players. Threat substitution from CRISPR-based gene editing platforms demands preemptive patent landscaping. Vertical integration into vector manufacturing insulates against supply bottlenecks.
For New Entrants and Emerging Players: Establish a beachhead in optogenetic sensory substitution for late-stage patients excluded from gene supplementation eligibility. Target European PRIME scheme acceleration pathways to compress time-to-revenue versus FDA timelines. White-space exists in intravitreal delivery methods that circumvent subretinal surgical infrastructure requirements. Go-to-market through academic medical center licensing agreements bypasses incumbent channel control.
For Investors and Strategic Acquirers: The market sits at a platform-validation phase that favors vector engineering specialists with manufacturing scalability proofs. Long-term viability hinges on reimbursement mechanism durability for single-administration curative therapies. Acquisition target archetype: RNA editing platforms with mutation-agnostic positioning and European regulatory submissions underway. Signal to watch: CMS national coverage determination for ocular gene therapy.
| Strategic Initiative | Industry Significance |
|---|---|
| AAV Manufacturing Scale-Up | Suspension bioreactor adoption reduces per-dose costs and expands treatment accessibility beyond academic hubs. |
| Subretinal Surgical Training Expansion | Fellowship program proliferation addresses vitreoretinal surgeon pipeline constraints limiting procedure volume growth. |
| Mutation-Agnostic Platform Development | RNA editing technologies bypass patient-specific genetic screening and expand addressable populations. |
| European PRIME Scheme Access | EMA accelerated assessment timelines compress regulatory lag versus FDA pathways for innovative modalities. |
| Reimbursement Strategy Formulation | CMS and commercial payer engagement determines commercial viability for single-administration curative pricing models. |
Research Methodology
The analysis maps gene therapy platforms, ocular implants, and neuroprotective medications, each validated through retinal specialists, hospital procurement managers, payer access specialists, and CDMO operations directors. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Assumptions held fixed include regulatory pathway timelines, reimbursement mechanism durability, and vector manufacturing yield improvements, while patient eligibility criteria and competitive entry timing were varied. Segmentation dimensions modeled encompass treatment modality, delivery method, end-user setting, disease stage, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, pricing evolution patterns, and manufacturing cost curves. Forecast inputs incorporated natural history study enrollment rates and pivotal trial readout schedules.
Macroeconomic conditions sit as an overlay; deviation in biotech funding availability, healthcare reimbursement policy, or rare disease research prioritization would shift the trajectory. Forecasts reflect assumptions about regulatory continuity and manufacturing scale-up success. Material shifts in FDA breakthrough therapy designation criteria or CMS national coverage determinations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market