
 Latin America Kitchen Furniture Market | 2026-2036
Latin America Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Kitchen Furniture Market Foresight
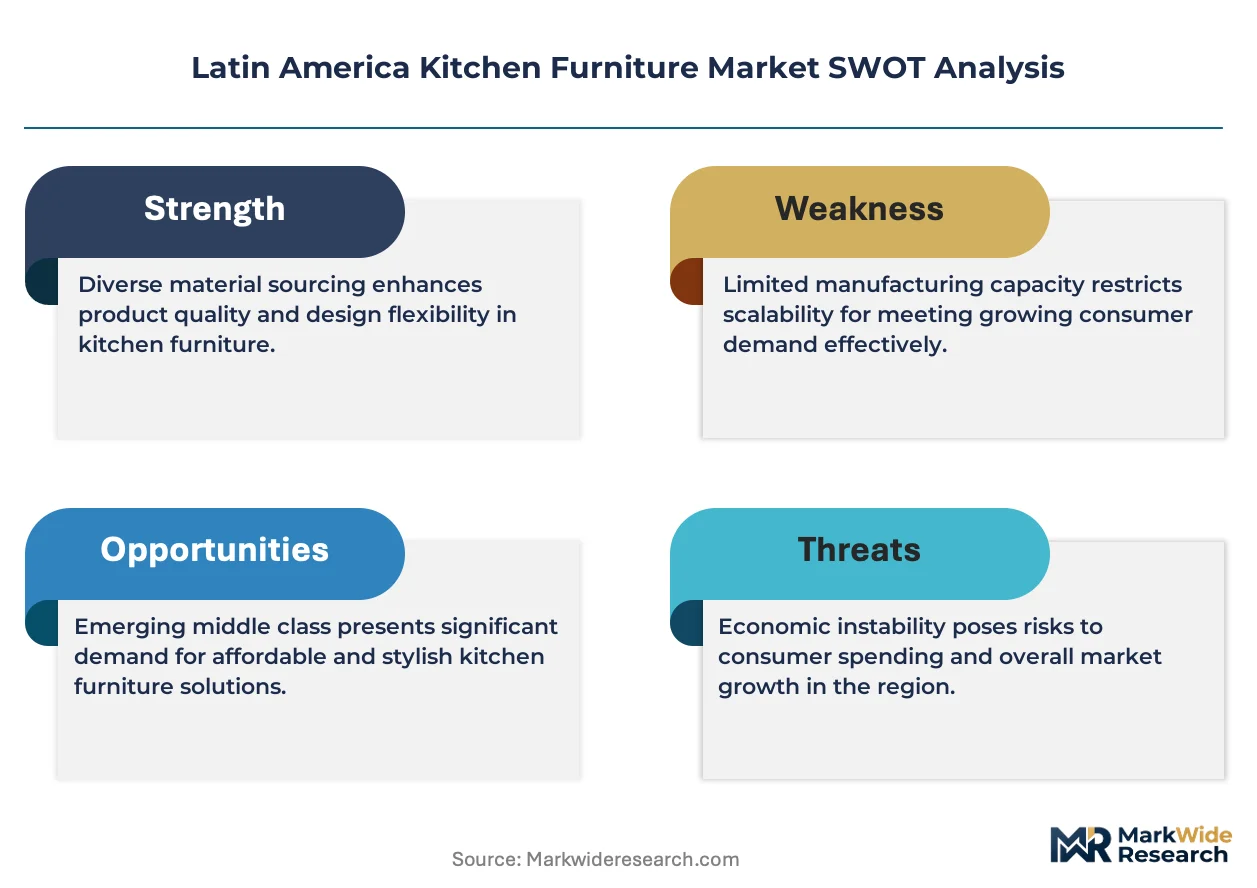
INMETRO certification is pivoting the cost-of-entry calculus for kitchen furniture manufacturers sourcing tropical hardwoods across Brazil. Santos Andira leverages captive forestry assets to sustain margin stability under stricter chain-of-custody rules. IKEA Group anchors its regional position through flat-pack logistics networks that navigate import tariff complexity. Dalla Costa differentiates via specialized solid-wood craftsmanship that commands premium positioning in southern Brazilian markets.
Latin America kitchen furniture encompasses fixed and modular storage, preparation, and dining systems engineered from engineered wood panels, solid timber, metal framing, and synthetic surfaces, typically specified to withstand high-humidity environments while supporting residential and hospitality food-service workflows. Cabinets fabricated from medium-density fiberboard with thermally fused laminate surfaces dominate volume production due to cost efficiency and moisture resistance, while solid-wood countertops command concentrated margin pools among restoration-grade buyers. Metal-frame minimalist tables represent the fastest-growing style-material intersection, driven by urban apartment downsizing trends across São Paulo and Buenos Aires.
Brazil's INMETRO and Mexico's PROFECO enforce divergent product safety and labeling standards that fragment compliance architectures for cross-border suppliers. Argentina's national consumer protection framework adds further testing requirements for imported kitchen components. Stakeholders must monitor pending Mercosur harmonization negotiations, as unified technical standards would reshape competitive access across the southern cone.
Market Dynamics
Urban condominium developers in São Paulo and Mexico City are compressing kitchen footprints while elevating specification standards, forcing manufacturers to reconcile space constraints with premium material expectations.
Growth Catalysts
- INMETRO chain-of-custody rules:Brazil's certification mandates for tropical hardwood sourcing are accelerating formalization of previously informal supplier networks, reducing illegal timber circulation.
- Metal-frame minimalist systems:Buenos Aires apartment downsizing is pulling demand toward space-efficient dining-prep hybrids that occupy under 12 square meters.
- Engineered wood panel fabrication:MDF-thermally-fused-laminate production lines achieve moisture resistance at 40% lower material cost than solid-wood alternatives.
Market Restraints
- Tropical hardwood input volatility:CITES-listed species sourcing restrictions in Amazon basin states generate 18-24 month procurement lead times for certified timber.
- Cross-border regulatory friction:Mercosur technical standards non-harmonization forces duplicate testing for Brazilian exporters serving Argentine markets.
- Flat-pack import tariff complexity:IKEA Group's regional logistics networks face cascading duty calculations across Brazil, Argentina, and Mexico customs regimes.
Strategic Opportunities
- Colombia's underpenetrated renovation market:Bogotá and Medellín kitchen replacement cycles lag São Paulo by 4-6 years, creating first-mover positioning for modular system suppliers.
- PROFECO energy-labeling alignment:Mexico's appliance integration standards for kitchen cabinetry create compliance-driven specification windows for certified manufacturers.
- Direct-to-developer channel bypass:São Paulo condominium builders are eliminating distributor markups through specification-direct relationships with panel fabricators.
Industry Challenges
- Master craftsperson scarcity:Solid-wood joinery specialization in southern Brazilian markets faces generational skill transfer gaps as training programs contract.
- Dual-certification timeline compression:Suppliers seeking simultaneous INMETRO and FSC chain-of-custody approvals encounter conflicting audit schedules and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Kitchen Furniture Market |
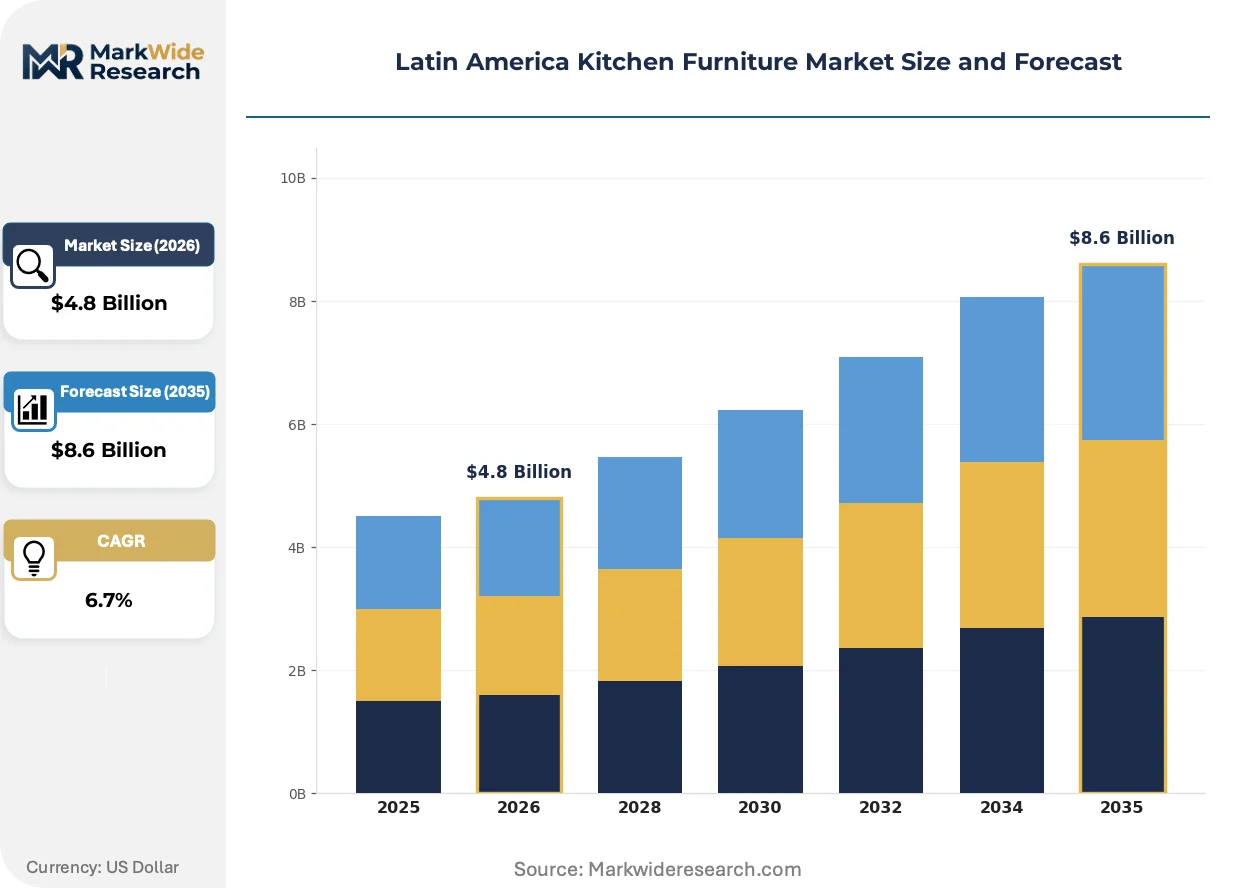
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Tables, Chairs, Countertops Material: Wood, Metal, Glass, Plastic Style: Modern, Traditional, Rustic, Minimalist Distribution Channel: Online, Retail Store, Wholesale, Direct Sales |
| Companies Covered | Santos Andira, IKEA Group, Linea Brasil, Arteqiri, Ashley Furniture Industries, Dalla Costa, Politorno, Fontenlastore, Techni Mobili, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Kitchen Furniture Market Shifts & Advancements
Digital specification tools and moisture-resistant material science are compressing traditional design-to-installation cycles while elevating performance benchmarks for high-humidity environments.
Medium-density fiberboard with thermally fused laminate surfaces is consolidating market position in volume production segments. São Paulo condominium developers specify these systems for 70% of new unit installations. The technology is consolidating previously fragmented panel supplier tiers into three dominant fabrication clusters.
PROFECO's mandatory energy-efficiency labeling for integrated kitchen appliances is forcing cabinetry manufacturers to redesign compartment dimensions and ventilation pathways. Mexican importers now face pre-shipment inspection requirements that add 6-8 weeks to delivery schedules. Buenos Aires distributors are absorbing compliance costs rather than passing through price increases to preserve market share.
Developer-direct specification contracts are displacing traditional distributor-showroom networks across major metropolitan markets. São Paulo and Mexico City builders now issue consolidated RFPs covering 500-2,000 unit kitchen packages. Argentina lags this transition by approximately 36 months, maintaining stronger distributor intermediation in Buenos Aires and Córdoba procurement patterns.
Latin America Kitchen Furniture Market Segmentation
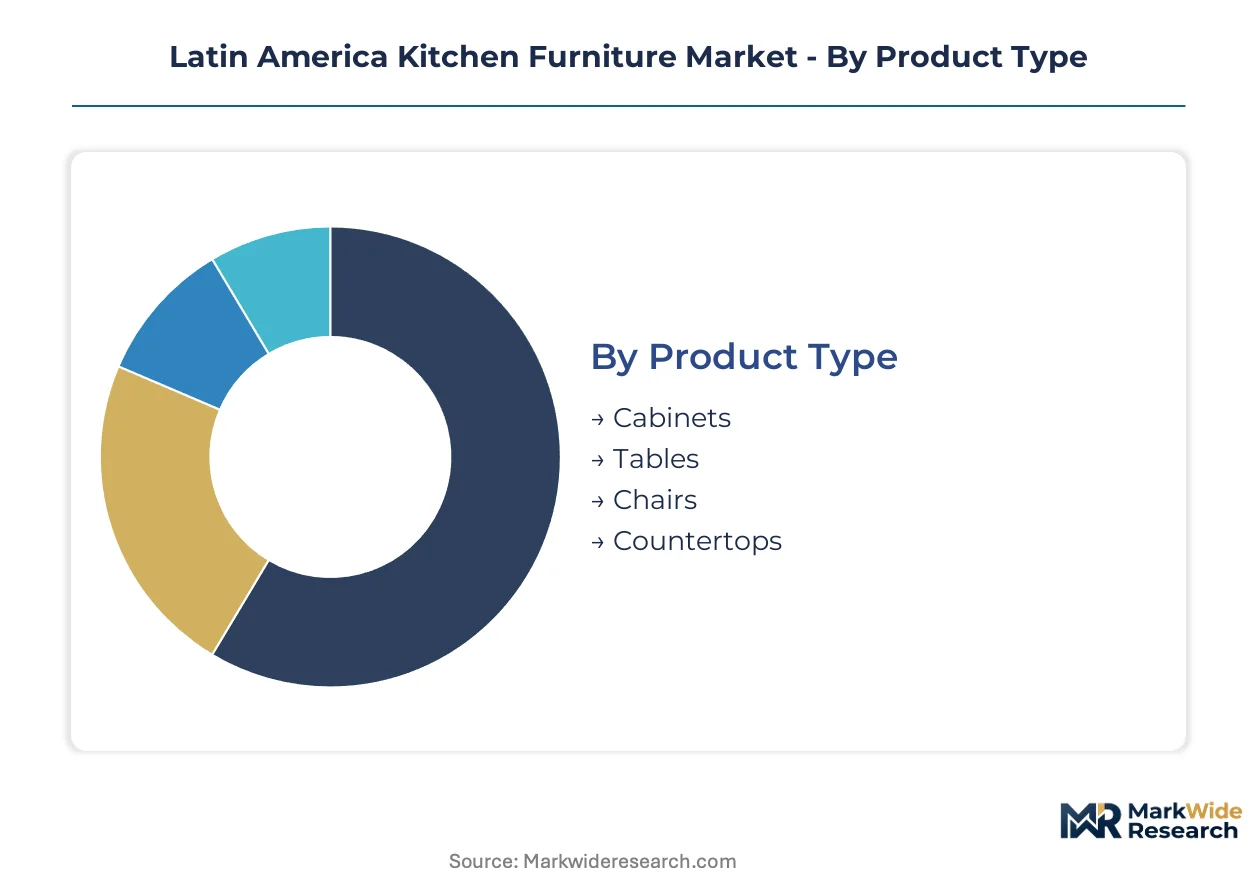
Kitchen furniture procurement in Latin America splits across customization intensity, material durability requirements, and channel access economics. Developers, renovators, and hospitality operators each prioritize different segment combinations based on project scale and humidity exposure.
Product Type:
Customization intensity varies sharply across product categories, with built-in systems demanding specification depth that freestanding items rarely require.
- Cabinets:Engineered wood panels with thermally fused laminate surfaces dominate volume production for São Paulo condominium developers seeking moisture resistance at controlled cost points. Brazilian INMETRO chain-of-custody rules are compressing supplier pools for solid-wood cabinet orders.
- Tables:Metal-frame minimalist designs with integrated storage are gaining share fastest among Buenos Aires apartment downsizers. These systems occupy under 12 square meters while supporting dual dining-prep functions.
- Chairs:Stackable polymer and metal hybrid seating serves hospitality renovation cycles in Mexico City and Bogotá.
- Countertops:Quartz-composite surfaces are displacing laminate in premium Brazilian kitchen replacement projects.
Most installed capacity flows through Cabinets. Expansion is steepest in Tables.
Material:
Cost tiers separate segments by procurement lead time, certification burden, and climate performance.
- Wood:Medium-density fiberboard achieves 40% lower material cost than solid alternatives while meeting humidity resistance specifications. CITES-listed tropical hardwood sourcing generates 18-24 month procurement timelines for certified timber.
- Metal:Powder-coated steel framing anchors the fastest-expanding style-material intersection across São Paulo and Buenos Aires urban cores. Downsizing trends favor metal's space-efficiency and durability.
- Glass:Tempered panel backsplashes and shelving serve premium renovation segments in southern Brazilian markets.
- Plastic:Injection-molded polymer components target entry-level hospitality and rental property specifications.
Wood commands the greatest installed base. Metal is climbing the fastest.
Style:
Geography drives style preference concentration, with metropolitan density correlating to minimalist adoption and regional heritage markets sustaining traditional demand.
- Modern:Clean-line cabinetry with integrated appliance housing dominates São Paulo and Mexico City developer specifications. PROFECO energy-labeling alignment is forcing ventilation pathway redesigns.
- Traditional:Ornate solid-wood joinery maintains concentrated demand in southern Brazilian restoration-grade markets facing master craftsperson scarcity.
- Rustic:Reclaimed timber aesthetics serve boutique hospitality projects in Colombia's coffee region and Argentine Patagonia.
- Minimalist:Metal-frame systems with concealed storage are expanding most quickly in Buenos Aires apartment conversions.
Modern styling absorbs the greatest specification volume. Minimalist is gaining share fastest.
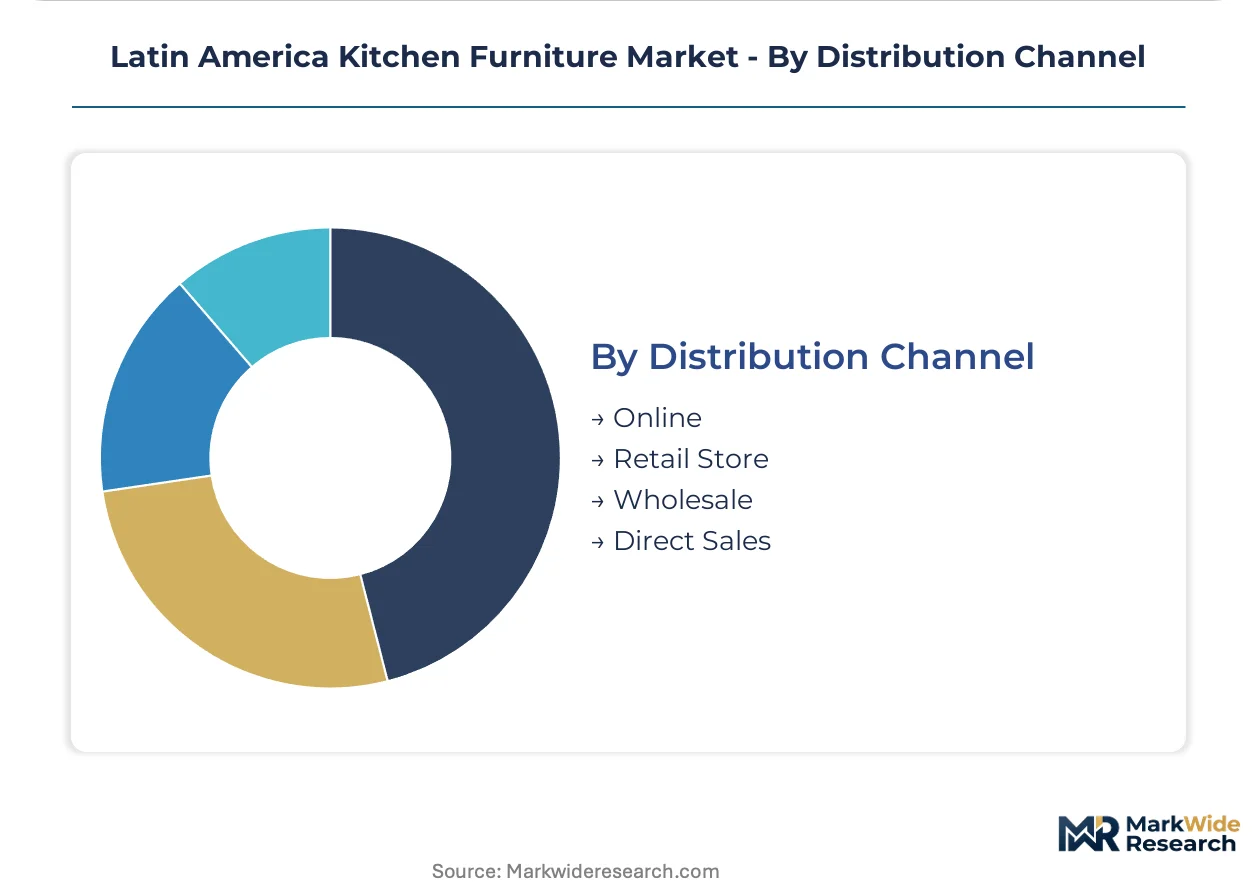
Distribution Channel:
Channel selection determines margin capture, with direct relationships compressing traditional intermediary economics.
- Online:Digital specification tools are compressing design-to-installation cycles for standardized modular systems. São Paulo developers increasingly issue consolidated RFPs through platform interfaces.
- Retail Store:Showroom networks maintain stronger position in Argentina, where distributor intermediation lags the direct-channel transition by approximately 36 months.
- Wholesale:Panel fabricator clusters supply bulk orders to regional contractors serving secondary Brazilian and Mexican markets.
- Direct Sales:Developer-direct contracts covering 500-2,000 unit kitchen packages are displacing distributor-showroom networks across São Paulo and Mexico City.
Direct Sales channels capture the greatest project value. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian furniture manufacturing traces its modern scale to post-war industrialization in São Paulo state, where Italian immigrant craft traditions merged with panel processing technology imported from Germany and Austria during the 1960s.
Brazil
São Paulo condominium developers specify moisture-resistant MDF-thermally-fused-laminate systems for 70% of new unit installations. INMETRO chain-of-custody certification mandates for tropical hardwood sourcing are compressing supplier pools and accelerating formalization of previously informal timber networks. The Bento Gonçalves furniture cluster in Rio Grande do Sul sustains solid-wood craftsmanship specialization despite generational skill transfer gaps.
Mexico
Mexico City metro area developers are consolidating kitchen package procurement through direct specification relationships covering 500-2,000 unit developments. PROFECO mandatory energy-efficiency labeling for integrated appliances forces cabinetry manufacturers to redesign compartment dimensions and ventilation pathways. The Bajío Region's Querétaro and Guanajuato industrial corridors host expanding panel fabrication capacity serving North American export channels.
Argentina
Buenos Aires apartment downsizing trends pull demand toward metal-frame minimalist dining-prep hybrids occupying under 12 square meters. The national consumer protection framework adds testing requirements for imported kitchen components that duplicate Mercosur standards, generating 6-8 week pre-shipment inspection delays. Córdoba maintains stronger distributor intermediation than São Paulo or Mexico City, lagging the direct-channel transition by approximately 36 months.
Colombia
Bogotá and Medellín kitchen replacement cycles trail São Paulo by 4-6 years, creating first-mover positioning for modular system suppliers targeting renovation demand. The country's national standards body enforces product safety testing that fragments compliance architectures for cross-border suppliers. Cali's manufacturing base is expanding engineered wood panel capacity to serve Andean region distribution networks.
Chile
Santiago metropolitan area hospitality renovation cycles sustain demand for stackable polymer-metal hybrid seating and standardized modular storage systems. The national economic development agency promotes wood product export certification alignment with international chain-of-custody standards. Valparaíso port logistics infrastructure supports import distribution for international flat-pack suppliers serving the southern cone.
Latin America Kitchen Furniture Market Competitive Landscape
The competitive structure tilts toward captive-forestry specialists and flat-pack logistics operators with cross-border tariff navigation capabilities. Brazilian panel fabricators dominate volume production through MDF-thermally-fused-laminate technology, while southern European heritage craft traditions sustain premium solid-wood positioning in select sub-regions. Three archetypes anchor positioning: vertically integrated timber holders, international flat-pack distributors, and specialized joinery ateliers. Capacity consolidation and developer-direct channel bypass represent the dominant competitive moves reshaping intermediary economics.
Among Brazilian specialists, Santos Andira exemplifies the captive-forestry archetype through upstream timber control that sustains margin stability under stricter chain-of-custody rules. Dalla Costa occupies a position within the premium solid-wood tier, anchoring craftsmanship differentiation in southern Brazilian restoration-grade markets. IKEA Group represents the international flat-pack logistics archetype, navigating import tariff complexity across Brazil, Argentina, and Mexico customs regimes through regional distribution network configuration.
| Leading Market Players |
|---|
| Santos Andira |
| IKEA Group |
| Linea Brasil |
| Arteqiri |
| Ashley Furniture Industries |
| Dalla Costa |
| Politorno |
| Fontenlastore |
| Techni Mobili |
| Others |
Supply & Pricing Matrix
Tropical hardwood certification costs cascade through Brazilian supply chains, compressing margins for uncertified panel fabricators while elevating pricing power for INMETRO-compliant suppliers serving São Paulo developers. MDF-thermally-fused-laminate production lines absorb displaced demand as buyers trade solid-wood premiums for moisture-resistant engineered alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Solid-wood craftsmanship commands premium positioning in southern Brazilian restoration markets, while bulk condominium procurement extracts standard-tier discounts from panel fabricators. Pricing pressure stems from CITES-listed species procurement delays forcing buyers toward engineered substitutes. Developer-direct channels exhibit lowest price sensitivity; independent renovators in secondary markets absorb highest cost volatility.
Supply Chain Analysis
Freight cost differentials between Amazon basin timber origins and São Paulo manufacturing clusters compress margins for non-integrated suppliers. Brazil, Mexico, and Argentina anchor regional production, with Colombian capacity expanding to serve Andean distribution networks. Raw material flows draw from tropical hardwood concessions, engineered wood panel imports, and powder-coated steel framing. Single-source vulnerability concentrates in certified timber networks facing 18-24 month procurement timelines. Distribution runs through developer-direct contracts displacing traditional showroom intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
INMETRO chain-of-custody formalization operates as a regulatory compounder, accelerating supplier consolidation as compliance costs exclude informal timber networks from São Paulo developer specifications.
For Market Incumbents: Deepen captive forestry control to sustain margin stability under stricter chain-of-custody rules. Consolidate panel fabrication capacity around MDF-thermally-fused-laminate technology serving moisture-resistant demand from condominium developers. Defensive certification investment in simultaneous FSC-INMETRO dual approval creates competitive moats against emerging regional entrants. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in Colombian renovation markets offer white-space positioning for modular system suppliers. Bogotá and Medellín replacement cycles lag São Paulo by 4-6 years, creating first-mover windows for standardized panel fabricators. Direct-to-developer channel bypass in Mexico City metro area extracts distributor markups through consolidated RFP relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where certification burdens exceed informal supplier working capital capacity. Long-term viability favors vertically integrated timber holders with compliant concession access over pure-play fabricators. Acquisition target archetype: mid-scale panel producers with latent INMETRO certification progress and São Paulo developer relationships. Signal to monitor: Mercosur technical standards harmonization negotiations reshaping cross-border competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forestry Integration | Upstream timber control insulates margin stability under INMETRO chain-of-custody mandates. |
| Developer-Direct Channel Establishment | São Paulo condominium builders eliminate distributor markups through specification-direct panel procurement. |
| Dual Certification Investment | Simultaneous INMETRO-FSC approval unlocks premium positioning in restoration-grade southern Brazilian markets. |
| Metal-Frame Minimalist Product Line Launch | Buenos Aires downsizing trends pull demand toward sub-12-square-meter dining-prep hybrid systems. |
| Colombian Distribution Network Expansion | Bogotá and Medellín lag São Paulo replacement cycles, creating first-mover positioning for modular suppliers. |
Research Methodology
Multiple input streams — primary interviews with furniture manufacturing executives, procurement leads at São Paulo condominium developers, and INMETRO certification auditors; secondary validation through customs trade data, SEC filings of listed furniture groups, and Brazilian forestry concession registries; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Field perspectives from panel fabrication plant managers, distributor network heads in Buenos Aires and Mexico City, and hospitality renovation contractors supplied demand-side calibration.
Data-stream reconciliation across product type, material grade, style category, and distribution channel dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling. Industry-specific forecast inputs incorporated INMETRO certification penetration curves, PROFECO energy-labeling implementation timelines, and metal-frame minimalist style adoption rates in downsizing urban markets.
The model assumes a particular technology adoption path; alternative pathways for moisture-resistant engineered wood panel substitution would alter the outlook for solid-wood demand trajectories. Forecasts embed assumptions regarding Mercosur harmonization progress and CITES enforcement intensity in Amazon basin states. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
North America Countertop Market