
 Medium-Density Fibreboard (MDF) Market | 2026-2036
Medium-Density Fibreboard (MDF) Market Size, Share, and Industry Trends Forecast 2026-2036
Medium-Density Fibreboard (MDF) Market Intelligence
The EU Green Deal is recalibrating procurement criteria across European construction and furniture supply chains, pushing buyers toward low-emission panel products. Kastamonu Entegre leverages integrated forestry-to-panel operations across Central and Eastern Europe to secure feedstock cost advantages. Swiss Krono Group anchors its position through continuous press technology investments that improve density uniformity and reduce resin consumption. Weyerhaeuser Company competes via controlled timberland assets in the US Pacific Northwest, ensuring captive fiber supply for specialty MDF grades.
Medium-Density Fibreboard is an engineered wood product manufactured from refined wood fibers bonded with synthetic resin under heat and pressure, typically achieving densities between 600 and 800 kg/m³ for structural and decorative applications. Its uniform surface, absence of knots, and machinability make it the substrate of choice for laminated furniture, intricate mouldings, and painted cabinetry. Moisture Resistant MDF and Fire Retardant MDF command expanding share as building codes tighten in commercial construction, while standard grades face margin compression from commoditization in high-volume furniture markets. Eco-Friendly Grade products carry premium positioning where LEED certification and green building standards influence material selection.
EPA formaldehyde emission standards under the Toxic Substances Control Act, ECHA REACH restrictions on hazardous substances, and California Air Resources Board (CARB) Phase 2 compliance requirements collectively define the regulatory perimeter for MDF manufacturers seeking access to North American and European markets. These frameworks elevate testing and certification costs but simultaneously create market access barriers that favor producers with established compliance infrastructure. Stakeholders must monitor evolving bio-based resin technologies and regional carbon accounting rules that could reshape competitive advantage in panel manufacturing.
Market Dynamics
The EU Green Deal's formaldehyde emission ceilings are compressing margins for commodity-grade producers while rewarding integrated operators with captive resin technology and certified low-emission product lines.
Growth Catalysts
- EU Green Deal procurement mandates:Public construction tenders across Germany, France, and the Netherlands now specify E1 or E0 emission classifications, redirecting volume toward certified suppliers.
- Flat-pack furniture manufacturing:IKEA and regional ready-to-assemble producers are expanding MDF offtake for uniform substrate requirements in kitchen and bedroom collections.
- Continuous press technology diffusion:New capacity installations in Poland and Romania are achieving density uniformity improvements that reduce resin loading rates by mid-single-digit percentages.
Market Restraints
- Urea-formaldehyde resin cost volatility:Methanol and urea feedstock prices track natural gas benchmarks, exposing non-integrated producers to margin squeezes during energy price spikes.
- Softwood fiber supply concentration:Baltic and Nordic timber markets dominate structural-grade fiber supply, creating geographic chokepoints for Central European panel mills.
- Cross-laminated timber substitution:CLT and mass timber systems are capturing mid-rise commercial structural applications previously served by fire-retardant MDF sheathing.
Strategic Opportunities
- India construction-grade penetration:Urban housing stock expansion and commercial interior fit-out growth in Mumbai and Bangalore create import substitution potential for moisture-resistant grades.
- Bio-based resin convergence:Tannin-lignin adhesive systems paired with continuous press retrofit investments open premium positioning in Nordic green building certification schemes.
- Direct-to-fabricator digital channels:B2B platforms linking panel mills to custom cabinetry shops are compressing distributor layers in North American renovation markets.
Industry Challenges
- Resin chemistry talent scarcity:Formulation expertise for low-emission adhesive systems concentrates among a narrow cohort of industrial chemists with wood-panel specialization.
- CARB Phase 2 certification timelines:Third-party testing and chain-of-custody documentation for California market access extends product launch cycles by 8-14 months.
- Legacy thermoset equipment retrofit complexity:Batch press installations from the 1990s require substantial capital outlays to achieve temperature uniformity standards for thin-MDF production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium-Density Fibreboard (MDF) Market |
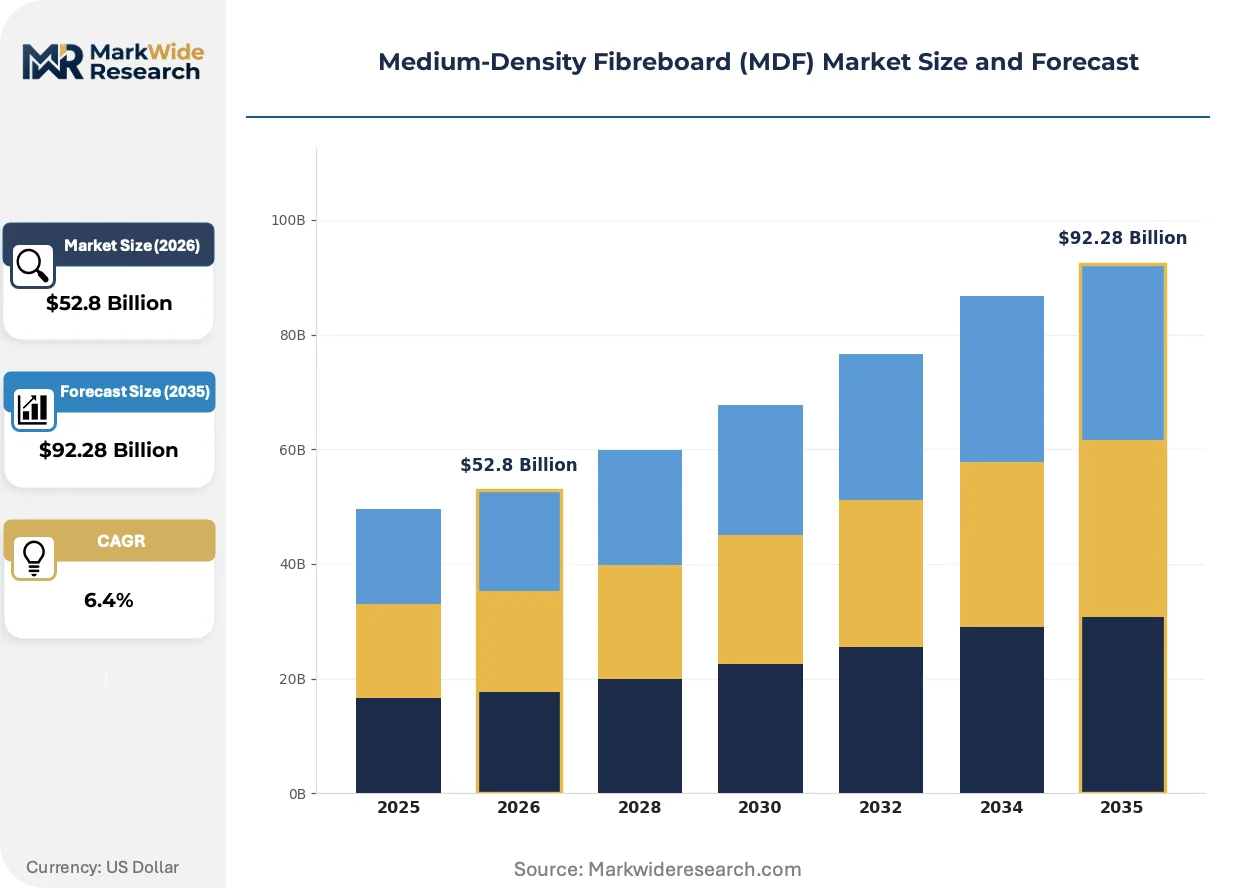
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MDF, Moisture Resistant MDF, Fire Retardant MDF, Laminated MDF Application: Furniture, Cabinetry, Flooring, Decorative Panels Grade: Commercial Grade, Industrial Grade, Premium Grade, Eco-Friendly Grade Distribution Channel: Direct Sales, Distributors, Retailers, Online Stores |
| Companies Covered | Sonae Arauco, Kastamonu Entegre, Arauco, M. Kaindl GmbH, Dynea AS, Swiss Krono Group, Weyerhaeuser Company, Dexco, Egger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium-Density Fibreboard (MDF) Market Strategic Shifts & Innovations
Digital manufacturing controls and bio-based chemistry are converging to redefine quality benchmarks and emission profiles across MDF supply chains.
Continuous press digitalization is electrifying quality consistency in high-volume operations. Real-time density scanning and hydraulic gap control systems now enable 0.5 mm thickness tolerances across 8-hour production runs. German and Austrian equipment suppliers are retrofitting 2010-era presses with IoT-enabled feedback loops that compress off-specification generation rates.
REACH restrictions on hazardous substance classifications are tightening resin formulation requirements across European manufacturing. ECHA's 2023 updates to substance evaluation criteria are forcing reformulation of conventional melamine-urea adhesives. Panel producers with in-house resin synthesis capabilities are accelerating substitution trials with soy-protein and tannin-extended systems.
Certification-driven specification behavior is restructuring procurement authority in commercial construction. LEED v4.1 and BREEAM material credits now require documented lifecycle carbon data for interior fit-out substrates. General contractors in London, Singapore, and Vancouver are consolidating panel purchasing through pre-qualified supplier lists that exclude uncertified commodity grades.
Medium-Density Fibreboard (MDF) Market Segmentation
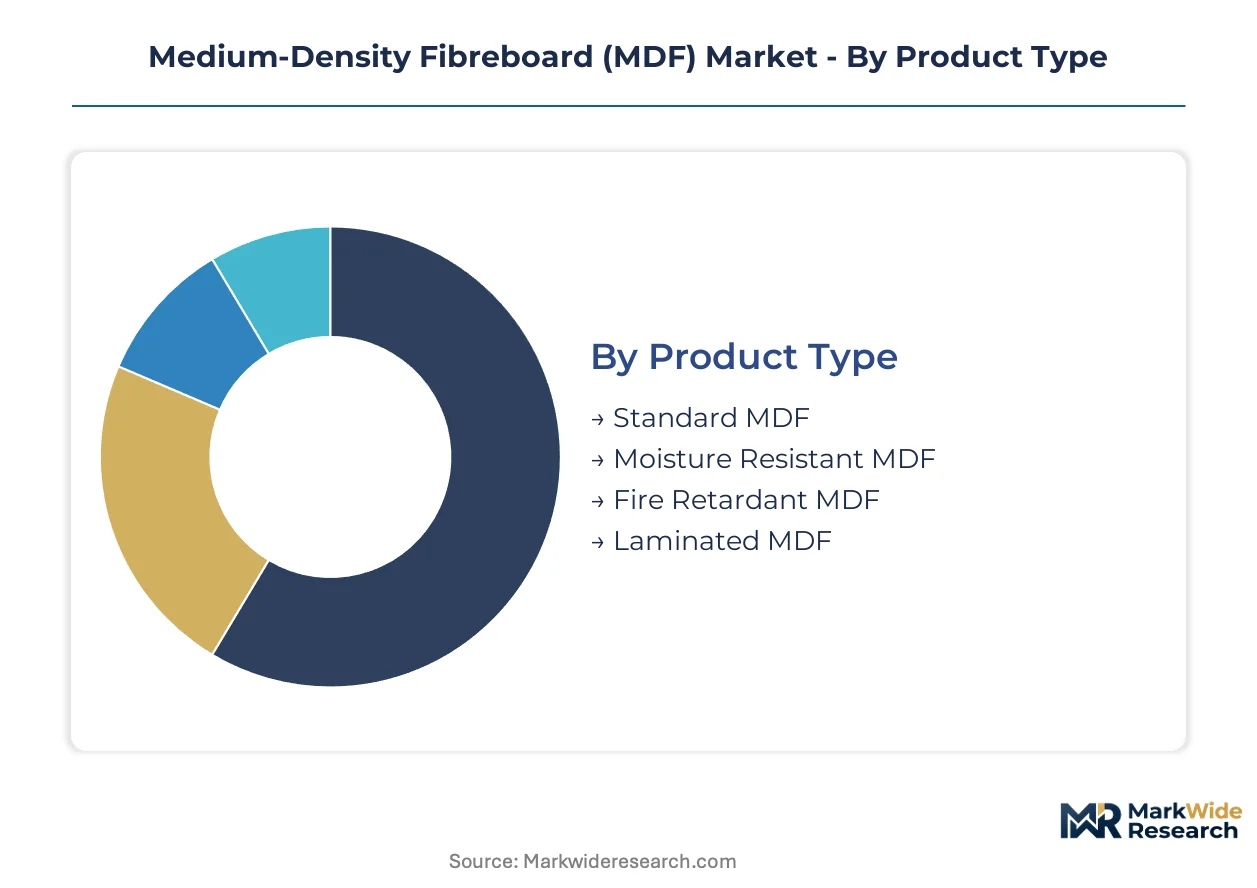
MDF segmentation reflects divergent margin profiles across commodity and specialty grades. Product type and application splits determine resin chemistry investments, while grade and channel structures shape pricing power and customer access.
Product Type:
Volume concentrates in commodity grades serving furniture mass production, while premium positioning accrues to performance-engineered variants.
- Standard MDF:Manufactured from refined softwood fibers bonded with urea-formaldehyde resin at densities of 600-800 kg/m³. Demand concentrates in flat-pack furniture manufacturing across Germany and Poland, where IKEA and regional ready-to-assemble producers drive procurement at scale. Margin compression intensifies as Chinese imports flood European spot markets.
- Moisture Resistant MDF:Incorporates hydrophobic wax emulsions and modified resins to achieve reduced thickness swelling in humid environments. Specification is climbing fastest in UK and Netherlands kitchen and bathroom cabinetry, where building codes mandate moisture-tolerant substrates for wet-zone installations.
- Fire Retardant MDF:Engineered with intumescent additives and phosphate-based flame suppressants meeting EN 13501-1 classifications.
- Laminated MDF:Pre-finished decorative surfaces bonded to MDF cores, eliminating secondary finishing steps for fabricators.
Mature deployment sits with Standard MDF. Newer deployment is concentrated in Moisture Resistant MDF.
Application:
End-use fragmentation creates divergent technical specifications and customer relationship intensities across construction and furniture verticals.
- Furniture:Dominates volume absorption across residential and commercial seating, storage, and table applications. Procurement is consolidating through direct mill relationships in North Carolina and Guangdong manufacturing clusters, bypassing traditional distributor layers.
- Cabinetry:Demands precision-machined edges and consistent density for hinge and hardware anchoring. Premium specification is expanding most quickly in German and Austrian bespoke kitchen manufacturing, where CNC fabrication tolerances reward substrate uniformity.
- Flooring:Requires elevated density and abrasion-resistant surfaces for laminate core and engineered wood substrates.
- Decorative Panels:Serves wall cladding, ceiling systems, and architectural feature applications with veneer-laminated or painted finishes.
Volume leadership belongs to Furniture. Specification complexity is climbing fastest in Cabinetry.
Grade:
Certification tiering separates commodity supply from premium positioning in green building and precision manufacturing segments.
- Commercial Grade:Standard emission classifications meeting baseline E1 or CARB Phase 2 thresholds. Procurement concentrates in volume furniture manufacturing across Vietnam and Mexico export platforms, where cost minimization dominates supplier selection.
- Premium Grade:Superior density uniformity and surface integrity for high-end lamination and painting. Demand is climbing fastest in Italian and Spanish luxury furniture manufacturing, where defect-free finishing commands substrate premiums.
- Industrial Grade:Engineered for non-visible structural applications with relaxed aesthetic tolerances.
- Eco-Friendly Grade:E0 emission classifications, bio-based resins, or FSC chain-of-custody certification.
Commercial Grade anchors volume throughput. Premium positioning is expanding most quickly in Eco-Friendly Grade.
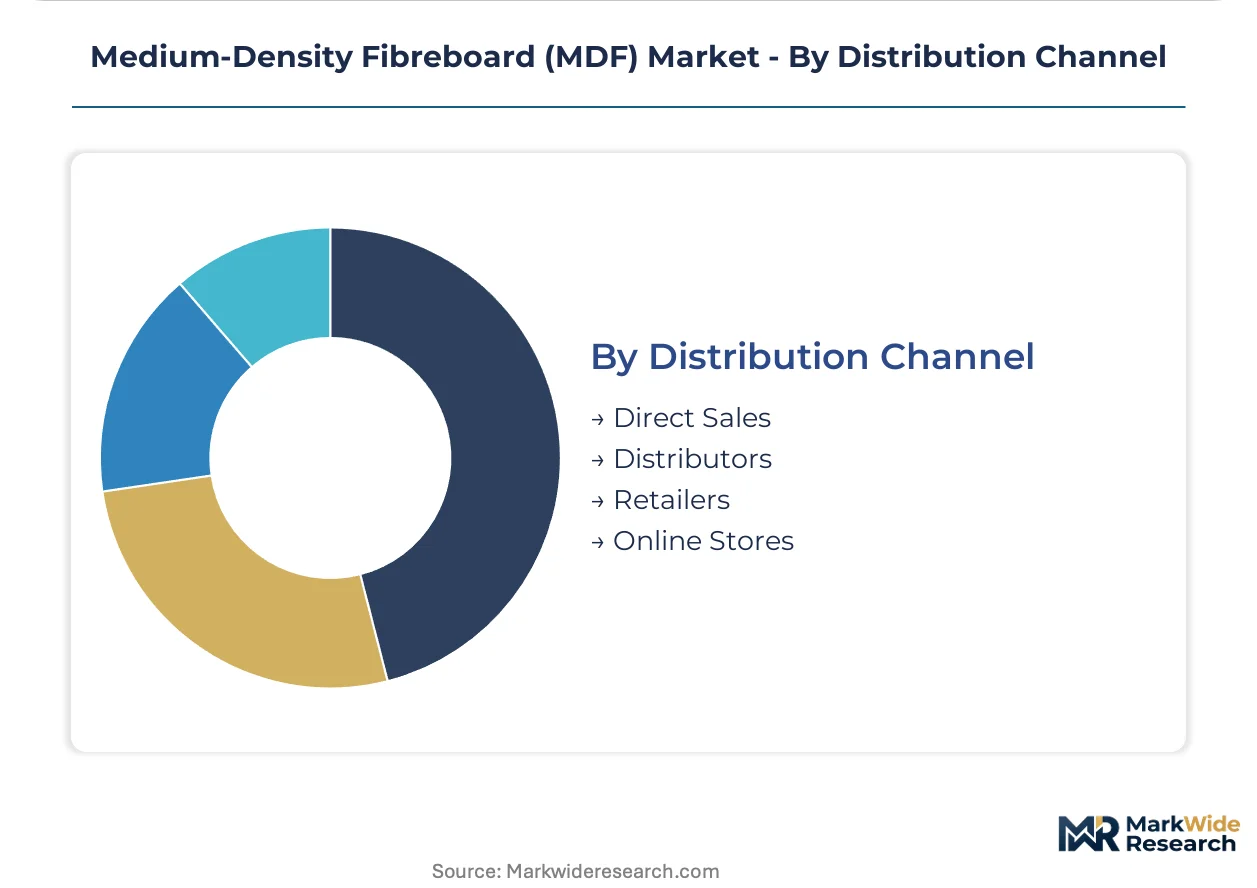
Distribution Channel:
Channel structure determines margin capture and customer data access across project-based and retail demand segments.
- Direct Sales:Mill-to-fabricator relationships for high-volume, specification-driven accounts. Concentration is heaviest in German and Polish panel manufacturing serving integrated furniture producers, where annual contracts lock in resin cost pass-through mechanisms.
- Distributors:Regional inventory positioning for small-to-mid fabricators and contractors. Share is climbing fastest in US Southeast and Texas construction markets, where just-in-time delivery requirements favor local stockholding intermediaries.
- Retailers:Big-box and specialty lumber yard channels serving renovation and DIY demand.
- Online Stores:B2B platforms and direct-to-fabricator digital marketplaces.
Direct Sales dominates contract volume. Digital channel penetration is expanding most quickly in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors the world's largest MDF manufacturing corridor, where Pearl River Delta panel mills feed furniture export clusters across Guangdong province. Demand concentrates in four additional national markets where construction cycles and regulatory frameworks reshape procurement patterns.
China
Urban renovation programs in Shanghai and Beijing are absorbing moisture-resistant grades for kitchen retrofitting. MIIT's updated GB standards for formaldehyde emissions are accelerating plant upgrades in Shandong province. The Yangtze River Delta manufacturing belt is consolidating capacity as smaller mills exit under environmental compliance pressure.
Germany
Passivhaus construction standards in Bavaria and North Rhine-Westphalia are specifying low-emission panels for interior fit-outs. The EU Green Deal's procurement mandates are redirecting public tender volumes toward E0-classified suppliers. The Cologne-Düsseldorf corridor hosts integrated forestry-to-panel operations serving bespoke kitchen manufacturers.
United States
Multi-family housing starts in Texas and Florida are driving construction-grade absorption. EPA formaldehyde emission standards under the Toxic Substances Control Act are elevating testing costs for import-dependent distributors. The Pacific Northwest timber base supplies captive fiber streams for specialty MDF grades.
India
Commercial interior build-outs in Mumbai and Bangalore are creating specification openings for fire-retardant grades. BIS certification requirements for engineered wood products are extending market access timelines for foreign suppliers. The Gujarat industrial corridor is attracting greenfield panel investments targeting import substitution.
Brazil
Residential furniture manufacturing in São Paulo state is expanding MDF offtake for middle-market cabinetry. ANVISA's monitoring of formaldehyde in consumer products is tightening quality documentation requirements. The Paraná pine belt supplies structural fiber to integrated panel operations in the South region.
Medium-Density Fibreboard (MDF) Market Key Industry Players
The competitive structure tilts toward integrated forestry operators with captive resin synthesis capabilities. Three distinct archetypes occupy distinct positions: timberland-backed North American producers, Central European continuous-press specialists, and emerging-market scale players. Consolidation pressures favor operators with backward integration into forestry assets and forward linkages to furniture manufacturing. Technology licensing and regional capacity expansion represent the dominant competitive moves as producers defend margin positions against Asian import competition.
Among European integrated operators, Kastamonu Entegre and Swiss Krono Group exemplify the forestry-to-panel archetype with Central and Eastern European manufacturing footprints. Weyerhaeuser Company anchors the timberland-backed North American position. These three entities represent contrasting strategic foundations: European continuous-press density uniformity, Nordic green certification alignment, and Pacific Northwest captive fiber security.
| Leading Market Players |
|---|
| Sonae Arauco |
| Kastamonu Entegre |
| Arauco |
| M. Kaindl GmbH |
| Dynea AS |
| Swiss Krono Group |
| Weyerhaeuser Company |
| Dexco |
| Egger |
| Others |
Cost & Logistics Intelligence
EU Green Deal procurement mandates specifying E0 and E1 emission classifications are forcing supply-side reconfiguration toward certified low-emission grades, compressing margins for commodity producers while rewarding integrated operators with captive resin technology and documented chain-of-custody systems.
Pricing Analysis
Value-based pricing anchors on emission certification tier and density uniformity outcomes rather than raw material throughput alone. Three-tier pricing structure across premium, standard, and economy levels separates E0-certified eco-friendly grades from E1 commercial grades and uncertified commodity imports. Pricing pressure stems from Chinese spot market flooding into European furniture manufacturing clusters. Volume furniture producers in Vietnam and Mexico exhibit highest price sensitivity, while German bespoke kitchen manufacturers accept substrate premiums for defect-free finishing.
Supply Chain Analysis
Regional distribution centers in Germany, Poland, and Romania operate hub-and-spoke patterns feeding Central European furniture manufacturing clusters. Raw material dependencies center on Baltic and Nordic softwood fiber, urea-formaldehyde resin, and intumescent additives for fire-retardant grades. Supply chain risk concentrates in single-source vulnerability for methanol-derived resins tracking natural gas benchmarks. Distribution runs through direct mill-to-fabricator relationships for high-volume accounts, with distributor layers serving just-in-time construction markets in the US Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous press digitalization is displacing legacy batch press installations, with real-time density scanning and IoT-enabled feedback loops now defining quality benchmarks for high-volume MDF operations.
For Market Incumbents: Deploy backward integration into captive resin synthesis capabilities to secure formulation expertise for low-emission adhesive systems. Consolidate capacity around continuous press technology investments in Poland and Romania that achieve density uniformity improvements. Defend against cross-laminated timber substitution in mid-rise commercial structural applications by accelerating fire-retardant grade certification. For New Entrants and Emerging Players: Capture import substitution potential in India's moisture-resistant grade segment, where urban housing stock expansion in Mumbai and Bangalore outpaces domestic panel capacity. Target commercial interior build-outs requiring BIS-certified engineered wood products. Establish B2B platform linkages to custom cabinetry shops, compressing distributor layers in fragmented renovation markets. For Investors and Strategic Acquirers: The window for entry favors integrated forestry-to-panel operators with Central and Eastern European manufacturing footprints and established EU Green Deal compliance infrastructure. Long-term viability hinges on backward integration into timberland assets and forward linkages to furniture manufacturing. Watch for inflection signals in bio-based resin convergence trials pairing tannin-lignin adhesive systems with continuous press retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Press Technology Retrofit | Real-time density scanning achieves 0.5 mm thickness tolerances across extended production runs. |
| Bio-Based Resin Convergence | Tannin-lignin adhesive systems open premium positioning in Nordic green building certification schemes. |
| Direct-to-Fabricator Digital Channels | B2B platforms compress distributor layers in North American custom cabinetry markets. |
| Backward Integration into Forestry Assets | Captive fiber supply secures cost advantages against Baltic timber market volatility. |
| E0 Emission Certification Investment | Documented chain-of-custody systems unlock EU Green Deal public tender volumes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this MDF market analysis. Primary interviews with panel mill operations directors, furniture manufacturing procurement leads, resin formulation chemists, and distribution channel partners were cross-validated against ECHA REACH substance evaluations, EPA Toxic Substances Control Act filings, and MIIT GB standard updates. Bottom-up capacity assessments across Shandong, Guangdong, and Pearl River Delta manufacturing belts were reconciled with top-down demand modeling from construction and furniture verticals.
Production volume data from customs records and industry association disclosures were reconciled against end-use consumption patterns across furniture, cabinetry, flooring, and decorative panel applications. Segmentation dimensions modeled include product type tier, emission certification grade, application vertical, and regional manufacturing hub clustering. CAGRs were derived from trend extrapolation of continuous press technology diffusion rates and bio-based resin substitution trajectories, stress-tested against energy price volatility scenarios affecting urea-formaldehyde input costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory acceleration in formaldehyde emission ceilings and breakthrough commercialization of soy-protein adhesive systems. Forecasts reflect documented assumptions regarding continuous press retrofit timelines and EU Green Deal procurement mandate expansion. Periodic stress-testing of base assumptions is recommended against evolving ECHA substance evaluation criteria and regional carbon accounting rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
HORECA Furniture Market
Furniture
Ergonomic Chair for Children Market
Furniture
Netherlands Home Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Australia Smart Furniture Market
Furniture
School Furniture Market
Furniture
Global Folding Furniture Market
Furniture
Study Carrels Market
Furniture
Contract Furniture and Furnishing Market
Furniture
Back Mount Frames Market
Furniture
Plastic Furniture Market
Furniture
RTA Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
North America Home Furniture Market
Furniture
Europe Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market