
 Dining Table Market | 2026-2036
Dining Table Market Size, Share, and Industry Trends Forecast 2026-2036
Dining Table Market Analytics
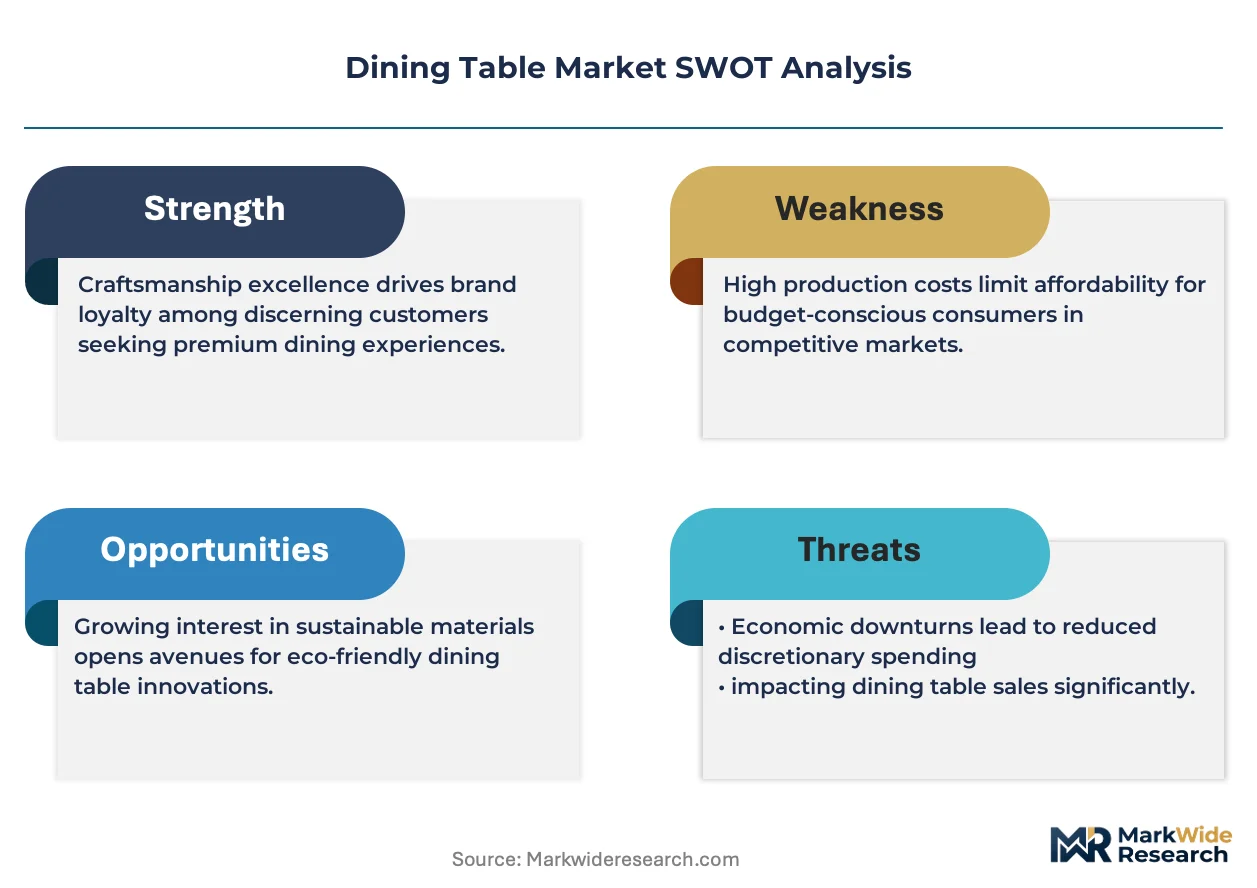
ISO 14001 environmental management certification is redrawing competitive boundaries in dining table manufacturing, favoring suppliers with audited supply chain traceability. Inter IKEA Systems B.V. leverages its captive forestry operations and flat-pack logistics to sustain margin discipline across price tiers. Ashley Furniture anchors North American mass-market distribution through vertically controlled retail networks. Ethan Allen competes on made-to-order craftsmanship, commanding premium positioning in the traditional style segment.
A dining table is a horizontal surface furniture piece, typically 28 to 30 inches in height, engineered for seated meal consumption and supporting distributed loads of 100 to 300 pounds depending on construction. Primary manufacturing employs hardwood lumber, engineered wood substrates, tempered glass, or welded steel frames, finished with moisture-resistant coatings to withstand thermal cycling from hot serveware. The wood material segment dominates value capture due to sustained consumer preference for natural grain aesthetics and perceived durability, while metal and glass combinations represent the fastest-growing structural category in modern and industrial style portfolios. Extendable tables concentrate margin pools in urban residential channels where space constraints drive functional premiumization.
The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, directly constraining substrate selection for US-bound manufacturers, while REACH restricts hazardous substance use in European coatings and adhesives. The EU Timber Regulation mandates due diligence on illegal logging, elevating compliance costs for wood-sourced suppliers without chain-of-custody documentation. Stakeholders must monitor evolving extended producer responsibility frameworks in key demand jurisdictions, as these will increasingly dictate end-of-life collection obligations and circular design requirements.
Market Dynamics
Urban space compression is restructuring demand toward multifunctional furniture, with extendable and drop-leaf dining table designs capturing disproportionate margin pools from multi-family residential developers in dense metropolitan zones.
Growth Catalysts
- EU Timber Regulation:Due diligence mandates on illegal logging are accelerating chain-of-custody investments, differentiating certified European suppliers from undifferentiated Asian exporters and creating premium positioning for documented sustainable sourcing.
- Engineered wood substrates:Cross-laminated timber and high-density fiberboard are enabling thinner, lighter table constructions without sacrificing load-bearing capacity, opening logistics efficiencies for flat-pack distribution models.
- China's Zhejiang cluster:Integrated supply chains spanning raw timber import, CNC machining, and containerized export are compressing production cycle times and sustaining cost-competitive positioning for global mass-market channels.
Market Restraints
- Hardwood lumber cost volatility:Oak and walnut price swings tied to North American milling capacity constraints are compressing gross margins for solid-wood specialists unable to pass through material increases.
- Formaldehyde emission controls:EPA TSCA Title VI and REACH restrictions on composite wood products are elevating compliance costs for manufacturers reliant on conventional particleboard substrates.
- Steel and aluminum tariffs:Trade policy friction on metal inputs is inflating landed costs for industrial-style table frames, particularly affecting suppliers without captive metal fabrication or alternative sourcing corridors.
Strategic Opportunities
- India's urban housing stock:Underpenetrated organized furniture retail in tier-two cities creates whitespace for modular dining systems targeting 800-1200 square foot apartment formats.
- Extended producer responsibility frameworks:Emerging take-back mandates in France and the Netherlands are rewarding circular design capabilities, including disassembly-friendly joinery and material passport documentation.
- Digital fabrication convergence:Parametric design software paired with robotic CNC routing is enabling mass customization at batch-size-one economics, collapsing the lead-time gap between made-to-order and mass production.
Industry Challenges
- CAD-to-factory translation:Shortage of technicians capable of programming five-axis CNC workflows for complex joinery is constraining throughput at mid-scale manufacturers investing in automation.
- ISO 14001 audit timelines:Eighteen-month certification cycles for environmental management systems are delaying supplier qualification for European retail tenders with mandatory sustainability credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dining Table Market |
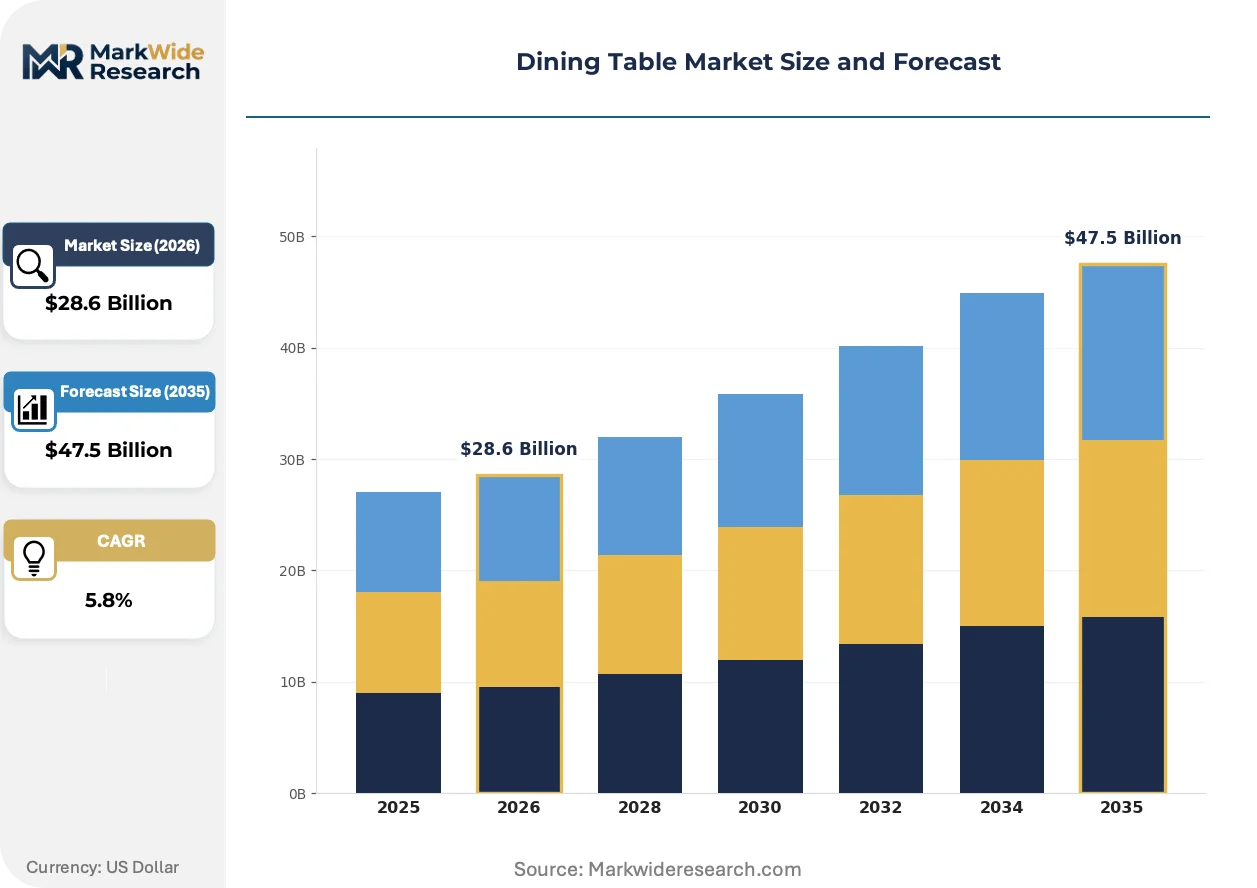
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Tables, Rectangular Tables, Extendable Tables, Drop-leaf Tables Material: Wood, Glass, Metal, Plastic Style: Modern, Traditional, Rustic, Industrial Size: Small, Medium, Large, Extra Large |
| Companies Covered | Inter IKEA Systems B.V., Ashley Furniture Industries, Ethan Allen, MillerKnoll, Wayfair, Williams-Sonoma, Steelcase, Godrej & Boyce Manufacturing Company, KOKUYO Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dining Table Market Evolving Landscape
Material science advances and regulatory disclosure requirements are converging to redefine competitive advantage, favoring manufacturers with integrated testing laboratories and transparent supply chain documentation over assembly-only operations.
Cross-laminated timber is displacing traditional hardwood aprons in extendable table mechanisms, delivering equivalent torsional rigidity at 40% reduced mass. Scandinavian and Japanese residential developers are specifying CLT-core designs for high-rise dining furniture, compressing freight costs and enabling single-person assembly without structural compromise.
California's Title 24 building efficiency standards are mandating low-emitting materials in new residential construction, directly constraining substrate selection for dining tables installed in compliant units. Manufacturers serving West Coast multi-family channels are reformulating adhesives and finishes to meet combined VOC thresholds, with compliance costs concentrated in small-batch artisan producers lacking in-house chemistry capabilities.
Multi-channel inventory unification is collapsing the distinction between contract and retail procurement, with hospitality specifiers now accessing the same SKUs as individual consumers through B2B portals. Property developers in Germany and Australia are leveraging this convergence to standardize dining furniture across portfolio properties, extracting volume pricing without sacrificing design consistency or shortening replacement cycles.
Dining Table Market Segmentation
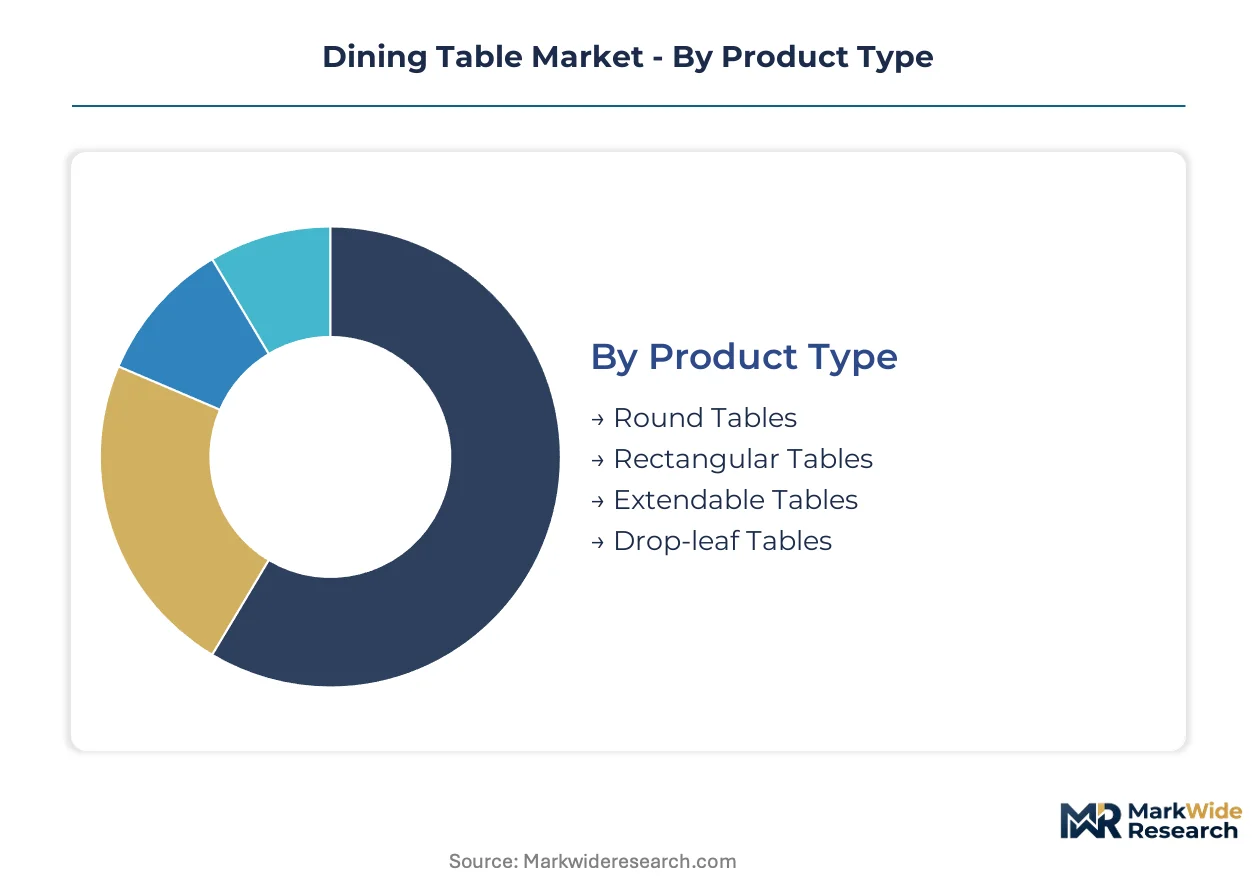
Dining table segmentation reveals how functional requirements and aesthetic preferences partition purchasing decisions across residential and contract channels. Material choices and form factors carry disproportionate margin implications due to supply chain complexity and assembly labor intensity.
Product Type:
Margin pools concentrate in space-adaptive designs where engineering complexity justifies premium positioning against commodity fixed-form alternatives.
- Round Tables:Pedestal or tripod base constructions optimize floor space efficiency in compact dining zones. Demand clusters in urban apartment renovations across Germany and Japan where circular traffic flow matters more than seating density.
- Rectangular Tables:Linear apron-and-leg assemblies dominate volume production due to standardized dimensional modules and efficient material yield from sheet goods. North American suburban single-family construction sustains procurement of six-to-eight-seat formats.
- Extendable Tables:Synchronized leaf mechanisms with metal glide hardware command 40-60% price premiums over fixed equivalents. Multi-family developers in London and Singapore specify these for convertible dining-living layouts.
- Drop-leaf Tables:Hinged side panels fold to sub-20-inch depths for corridor clearance. Aging-in-place retrofits across Scandinavian social housing programs drive specification of wheelchair-accessible variants.
The dominant share belongs to Rectangular Tables, while Extendable Tables is closing the gap fastest.
Material:
Cost tier stratification separates certified sustainable hardwoods from engineered substrates and synthetic alternatives with divergent compliance burdens.
- Wood:Solid hardwood lumber and veneered engineered cores deliver thermal mass and repairability. EPA TSCA Title VI and EU Timber Regulation chain-of-custody documentation now gates access to California and Northern European retail channels.
- Glass:Tempered or laminated transparent tops create visual lightness in open-plan interiors. Hospitality specifiers in Dubai and Miami favor these for beachfront venues where salt corrosion attacks metal and wood.
- Metal:Welded steel or aluminum frames with powder-coated finishes enable slender profiles impossible in timber. Industrial-style portfolios in Brooklyn and Shoreditch source these from Turkish and Vietnamese fabrication clusters.
- Plastic:Injection-molded polypropylene or polycarbonate shells suit outdoor and institutional deployment. Brazilian educational furniture tenders specify UV-stabilized grades for uncovered cafeteria installations.
Wood commands the volume base, though Metal is expanding most quickly in contract specification.
Style:
Application context determines style selection, with residential renovation cycles running shorter than hospitality replacement timelines.
- Modern:Minimalist lines, hidden joinery, and neutral palettes align with contemporary architecture. South Korean apartment developers specify these for 25-35 square meter studio formats.
- Traditional:Turned legs, carved aprons, and dark stains reference 18th-century precedents. Secondary market demand in the US Southeast sustains domestic artisan production of mahogany and cherry variants.
- Rustic:Live-edge slabs, distressed finishes, and visible hardware evoke craft authenticity. Mountain resort properties in Colorado and the Alps procure these for lobby and suite dining installations.
- Industrial:Exposed welding, reclaimed timber, and cast iron bases target loft conversions. Melbourne and Berlin co-living operators standardize on these for brand consistency across portfolio properties.
Modern styling leads specification frequency, while Industrial is gaining share fastest among millennial-first-time-buyer segments.
Size:
Customer type and dwelling footprint dictate size selection, with developer procurement favoring standardized modules over custom dimensions.
- Small:Two-to-four-seat formats under 48 inches suit breakfast nooks and studio apartments. Tokyo and Hong Kong micro-unit developers specify wall-mounted or nesting variants.
- Medium:Four-to-six-seat dimensions between 48 and 72 inches balance everyday utility with occasional entertaining. This tier captures the median in European mass-market retail.
- Large:Eight-to-ten-seat tables exceeding 72 inches anchor dedicated dining rooms in North American suburban construction. Custom builders in Texas and Florida report sustained demand for 96-inch and longer formats.
- Extra Large:Twelve-plus seating for hospitality banquet and residential estate applications. Saudi royal compound and Nigerian private residence procurement drives ultra-premium commissioning of single-slab hardwood tops.
Medium dimensions dominate unit volume, though Small formats are climbing the fastest as urban density intensifies across Asian megacities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European distribution networks for flat-pack furniture, while China's Ningbo-Zhoushan port complex anchors Asia-Pacific export corridors for finished wood products.
United States
Multi-family residential construction in Austin and Nashville drives specification of space-efficient extendable formats. EPA TSCA Title VI formaldehyde emission rules constrain substrate selection for California-bound shipments. North Carolina's Catawba Valley furniture cluster sustains domestic hardwood milling and upholstery integration.
Germany
Energy-efficient building renovation programs in Berlin and Hamburg accelerate replacement cycles for low-emitting dining furniture. EU Timber Regulation due diligence mandates elevate documentation requirements for wood-sourced suppliers. The Black Forest region hosts precision metal fabrication for synchronized table extension mechanisms.
China
Urban micro-apartment development in Shenzhen and Hangzhou concentrates demand for nesting and wall-mounted dining solutions. MIIT industrial standards govern structural safety testing for exported furniture. Zhejiang province's integrated supply chains span timber import, CNC machining, and containerized export to European and North American channels.
India
Tier-two city housing stock expansion in Pune and Ahmedabad creates whitespace for modular dining systems targeting compact apartment formats. BIS furniture safety standards are tightening structural load-testing protocols. Gujarat's Sanand industrial corridor attracts particleboard and engineered wood substrate manufacturing for domestic cost-competitive positioning.
Japan
Shrinking household sizes in Tokyo and Osaka sustain preference for drop-leaf and foldable dining formats. METI circular economy guidelines encourage disassembly-friendly joinery and material passport documentation. The Aichi prefecture cluster concentrates robotic CNC routing for precision component fabrication.
Dining Table Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions, producing a tiered structure where scale-driven players anchor mass-market channels while family-owned workshops occupy artisan positioning. Three archetypes dominate: vertically integrated retailers controlling captive forestry and logistics; contract furniture specialists serving hospitality and corporate procurement; and platform-native brands leveraging direct-to-consumer distribution. Consolidation pressures favor acquisition of regional specialists for geographic coverage, while portfolio diversification into adjacent seating and storage categories deepens account relationships.
Within the vertically integrated tier, Inter IKEA Systems B.V. and Ashley Furniture Industries exemplify scale-driven positioning through captive supply chains and controlled retail networks. Ethan Allen occupies a position in the made-to-order craftsmanship segment, representing premium-tier differentiation through traditional manufacturing approaches. These three anchors illustrate how competitive advantage in dining table manufacturing increasingly depends on supply chain control depth rather than assembly capability alone.
| Leading Market Players |
|---|
| Inter IKEA Systems B.V. |
| Ashley Furniture Industries |
| Ethan Allen |
| MillerKnoll |
| Wayfair |
| Williams-Sonoma |
| Steelcase |
| Godrej & Boyce Manufacturing Company |
| KOKUYO Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between North American hardwood mills and mass-market furniture manufacturers lock in supply access and price visibility across volatile lumber cycles. These arrangements insulate vertically integrated players from spot-market swings while exposing artisan producers to margin compression when oak and walnut prices spike.
Pricing Analysis
Volume-discount tiering structures separate contract hospitality procurement from individual retail purchases, with developers extracting pricing concessions unavailable to consumers. Certification grade and customization level drive price differentiation, with ISO 14001-audited suppliers commanding premiums over undifferentiated competitors. Cost compression in the mid-market tier is intensifying because engineered wood substrate compliance with EPA TSCA Title VI elevates formulation expenses. Multi-family residential developers exhibit highest price sensitivity, while ultra-premium estate commissioning shows lowest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites containerized movement of finished dining tables from China's Zhejiang cluster to European and North American distribution hubs. Manufacturing gravity centers on China, Vietnam, and Turkey, with raw material dependencies spanning North American hardwood lumber, Indonesian plywood cores, and Turkish steel tubing. Single-source vulnerability concentrates in synchronized leaf mechanism hardware sourced from German precision fabricators. Distribution runs through vertically controlled retail networks for mass-market penetration and direct-to-consumer portals for specialist positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against ready-to-assemble flat-pack alternatives and multifunctional kitchen islands that displace dedicated dining furniture in compact dwellings.
For Market Incumbents: Shield core margin pools by securing captive forestry operations or long-term timber offtake agreements that neutralize hardwood cost volatility. Accelerate ISO 14001 certification timelines to preempt European retail tender requirements before competitors qualify. Vertical integration into CNC machining capabilities preserves throughput against technician shortages constraining automation adoption. For New Entrants and Emerging Players: Differentiate on circular design capabilities including disassembly-friendly joinery and material passport documentation to capture emerging extended producer responsibility mandates in France and the Netherlands. India's tier-two cities present the most penetrable whitespace, with modular dining systems targeting 800-1200 square foot apartment formats. A direct-to-consumer digital fabrication model collapses lead times between made-to-order and mass production economics. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale manufacturers with installed CNC capacity and pending environmental certifications that strategic buyers can activate through distribution integration. Long-term viability favors suppliers with demonstrated chain-of-custody documentation and testing laboratory capabilities over assembly-only operations. Watch parametric design software adoption rates as the inflection indicator for mass customization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Chain-of-Custody Certification Investment | EU Timber Regulation compliance gates access to Northern European retail channels for wood-sourced suppliers. |
| Robotic CNC Routing Deployment | Aichi prefecture precision fabrication capabilities enable batch-size-one mass customization at competitive economics. |
| Flat-Pack Logistics Optimization | Inter IKEA Systems B.V. demonstrates how captive distribution networks sustain margin discipline across price tiers. |
| Extended Producer Responsibility Preparation | France and Netherlands take-back mandates reward circular design capabilities including material passport documentation. |
| Direct-to-Consumer Channel Launch | Platform-native brands bypass wholesale margin extraction while capturing customer data for customization algorithms. |
Research Methodology
Cross-validation between trade association shipment data and customs import records anchors the qualitative findings on regional demand patterns. Primary interviews with furniture manufacturing executives, multi-family residential developers, hospitality procurement managers, and CNC programming technicians combined with secondary validation from EPA regulatory filings, EU Timber Regulation enforcement reports, and MIIT industrial standards documentation. Bottom-up production capacity estimates and top-down consumption surveys triangulate market sizing across the analysis window.
Sensitivity analysis around hardwood lumber price volatility and tariff exposure on metal inputs stress-tests projection robustness. Segmentation modeling spans product type, material substrate, style archetype, and size tier alongside distribution channel structure and regional regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for structural shifts including urban space compression and digital fabrication convergence. Cross-laminated timber adoption rates and extended producer responsibility implementation timelines serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained multi-family residential construction momentum or stable trade policy on metal inputs would require recalibration. Forecasts reflect documented assumptions regarding certification adoption curves and automation penetration rates. Practitioners should keep alternative scenarios live as EU Timber Regulation enforcement intensity and California Title 24 building efficiency standard expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Kitchen and Dining Furniture Market