
 Kitchen Islands and Carts Market | 2026-2036
Kitchen Islands and Carts Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Islands and Carts Market Foresight
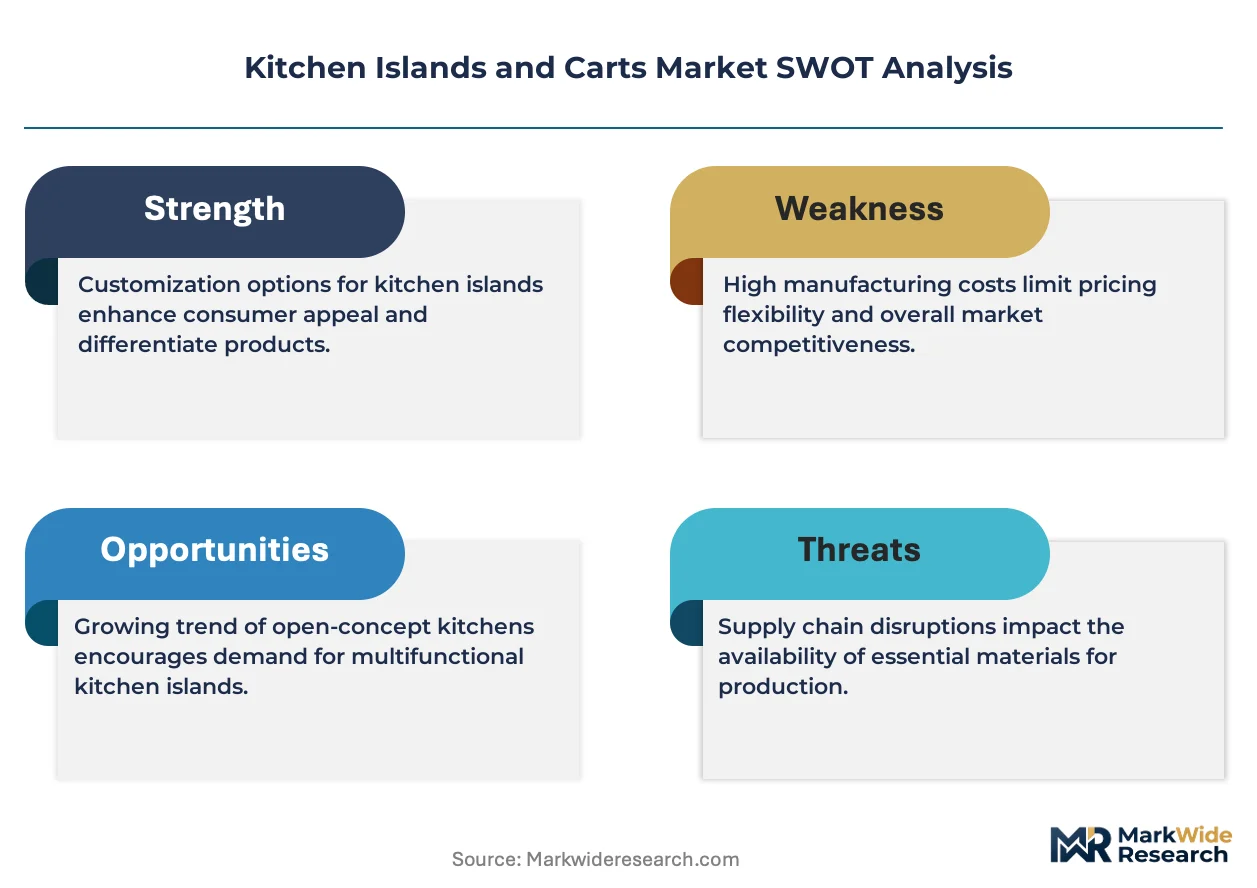
Solid hardwood is recalibrating product economics across the Kitchen Islands and Carts Market as manufacturers retreat from composite substrates facing stricter emission testing. John Boos & Co. anchors its premium positioning through butcher-block specialization and domestic hardwood sourcing. IKEA International Group leverages flat-pack logistics to control costs across mass-market distribution. Seville Classics, Inc. competes in metal-framed utility segments with powder-coated steel construction.
Kitchen islands and carts are freestanding or wheeled food-prep and storage platforms, typically constructed from hardwood, stainless steel, or engineered stone with dimensions spanning 24 to 60 inches in width and load ratings from 150 to 500 pounds, designed to extend counter space and organize culinary workflows in residential and light-commercial kitchens. Stationary islands command the largest volume share due to permanent-installation preference in single-family renovations, while portable carts capture faster growth from apartment and rental housing flexibility needs. Wood material segments retain the deepest margin pools through premium-grade hardwood positioning, though metal substrates gain traction in commercial-style residential aesthetics.
The EPA enforces TSCA Title VI formaldehyde limits on composite wood products, compelling domestic manufacturers to certify supply chains or shift to solid-material construction. California Air Resources Board (CARB) Phase 2 standards extend compliance obligations for products sold into the state, effectively nationalizing emission benchmarks. Stakeholders must monitor state-level chemical disclosure laws and federal tariff schedules on imported hardwoods to protect margin structures and sourcing flexibility.
Market Dynamics
Millennial homeowners are redirecting residential renovation budgets toward permanent kitchen infrastructure, forcing manufacturers to recalibrate product portfolios away from entry-level disposable furniture toward heirloom-grade construction with certified material sourcing.
Growth Catalysts
- TSCA Title VI Compliance:EPA formaldehyde emission limits on composite wood products are accelerating solid hardwood substitution across premium product lines, expanding addressable margin pools for domestic manufacturers with certified supply chains.
- Suburban Housing Markets:Single-family renovation activity concentrates in Texas and Florida metropolitan statistical areas, creating localized demand surges for stationary island installations with permanent utility connections.
- Butcher-Block Specialization:End-grain hardwood construction techniques are capturing chef-influenced residential segments through superior knife-friendliness and repairability compared to synthetic alternatives.
Market Restraints
- Hardwood Input Volatility:North American white oak and maple lumber pricing fluctuates with export demand from Asian furniture manufacturers, compressing margin predictability for solid-wood producers.
- CARB Phase 2 Nationalization:California Air Resources Board standards effectively mandate compliance for all interstate commerce, imposing testing and certification costs that disadvantage small-scale fabricators without dedicated quality infrastructure.
- Flat-Pack Substitution:Engineered particleboard alternatives with veneer finishes threaten entry-market positioning through 60-70% cost advantages despite shorter functional lifespans.
Strategic Opportunities
- Rental Housing Flexibility:Portable cart segments with locking caster systems and compact footprints address apartment dweller needs in urban core markets with high tenant turnover and space constraints.
- Light-Commercial Crossover:Residential kitchens are adopting NSF-certified stainless steel work surfaces and shelving from foodservice equipment standards, opening specification channels through restaurant supply distributors.
- Powder-Coated Steel Aesthetics:Industrial-style metal framing with customizable color finishes is penetrating design-conscious segments seeking commercial-kitchen visual language without professional-grade cost structures.
Industry Challenges
- Skilled Joinery Labor Scarcity:Domestic manufacturers face recruitment gaps for traditional woodworking crafts including mortise-and-tenon construction and hand-planed surface finishing.
- Multi-Jurisdiction Certification Timelines:Products requiring both EPA TSCA composite wood certification and state-level chemical disclosure compliance face 90-120 day approval cycles that delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Islands and Carts Market |
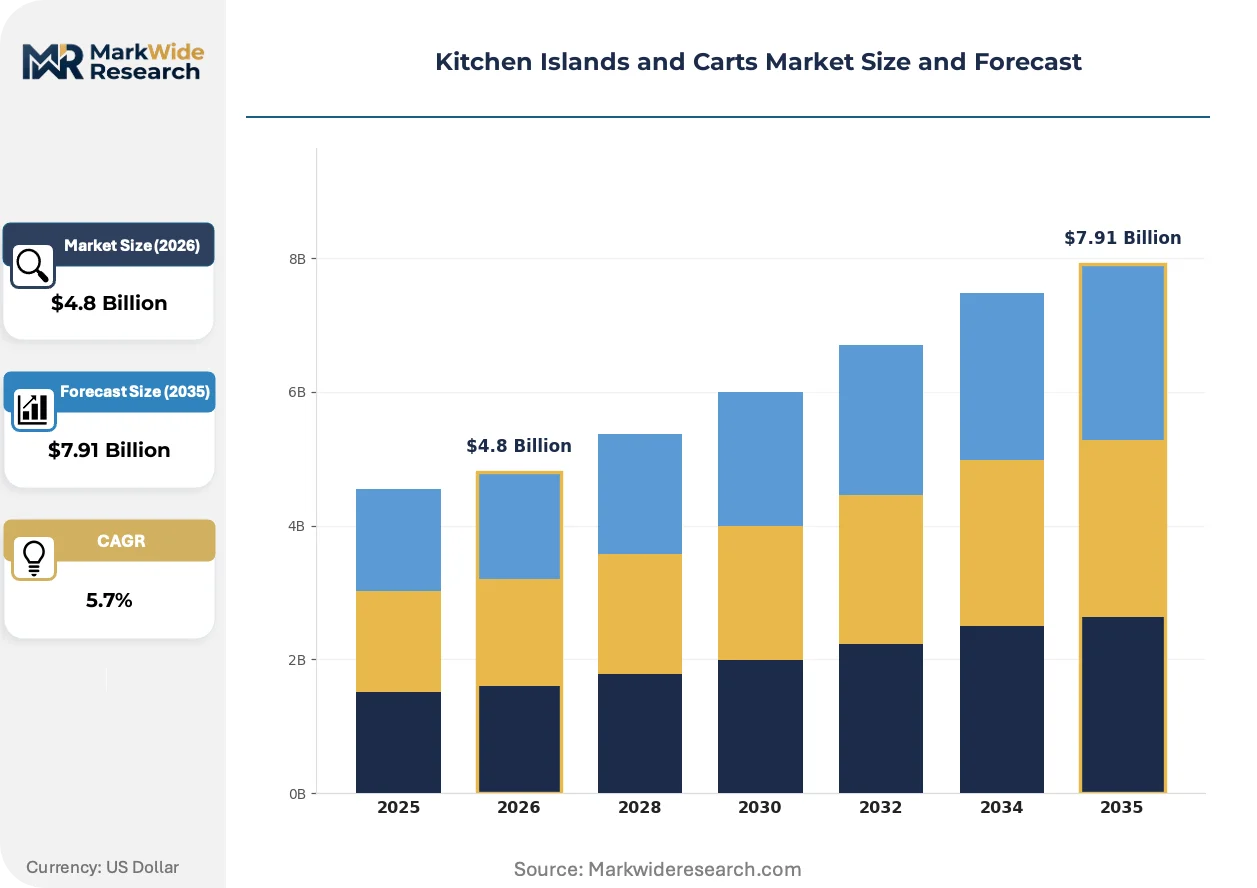
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Carts, Stationary Islands, Mobile Islands, Storage Units Material: Wood, Metal, Plastic, Stone Style: Modern, Rustic, Traditional, Contemporary Size: Small, Medium, Large, Custom |
| Companies Covered | Catskill Craftsmen, Inc., Seville Classics, Inc., IKEA International Group, John Boos & Co., Linon Home Décor Products, Inc., Crosley Brands, Inc., Winsome Trading, Inc., Trinity, Home Styles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Islands and Carts Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape construction methodologies, with manufacturers abandoning legacy substrate systems in favor of certified solid materials and modular assembly architectures.
Quartz-engineered stone surfaces are integrating into mid-premium island configurations as homeowners prioritize stain resistance and minimal maintenance over natural stone patina development. Kitchen designers specify these materials for baking and pastry workstations where temperature stability matters. This integration is compressing the traditional granite fabrication supply chain by enabling factory-cut dimensional accuracy.
EPA enforcement of TSCA Title VI formaldehyde limits is eliminating uncertified composite wood imports from Southeast Asian supply chains. Domestic manufacturers must maintain chain-of-custody documentation or shift entirely to solid lumber construction. The stationary island segment bears the highest compliance burden due to larger surface areas subject to emission testing protocols.
Direct-to-consumer configuration tools are displacing traditional retail showroom dependence as millennial buyers research dimensions, materials, and assembly requirements through augmented reality applications before purchase. Big-box home improvement channels respond with expanded drop-ship partnerships that reduce inventory carrying costs. This behavioral shift concentrates in suburban markets where delivery logistics favor parcel-scale packaging over white-glove installation services.
Kitchen Islands and Carts Market Segmentation
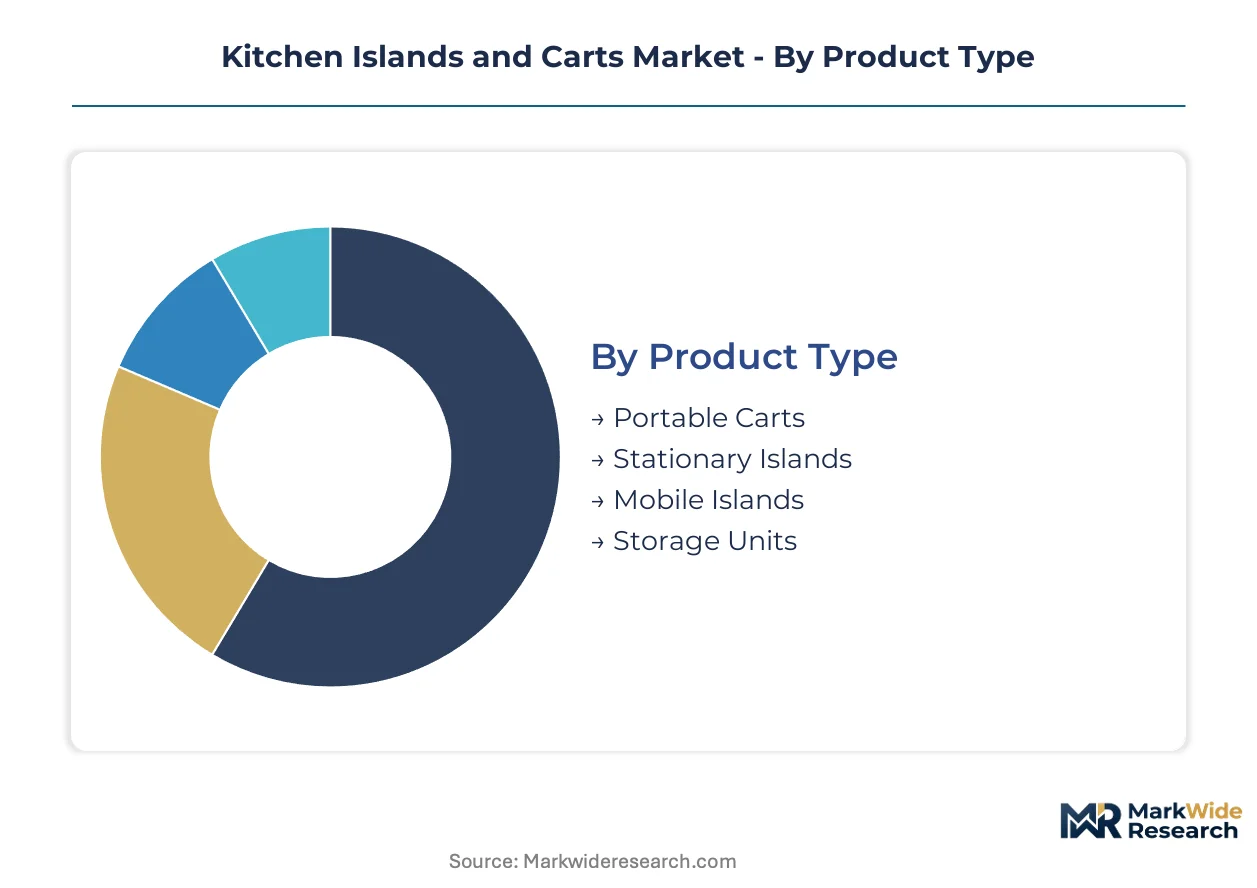
Segmentation in the Kitchen Islands and Carts Market determines sourcing strategies, margin architecture, and channel placement. Product mobility and material composition create distinct competitive arenas with divergent regulatory exposure and customer lifetime value profiles.
Product Type:
Mobility specifications define installation complexity, utility connection requirements, and replacement frequency across residential and light-commercial deployments.
- Portable Carts:Wheeled platforms with locking caster systems and compact footprints serve apartment dwellers and rental housing markets where permanent installation is prohibited. Demand concentrates in urban core markets with high tenant turnover, driven by space constraints and lease restrictions on structural modifications.
- Stationary Islands:Permanent-installation platforms with fixed utility connections for electrical and plumbing integration dominate single-family renovation spending. Suburban housing markets across Texas and Florida generate concentrated demand for these installations during kitchen infrastructure upgrades.
- Mobile Islands:Hybrid designs with removable caster systems bridge permanent and temporary use cases, appealing to homeowners anticipating future relocation.
- Storage Units:Specialized configurations emphasizing enclosed cabinetry and pantry organization serve secondary kitchen zones and basement food-prep areas.
Stationary islands lead on scale; portable carts lead on momentum.
Material:
Substrate selection determines emission compliance burden, supply chain geography, and end-use durability expectations across price tiers.
- Wood:Solid hardwood construction commands premium positioning through certified sourcing and repairability, though faces input volatility from North American white oak and maple export demand. TSCA Title VI compliance costs accelerate substitution away from composite substrates toward solid lumber.
- Metal:Powder-coated steel and stainless steel configurations penetrate design-conscious segments seeking commercial-kitchen aesthetics, with NSF-certified surfaces crossing over from foodservice equipment standards.
- Plastic:Polymer-based alternatives serve entry-market positioning with cost advantages and moisture resistance for outdoor kitchen applications.
- Stone:Quartz-engineered and natural stone surfaces integrate into mid-premium configurations prioritizing stain resistance and temperature stability for baking workstations.
Wood dominates revenue contribution; metal gains share fastest.
Style:
Aesthetic positioning aligns with housing stock age, regional design preferences, and social media-influenced renovation trends.
- Modern:Clean lines, minimal ornamentation, and integrated hardware serve contemporary suburban construction and influencer-driven renovation content.
- Rustic:Distressed finishes, reclaimed wood aesthetics, and farmhouse-inspired hardware dominate exurban and rural markets with older housing stock.
- Traditional:Raised-panel detailing, decorative molding, and classic hardware profiles align with established neighborhoods and resale-conscious renovations.
- Contemporary:Mixed-material experimentation and bold color applications target design-forward urban markets and custom specification channels.
Traditional maintains volume leadership; contemporary shows steepest expansion trajectory.
Size:
Dimensional categories reflect kitchen square footage constraints, workflow requirements, and customization willingness across customer segments.
- Small:Compact footprints under 36 inches width address galley kitchens, apartment layouts, and auxiliary prep zones with minimal spatial disruption.
- Medium:Standard 36-48 inch configurations balance workspace expansion with traffic flow preservation in typical suburban kitchen layouts.
- Large:Oversized platforms exceeding 48 inches serve open-concept renovations and entertainment-focused kitchen designs with multiple simultaneous users.
- Custom:Bespoke dimensional and feature specifications capture high-budget renovations with irregular spatial constraints or specialized functional requirements.
Medium sizes anchor volume; custom specifications deliver highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metropolitan corridor anchors North American demand for stationary kitchen islands as suburban single-family construction accelerates. Millennial homeowner renovation spending concentrates in Texas and Florida metropolitan statistical areas. Regulatory frameworks across major economies are reshaping material sourcing and compliance architectures.
United States
Suburban housing markets in Texas and Florida generate concentrated demand for permanent-installation islands with utility connections. The EPA enforces TSCA Title VI formaldehyde emission limits on composite wood products, compelling manufacturers to certify supply chains or shift to solid hardwood construction. Dallas-Fort Worth and Houston metropolitan areas lead renovation spending volumes.
Germany
Precision-engineered kitchen systems drive demand for modular island configurations with integrated appliance housing. The EU Green Deal and national building efficiency standards prioritize low-emission materials and circular construction practices. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate premium furniture manufacturing capacity.
China
Rapid urbanization and middle-class housing upgrades expand the addressable market for compact, multi-functional kitchen storage solutions. The Ministry of Ecology and Environment enforces GB standards on indoor air quality and formaldehyde emissions in wood-based panels. Manufacturing gravity centers on the Pearl River Delta and Yangtze River Delta export zones.
Canada
Cross-border supply chain integration with US markets sustains demand for hardwood-sourced island production. Health Canada and the PMRA oversee chemical safety standards for residential furniture and indoor air quality. Ontario and Quebec host established woodworking clusters serving North American distribution channels.
United Kingdom
Housing stock renovation and kitchen modernization programs sustain steady replacement demand. Building regulations and fire safety standards govern material specifications for permanent kitchen installations. Greater London and Southeast England concentrate higher-value custom specification activity.
Kitchen Islands and Carts Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers recalibrate away from composite substrates toward solid-material construction. The vendor base organizes into three tiers: mass-market flat-pack distributors, premium hardwood specialists, and metal-framed utility fabricators. Two strategic archetypes have emerged: certified-sourcing premium brands commanding margin premiums, and logistics-optimized scale players controlling cost structures. Competitive intensity centers on supply chain certification investments and direct-to-consumer channel development.
Within the premium hardwood tier, John Boos & Co. exemplifies butcher-block specialization through domestic sourcing architectures. IKEA International Group anchors mass-market positioning through flat-pack logistics and global distribution density. Seville Classics, Inc. occupies the metal-framed utility segment with powder-coated steel construction. These three entities represent divergent competitive vectors: certified material premiumization, cost-engineered scale, and industrial aesthetic crossover.
| Leading Market Players |
|---|
| Catskill Craftsmen, Inc. |
| Seville Classics, Inc. |
| IKEA International Group |
| John Boos & Co. |
| Linon Home Décor Products, Inc. |
| Crosley Brands, Inc. |
| Winsome Trading, Inc. |
| Trinity |
| Home Styles |
| Others |
Supply & Pricing Matrix
EPA TSCA Title VI formaldehyde emission standards gate qualified supply access and premium-tier pricing power for domestic manufacturers with certified hardwood sourcing architectures. Compliance investments compress margin structures for composite-substrate producers while solid-wood specialists capture pricing premiums through chain-of-custody documentation.
Pricing Analysis
North American white oak and maple lumber cost pass-through determines margin predictability across solid-wood product tiers. Three-tier pricing structure across premium hardwood, certified composite, and entry-level particleboard separates heirloom-grade positioning from disposable furniture alternatives. Price differentiation hinges on TSCA Title VI certification status and domestic sourcing verification. Cost compression in entry tiers intensifies because Asian export demand for hardwood inputs elevates raw material pricing. Rental housing buyers exhibit highest price sensitivity; custom renovation clients demonstrate lowest.
Supply Chain Analysis
Skilled joinery labor scarcity in Vietnam, Indonesia, and Malaysia constrains manufacturing capacity for hand-finished hardwood components. Raw material flows draw from Appalachian hardwood forests, Canadian maple stands, and European oak plantations. Single-source vulnerability concentrates in Southeast Asian engineered wood panel suppliers facing EPA enforcement exclusion. Distribution runs through big-box home improvement channels, direct-to-consumer drop-ship partnerships, and restaurant supply distributors for light-commercial crossover segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory-driven material substitution, with EPA TSCA Title VI enforcement accelerating demand for certified solid-wood construction.
For Market Incumbents: Deepen backward integration into Appalachian and Canadian hardwood sourcing to secure chain-of-custody documentation against EPA audit exposure. Expand certified joinery capacity in Texas and Florida metropolitan corridors where suburban renovation spending concentrates. Defend margin position through butcher-block specialization and domestic material verification that flat-pack competitors cannot replicate. For New Entrants and Emerging Players: Powder-coated steel fabrication automation offers a technology-first wedge into metal-framed utility segments with shorter certification timelines than composite wood compliance. Target apartment and rental housing markets in urban core geographies with portable cart configurations featuring locking caster systems. Pursue direct-to-consumer channel development through augmented reality configuration tools that displace traditional showroom dependence. For Investors and Strategic Acquirers: Roll-up economics work for certified-sourcing hardwood specialists because regulatory compliance creates defensible moats against low-cost Asian imports. The five-to-ten year viability window favors domestic manufacturers with established EPA documentation infrastructure. Acquisition target archetype: mid-scale fabricators with verified solid-wood supply chains and underdeveloped direct-to-consumer channels. Monitor EPA enforcement action intensity as inflection indicator for composite-substrate margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| TSCA Title VI Certification Investment | EPA compliance documentation unlocks premium-tier pricing and defensible market positioning against uncertified imports. |
| Direct-to-Consumer Channel Development | Augmented reality configuration tools displace traditional retail showroom dependence among millennial renovation buyers. |
| Butcher-Block Product Line Expansion | End-grain hardwood construction captures chef-influenced residential segments through superior knife-friendliness and repairability. |
| Light-Commercial Crossover Specification | NSF-certified stainless steel surfaces open restaurant supply distributor channels for residential kitchen adoption. |
| Portable Cart Mobility Innovation | Locking caster systems and compact footprints address apartment dweller needs in high-turnover urban rental markets. |
Research Methodology
Bottom-up residential renovation spending modeling reconciled against top-down hardwood supply chain tracking forms the analytical core of this study. Primary interviews with kitchen designers, millennial homeowner focus groups, certified lumber suppliers, and EPA compliance consultants combined with secondary validation from customs records, home improvement retail audit data, and TSCA enforcement disclosure filings. Triangulation across stakeholder perspectives and documentary sources ensures dimensional accuracy.
Historical trendline analysis of stationary island installation rates and portable cart unit shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product mobility specifications, material substrate categories, aesthetic style positioning, and dimensional size tiers alongside metropolitan statistical area renovation spending indices. CAGRs derived from regression analysis of housing stock age demographics and kitchen infrastructure upgrade cycles.
The model holds under steady EPA enforcement intensity and stable North American hardwood export demand; deviation in tariff schedules or accelerated CARB Phase 2 nationalization would shift supply chain economics and pricing structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Vietnam Kitchen Furniture Market