
 Kitchen and Dining Furniture Market | 2026-2036
Kitchen and Dining Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen and Dining Furniture Market Foresight
The EU Timber Regulation is decoupling European kitchen furniture demand from undocumented wood sources, forcing manufacturers to certify supply chains. MasterBrand Cabinets leverages its North American hardwood sourcing networks to sustain compliance advantages. Roche Bobois anchors its premium positioning through controlled European atelier production.
Kitchen and dining furniture comprises fixed and movable fixtures designed for food preparation, storage, and communal eating, typically constructed from engineered wood panels, solid timber, or metal frames with moisture-resistant surface treatments. Kitchen cabinets dominate product-type revenue due to built-in installation requirements and higher per-unit value, while metal-frame bar stools represent the fastest-expanding segment as open-plan residential layouts proliferate. Wood retains the largest material share though glass-accented modern styling commands premium pricing in urban household segments.
The EPA formaldehyde emission standards for composite wood products and California Air Resources Board ATCM requirements shape product chemistry and market access for US-bound manufacturers. REACH chemical restrictions in Europe and China's GB standards for indoor decoration materials similarly constrain adhesive and coating formulations. Stakeholders must monitor evolving cross-border timber certification requirements as sustainability disclosure obligations tighten across major demand centers.
Market Dynamics
The EU Green Deal's timber traceability mandates are forcing supply chain reconfiguration across kitchen furniture manufacturing, decoupling European demand from undocumented wood sources and elevating certified hardwood networks into competitive differentiators.
Growth Catalysts
- Urban residential renovation spending:Middle-class apartment upgrades in Chinese cities accelerate premium cabinet adoption, with modular kitchen systems capturing share from traditional carpentry.
- REACH chemical restrictions:European adhesive and coating reformulations are driving R&D investment in bio-based binders, creating first-mover advantages for compliant manufacturers.
- Open-plan residential layouts:Metal-frame bar stools represent the fastest-expanding product segment as kitchen-dining boundaries dissolve in Western apartment design.
Market Restraints
- North American hardwood supply concentration:MasterBrand Cabinets and similar players control certified sourcing networks, creating entry barriers for new competitors seeking EPA formaldehyde compliance.
- Engineered wood panel cost volatility:Resin and fiber input prices fluctuate with petrochemical feedstock markets, compressing margins for mid-tier manufacturers.
- Glass-accented modern styling substitution:Premium urban segments increasingly favor metal-glass hybrid furniture over solid timber, threatening traditional wood-dominant product lines.
Strategic Opportunities
- GB standards compliance in China:Indoor decoration material certifications create export pathways for European manufacturers with established ECHA-aligned testing protocols.
- Direct-to-consumer channel expansion:Configurator-driven online sales bypass traditional kitchen studio networks, capturing margin previously allocated to retail intermediaries.
- Atelier production convergence:Roche Bobois-style controlled European manufacturing models are replicable in secondary cities, marrying craftsmanship with scalable quality assurance.
Industry Challenges
- Cross-border timber certification timelines:EU Timber Regulation documentation requirements extend procurement cycles by 8-14 weeks, straining just-in-sequence kitchen installation schedules.
- California Air Resources Board ATCM alignment:US-bound manufacturers must maintain dual chemistry formulations to satisfy both EPA and state-level emission standards, complicating inventory management.
- Moisture-resistant surface treatment integration:Legacy cabinet lines require retrofitting with advanced coating systems to compete in humid climate markets, demanding capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen and Dining Furniture Market |
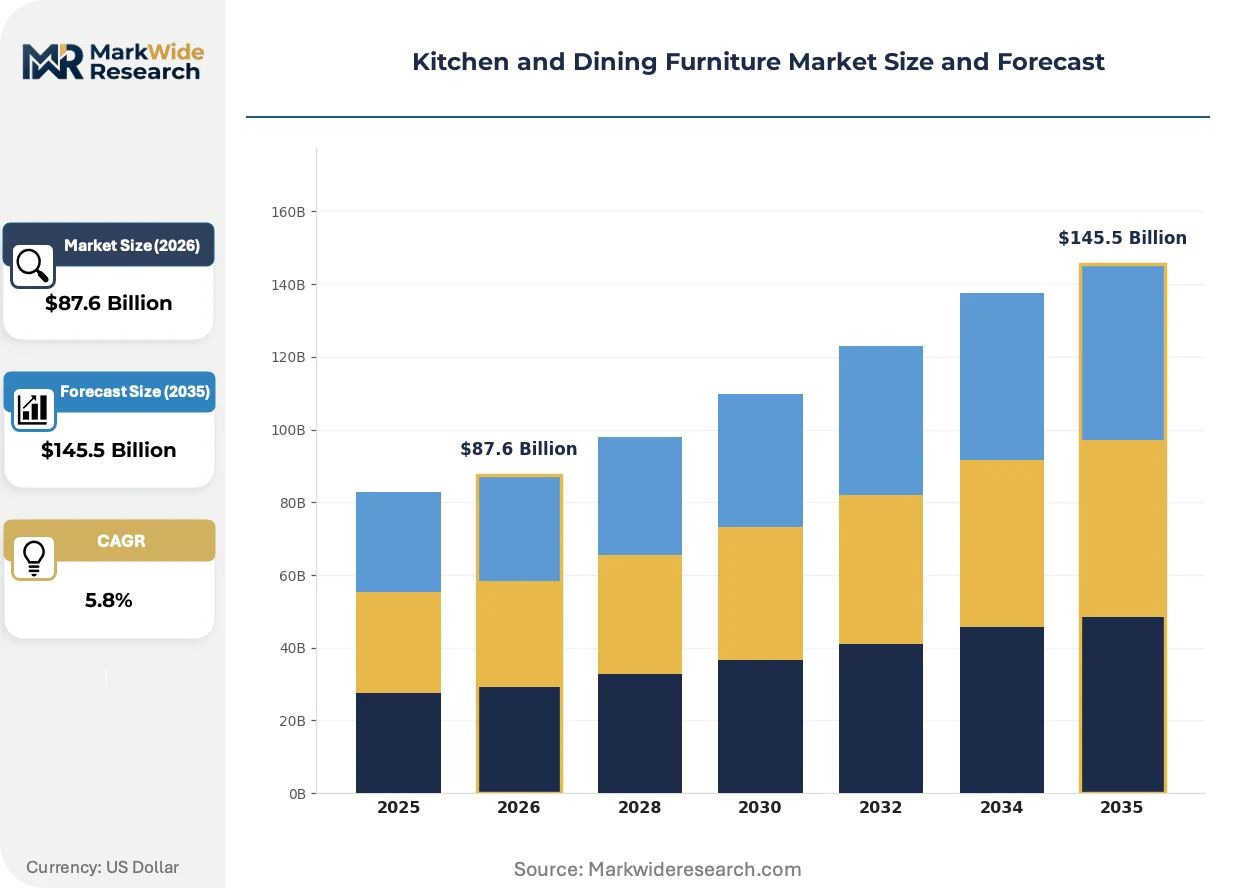
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dining Tables, Bar Stools, Sideboards, Kitchen Cabinets Material: Wood, Metal, Glass, Plastic Style: Modern, Contemporary, Rustic, Traditional End User: Households, Restaurants, Cafés, Hotels |
| Companies Covered | Merillat, Omega Cabinetry, MasterBrand Cabinets, Roche Bobois, Crate & Barrel, American Woodmark, Schrock Cabinetry, SieMatic, KraftMaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen and Dining Furniture Market Shifts & Advancements
Material chemistry and production geography are converging to reshape competitive positioning, with regulatory compliance becoming inseparable from product architecture rather than an aftermarket overlay.
Electrostatic powder coating systems are electrifying metal-frame furniture finishing, replacing solvent-based liquid applications. Urban millennial buyers in Berlin and Shanghai specify these finishes at accelerating rates. The technology is electrifying margin structures by eliminating VOC handling costs and enabling same-day color switching on production lines.
REACH SVHC candidate list expansions are tightening restrictions on formaldehyde-releasing adhesives in composite wood products. European manufacturers face reformulation deadlines that compress product development cycles. Kitchen cabinet producers serving Germany and France are accelerating bio-based resin partnerships to maintain market access.
Configurator-driven specification is displacing traditional kitchen studio consultations among time-constrained urban professionals. Direct digital channels capture preference data that feeds back into modular system design. This behavioral shift is most visible in Chinese first-tier cities and Scandinavian capitals, where apartment renovation timelines compress below six weeks.
Kitchen and Dining Furniture Market Segmentation
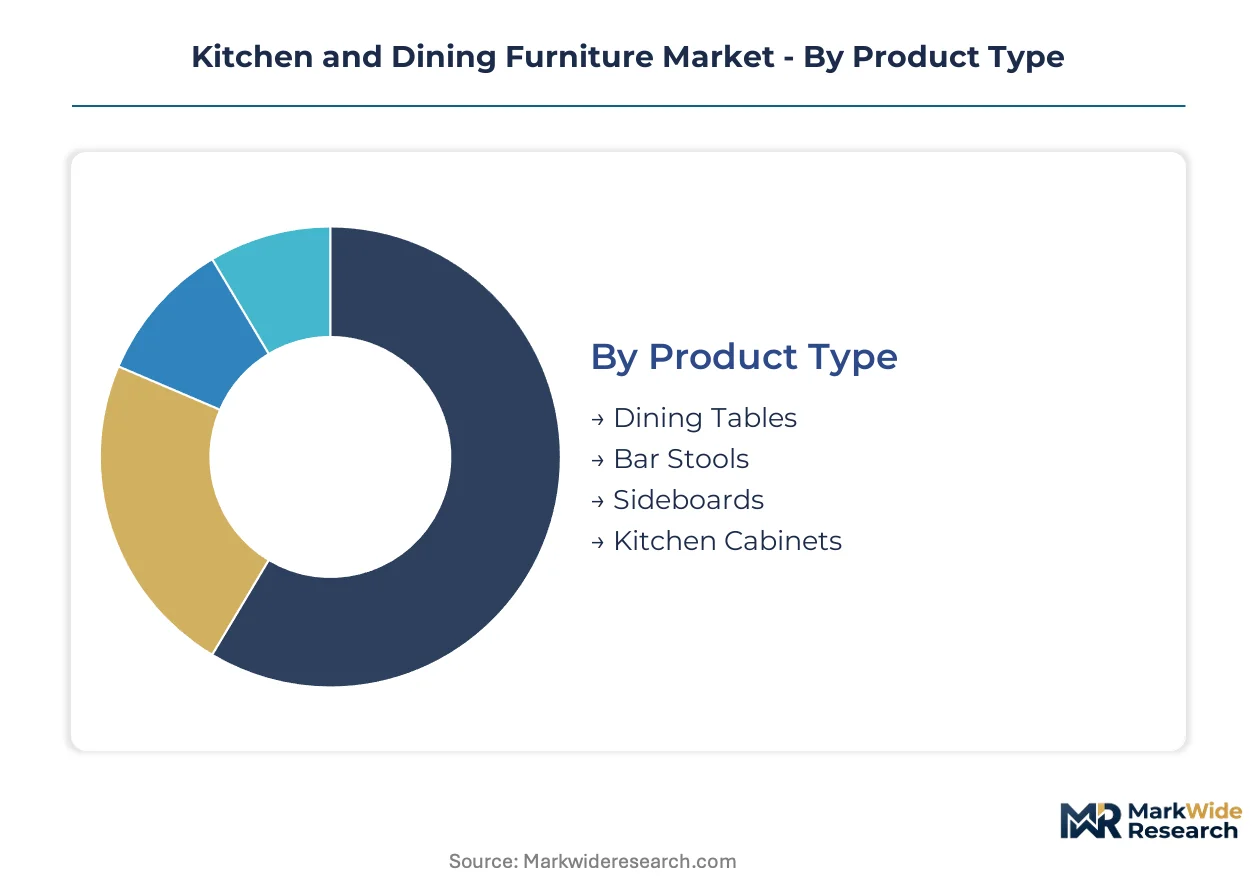
Kitchen and dining furniture segmentation reveals how installation permanence shapes purchasing behavior. Fixed installations like cabinets command project-based procurement cycles, while movable pieces follow faster replacement patterns. Material and style choices increasingly trace regulatory compliance requirements across major demand centers.
Product Type:
Integration depth varies sharply—built-in systems demand architectural coordination, while freestanding pieces enable standalone purchase decisions.
- Kitchen Cabinets:Engineered wood panel construction with moisture-resistant surface treatments dominates this segment. Urban residential renovation in Chinese cities accelerates modular system adoption over traditional carpentry. Built-in installation requirements create higher per-unit value and longer replacement cycles.
- Bar Stools:Metal-frame construction with electrostatic powder coating finishes is displacing solvent-based alternatives. Open-plan residential layouts in Berlin and Shanghai dissolve kitchen-dining boundaries, expanding demand for transitional seating. Urban millennial buyers specify these finishes at accelerating rates.
- Dining Tables:Solid timber and engineered wood surfaces anchor communal eating spaces across household and hospitality settings.
- Sideboards:Storage-forward designs support serving functions in compact urban apartments and restaurant back-of-house areas.
Kitchen cabinets lead volumes today; bar stools are gaining share fastest.
Material:
Cost tier stratification separates premium certified hardwood networks from commodity panel alternatives.
- Wood:Solid timber and engineered wood panels retain the largest material share, though sourcing complexity is rising. EU Green Deal timber traceability mandates are decoupling European demand from undocumented sources, elevating certified supply chains into competitive differentiators. EPA formaldehyde emission standards and California Air Resources Board ATCM requirements constrain composite wood chemistry for US-bound production.
- Metal:Steel and aluminum frames enable electrostatic powder coating systems that eliminate VOC handling costs. Metal-frame bar stools represent the fastest-expanding product category as open-plan layouts proliferate. Same-day color switching on production lines electrifies margin structures.
- Glass:Accent panels and tabletops command premium pricing in urban household segments favoring modern styling over solid timber.
- Plastic:Polymer constructions serve cost-sensitive hospitality and outdoor applications with moisture immunity.
Wood leads volumes today; metal is climbing the fastest.
Style:
Application context drives style selection—residential renovations favor cohesive system aesthetics, while hospitality procurement prioritizes durability and brand differentiation.
- Modern:Clean lines and minimal ornamentation dominate urban apartment upgrades. Glass-accented and metal-glass hybrid constructions command premium positioning in first-tier Chinese cities and Scandinavian capitals. Configurator-driven specification channels capture preference data that feeds back into modular system design.
- Contemporary:Evolving interpretations blend current trends with functional pragmatism for mainstream household adoption.
- Rustic:Reclaimed wood aesthetics and distressed finishes target secondary-city markets and experiential hospitality concepts.
- Traditional:Ornate detailing and classic proportions persist in heritage property renovations and formal dining contexts.
Modern styling leads volumes today; contemporary interpretations are expanding most quickly.
End User:
Customer type separates project-scale procurement with extended decision cycles from transactional household purchases.
- Households:Residential renovation spending by urban households accelerates demand for modular kitchen systems. Middle-class apartment upgrades in Chinese cities drive premium cabinet adoption. Direct-to-consumer channel expansion captures margin previously allocated to kitchen studio networks.
- Restaurants:High-turnover seating and commercial-grade durability requirements favor metal-frame construction and replaceable components.
- Cafés:Flexible seating configurations and aesthetic differentiation support rapid furniture refresh cycles.
- Hotels:Brand-standard consistency across properties demands scalable supply relationships with certified material documentation.
Households lead volumes today; restaurant procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European cabinetry traditions established the modern kitchen furniture industry, with German and Italian manufacturers scaling modular systems through the twentieth century. Contemporary demand patterns now trace regulatory divergence across major economies, reshaping where certified materials concentrate and which production geographies capture value.
United States
Urban household renovation spending drives modular cabinet adoption in coastal metropolitan areas. EPA formaldehyde emission standards and California Air Resources Board ATCM requirements constrain composite wood chemistry, favoring manufacturers with certified hardwood networks. North Carolina and Pennsylvania host concentrated cabinetry production clusters serving national distribution.
Germany
EU Green Deal timber traceability mandates are decoupling demand from undocumented wood sources, elevating certified supply chains. REACH chemical restrictions tighten adhesive formulations, accelerating bio-based resin partnerships. The North Rhine-Westphalia industrial corridor anchors precision manufacturing for export-oriented kitchen systems.
China
Middle-class apartment upgrades in Shanghai and Shenzhen accelerate premium cabinet adoption over traditional carpentry. GB standards for indoor decoration materials create compliance pathways for certified manufacturers. The Yangtze River Delta concentrates modular kitchen production serving domestic and export demand.
France
Controlled atelier production models sustain premium positioning in Paris and Lyon metropolitan markets. ECHA-aligned testing protocols enable export certification advantages. The Auvergne-Rhône-Alpes region hosts specialized manufacturing for design-forward kitchen furniture serving European hospitality.
Italy
Heritage woodworking traditions intersect with modern styling demands in Milan and Turin design centers. CE marking requirements and timber documentation obligations shape procurement cycles. Lombardy maintains concentrated production of high-end cabinetry for Middle Eastern and Asian export markets.
Kitchen and Dining Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates between integrated manufacturers controlling certified material networks and brand-focused assemblers outsourcing production. Three archetypes dominate: hardwood-sourcing specialists with compliance advantages, atelier-scale craftsmen serving premium segments, and scale-driven fabricators optimizing standardized modules. M&A activity concentrates certified sourcing networks, while direct-to-consumer channel expansion captures margin from traditional retail intermediaries.
Among North American hardwood-sourcing specialists, MasterBrand Cabinets exemplifies compliance-forward vertical positioning, while American Woodmark occupies a scale-driven fabrication tier. Roche Bobois represents the atelier-production archetype, anchoring premium European positioning through controlled manufacturing geography. These three players illustrate how material certification and production geography increasingly determine competitive boundaries rather than brand marketing alone.
| Leading Market Players |
|---|
| Merillat |
| Omega Cabinetry |
| MasterBrand Cabinets |
| Roche Bobois |
| Crate & Barrel |
| American Woodmark |
| Schrock Cabinetry |
| SieMatic |
| KraftMaid |
| Others |
Supply & Pricing Matrix
Captive hardwood sourcing networks anchor both supply security and pricing power for kitchen furniture manufacturers serving EPA-regulated markets. MasterBrand Cabinets and similar specialists leverage backward integration into North American timberlands to sustain margin advantages while mid-tier competitors absorb engineered wood panel cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates kitchen furniture procurement, with certification grade and customization depth as primary differentiation drivers. Pricing pressure stems from resin and fiber input fluctuations tied to petrochemical feedstock markets, compressing margins for manufacturers lacking captive material networks. Household renovators in Chinese first-tier cities exhibit lowest price sensitivity, while cost-sensitive hospitality buyers in secondary markets drive volume at economy tiers.
Supply Chain Analysis
Regional distribution centers in North Carolina, Pennsylvania, and the Yangtze River Delta anchor hub-and-spoke patterns for kitchen furniture fulfillment. Manufacturing concentrates in the United States, China, and Germany, with raw material dependencies on certified hardwood, engineered wood panels, and electrostatic coating chemicals. Single-source vulnerability around North American certified timber networks poses structural risk. Distribution runs through kitchen studio networks, though direct-to-consumer channels are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bio-based resin partnerships that command premium positioning under tightening REACH and GB standards compliance requirements.
For Market Incumbents: Deploy certified sourcing network expansion to defend against emerging metal-glass hybrid furniture substitutes threatening traditional wood-dominant lines. MasterBrand Cabinets exemplifies the captive timberland model that creates defensible compliance advantages under EPA formaldehyde standards. Channel control through configurator-driven direct sales captures margin from traditional kitchen studio intermediaries. For New Entrants and Emerging Players: Capture white-space in bar stool segments where electrostatic powder coating technology lowers capital barriers versus cabinet manufacturing. Chinese secondary cities and Southeast Asian hospitality markets present penetrable geographies with compressed compliance timelines. Go-to-market through digital configurators bypasses established studio network gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for atelier-scale craftsmen because ECHA-aligned testing protocols create export certification moats replicable across European production clusters. Five-to-ten year viability hinges on bio-based binder R&D positioning ahead of REACH SVHC expansion deadlines. Monitor EU Timber Regulation documentation timeline extensions as inflection signal for just-in-sequence installation bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Resin Partnership | REACH SVHC compliance secures German and French market access ahead of reformulation deadlines. |
| Direct-to-Consumer Channel Launch | Configurator-driven sales capture kitchen studio margin in Chinese first-tier cities. |
| Certified Hardwood Network Expansion | EPA formaldehyde alignment sustains North American market entry against composite wood competitors. |
| Electrostatic Coating Capacity Addition | VOC elimination reduces handling costs for Berlin and Shanghai millennial buyer segments. |
| Atelier Production Replication | Roche Bobois-style controlled manufacturing marries craftsmanship with scalable quality assurance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cabinetry procurement managers, timberland sourcing directors, kitchen studio operators, and regulatory compliance officers with secondary validation from EPA emission filings, ECHA SVHC candidate list updates, and Chinese GB standard revisions. Bottom-up segment sizing triangulated against top-down trade flow analysis across the analysis window.
Segment-weighting approaches modeled kitchen cabinets, bar stools, dining tables, and sideboards by material type, installation permanence, and end-user category. CAGRs derived from regression analysis against urban renovation spending indices and regulatory compliance cost curves. Forecast inputs included modular kitchen adoption rates in Chinese cities and electrostatic coating technology penetration in Western markets.
Timber certification timeline delays, resin feedstock price volatility, and metal-glass substitution acceleration are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Accent Tables Market
Kitchen and Dining
Turkey Kitchen Furniture Market