
 Kitchen Hand Tools Market | 2026-2036
Kitchen Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Hand Tools Market Foresight
Restaurant chain procurement is consolidating around fewer approved vendors with stricter lifecycle cost criteria. Williams Sonoma leverages its direct-to-consumer channel and private-label manufacturing partnerships to sustain margin control. OXO competes through ergonomic design patents and universal accessibility features that command premium shelf placement. KitchenAid anchors its position in the professional segment with reinforced construction and color-customization programs for culinary schools.
Kitchen hand tools comprise manually operated implements for food preparation, typically constructed from stainless steel alloys with chromium content exceeding 10.5 percent, hardwoods such as acacia or beech, or food-grade silicone rated for temperatures between negative forty and four hundred fifty degrees Fahrenheit, serving commercial kitchens and domestic consumers through cutting, measuring, mixing, and peeling functions. Cutting tools dominate value generation due to blade replacement frequency and professional sharpening service attachments, while silicone-based mixing tools represent the fastest-expanding material-product intersection as thermal resilience requirements intensify in pastry and confectionery applications. Stainless steel maintains the largest material share by revenue owing to NSF certification requirements and dishwasher durability expectations in restaurant environments.
The FDA governs indirect food additive migration limits under 21 CFR 177, compelling manufacturers to validate polymer and coating compositions for repeated utensil-food contact. NSF International protocol P335 establishes commercial kitchen equipment sanitation benchmarks that directly determine restaurant procurement eligibility and insurance compliance. ISO 8442 specifies material and performance requirements for cutlery and table hollowware, creating export certification friction for producers targeting multiple regulatory jurisdictions. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as California and Washington have advanced prohibitions that will cascade through national supply chains.
Market Dynamics
Professional kitchen equipment procurement is consolidating around lifecycle cost accounting as NSF International sanitation protocols tighten stainless steel sourcing specifications across commercial hospitality supply chains.
Growth Catalysts
- NSF International P335 protocol:Restaurant chains now mandate certified sanitation benchmarks for insurance compliance, accelerating replacement cycles in high-volume commercial kitchens.
- German precision manufacturing heritage:Commercial hospitality investment clusters in Baden-Württemberg and Bavaria concentrate demand for chromium-alloy tools exceeding 10.5 percent content.
- Silicone thermal resilience:Pastry and confectionery applications drive adoption of food-grade silicone rated for negative forty to four hundred fifty degrees Fahrenheit.
Market Restraints
- Chromium alloy price volatility:Stainless steel input costs fluctuate with nickel and molybdenum commodity markets, compressing margins on NSF-certified product lines.
- ISO 8442 certification friction:Export-oriented manufacturers face redundant testing requirements when targeting multiple regulatory jurisdictions simultaneously.
- Polymer migration validation:FDA 21 CFR 177 compliance timelines extend product development cycles for coated and composite utensil introductions.
Strategic Opportunities
- California PFAS prohibitions:State-level restrictions on per- and polyfluoroalkyl substances will cascade through national supply chains, favoring early reformulators of non-stick coatings.
- Direct-to-consumer channel expansion:Private-label manufacturing partnerships enable margin control bypassing traditional foodservice distribution tiers.
- Color-customization programs:Culinary schools seek differentiated tool kits for institutional branding and student identification protocols.
Industry Challenges
- Blade sharpening service integration:Professional kitchens demand attached maintenance programs, requiring field technician networks or third-party logistics partnerships.
- Ergonomic patent navigation:Universal accessibility features create licensing complexity when designing handles for repetitive strain reduction.
- Dishwasher durability validation:Repeated high-temperature exposure testing extends quality assurance timelines before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Hand Tools Market |
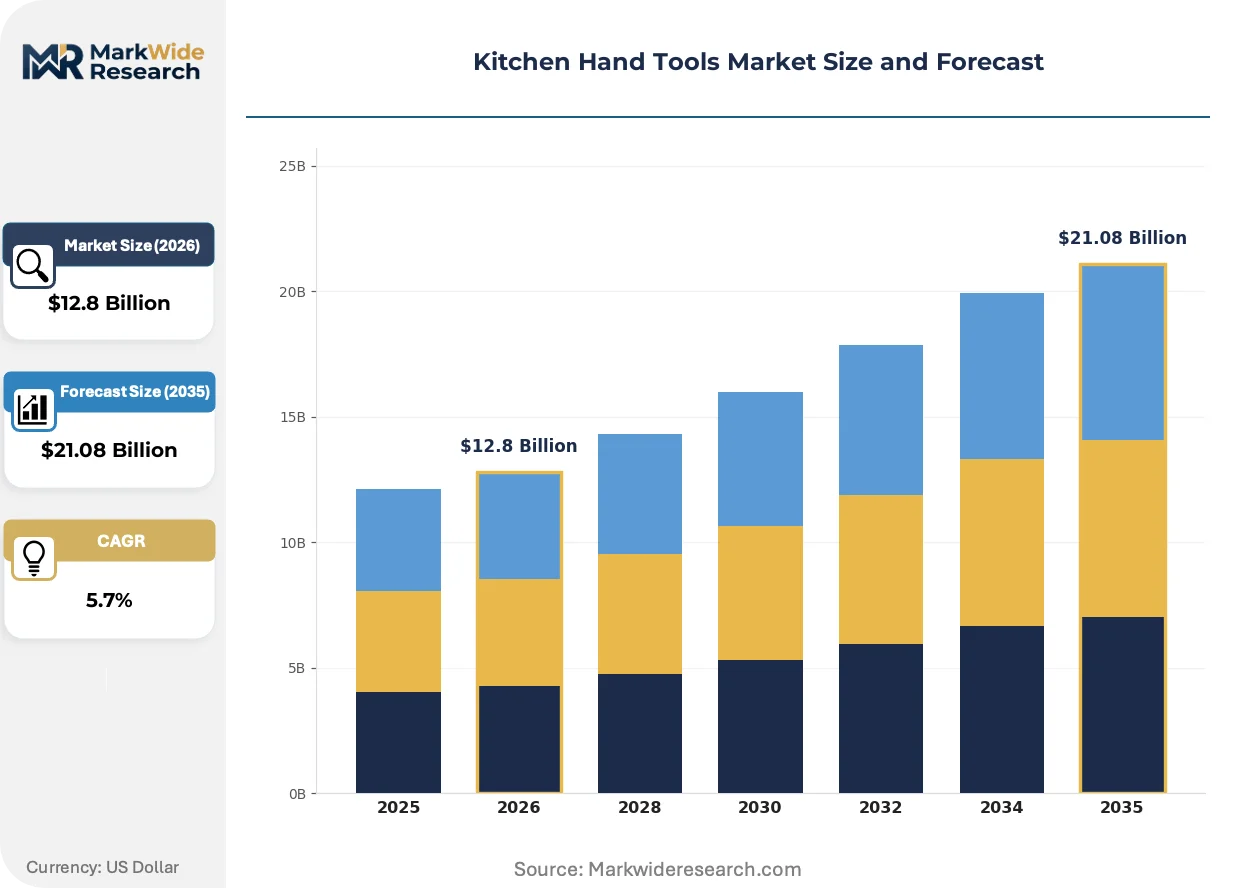
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Tools, Measuring Tools, Mixing Tools, Peeling Tools Material: Stainless Steel, Plastic, Wood, Silicone End User: Households, Restaurants, Catering Services, Culinary Schools Usage Type: Professional Use, Home Use, Specialty Use, General Use |
| Companies Covered | Williams Sonoma, Cuisinart, KitchenAid, OXO, IKEA, Kitchen Craft, Farberware, Cuisipro, Culinare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Hand Tools Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing traditional product development cycles while opening new specification tiers for specialized kitchen applications.
Composite silicone-steel hybrid construction is unifying thermal resilience with structural rigidity in pastry tools. High-end restaurant chains are adopting these implements within eighteen-month refresh cycles. The technology is unifying previously separate tool categories into multi-function implements that reduce drawer inventory counts.
REACH substance restrictions in the European Union are compelling coating reformulation across hollowware export portfolios. Manufacturers serving German and French markets must validate alternative non-stick chemistries before 2025 enforcement windows. Commercial buyers in these jurisdictions are accelerating pre-qualification audits to avoid supply interruptions.
Culinary school procurement offices are bundling tool specifications with curriculum licensing agreements. Traditional restaurant supply distributors face disintermediation as institutional buyers negotiate direct relationships with manufacturers offering customization and volume pricing. This pattern concentrates most visibly in North American hospitality education networks seeking differentiated student kits.
Kitchen Hand Tools Market Segmentation
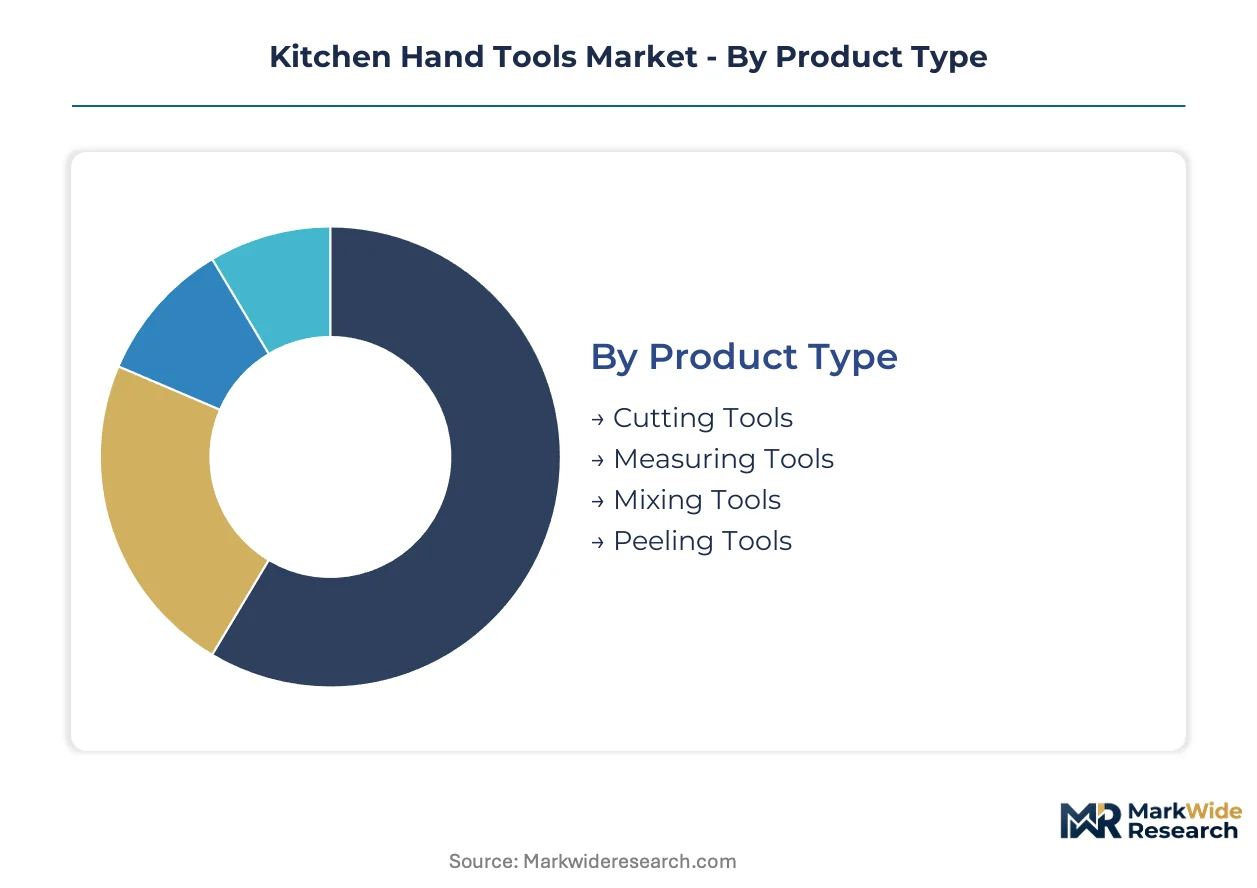
Kitchen hand tools fragment across four intersecting dimensions that determine pricing power, certification requirements, and replacement frequency. Product type and material composition anchor technical specifications, while end user and usage type dictate procurement channels and lifecycle economics.
Product Type:
Professional kitchens prioritize blade integrity and calibration precision, while domestic buyers emphasize multi-functionality and storage efficiency.
- Cutting Tools:Knives, shears, and mandolines constructed from chromium-alloy steel exceeding 10.5 percent content dominate commercial procurement. Demand concentrates in high-volume restaurant chains where NSF P335 certification determines insurance eligibility and blade replacement programs lock in recurring revenue.
- Measuring Tools:Scales, cups, and thermometers requiring ISO 8442 calibration validation face export friction when targeting multiple regulatory jurisdictions. Precision manufacturing clusters in Baden-Württemberg supply culinary schools seeking differentiated kits for institutional branding.
- Mixing Tools:Whisks, spatulas, and spoons span silicone-steel hybrid construction for thermal resilience in pastry applications.
- Peeling Tools:Y-peelers, julienne cutters, and rotary peelers compete on ergonomic handle patents for repetitive strain reduction.
Volume sits with Cutting Tools; growth tilts toward Mixing Tools.
Material:
Regulatory compliance costs and dishwasher durability expectations segment buyers by risk tolerance and replacement horizon.
- Stainless Steel:Chromium-alloy grades with nickel and molybdenum additives command premium positioning in commercial hospitality. FDA 21 CFR 177 migration limits and NSF sanitation protocols compress margins when commodity input prices fluctuate.
- Silicone:Food-grade formulations rated for negative forty to four hundred fifty degrees Fahrenheit are climbing the fastest as thermal resilience requirements intensify in confectionery and pastry segments.
- Plastic:Polymer compositions face California and Washington PFAS prohibitions cascading through national supply chains.
- Wood:Acacia and beech hardwoods serve specialty carving and presentation applications with natural antimicrobial properties.
Revenue concentrates in Stainless Steel; steepest expansion trajectory belongs to Silicone.
End User:
Procurement authority and customization requirements separate institutional buyers from discretionary purchasers.
- Restaurants:High-end establishments and chain operators consolidate around fewer approved vendors with lifecycle cost accounting. German commercial hospitality investment tightens durability standards and extends replacement cycles.
- Culinary Schools:North American hospitality education networks negotiate direct manufacturer relationships, bundling tool specifications with curriculum licensing agreements and color-customization programs for student identification.
- Households:Direct-to-consumer channels and private-label partnerships enable margin control bypassing traditional foodservice distribution.
- Catering Services:Mobile food operations prioritize lightweight, nested designs for transport efficiency and rapid deployment.
Restaurants capture the largest order values; Culinary Schools show the fastest procurement pattern shift.
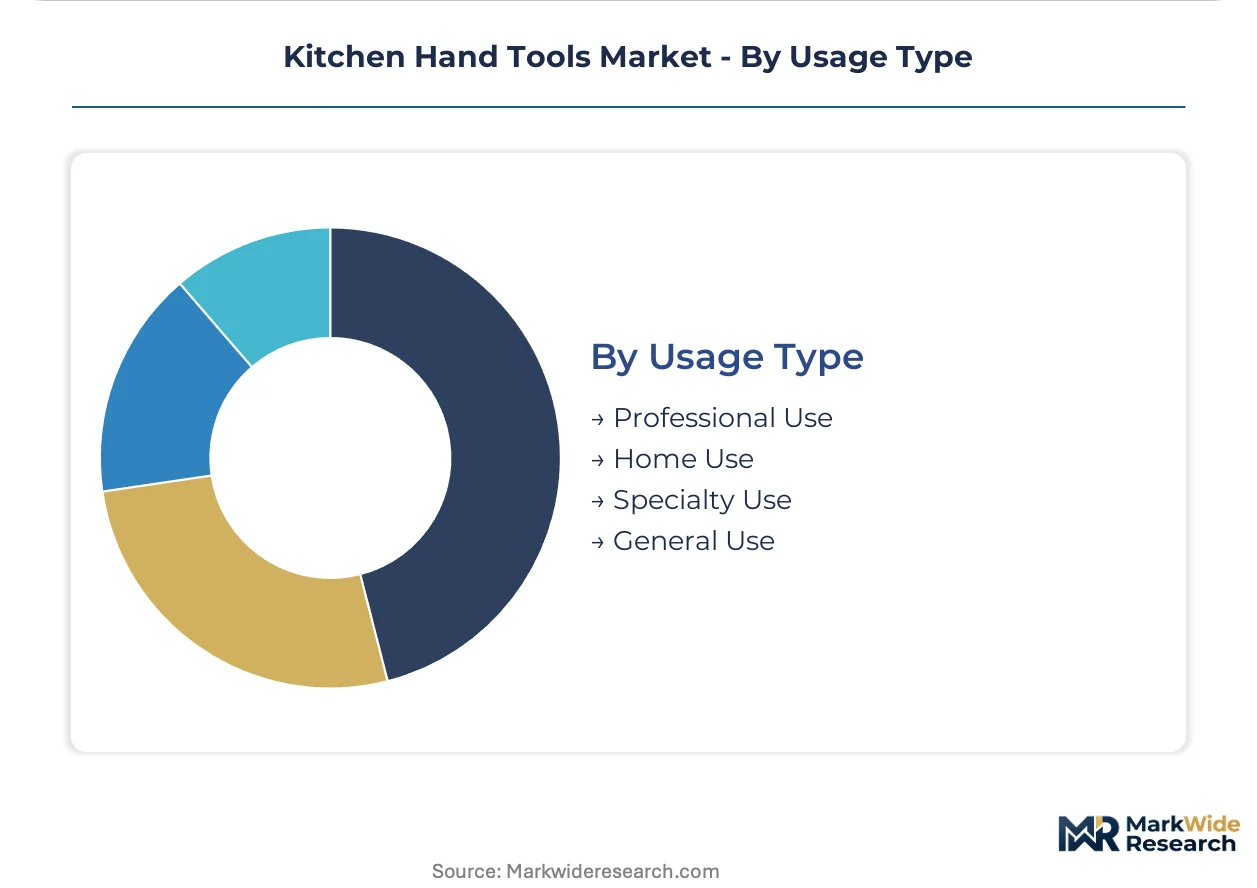
Usage Type:
Intensity of use and exposure conditions determine warranty terms, maintenance attachment, and distribution channel selection.
- Professional Use:Commercial kitchens demand attached sharpening services and field technician networks, with dishwasher durability validation extending quality assurance timelines before launch.
- Specialty Use:Pastry, confectionery, and butchery applications specify thermal resilience and precision tolerances that unify previously separate tool categories into multi-function implements.
- Home Use:Domestic buyers prioritize ergonomic accessibility features and universal design patents commanding premium shelf placement.
- General Use:Versatile implements serve occasional cooks seeking drawer inventory reduction through hybrid construction.
Professional Use anchors replacement frequency; Specialty Use drives specification tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium-alloy steel supply from German foundries anchors procurement patterns for precision kitchen implements across commercial hospitality networks.
Germany
Baden-Württemberg and Bavaria concentrate commercial hospitality investment with precision manufacturing heritage driving demand for chromium-alloy tools. ECHA REACH substance restrictions compel coating reformulation across hollowware export portfolios. Stuttgart industrial clusters validate alternative non-stick chemistries ahead of enforcement windows.
United States
Restaurant chain procurement consolidates around lifecycle cost accounting with stricter vendor approval criteria. FDA 21 CFR 177 governs indirect food additive migration limits for polymer utensil compositions. California PFAS prohibitions cascade through national supply chains, favoring early coating reformulators.
France
Commercial buyers accelerate pre-qualification audits to avoid supply interruptions from evolving substance restrictions. ANSM and CNIL oversight extends to food-contact material traceability requirements. Lyon hospitality equipment distributors consolidate sourcing relationships with NSF-certified manufacturers.
China
Export-oriented manufacturers face redundant ISO 8442 certification friction when targeting multiple regulatory jurisdictions simultaneously. SAMR and GB standards govern domestic food-contact utensil safety. Yangtze River Delta production clusters specialize in silicone-steel hybrid construction for pastry applications.
Japan
Culinary schools negotiate direct manufacturer relationships bundling tool specifications with curriculum licensing agreements. METI and PMDA frameworks influence food-contact material validation protocols. Osaka-based hospitality education networks seek differentiated student kits with color-customization programs.
Kitchen Hand Tools Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ergonomic specialization and direct-to-consumer channel control. The vendor base spans consolidated restaurant supply distributors and fragmented private-label manufacturers. Three archetypes dominate: heritage kitchenware brands with culinary school relationships, direct-to-consumer specialists leveraging private-label manufacturing partnerships, and mass-market retailers with captive product development. Competitive moves concentrate on strategic partnerships for field technician networks and portfolio diversification into silicone-steel hybrid construction.
Among heritage American kitchenware specialists, Williams Sonoma, KitchenAid, and OXO exemplify distinct positioning vectors. Williams Sonoma represents the direct-to-consumer archetype with private-label manufacturing control. KitchenAid anchors professional-segment positioning through reinforced construction programs. OXO occupies the ergonomic innovation tier with universal accessibility features commanding premium placement. These three entities collectively illustrate how brand heritage, channel strategy, and design specialization segment competitive space without overlapping core positioning.
| Leading Market Players |
|---|
| Williams Sonoma |
| Cuisinart |
| KitchenAid |
| OXO |
| IKEA |
| Kitchen Craft |
| Farberware |
| Cuisipro |
| Culinare |
| Others |
Supply & Pricing Matrix
Captive chromium-alloy sourcing from Baden-Württemberg foundries anchors supply positions for NSF-certified manufacturers while compressing margin flexibility when nickel and molybdenum commodity markets fluctuate. Restaurant chain procurement offices exploit this concentration through consolidated vendor lists that extract volume pricing concessions in exchange for multi-year replacement program commitments.
Pricing Analysis
Attached sharpening service bundling separates premium NSF-certified cutting tool tiers from unbundled economy alternatives sold through mass retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and dishwasher durability validation timelines. Cost compression in standard tiers is intensifying because ISO 8442 redundant testing requirements extend commercial launch timelines without commensurate price recovery. Culinary schools exhibit lowest price sensitivity due to curriculum licensing bundling, while catering services face acute margin pressure from lightweight transport efficiency mandates.
Supply Chain Analysis
NSF P335 qualification gating restricts approved supplier pools to chromium-alloy processors with validated migration testing protocols under FDA 21 CFR 177. Manufacturing concentrates in Germany, China, and Japan, with Yangtze River Delta clusters specializing in silicone-steel hybrid construction for pastry applications. Raw material feeds draw from nickel and molybdenum commodity markets, food-grade silicone resin suppliers, and acacia hardwood plantations. Single-source vulnerability runs through German precision forging capacity for high-chromium grades. Distribution runs through consolidated restaurant supply distributors and direct-to-consumer private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a vertical-integration race where upstream control over chromium-alloy foundry capacity and downstream field technician networks for blade maintenance determine margin sustainability.
For Market Incumbents: Hedge against commodity volatility through captive sourcing partnerships with Baden-Württemberg steel processors and accelerate silicone-steel hybrid R&D to offset chromium price exposure. Defensive certification investment in ISO 8442 multi-jurisdiction validation preserves export eligibility against emerging entrant cost advantages. For New Entrants and Emerging Players: Enter via ergonomic handle patent licensing for repetitive strain reduction applications, targeting North American culinary school direct procurement channels disintermediating traditional distributors. White-space concentration sits in color-customization programs bundling tool specifications with institutional branding requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in heritage brand acquisition by private-label manufacturing platforms seeking direct-to-consumer channel control. Five-to-ten year viability favors targets with validated NSF P335 protocols and established field technician networks. The signal to watch is California PFAS enforcement cascade triggering coating reformulation capex demands that strain undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromium-Alloy Foundry Capacity | Captive sourcing from Baden-Württemberg processors insulates margin compression from nickel commodity volatility. |
| Silicone-Steel Hybrid Product Line Expansion | Thermal resilience unification opens pastry and confectionery specification tiers previously closed to pure steel construction. |
| Direct-to-Consumer Channel Launch | Private-label manufacturing partnerships bypass foodservice distribution tiers and sustain margin control. |
| Field Technician Network Partnership | Attached blade sharpening services lock in recurring revenue from high-volume restaurant chain accounts. |
| California PFAS Coating Reformulation | Early compliance with state-level prohibitions cascades through national supply chains and displaces lagging competitors. |
Research Methodology
Document review covered FDA 21 CFR 177 migration limit filings, NSF International P335 certification registries, and ECHA REACH substance restriction databases, complemented by interviews with restaurant chain procurement directors, culinary school curriculum licensing officers, stainless steel foundry operations managers, and foodservice distribution channel heads. Secondary validation drew from customs trade data, SEC 10-K filings of listed kitchenware specialists, and commercial hospitality investment tracking databases. Bottom-up vendor capacity assessments and top-down demand modeling from end-user segments were cross-referenced for triangulation.
Historical shipment data from chromium-alloy processors and silicone resin suppliers were cross-referenced against panel input from procurement directors at high-volume restaurant chains and culinary school administrators. The analytical framework modeled product type, material composition, end user category, and usage intensity across the analysis window. CAGRs were derived from replacement cycle frequency analysis and commercial hospitality investment flow tracking. Forecast inputs incorporated NSF certification pipeline visibility and REACH enforcement timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS prohibition enforcement or sustained nickel commodity price spikes. Model outputs reflect assumptions on regulatory harmonization pace and vendor consolidation velocity. A model refresh is warranted upon material change in FDA food-contact material rulemaking or German commercial hospitality investment flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Turkey Kitchen Furniture Market