
 Kitchen Cabinets Market | 2026-2036
Kitchen Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Cabinets Market Outlook
KCMA's Environmental Stewardship Program certification is rotating the competitive landscape by filtering suppliers based on verified emissions and material chain-of-custody documentation. MasterBrand Cabinets sustains broad distribution through multi-channel coverage across big-box retail and independent dealer networks. Fabuwood differentiates through import-led cost positioning combined with domestic finishing capabilities. American Woodmark Corp anchors production scale across multiple U.S. manufacturing facilities serving new construction builders.
Kitchen cabinets are rigid furniture assemblies designed for food preparation and storage environments, typically constructed from engineered wood substrates with applied finishes and hardware systems rated for moisture exposure and cyclic loading. Base cabinets provide foundational countertop support and represent the volume core of residential projects, while wall cabinets capture premium margin pools through custom sizing and integrated lighting specifications. Shaker styling dominates current specification activity across new residential developments, with modern finishes gaining share in urban infill renovations. Material selection clusters around plywood and MDF depending on price tier and regional humidity exposure.
EPA TSCA Title VI governs composite wood formaldehyde emissions and directly constrains panel procurement for U.S.-based cabinet assembly operations. KCMA certification programs and California Air Resources Board precedents shape product labeling requirements and market access conditions for national distribution. Stakeholders must monitor evolving state-level indoor air quality legislation and building code amendments that specify low-emitting material thresholds for residential construction permits.
Market Dynamics
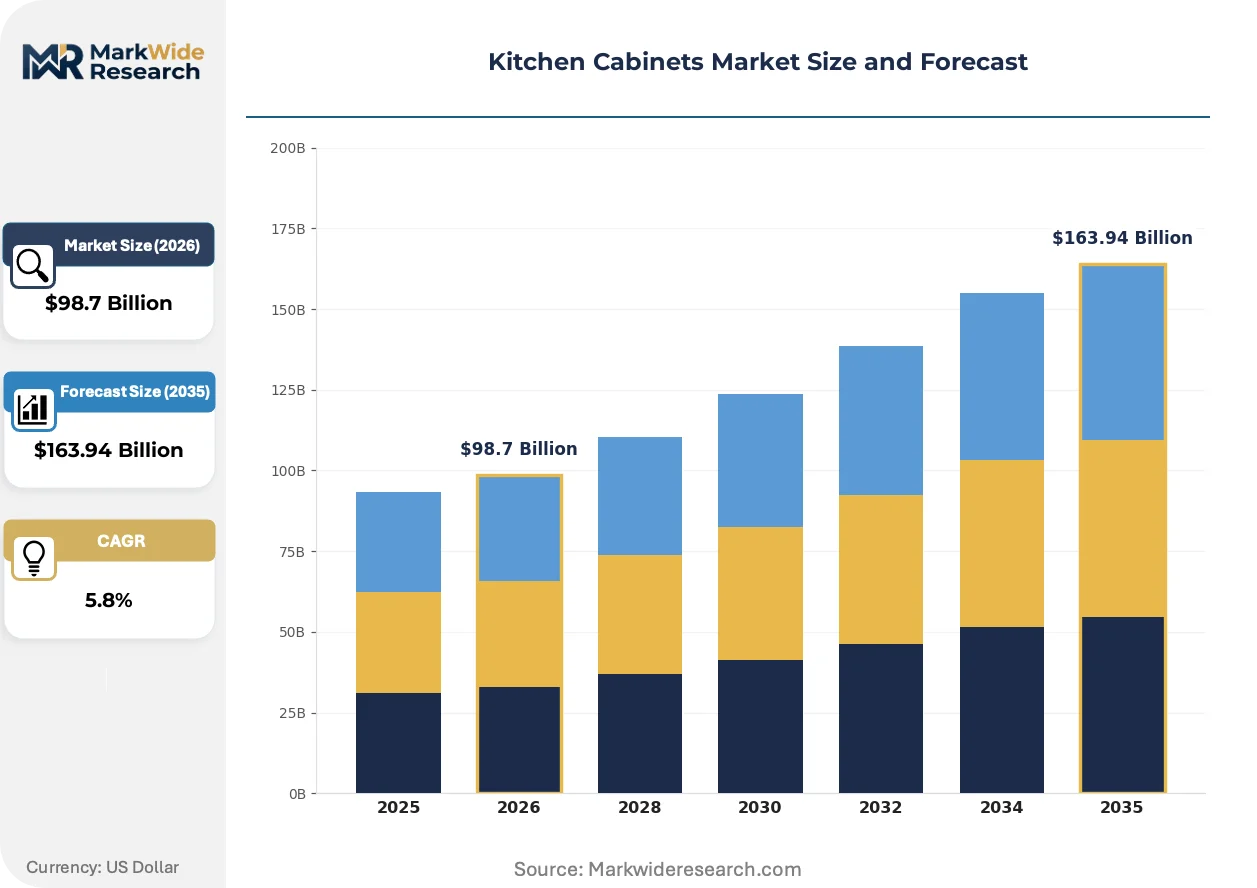
EPA TSCA Title VI formaldehyde emission limits are compressing domestic panel sourcing options while Sun Belt housing construction pulls volume through suburban new-build channels.
Growth Catalysts
- Suburban new construction:Residential ground-up development across Sun Belt metropolitan statistical areas is expanding base cabinet procurement volumes through builder-direct specification channels.
- EPA TSCA Title VI:Composite wood product emission standards are filtering supplier qualification pools and accelerating certified panel adoption across U.S. assembly operations.
- Shaker styling standardization:Specification convergence around five-piece door profiles is reducing SKU complexity and enabling production line efficiency gains for mid-market manufacturers.
Market Restraints
- Domestic hardwood supply:Appalachian oak and maple availability constraints are elevating raw material costs for solid wood component production.
- Import panel dependency:Southeast Asian plywood sourcing concentration creates exposure to ocean freight rate volatility and customs processing delays.
- MDF moisture limitation:Medium-density fiberboard substrate performance degradation in high-humidity installations restricts application scope in coastal Gulf markets.
Strategic Opportunities
- Urban infill renovation:Compact kitchen footprints in dense metropolitan cores are driving demand for vertical storage solutions and integrated appliance cabinetry.
- KCMA Environmental Stewardship certification:Chain-of-custody verification programs are opening specification access to green building incentive programs and municipal procurement preferences.
- LED-integrated wall cabinets:Task lighting convergence with storage hardware is capturing premium positioning in custom renovation projects.
Industry Challenges
- Cabinet installation technician shortage:Skilled trim carpentry labor scarcity is extending project completion timelines and elevating contractor wage rates.
- Multi-facility certification synchronization:Maintaining consistent EPA and KCMA compliance documentation across distributed manufacturing footprints strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Cabinets Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Cabinets, Wall Cabinets, Tall Cabinets, Specialty Cabinets Material: Wood, MDF, Particleboard, Plywood Style: Traditional, Modern, Shaker, Rustic Finish Type: Painted, Stained, Varnished, Laminate |
| Companies Covered | Wellborn Cabinet, Foremost Groups, MasterBrand Cabinets, W.W. Wood Products, Leedo Mfg, American Woodmark Corp, Bertch Cabinet Mfg, Fabuwood, Cabinetworks Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Cabinets Market Strategic Shifts
Material science advances and regulatory disclosure requirements are restructuring how cabinet manufacturers specify substrates, apply finishes, and document environmental performance for specification-driven buyers.
Thermally fused laminate surfacing is fragmenting traditional high-pressure laminate market segmentation by delivering comparable abrasion resistance at reduced material thickness and simplified press cycle requirements. Multi-family developers in Texas and Florida are specifying TFL for rental unit turnover durability. The technology is fragmenting premium-mid tier boundary definitions that previously separated thermofoil from HPL specification bands.
California Air Resources Board ATCM precedents are extending formaldehyde testing protocols beyond EPA baseline requirements and creating bifurcated compliance documentation obligations for national distributors. Manufacturers serving California plus additional states with indoor air quality legislation must maintain dual certification tracks. The regulatory layering most affects importers lacking captive U.S. panel production capacity.
Builder procurement consolidation through national purchasing agreements is compressing independent dealer influence in new construction specification. Volume commitments to production homebuilders are displacing traditional two-step distribution through kitchen design showrooms. The channel shift concentrates most visibly in Arizona, Nevada, and Carolinas markets where top-ten builders control supermajority starts.
Kitchen Cabinets Market Segmentation
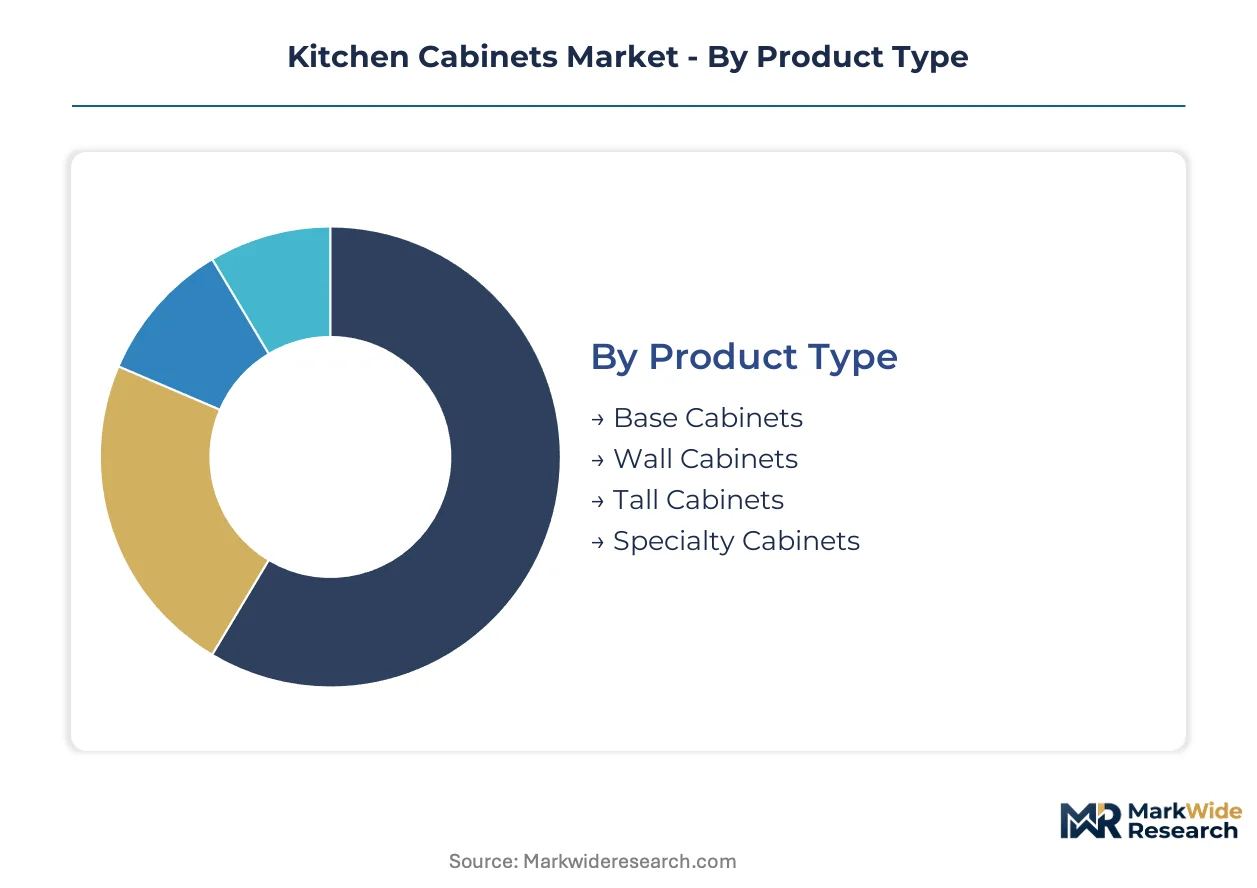
Kitchen cabinet segmentation reveals how specification decisions cascade through material compliance, installation environment, and aesthetic positioning. Distinct buyer profiles—production homebuilders, renovation contractors, and retail consumers—prioritize different attribute bundles when evaluating cabinet systems.
Product Type:
Substitution pressure runs strongest against tall cabinets as open shelving and pantry systems capture storage demand in compact kitchens.
- Base Cabinets:These floor-mounted units provide structural countertop support and house sink plumbing, drawer storage, and appliance integration. Demand concentrates in Sun Belt suburban new construction where production builders specify standardized 34.5-inch heights for cost efficiency. EPA TSCA Title VI compliance requirements filter panel sourcing options for high-volume assembly operations.
- Wall Cabinets:Elevated storage units mount above countertops and capture premium positioning through integrated LED task lighting and glass door options. Urban infill renovations in dense metropolitan cores drive vertical storage demand as kitchen footprints compress. Custom sizing capabilities differentiate mid-market suppliers from commodity producers.
- Tall Cabinets:Full-height pantry and utility units extend from floor to ceiling for bulk storage. These face displacement from standalone furniture systems in rental and starter home segments.
- Specialty Cabinets:Corner units, appliance garages, and pull-out organizers address specific spatial constraints. Demand clusters in custom renovation projects where kitchen designers specify tailored solutions.
Base cabinets retain volume leadership; wall cabinets hold the steepest expansion curve.
Material:
Cost tier stratification separates solid wood premium positioning from engineered substrate mid-market dominance.
- Wood:Solid hardwood components—oak, maple, cherry—deliver dimensional stability and refinishing longevity. Appalachian hardwood supply constraints elevate raw material costs for domestic manufacturers. Solid wood door frames and face frames persist in custom and semi-custom specification channels despite panel substrate shifts.
- MDF:Medium-density fiberboard provides uniform surface quality for painted finishes and detailed machining. High-humidity installation restrictions in Gulf Coast markets limit application scope despite cost advantages. EPA formaldehyde emission standards constrain domestic panel sourcing options for U.S. assembly operations.
- Particleboard:Lower-density engineered wood serves economy-tier cabinet systems with thermofoil or laminate surfacing. Moisture sensitivity restricts use to dry interior environments.
- Plywood:Cross-laminated veneer construction delivers structural integrity and moisture resistance for sink base and high-wear applications. Southeast Asian sourcing concentration creates supply chain exposure to freight volatility and customs delays.
Plywood anchors structural performance requirements; MDF captures the fastest share gain in painted-finish segments.
Style:
Application context drives specification—new construction standardizes while renovation favors differentiation.
- Shaker:Five-piece door profile with recessed center panel dominates current residential development specification. Production line efficiency gains from SKU reduction reward manufacturers with standardized door dimension programs. Sun Belt metropolitan markets standardize around this profile for cost-controlled builder-direct procurement.
- Modern:Flat-panel slab doors with minimal hardware deliver clean lines for urban infill renovations and contemporary architecture. European hinge systems and handle-less push-latch mechanisms elevate hardware specification requirements.
- Traditional:Raised-panel profiles with decorative molding target established suburban renovation markets and replacement demand in mature housing stock.
- Rustic:Distressed finishes and reclaimed-wood aesthetics serve vacation property and farmhouse-style segments with limited volume scale.
Shaker styling commands volume leadership; modern styling posts the steepest trajectory in urban renovation channels.
Finish Type:
Margin structure separates factory-applied coatings from field-finished custom work, with laminate disrupting traditional tier boundaries.
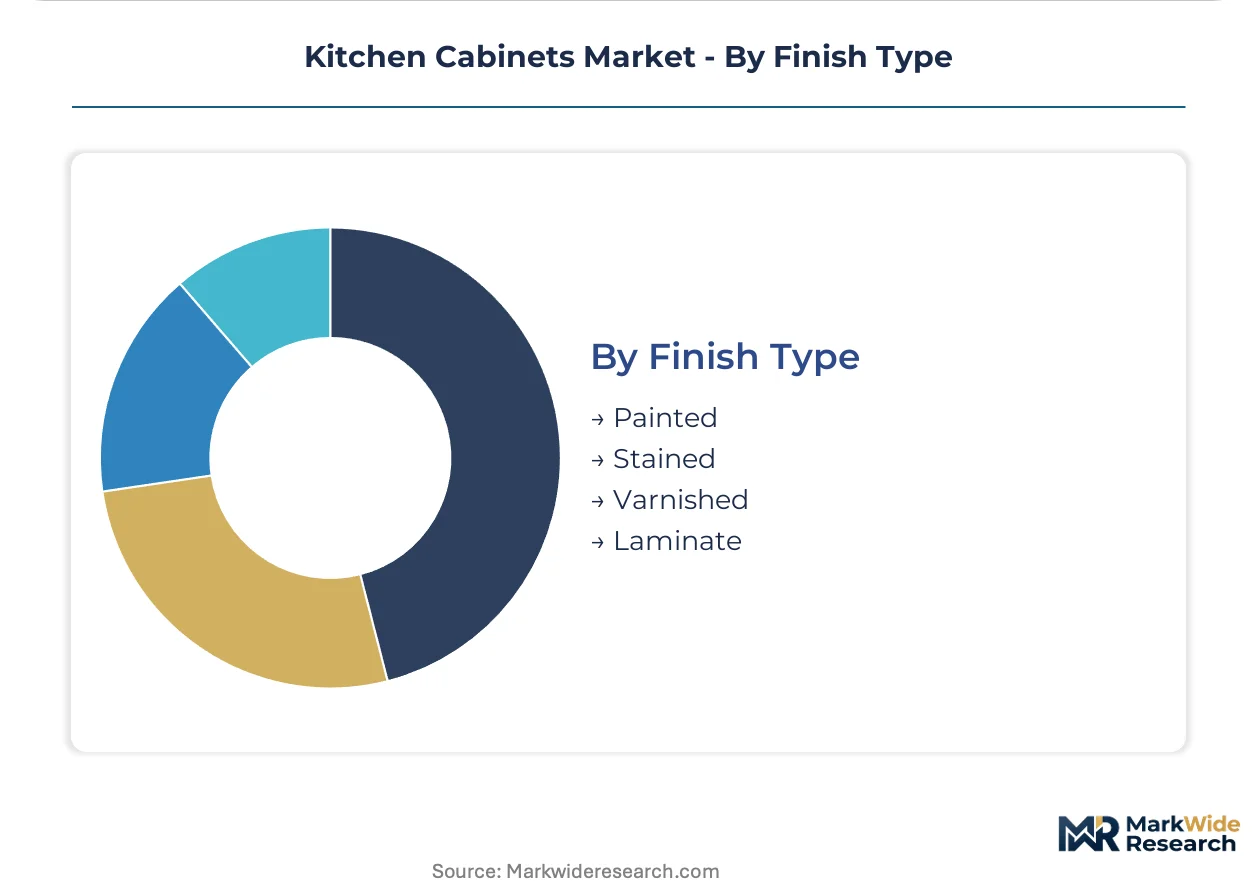
- Painted:Catalyzed conversion varnish and UV-cured coatings deliver consistent color matching and durability for MDF and wood substrates. Multi-family developers in Texas and Florida specify painted finishes for rental unit turnover resilience. KCMA Environmental Stewardship certification programs document low-VOC formulation compliance.
- Laminate:Thermally fused laminate surfacing fragments traditional high-pressure laminate segmentation by delivering comparable abrasion resistance at reduced material thickness. Simplified press cycle requirements compress manufacturing cost structures for mid-market producers.
- Stained:Transparent pigmented finishes showcase natural wood grain variation for premium solid wood and veneer applications. Color consistency challenges across production batches constrain high-volume adoption.
- Varnished:Clear protective topcoats preserve natural wood appearance in traditional and rustic style segments with limited growth trajectory.
Painted finishes retain volume leadership; laminate surfacing gains share fastest through multi-family and rental specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Savannah's container throughput underwrites southeastern U.S. cabinet distribution, while the Panama Canal's capacity constraints redirect Asian plywood shipments toward West Coast gateways.
United States
Sun Belt metropolitan construction drives base cabinet procurement through builder-direct channels. EPA TSCA Title VI formaldehyde emission standards filter domestic panel sourcing options for assembly operations. Atlanta and Dallas-Fort Worth anchor distribution hubs where multi-facility manufacturers coordinate national fulfillment networks.
Canada
Cross-border hardwood supply chains feed U.S. cabinet component demand from Ontario and Quebec forestry operations. Health Canada indoor air quality guidelines align with California Air Resources Board precedents for low-emitting material thresholds. Toronto-area fabricators specialize in semi-custom painted finishes for northern U.S. renovation markets.
Germany
European hinge system and hardware exports supply global cabinet assembly operations. ECHA REACH chemical disclosure requirements govern finish formulation imports into EU member states. North Rhine-Westphalia's machinery builders export press equipment to Southeast Asian panel producers.
China
Yangtze River Delta plywood mills supply cross-laminated veneer substrates to North American cabinet assemblers. GB standards for formaldehyde emissions in composite wood products shape export panel certification documentation. Ningbo and Shanghai ports handle outbound containerized shipments subject to U.S. customs processing timelines.
Vietnam
Southeast Asian plywood production concentration creates supply chain exposure for U.S. cabinet manufacturers dependent on imported structural substrates. The country's national trade regulator monitors export licensing for forest product shipments. Ho Chi Minh City-area finishing operations provide domestic surface treatment for re-export to North American markets.
Kitchen Cabinets Market Competitive Environment
Listed leaders compete with private specialists across distribution channel coverage, with public companies commanding scale advantages in builder-direct procurement while private operators retain flexibility in custom renovation segments. The vendor base stratifies across three tiers: multi-brand holding companies with national coverage, regional specialists with captive manufacturing, and import-dependent assemblers with domestic finishing capabilities. Consolidation pressures concentrate most visibly in Sun Belt markets where production homebuilders consolidate purchasing agreements. Strategic moves center on multi-facility certification synchronization and backward integration into panel production.
Within the import-led assembly tier, Fabuwood occupies a position exemplifying cost-focused positioning combined with domestic distribution infrastructure. Among publicly held manufacturers, American Woodmark Corp represents scale-driven production across distributed U.S. facilities. MasterBrand Cabinets anchors the multi-brand portfolio approach, spanning big-box retail and independent dealer channels. These three archetypes capture distinct competitive vectors: offshore sourcing leverage, domestic manufacturing scale, and channel breadth diversification.
| Leading Market Players |
|---|
| Wellborn Cabinet |
| Foremost Groups |
| MasterBrand Cabinets |
| W.W. Wood Products |
| Leedo Mfg |
| American Woodmark Corp |
| Bertch Cabinet Mfg |
| Fabuwood |
| Cabinetworks Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day panel inventory cycles at U.S. assembly operations compress procurement flexibility and amplify supplier pricing power during Southeast Asian shipping disruptions. This lead-time exposure concentrates buyer leverage among vertically integrated manufacturers with captive panel production, while import-dependent assemblers absorb margin compression from ocean freight volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyer access by certification grade and volume commitment scale. Premium positioning commands KCMA Environmental Stewardship verification and extended warranty terms, while standard tiers compete on Shaker-style SKU efficiency for production builders. Cost compression in the economy segment intensifies as Chinese plywood sourcing faces customs processing delays. Production homebuilders exhibit lowest price sensitivity due to national purchasing agreement leverage, whereas independent renovation contractors face acute margin pressure from skilled installation labor scarcity.
Supply Chain Analysis
Port congestion at Ningbo and Shanghai extends container dwell times for cross-laminated veneer substrates bound for North American assembly operations. Vietnam, China, and Indonesia anchor global plywood supply for structural cabinet components, with Malaysian hardwood feedstock drawing from regional forestry concessions. U.S.-based manufacturers rest on Southeast Asian panel imports, Appalachian oak for solid wood doors, and European hinge hardware from Germany. Single-source vulnerability concentrates in Yangtze River Delta mill capacity. Distribution runs through builder-direct procurement channels in Sun Belt metropolitan markets and independent dealer networks for renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kitchen cabinet specification is approaching a platform-economics inflection as builder procurement consolidation and certification interoperability reshape competitive boundaries. The emergence of national purchasing agreements as de facto standard-setting mechanisms rewards scale players with data-driven demand forecasting.
For Market Incumbents: Consolidate multi-facility EPA TSCA Title VI certification synchronization to defend against quality assurance bandwidth constraints. Acquire captive panel production capacity in the Southeast to offset ocean freight exposure from Asian sourcing. Channel control through exclusive builder-direct relationships in Arizona and Nevada markets anchors volume retention against import-led cost competitors.
For New Entrants and Emerging Players: KCMA Environmental Stewardship fast-track certification opens specification access to municipal green building incentive programs. Urban infill renovation in dense metropolitan cores offers the most penetrable white-space, with vertical storage solutions and LED-integrated wall cabinets capturing premium positioning. Direct-to-contractor digital platforms bypass traditional two-step distribution through kitchen design showrooms.
For Investors and Strategic Acquirers: Carve-out targets emerge from private equity-backed multi-brand holding companies seeking portfolio rationalization. Long-term viability favors manufacturers with backward integration into panel production and distributed U.S. manufacturing footprints. The signal to watch is consolidation velocity among top-ten production homebuilders in Sun Belt markets, as procurement concentration accelerates supplier selection permanence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Production | Captive plywood supply insulates margins from Ningbo port congestion and customs delays. |
| KCMA Environmental Stewardship Certification | Verified emissions documentation unlocks green building incentive program specification access. |
| Multi-Channel Distribution Expansion | Simultaneous big-box retail and independent dealer coverage captures renovation and new construction demand. |
| LED-Integrated Product Line Launch | Task lighting convergence with storage hardware captures premium positioning in custom renovation projects. |
| National Purchasing Agreement Negotiation | Volume commitments to top-ten builders in Arizona and Nevada markets displace competitor access. |
Study Parameters
A standing panel of production builder procurement directors, independent kitchen design showroom owners, cabinet assembly plant managers, and EPA compliance officers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from KCMA certification databases, EPA TSCA Title VI compliance filings, U.S. Census Bureau housing starts data, and customs import records. Bottom-up demand modeling from metropolitan statistical area construction permits triangulated against top-down manufacturer capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, material substrate, finish category, style classification, and regional construction activity cluster. CAGRs were derived from regression analysis of historical procurement volumes correlated with housing start permits and renovation spending indices. Industry-specific forecast inputs incorporated panel import lead-time volatility and skilled installation labor availability constraints.
Underlying assumptions cover sustained Sun Belt housing construction activity and stable EPA formaldehyde emission standards, with deviation risk concentrated in ocean freight rate spikes and hardwood supply constraints from Appalachian forestry operations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Kitchen and Dining Furniture Market