
 Hobs Market | 2026-2036
Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Hobs Market Outlook
Buyer concentration in the European builder channel is rebalancing toward large kitchen studio chains and property developers sourcing at volume. Bosch sustains manufacturing scale across German and Polish facilities, leveraging vertical integration into control systems and burner assemblies. Electrolux competes through geographic diversification of its hob portfolio, anchoring premium positioning in Nordic markets while extending mid-range distribution through retail partnerships in Southern Europe. Miele differentiates via R&D intensity in sensor-driven cooking automation, occupying the ultra-premium segment where brand strength commands channel control.
A hob is a flat cooking surface, typically integrated into kitchen countertops, that houses gas burners, electric heating elements, or electromagnetic induction coils beneath a glass-ceramic or stainless steel panel and serves as the primary thermal appliance for residential and commercial food preparation. Gas hobs retain installed-base dominance in markets with established pipeline infrastructure, though induction hobs represent the fastest-growing type as energy efficiency mandates and speed-of-heating performance reshape consumer preference. Glass and ceramic materials command margin pools in premium segments, while stainless steel anchors volume production for developer-specified installations where durability and cost control outweigh aesthetic considerations.
EU Ecodesign requirements and Energy Label regulations constrain standby power consumption and mandate efficiency disclosures at point of sale, directly influencing manufacturer R&D allocation and retailer assortment decisions. EPA ENERGY STAR certification in the United States creates parallel compliance obligations for brands seeking federal procurement eligibility and utility rebate program participation. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and appliance circularity requirements reshape sourcing economics for glass-ceramic substrates and electronic control modules.
Market Dynamics
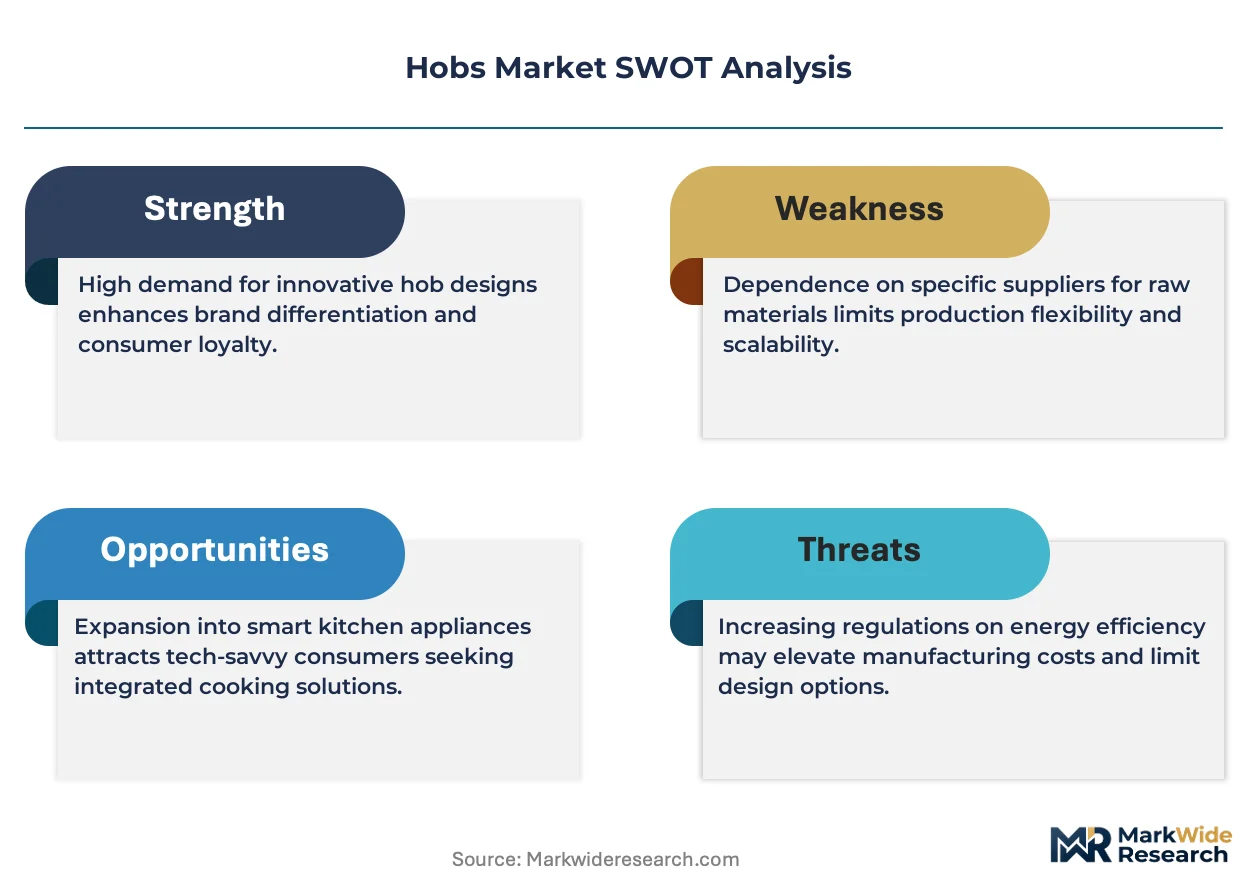
EU F-Gas Regulation and national gas phase-out timelines are compressing the replacement window for gas hobs, forcing manufacturers to retool toward induction platforms while managing stranded inventory in pipeline-dependent markets.
Growth Catalysts
- Residential kitchen renovation cycles:Aging housing stock in Germany and the United States is triggering appliance refresh waves as homeowners prioritize energy-efficient cooking surfaces during whole-kitchen remodels.
- EU Energy Label requirements:Mandatory efficiency disclosures at point of sale are redirecting consumer preference toward induction hobs rated A or above, accelerating electric conversion in member states.
- Smart home integration:Wi-Fi-enabled hobs with app-controlled temperature management are capturing premium-segment buyers in urban China and Nordic markets.
Market Restraints
- Glass-ceramic substrate concentration:Supply of Schott AG and EuroKera glass-ceramic panels concentrates in German and French production facilities, creating input vulnerability for mid-tier assemblers.
- Electrical infrastructure gaps:Rural properties in Italy and Spain lack the 32-amp circuits required for full-power induction, limiting addressable market expansion despite product availability.
- Gas pipeline sunk costs:Established natural gas distribution networks in the Netherlands and United Kingdom create consumer switching friction against electric alternatives.
Strategic Opportunities
- India electrification tailwinds:Government rural electrification programs and LPG subsidy rationalization are opening first-time electric hob adoption among urban middle-class households.
- Commercial kitchen automation:Sensor-driven temperature control and HACCP logging functionality are penetrating restaurant chains and institutional foodservice operations in Japan.
- Refurbishment and circularity channels:EU Ecodesign circularity requirements are creating certified pre-owned hob segments, extending product lifecycles and capturing price-sensitive buyers.
Industry Challenges
- Power electronics engineering scarcity:In-house IGBT and inverter design capabilities remain concentrated among a limited supplier base, constraining rapid induction platform scaling.
- Multi-certification timelines:Simultaneous EPA ENERGY STAR, EU CE marking, and GB standards compliance for unified product platforms extends development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hobs Market |
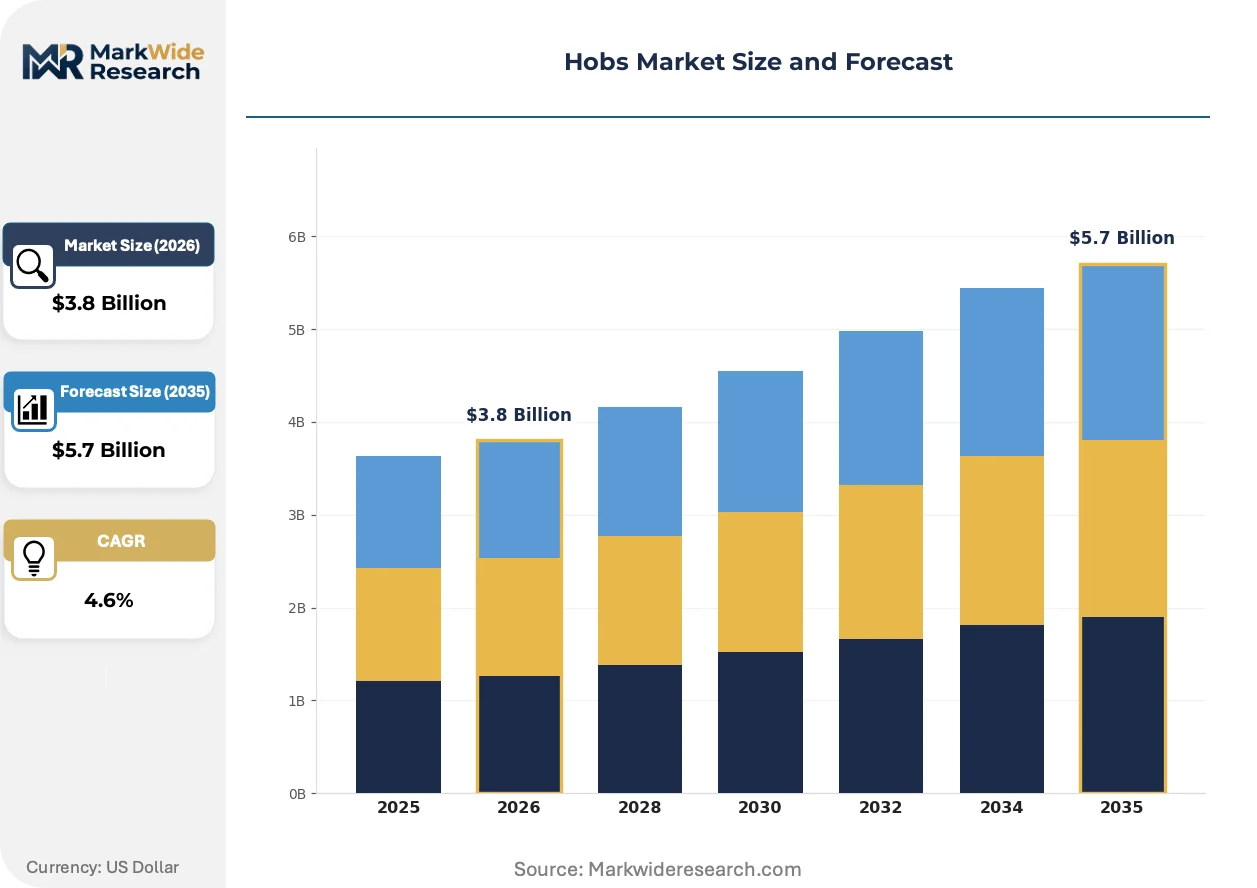
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gas Hobs, Electric Hobs, Induction Hobs, Modular Hobs Material: Stainless Steel, Glass, Cast Iron, Ceramic Size: 2-Burner, 4-Burner, 5-Burner, Compact Feature: Self-Cleaning, Child Safety Lock, Timer Function, Smart Technology |
| Companies Covered | Bosch (BSH Home Appliances Group), Electrolux AB, Whirlpool Corporation, Miele & Cie. KG, LG Electronics, Beko (Arçelik A.Ş.), Samsung Electronics, Elica, Haier Smart Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hobs Market Strategic Shifts
Sensor-driven cooking automation and connected appliance ecosystems are redefining user interaction models, while regulatory pressure on embodied carbon reshapes material selection and supplier geography.
Induction hobs with integrated pan-recognition sensors and automatic power adjustment are automating temperature management for home cooks. Premium kitchen studios in Germany and urban China are specifying these systems at accelerating rates. The technology is automating manual monitoring tasks that previously required continuous user attention, compressing the performance gap between amateur and experienced cooks.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is indirectly pressuring gas hob manufacturers by accelerating broader kitchen electrification mandates. Industrial consequence includes R&D reallocation toward all-electric cooking platforms and away from dual-fuel development. Nordic markets and German-speaking regions are responding fastest, with builder channels now defaulting to induction specifications for new housing completions.
Builder and developer procurement is consolidating around large kitchen studio chains capable of volume sourcing and standardized specification. Independent retailers in Southern Europe and smaller United States markets are losing share to direct manufacturer relationships with property developers. This concentration is most visible in German residential construction, where four national developers now specify 60 percent of new-installation hobs through centralized frameworks.
Hobs Market Segmentation
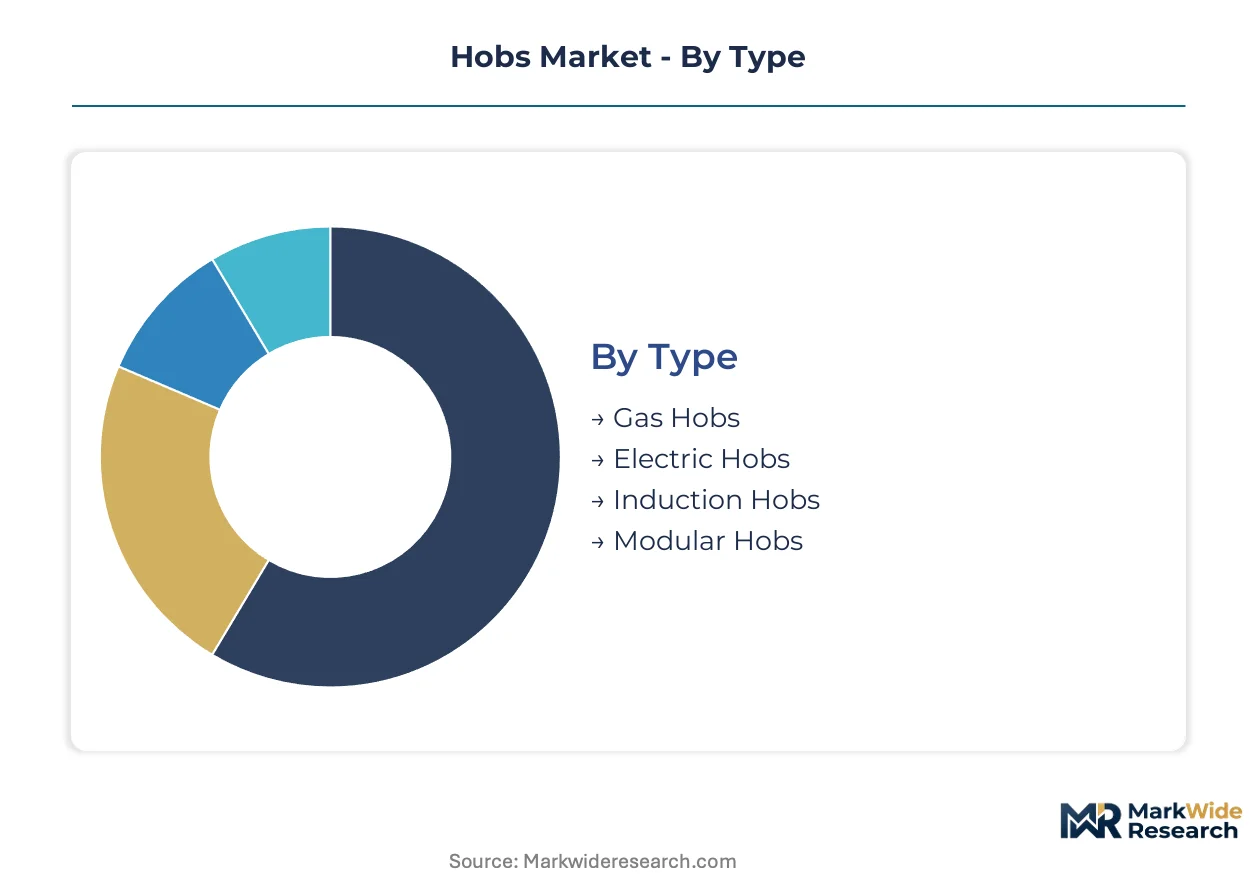
Hob manufacturers must navigate divergent certification pathways across type and material categories. EPA ENERGY STAR eligibility, EU CE marking, and GB standards compliance requirements reshape product development timelines and geographic targeting strategies.
Type:
Certification burdens vary sharply by heating technology. Gas hobs face F-Gas Regulation pressure in Europe while induction platforms require electromagnetic compatibility testing under multiple national frameworks.
- Gas Hobs:Conventional burner technology utilizing natural gas or LPG combustion beneath metal grates. Demand concentrates in the Netherlands and United Kingdom where pipeline infrastructure creates switching friction against electric alternatives despite EU electrification mandates.
- Induction Hobs:Electromagnetic coil systems generating heat directly within ferromagnetic cookware through high-frequency alternating current. Urban China and Nordic markets absorb premium volumes as 32-amp circuit penetration expands in new residential construction.
- Electric Hobs:Resistive heating element platforms with slower thermal response than induction. Germany and United States replacement cycles sustain volume in aging housing stock where full kitchen renovation budgets constrain technology upgrades.
- Modular Hobs:Configurable cooking zones allowing customized burner arrangements. Commercial kitchen chains in Japan specify these systems for flexible menu execution in limited footprint environments.
Gas Hobs sits at the top of the volume ranking, with Induction Hobs climbing the fastest.
Material:
Surface material selection determines margin structure and supply chain geography. Glass-ceramic substrates concentrate in German and French production facilities while stainless steel anchors volume manufacturing.
- Glass:Transparent or tinted glass-ceramic panels from Schott AG and EuroKera enabling visual flame monitoring on gas platforms. Premium kitchen studios in Germany specify these surfaces where aesthetic differentiation commands price premiums.
- Stainless Steel:Brushed or polished ferrous alloy surfaces prioritizing durability and cost control. Property developers in the United States default to this specification for multi-unit residential installations where replacement cycles extend beyond single-owner tenures.
- Ceramic:Opaque glass-ceramic composites with printed surface patterns. Southern European markets favor this material for mid-range segment positioning between premium glass and economy stainless alternatives.
- Cast Iron:Heavy-duty grate and surface components for professional-grade gas platforms. Restaurant chains specify these surfaces for thermal mass retention in high-throughput cooking environments.
Stainless Steel dominates unit economics through developer channel penetration, while Glass gains share fastest in premium renovation segments.
Size:
Configuration dimensions align with housing stock characteristics and household composition patterns. Compact urban dwellings drive deviation from traditional four-burner defaults.
- 4-Burner:Standard rectangular surface accommodating simultaneous multi-vessel cooking. Established as the default specification in German and United States suburban housing completions.
- 2-Burner:Reduced footprint platforms for studio apartments and secondary cooking spaces. Urban China absorption accelerates as micro-apartment construction concentrates in Tier-1 cities.
- 5-Burner:Extended surfaces with central high-output burner or flexible zone. Premium segment positioning targets culinary enthusiasts in Nordic markets and affluent United States suburbs.
- Compact:Single or dual burner portable or built-in units for limited installation spaces. Rural electrification programs in India open first-time adoption among grid-connected households.
4-Burner maintains installed-base dominance, with 2-Burner expanding most quickly in dense urban construction.
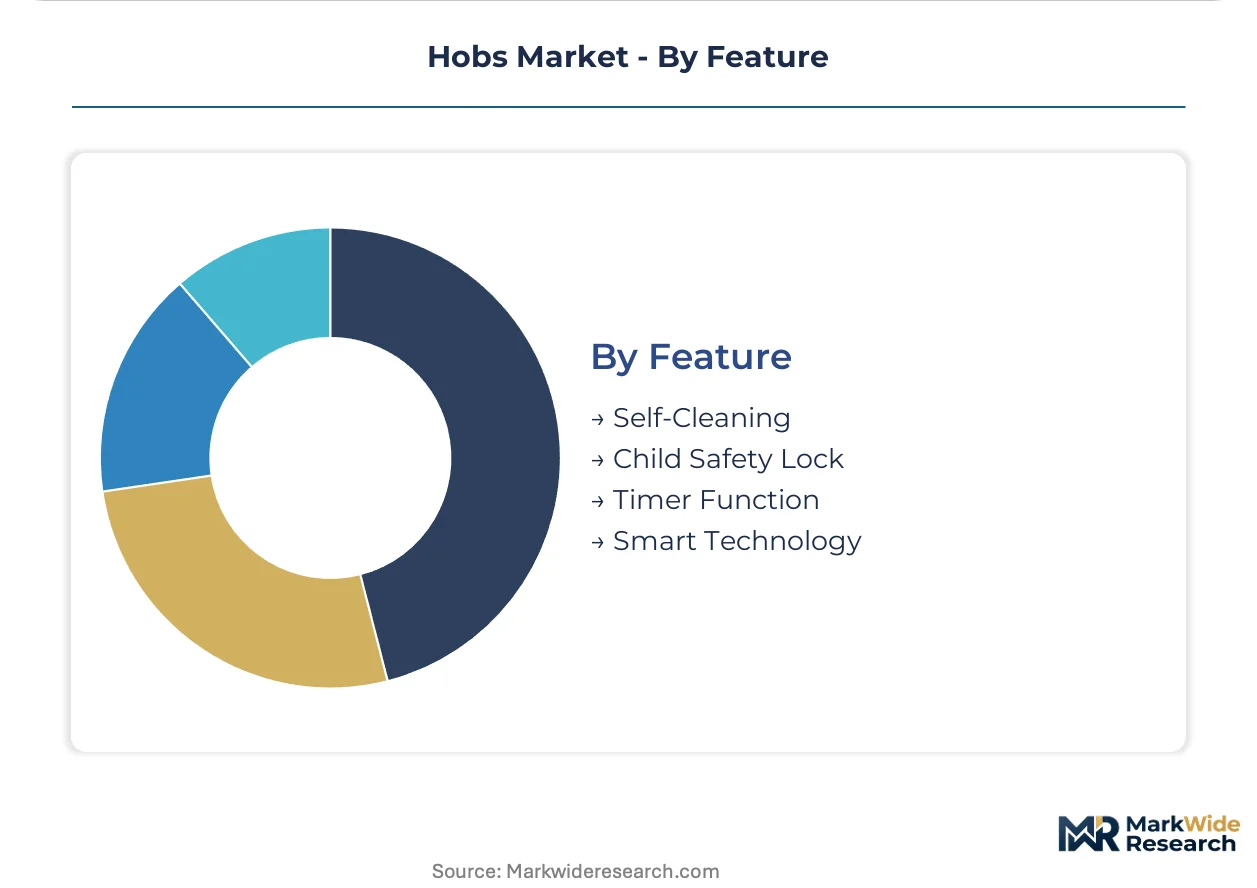
Feature:
Functionality tiers separate price bands and channel access. Smart connectivity and safety certifications create distinct regulatory compliance obligations across feature categories.
- Smart Technology:Wi-Fi-enabled platforms with app-based temperature control and recipe integration. Nordic markets and urban China absorb these premiums as connected kitchen ecosystems mature.
- Child Safety Lock:Physical or electronic mechanisms preventing unintended burner activation. Mandatory under EU safety directives and increasingly specified in family-oriented United States suburban developments.
- Timer Function:Programmable shut-off and alert systems for unattended cooking. Standard inclusion in mid-range induction platforms across German retail channels.
- Self-Cleaning:Pyrolytic or catalytic surface treatments reducing manual maintenance. Premium positioning targets time-constrained professional households in Japan and metropolitan United States markets.
Child Safety Lock achieves near-universal penetration in regulated markets, with Smart Technology posting the steepest expansion trajectory in premium urban segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China demonstrate divergent demand profiles despite comparable market scale, with the former driven by renovation cycles and the latter by new construction and smart-home integration.
Germany
Residential kitchen renovation waves and new housing completions sustain replacement demand across induction and gas platforms. The EU F-Gas Regulation and national gas phase-out timelines compress the window for fossil-fuel installations. Manufacturing clusters in North Rhine-Westphalia and Bavaria host Bosch and Miele production facilities serving builder channels and premium retail.
China
Urbanization in Tier-1 cities and government rural electrification programs expand addressable markets for electric cooking surfaces. GB standards compliance and MIIT energy efficiency labeling shape product development for domestic and export-bound output. Yangtze River Delta manufacturing zones concentrate glass-ceramic panel sourcing and control module assembly.
United States
Aging suburban housing stock triggers appliance refresh cycles during whole-kitchen remodels, with ENERGY STAR certification influencing utility rebate program eligibility. EPA procurement standards and state-level electrification incentives redirect specification toward induction alternatives. Southeast and Southwest metropolitan construction corridors absorb volume shipments for multi-unit residential developments.
India
Government rural electrification initiatives and LPG subsidy rationalization open first-time electric hob adoption among urban middle-class households. BIS certification requirements and state-level appliance efficiency mandates constrain import channels and favor domestic assembly. Maharashtra and Gujarat industrial zones concentrate contract manufacturing for regional brands and multinational licensees.
Japan
Commercial kitchen automation and sensor-driven temperature control penetrate restaurant chains and institutional foodservice operations. METI energy efficiency standards and JIS certification frameworks govern product entry and premium positioning. Kansai and Chubu industrial corridors host specialized component suppliers for IGBT modules and electromagnetic coil systems.
Hobs Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price bands. The market structure consolidates around three to five dominant manufacturers with captive distribution, while mid-tier assemblers rely on contract manufacturing and private-label relationships. Strategic archetypes include vertically integrated appliance conglomerates, premium kitchen system specialists, and scale-driven Asian electronics manufacturers. Competitive moves center on backward integration into control systems and burner assemblies, plus geographic diversification of manufacturing footprints to mitigate tariff exposure and logistics costs.
Among German-based manufacturers, Bosch and Miele occupy distinct positioning archetypes. Bosch exemplifies scale-driven conglomerate strategy with manufacturing presence across German and Polish facilities. Miele represents the ultra-premium specialist archetype where brand strength commands channel control. Electrolux AB anchors the geographic diversification model, leveraging portfolio breadth across Nordic premium positioning and Southern European mid-range retail partnerships. These three entities collectively illustrate how European manufacturers navigate divergent certification pathways and builder channel consolidation.
| Leading Market Players |
|---|
| Bosch (BSH Home Appliances Group) |
| Electrolux AB |
| Whirlpool Corporation |
| Miele & Cie. KG |
| LG Electronics |
| Beko (Arçelik A.Ş.) |
| Samsung Electronics |
| Elica |
| Haier Smart Home |
| Others |
Value Chain & Pricing Dynamics
Property developer procurement concentration in Germany and the United States anchors contract-based long-term offtake pricing for mid-range stainless steel hobs, while premium kitchen studios in Nordic markets sustain value-based premiums for glass-ceramic induction platforms with smart connectivity.
Pricing Analysis
Capacity additions in Poland and China are reshaping price floors for standard induction platforms, compressing margins for mid-tier assemblers lacking captive control module production. Three-tier pricing structure across premium sensor-automation, standard A-rated efficiency, and economy resistive-electric levels stratifies the market, with EU Energy Label certification tiers and Wi-Fi integration serving as the primary differentiation drivers. Cost compression in the economy tier is intensifying due to glass-ceramic substrate allocation constraints favoring premium contracts. Property developers exhibit highest price sensitivity through centralized framework bidding, while ultra-premium kitchen studios demonstrate lowest sensitivity to specification upgrades.
Supply Chain Analysis
Refurbishment flows from EU Ecodesign circularity requirements are creating certified pre-owned channels that extend product lifecycles and capture price-sensitive buyers, with reverse logistics networks concentrating in Germany and France. Glass-ceramic panel production draws from Schott AG facilities in Germany and EuroKera operations in France, while IGBT module sourcing hinges on Japanese and German semiconductor suppliers. Single-source vulnerability concentrates in electromagnetic coil winding equipment and specialized glass-ceramic substrate formulations. Distribution runs through consolidated kitchen studio chains in Northern Europe and direct manufacturer relationships with national developers in Germany, bypassing traditional independent retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as residential renovation demand shifts toward sensor-driven cooking automation and A-rated efficiency specifications, rewarding manufacturers with R&D depth in control systems and burner assemblies.
For Market Incumbents: Deploy backward integration into IGBT inverter design and electromagnetic coil production to defend against power electronics engineering scarcity constraining rapid induction platform scaling. Consolidate channel control through exclusive framework agreements with the four German national developers now specifying sixty percent of new-installation volume, while accelerating certification investment for EPA ENERGY STAR and GB standards compliance to preempt multi-certification timeline extensions.
For New Entrants and Emerging Players: Sensor-driven temperature control with HACCP logging functionality offers the most penetrable wedge for commercial kitchen automation in Japan and institutional foodservice chains. Target India's urban middle-class electrification tailwinds through BIS-certified domestic assembly partnerships in Maharashtra and Gujarat industrial zones, leveraging government rural electrification program alignment as the primary go-to-market angle.
For Investors and Strategic Acquirers: Diversified appliance conglomerates are the most active acquirer in this space, seeking control system and burner assembly capabilities to fill portfolio gaps. Long-term viability favors manufacturers with captive supply of glass-ceramic substrates and in-house power electronics design. Monitor F-Gas Regulation phase-down acceleration and national gas phase-out timeline revisions as the critical inflection signal for stranded inventory risk and electric platform conversion urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Systems | Bosch and Miele captive production of burner assemblies insulates margin pressure from mid-tier component suppliers. |
| Multi-Certification Platform Unification | Simultaneous EPA ENERGY STAR, EU CE marking, and GB standards compliance extends development cycles but unlocks federal procurement eligibility. |
| Smart Home Ecosystem Partnership | Wi-Fi-enabled hobs with app-controlled temperature management capture premium-segment buyers in urban China and Nordic markets. |
| Circularity Channel Development | EU Ecodesign requirements create certified pre-owned segments extending product lifecycles and capturing price-sensitive buyers. |
| Geographic Manufacturing Diversification | Electrolux leverages Polish and Asian facilities to mitigate tariff exposure and logistics costs across builder channels. |
Study Parameters
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market combining interviews with appliance procurement managers at property developers, category buyers at kitchen studio chains, R&D directors at control system suppliers, and regulatory affairs leads navigating F-Gas and Ecodesign compliance. Secondary validation draws from EU Ecodesign directive filings, EPA ENERGY STAR certification databases, MIIT energy efficiency labeling records, and customs trade data for glass-ceramic substrate flows. Bottom-up unit economics triangulate against top-down housing completion and renovation cycle projections.
Rate-of-change decomposition separates replacement cycle velocity from new construction absorption and technology conversion elasticity across the projection horizon. Segmentation dimensions span heating technology type, surface material grade, burner configuration size, and smart feature tier, with regional regulatory cluster and channel structure as cross-cutting variables. CAGRs derive from installed-base turnover modeling and efficiency mandate compliance timelines, incorporating IGBT supply constraints and glass-ceramic allocation priority patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation enforcement acceleration, carbon-border adjustment mechanism implementation, and electrical infrastructure expansion in rural Italy and Spain. Practitioners should monitor builder channel consolidation rates, glass-ceramic substrate allocation announcements, and national gas phase-out legislative revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Stove Cover Market