
 Kitchen Furniture and Fixtures Market | 2026-2036
Kitchen Furniture and Fixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Furniture and Fixtures Market Foresight
Asset-light leasing and pay-per-use financing for kitchen installations is fragmenting competitive dynamics across the value chain. Inter IKEA Group leverages its flat-pack logistics network to sustain low capital intensity in store expansion. MasterBrand Cabinets Inc. anchors its position through captive manufacturing scale across North American facilities. Nobilia GB Ltd. differentiates via precision-engineered German cabinetry standards that command specification in premium projects.
Kitchen furniture and fixtures comprise modular storage systems, work surfaces, water management units, and protective wall panels engineered from engineered wood substrates, stainless steel alloys, and sintered stone composites, manufactured through CNC routing, thermoforming, and automated edge-banding processes to deliver food-safe, moisture-resistant residential and commercial food preparation environments. Cabinets dominate product type value capture due to their centrality in spatial planning and customization intensity, while engineered quartz and porcelain countertops within the material dimension are expanding fastest as consumers prioritize stain resistance and minimal maintenance. The hospitality end user segment concentrates margin pools through specification-grade durability requirements and recurring renovation cycles in hotel and foodservice chains.
EPA formaldehyde emission standards under TSCA Title VI, CARB ATCM Phase 2 in California, and EU REACH restrictions on hazardous substances in surface coatings collectively elevate compliance costs and reshape supplier qualification criteria for wood-based panel and finish chemistry selection. These frameworks push manufacturers toward certified low-emission substrates and waterborne coating systems that require reformulation investment but unlock specification access in regulated jurisdictions. Stakeholders must monitor evolving chemical restriction schedules and building code harmonization between federal and state-level jurisdictions to anticipate product certification timelines and inventory positioning requirements.
Market Dynamics
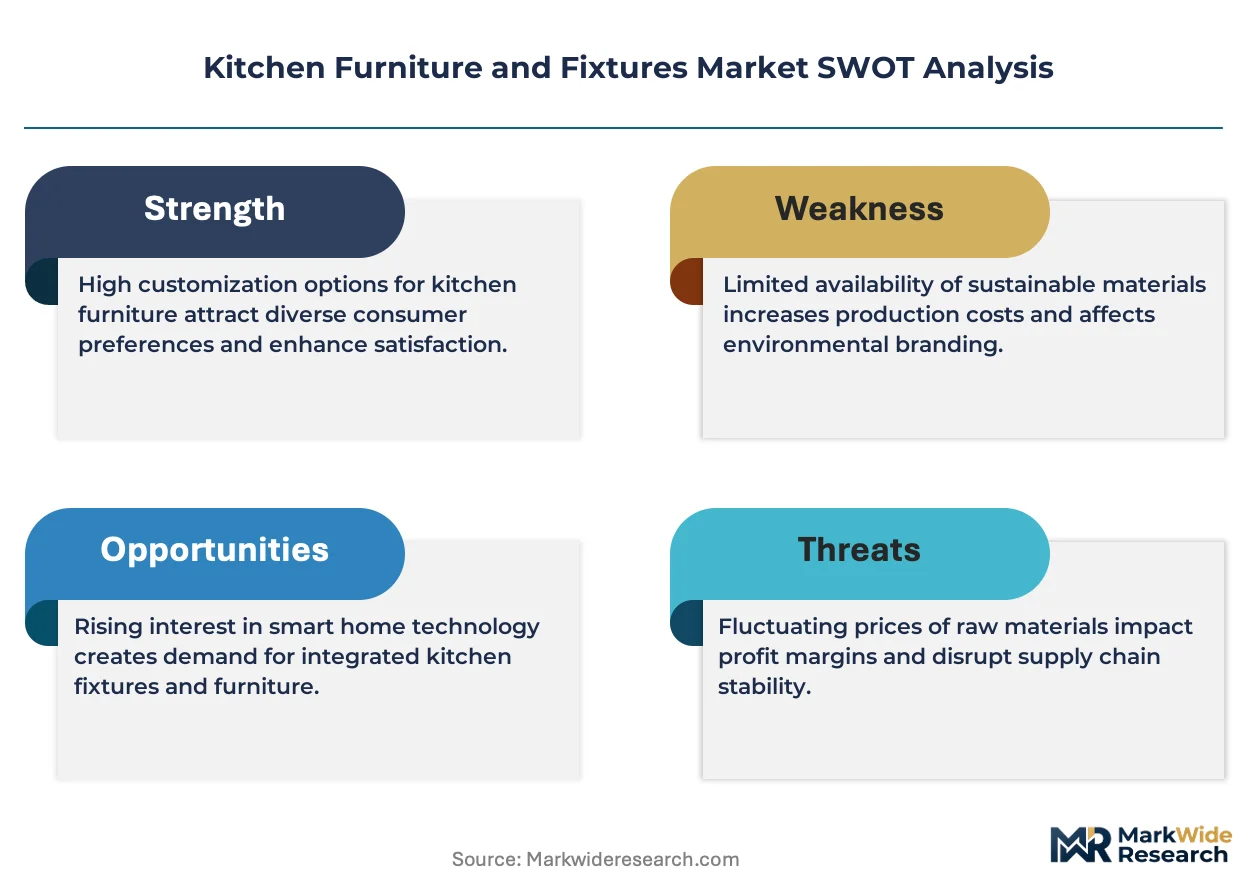
Modular manufacturing systems and flat-pack logistics networks are compressing capital requirements for kitchen furniture distribution, enabling asset-light market entry while fragmenting competitive positioning across traditional full-service incumbents.
Growth Catalysts
- Urban residential renovation cycles:Middle-class household upgrades in China and India are expanding addressable demand for cabinet systems and integrated appliances as property stock ages.
- REACH and CARB compliance premiums:Low-emission substrate certification unlocks specification access in European and Californian markets, creating margin pools for certified manufacturers.
- Sintered stone surface technology:Porcelain and engineered quartz countertops displace natural stone in premium residential projects due to stain resistance and thermal durability advantages.
Market Restraints
- Engineered wood panel cost volatility:Resin and timber input prices fluctuate with energy markets, compressing margin stability for cabinet manufacturers dependent on particleboard and MDF substrates.
- Supply concentration in Chinese hardware:Hinge, slide, and connector systems concentrate production in Zhejiang and Guangdong provinces, creating single-source vulnerability for Western assemblers.
- Formaldehyde emission testing friction:Divergent EPA TSCA Title VI and EU E1/E2 classification protocols force dual certification investments for cross-border suppliers.
Strategic Opportunities
- Subscription and pay-per-use financing:Leasing models for kitchen installations penetrate German and Dutch markets, converting capital expenditure to recurring revenue streams.
- Smart appliance integration protocols:IoT-enabled cabinetry with embedded charging, lighting, and inventory management converges with connected home ecosystems in North American new construction.
- EU Green Deal renovation wave:Building performance mandates accelerate kitchen replacement cycles in France, Italy, and Poland as energy efficiency standards tighten.
Industry Challenges
- CNC programming and automation skill scarcity:Cabinet manufacturers face recruitment friction for operators capable of managing five-axis routing and robotic edge-banding systems.
- Multi-jurisdiction certification timelines:Synchronized compliance with CARB Phase 2, EPA TSCA Title VI, and EU REACH surface coating restrictions extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Furniture and Fixtures Market |
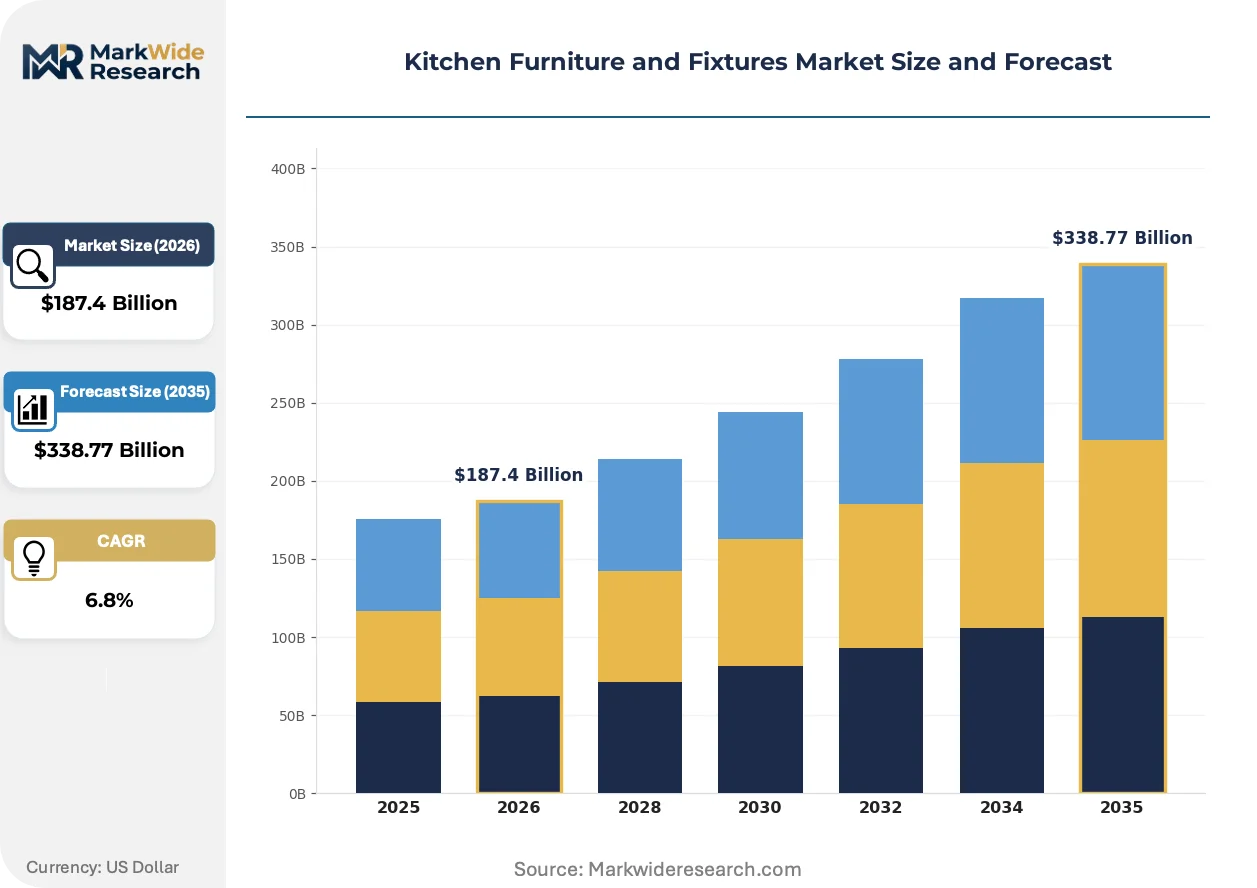
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Sinks, Backsplashes Material: Wood, Metal, Plastic, Glass Style: Modern, Traditional, Rustic, Minimalist End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Masco Corp., Symphony Group, Inter IKEA Group, Alno, Golden Home, MasterBrand Cabinets Inc., Nobilia GB Ltd., Howdens, American Woodmark Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Furniture and Fixtures Market Shifts & Advancements
Digital fabrication workflows and material science advances are compressing customization lead times while elevating performance specifications for moisture resistance and chemical safety in residential food preparation environments.
Waterborne UV-curable coating chemistry is migrating from solvent-based systems in European cabinet finishing operations. Premium German and Italian manufacturers adopt these formulations to meet ECHA restriction schedules while maintaining surface durability. The technology is compressing volatile organic compound emissions and enabling faster production line speeds without thermal curing bottlenecks.
REACH authorization requirements for hazardous substances in surface coatings are tightening supplier qualification criteria across EU member states. Manufacturers reformulate finish chemistry to eliminate restricted phthalates and isocyanates, elevating R&D intensity. Nordic and Benelux markets exhibit fastest compliance adoption due to consumer sensitivity toward indoor air quality certification.
Direct-to-consumer configuration platforms are displacing traditional kitchen studio intermediaries in North American and Australian markets. Homeowners utilize augmented reality visualization tools to specify cabinet layouts and material finishes before contractor engagement. This channel compression is most visible in metropolitan new construction segments where builder partnerships previously dominated specification authority.
Kitchen Furniture and Fixtures Market Segmentation
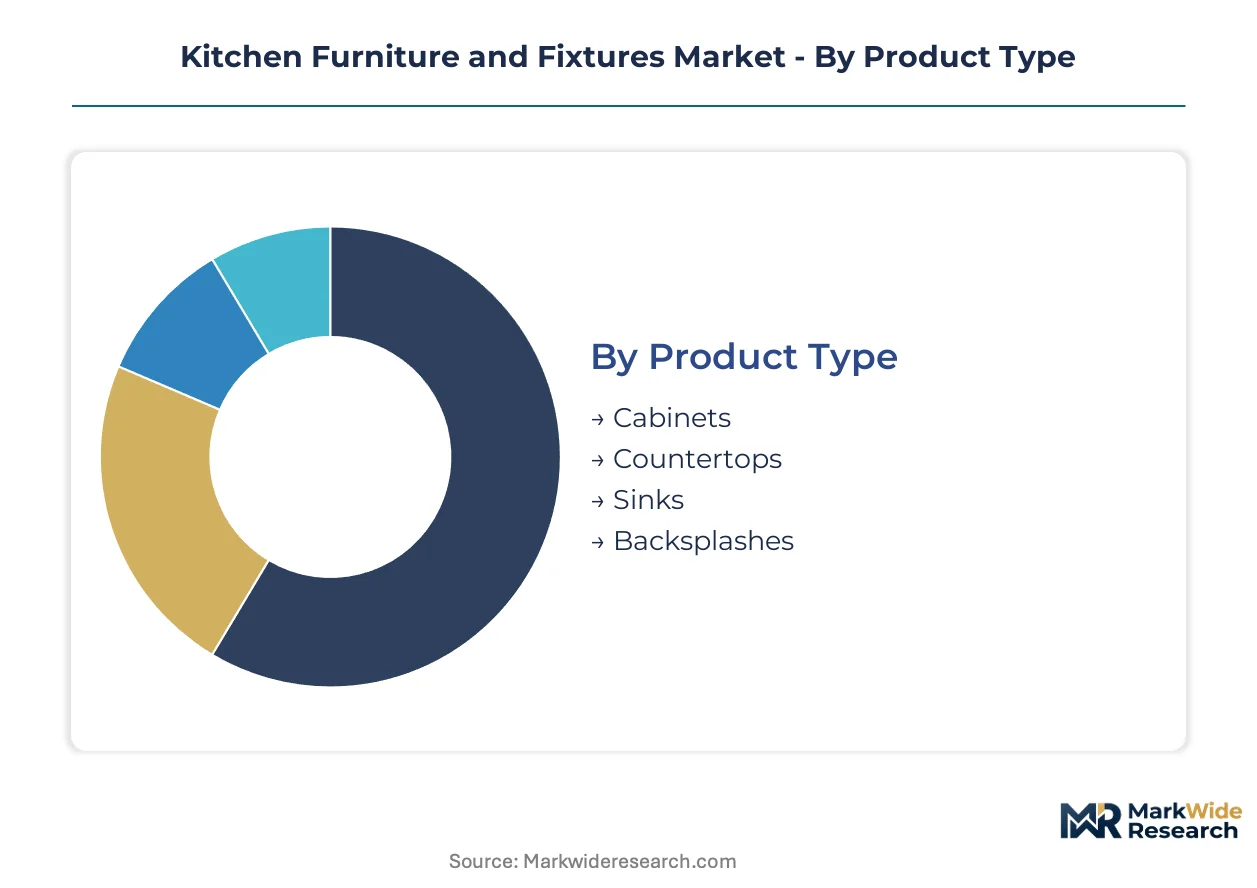
Kitchen furniture and fixtures fragment across four dimensions that determine specification authority, margin capture, and channel strategy. Product type and material selection drive capital allocation in manufacturing, while end-user category dictates compliance intensity and renovation cycle exposure.
Product Type:
Spatial planning decisions cascade through cabinet configuration, surface selection, water management, and protective cladding in residential and commercial food preparation environments.
- Cabinets:Modular storage systems engineered from particleboard, MDF, and plywood substrates with thermoformed or painted finishes dominate project value capture. Demand concentrates in Chinese urban renovation as middle-class households upgrade aging kitchen infrastructure. CARB Phase 2 and EPA TSCA Title VI certification requirements elevate supplier qualification barriers in North American specification.
- Countertops:Engineered quartz, sintered porcelain, and solid surface composites deliver stain resistance and thermal durability for high-use residential zones. Hospitality chains in Germany and France specify these materials for recurring renovation cycles driven by EU Green Deal building performance mandates.
- Sinks:Stainless steel alloys and fireclay ceramics form water management units integrated with cabinet carcasses.
- Backsplashes:Protective wall panels in ceramic tile, glass, and sintered stone shield moisture-sensitive substrates.
Cabinets command the dominant share of project value, while engineered quartz and porcelain countertops within this category are expanding most quickly through premium residential displacement of natural stone.
Material:
Substrate chemistry and surface finishing determine compliance pathways, cost volatility exposure, and indoor air quality certification access across regulated jurisdictions.
- Wood:Engineered panels—particleboard, MDF, plywood—form cabinet carcasses and shelving systems. REACH and CARB emission standards are reshaping resin formulation and supplier qualification in European and Californian markets.
- Metal:Stainless steel alloys and aluminum extrusions deliver structural hardware, sink basins, and appliance integration frames.
- Plastic:Thermoformed acrylics and polypropylene components enable seamless integration and moisture sealing.
- Glass:Tempered and laminated panels serve decorative and protective functions in backsplashes and cabinet inserts.
Wood-based substrates retain the largest volume position, though metal components are gaining specification intensity fastest through hospitality durability requirements.
Style:
Aesthetic positioning determines distribution channel access, price tier placement, and geographic demand concentration across renovation and new construction cycles.
- Modern:Flat-panel doors, integrated handles, and minimal ornamentation align with urban apartment stock in China and India. German and Italian manufacturers anchor specification through precision engineering and waterborne UV-curable coating adoption.
- Traditional:Raised-panel profiles, decorative molding, and warm wood tones persist in North American suburban renovation.
- Rustic:Distressed finishes and visible grain patterns target vacation property and regional aesthetic preferences.
- Minimalist:Handle-less systems and concealed storage maximize spatial efficiency in compact urban dwellings.
Modern styling holds the specification lead in metropolitan new construction, while Minimalist configurations are climbing fastest through direct-to-consumer configuration platforms in Australia and North America.
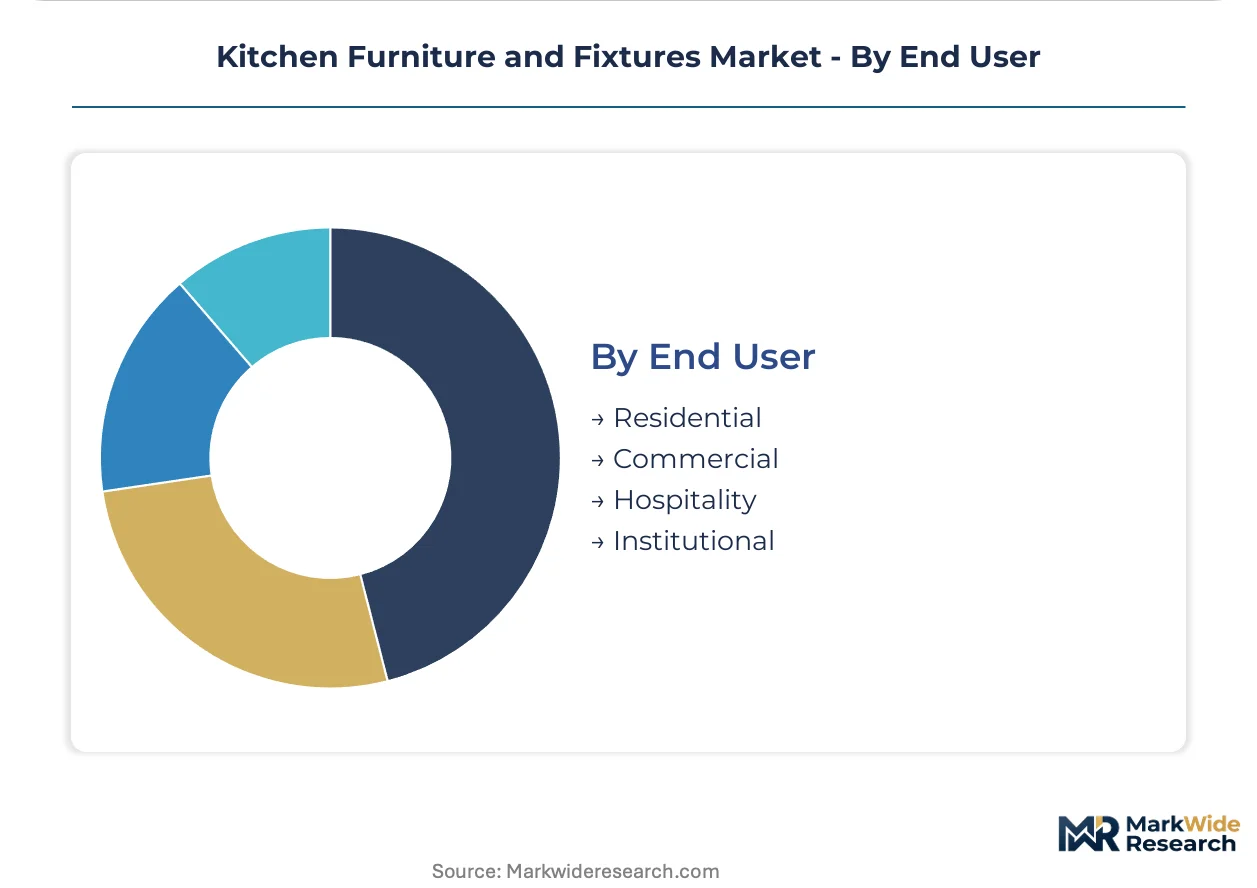
End User:
Renovation frequency, compliance stringency, and contract structure vary sharply across residential, commercial, hospitality, and institutional procurement channels.
- Residential:Single-family and multifamily homeowners drive volume through renovation cycles and new construction specification. Chinese middle-class upgrades and EU Green Deal renovation wave acceleration in France, Italy, and Poland concentrate demand expansion.
- Commercial:Foodservice operations and workplace cafeterias prioritize durability and hygiene certification.
- Hospitality:Hotel and restaurant chains concentrate margin pools through specification-grade durability requirements and recurring renovation cycles. Brand standards mandate certified low-emission substrates and waterborne coating systems.
- Institutional:Healthcare, education, and government facilities enforce procurement protocols emphasizing chemical safety and lifecycle cost.
Residential channels absorb the dominant volume share, though Hospitality procurement is gaining margin intensity fastest through recurring replacement cycles and specification-grade compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting manufacturing footprints as currency volatility and freight cost pressures reshape sourcing decisions. Major consuming markets are deepening domestic fabrication capacity to reduce lead-time exposure and capture compliance premiums.
United States
Single-family renovation cycles and multifamily new construction in Texas and Florida are absorbing cabinet volumes. EPA TSCA Title VI formaldehyde emission standards and California CARB ATCM Phase 2 enforcement are elevating substrate certification requirements. Production clusters in North Carolina and Virginia concentrate particleboard milling and thermoforming operations serving Eastern seaboard distribution.
Germany
EU Green Deal renovation wave mandates are accelerating kitchen replacement cycles in owner-occupied housing. ECHA REACH authorization schedules for surface coating chemistry are forcing reformulation investments among finish suppliers. The Ostwestfalen-Lippe region anchors precision-engineered cabinetry manufacturing with automated edge-banding and CNC routing density.
China
Middle-class household upgrades in Shanghai, Beijing, and Shenzhen are expanding demand for integrated cabinet-appliance systems. GB standards for indoor air quality and formaldehyde emission classification are tightening supplier qualification protocols. Zhejiang and Guangdong provinces concentrate hardware component manufacturing for hinge, slide, and connector systems.
India
Urban residential stock aging in Mumbai, Delhi-NCR, and Bangalore is driving modular kitchen penetration among affluent households. BIS certification requirements for engineered wood panel emissions are emerging as procurement filters in premium projects. Gujarat and Maharashtra are developing laminated particleboard and MDF substrate capacity to reduce import dependency.
United Kingdom
Housing transaction recovery and buy-to-let renovation activity in Greater London and Southeast England are sustaining replacement demand. Building Regulations Part F ventilation standards and impending Future Homes compliance are influencing kitchen spatial planning. The East Midlands and Yorkshire clusters concentrate flat-pack assembly and distribution logistics serving national retail networks.
Kitchen Furniture and Fixtures Market Competitive Landscape
On the supply side, the industry is structurally fragmented across three distinct tiers: multinational mass-market retailers with captive logistics networks, regional specialists with manufacturing scale in protected geographies, and niche fabricators serving specification-grade hospitality and institutional channels. Strategic archetypes include flat-pack logistics innovators, captive-manufacturing scale players, and precision-engineered premium specialists. Dominant competitive moves center on modular manufacturing system deployment and direct-to-consumer configuration platform development.
Among scale-driven fabricators, Masco Corp. and MasterBrand Cabinets Inc. exemplify North American manufacturing consolidation, while Inter IKEA Group occupies a position defined by global flat-pack logistics density. Nobilia GB Ltd. represents the precision-engineered German cabinetry archetype that commands specification access in premium residential and commercial projects.
| Leading Market Players |
|---|
| Masco Corp. |
| Symphony Group |
| Inter IKEA Group |
| Alno |
| Golden Home |
| MasterBrand Cabinets Inc. |
| Nobilia GB Ltd. |
| Howdens |
| American Woodmark Corp. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese particleboard milling is compressing supplier margins and forcing price concessions downstream, while simultaneously triggering inventory liquidation that destabilizes spot pricing for Western cabinet assemblers dependent on engineered wood substrates.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures in hospitality and commercial channels, where specification-grade durability requirements command premium-mid-economy pricing differentiation based on CARB Phase 2 certification status and after-sales installation bundling. Cost compression in economy-tier residential cabinetry is intensifying because resin and timber input volatility erodes manufacturer margin stability. Property developers exhibit highest price sensitivity through volume tender processes, while boutique hotel operators demonstrate lowest sensitivity due to brand-standard compliance mandates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for hinge, slide, and connector hardware sourced from Zhejiang and Guangdong provinces. Manufacturing gravity centers on China, Germany, and Poland for cabinet carcasses, with engineered wood panel production drawing from timber feedstocks and thermosetting resin chemistry. Single-source vulnerability concentrates in Chinese hardware components. Distribution runs through flat-pack logistics networks serving mass-market retail and direct-to-consumer configuration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kitchen furniture and fixtures market is entering a cyclical recovery phase as urban residential renovation cycles in China and India reaccelerate replacement demand for aging kitchen infrastructure.
For Market Incumbents: Entrench specification authority in hospitality channels by deepening captive manufacturing scale in EPA TSCA Title VI certified facilities, while accelerating waterborne UV-curable coating adoption to preempt ECHA restriction schedules. Vertical integration into hardware component sourcing mitigates Zhejiang supply concentration risk. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer configuration platforms serving Australian and North American metropolitan new construction, where augmented reality visualization tools displace traditional kitchen studio intermediaries. Target minimalist styling segments with handle-less systems for compact urban dwellings. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across flat-pack logistics innovators leveraging modular manufacturing systems, compressing capital requirements for market entry. Acquisition candidates include precision-engineered German cabinetry specialists with REACH-compliant finish chemistry and automated CNC routing density. Monitor EU Green Deal renovation wave implementation velocity in France and Italy as cyclical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Coating Reformulation | ECHA REACH authorization schedules force finish chemistry investment that unlocks EU specification access. |
| Flat-Pack Logistics Expansion | Inter IKEA Group's asset-light model compresses store expansion capital intensity across emerging markets. |
| Smart Appliance Integration | IoT-enabled cabinetry with embedded charging converges with connected home ecosystems in North American new construction. |
| Direct-to-Consumer Platform Launch | Augmented reality visualization tools displace kitchen studio intermediaries in metropolitan renovation segments. |
| Certified Substrate Manufacturing Scale-Up | EPA TSCA Title VI and CARB Phase 2 compliance unlocks specification access in regulated North American jurisdictions. |
Research Methodology
Desk research of trade customs data, SEC 10-K filings, and EU ECHA regulatory databases preceded structured interviews with cabinet manufacturing plant managers, hospitality procurement directors, engineered wood panel R&D leads, and flat-pack logistics operators. Primary fieldwork combined with secondary validation across CARB ATCM enforcement records and building permit databases enabled bottom-up and top-down triangulation of volume estimates.
Assumptions around urban residential renovation cycle duration, REACH authorization implementation timelines, and sintered stone surface technology displacement rates were held fixed across the projection horizon, while energy price volatility and currency fluctuation were modeled as scenario variables. Segmentation dimensions included product type, material chemistry, styling archetype, and end-user procurement channel. CAGRs were derived from installed base aging analysis and replacement cycle frequency modeling, with hospitality renovation cadence and EU Green Deal building performance mandates serving as key demand inputs.
Sensitivities concentrate around formaldehyde emission testing protocol harmonization between EPA TSCA Title VI and EU E1/E2 classifications, engineered wood panel resin cost volatility, and Chinese hardware supply disruption scenarios. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
North America Tabletop Kitchen Products Market