
 India Kitchen Furniture Market | 2026-2036
India Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
India Kitchen Furniture Market Insights
Modular manufacturing technology is fragmenting traditional carpentry-based kitchen production across India. Godrej Interio leverages its pan-India distribution network to supply standardized modular units at scale. Hafele anchors premium hardware and fitting systems that differentiate imported-equivalent specifications from local alternatives. Johnson Kitchens specializes in mid-market laminate finishes that compete effectively against unorganized sector fabricators.
India kitchen furniture encompasses engineered storage and work surface assemblies fabricated from plywood, MDF, particle board, or solid wood with laminated, veneered, or painted finishes, designed for residential and commercial food preparation spaces. BIS IS:303 and IS:710 standards govern plywood quality for moisture resistance and structural integrity in humid kitchen environments. Wood-based materials dominate volume shipments, though metal and glass accents are gaining share in premium contemporary and modern style segments. Residential end users absorb the majority of output, while hospitality and commercial applications command higher per-unit margins due to durability specifications and customization requirements.
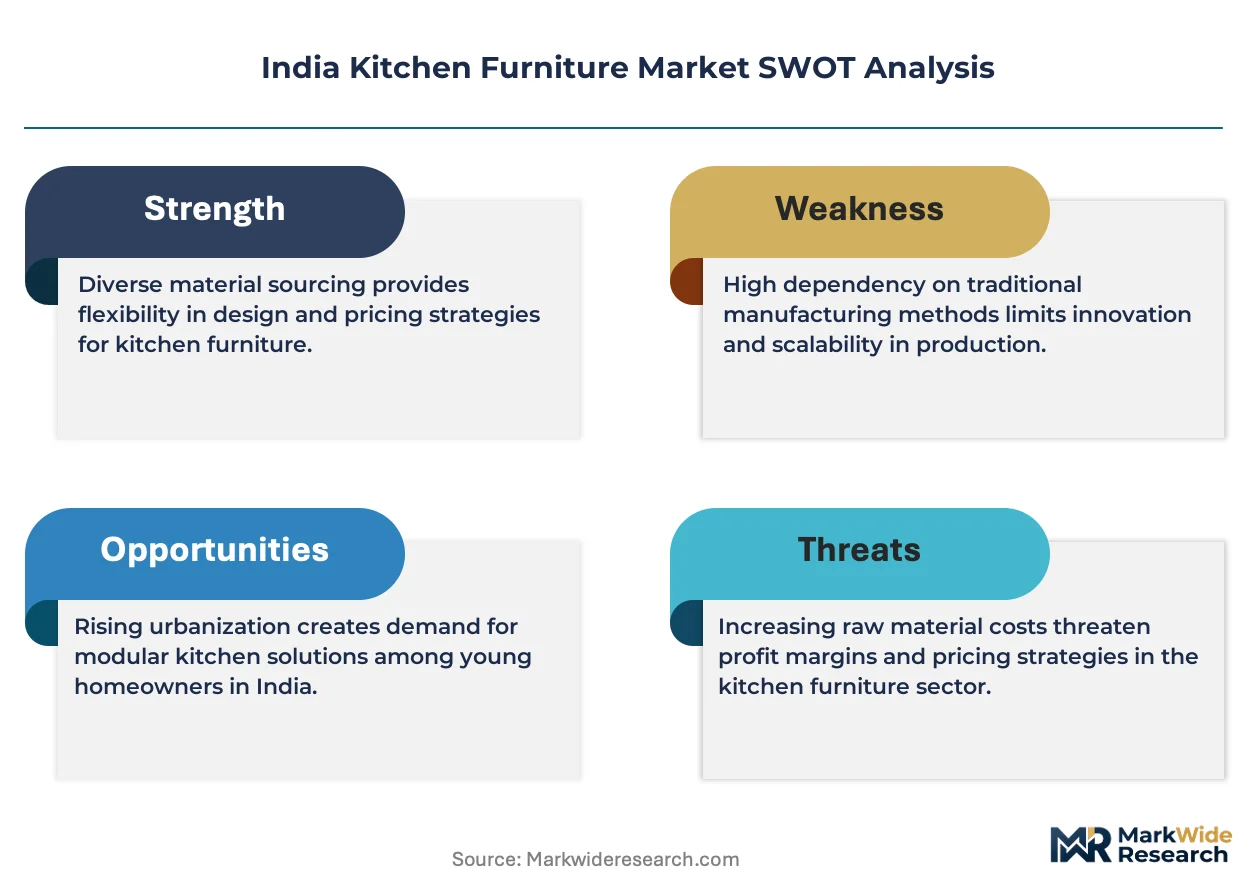
BIS mandates, the Bureau of Indian Standards certification scheme for engineered wood products, and state-level RERA compliance for delivered apartment specifications collectively shape product quality thresholds and supplier eligibility. The Ministry of Environment's emission norms for formaldehyde in composite boards are pressuring manufacturers toward E1 and E0 grade adhesives. Stakeholders must monitor evolving BIS amendments and state building codes to anticipate material substitution timelines and certification investment requirements.
Market Dynamics
Modular manufacturing systems are systematically dismantling India's carpentry-based kitchen production, compressing delivery timelines from weeks to days while standardizing quality across Maharashtra, Karnataka, and Delhi NCR urban clusters.
Growth Catalysts
- Nuclear family formations:Smaller household units in premium Mumbai and Bangalore residential projects demand compact, efficient storage configurations that modular systems deliver at scale.
- BIS IS:710 certification:Mandatory moisture-resistance standards for marine-grade plywood are filtering out unorganized fabricators and elevating consumer trust in certified suppliers.
- MDF and particle board substitution:Engineered wood materials priced below solid timber are expanding addressable demand into mid-income apartment segments previously served by local carpenters.
Market Restraints
- Formaldehyde emission compliance costs:Ministry of Environment mandates for E1 and E0 grade adhesives are raising input costs for composite board manufacturers.
- Plywood supply concentration:Kerala and Gujarat dominate moisture-resistant plywood production, creating vulnerability to monsoon logistics disruptions and regional price spikes.
- Skill scarcity in modular installation:Certified technicians capable of precision fitting remain concentrated in tier-1 cities, limiting rollout velocity in tier-2 markets.
Strategic Opportunities
- PLI scheme for furniture manufacturing:Production-linked incentives for domestic wood processing are attracting capital investment into integrated panel production facilities.
- Smart kitchen convergence:IoT-enabled appliances and sensor-integrated cabinetry are creating premium upgrade cycles in Delhi NCR luxury housing.
- Commercial hospitality retrofit:Durability-specified modular systems for hotels and cloud kitchens command margins significantly above residential installations.
Industry Challenges
- BIS amendment tracking burden:Evolving IS:303 and IS:710 standards require continuous laboratory testing investment that strains mid-tier manufacturer cash flows.
- Carpentry workforce displacement friction:Traditional fabricators resist modular adoption, creating last-mile installation quality variance and customer complaint escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Kitchen Furniture Market |
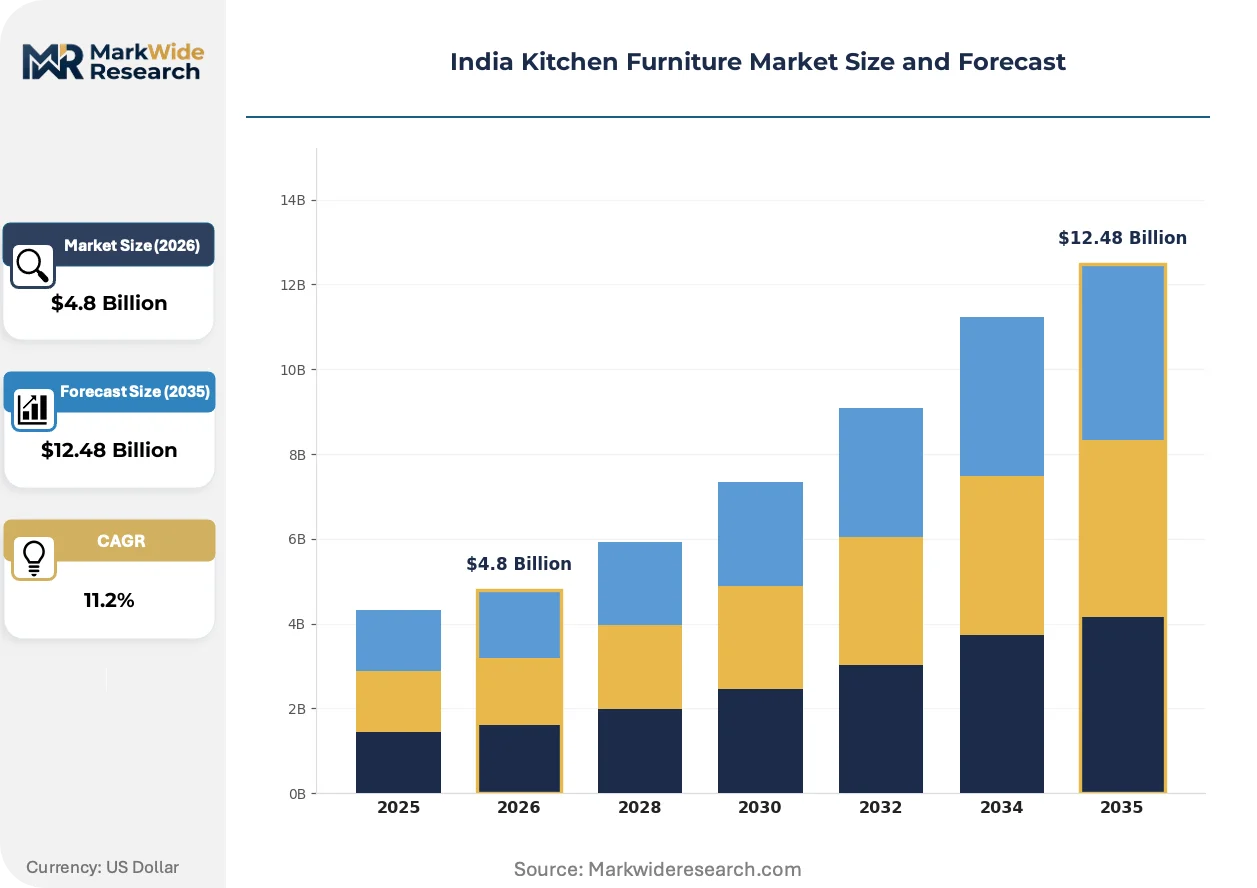
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Shelves, Tables, Chairs Material: Wood, Metal, Glass, Plastic Style: Modern, Traditional, Rustic, Contemporary End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Sleek, Johnson Kitchens, Hafele, Haecker, Kohler, Godrej Interio, Ebco, Evok, Spacewood, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Kitchen Furniture Market Trends and Innovations
Digital design-to-manufacture workflows are compressing the specification-to-installation cycle while material science advances enable thinner, stronger panels that expand usable kitchen volume in compact Indian apartments.
Acrylic and high-gloss laminate surfaces are hybridizing with traditional wood substrates to deliver imported-equivalent aesthetics at domestic price points. Premium apartment developers in Bangalore specify these finishes for model unit differentiation. The technology is hybridizing supply chains as laminate importers backward-integrate into local pressing operations to capture margin.
BIS mandates for formaldehyde emission testing under Ministry of Environment norms are accelerating adhesive formulation shifts. Composite board manufacturers must reformulate binding agents or forfeit certification eligibility. Maharashtra-based panel producers are responding fastest, leveraging proximity to testing laboratories and chemical suppliers.
Builder-direct procurement is consolidating specification authority away from end consumers. Large residential developers in Mumbai now mandate pre-approved modular vendor lists, compressing fabricator choice and standardizing apartment fit-outs. This concentration is most visible in RERA-registered projects where delivered specifications face post-handover audit scrutiny.
India Kitchen Furniture Market Segmentation
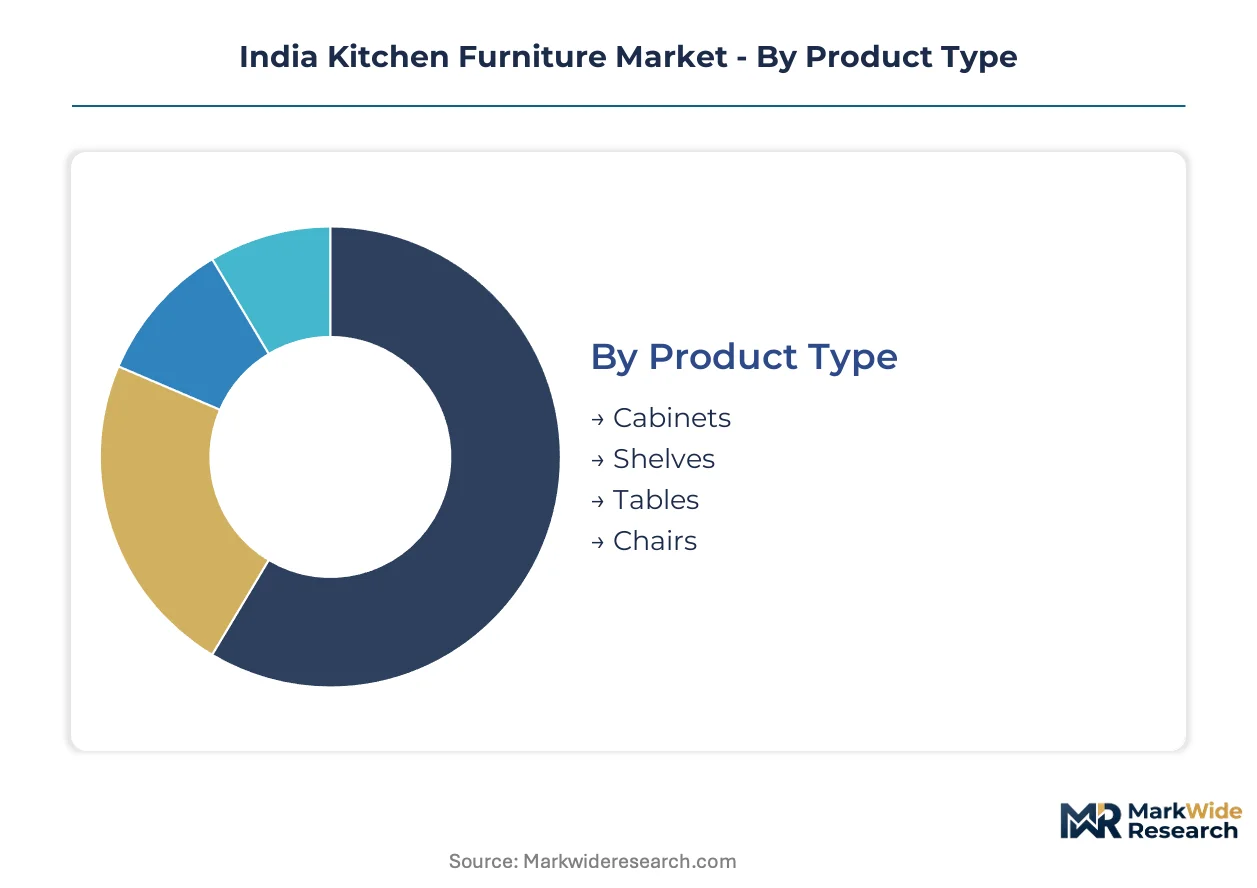
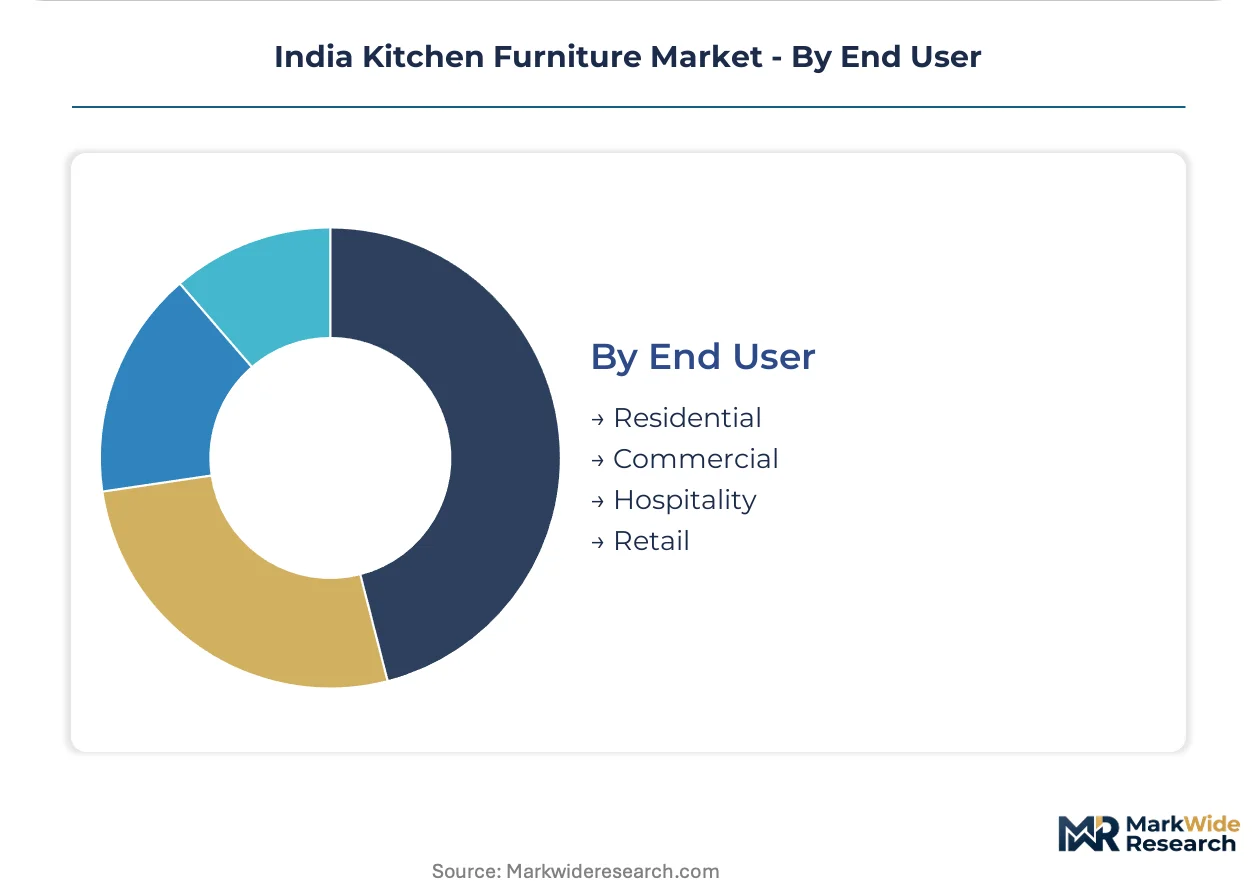
India kitchen furniture segmentation reveals how modular manufacturing, BIS certification tiers, and urban housing configurations reshape procurement patterns across Maharashtra, Karnataka, and Delhi NCR. Understanding these divides exposes where certified suppliers capture margin versus where unorganized fabricators retain price-sensitive volume.
Product Type:
Mature storage systems dominate revenue while emerging surface categories gain specification authority in premium residential projects.
- Cabinets:Base and wall-mounted storage units fabricated from BIS IS:710 certified marine-grade plywood or MDF with laminate facing. Mumbai and Bangalore luxury apartment developers specify these as builder-direct procurement bundles, compressing consumer choice but standardizing moisture-resistant quality.
- Shelves:Open and closed storage configurations in fixed or adjustable formats. Delhi NCR nuclear family housing demands space-efficient floating shelf systems that modular manufacturers deliver in standardized dimensions, displacing carpenter-fabricated alternatives.
- Tables:Freestanding work surfaces including island and dining-integrated formats.
- Chairs:Seating units for breakfast nooks and informal dining attached to kitchen spaces.
Cabinets retain volume leadership; shelves hold the steepest expansion curve.
Material:
Cost tier stratification separates certified engineered wood from premium imports and economy unorganized supply.
- Wood:Plywood, MDF, particle board, and solid timber with laminated, veneered, or painted finishes. Maharashtra panel producers dominate moisture-resistant plywood supply under BIS IS:303 and IS:710 mandates, though Kerala and Gujarat production concentration creates monsoon logistics vulnerability.
- Metal:Stainless steel and aluminum framing with powder-coated or brushed finishes. Bangalore contemporary-style apartments specify metal-accented cabinetry for imported-equivalent aesthetics at domestic price points.
- Glass:Tempered and lacquered panel inserts for cabinet doors and shelving.
- Plastic:Polymer-based storage accessories and modular fitting components.
Wood commands installed base dominance; metal captures the fastest specification gains in premium urban clusters.
Style:
Application context dictates style selection — developer-driven standardization versus end-user aesthetic preference.
- Modern:Clean lines, handle-less cabinetry, and integrated appliance housing with high-gloss or matte laminate surfaces. Premium Bangalore residential projects specify modern finishes for model unit differentiation, with laminate importers backward-integrating into local pressing operations.
- Traditional:Ornate detailing, carved wood elements, and classic hardware profiles. Kerala and Tamil Nadu independent housing retains demand for carpenter-fabricated traditional kitchens resistant to modular conversion.
- Rustic:Distressed wood textures and farmhouse-inspired configurations.
- Contemporary:Transitional aesthetics blending modern functionality with warmer material palettes.
Modern style leads specification value; contemporary blends gain share fastest among upgrade-minded nuclear families.
End User:
Margin structure separates high-volume residential from durability-premium commercial and hospitality applications.
- Residential:Individual homeowners and apartment buyers in nuclear family configurations across Mumbai, Bangalore, and Delhi NCR urban corridors. RERA-registered projects increasingly mandate pre-approved modular vendor lists, consolidating specification authority with developers rather than end consumers.
- Commercial:Office pantries, institutional cafeterias, and food service back-of-house operations. Cloud kitchen operators in Bangalore and Mumbai specify durability-rated modular systems with accelerated replacement cycles.
- Hospitality:Hotels, resorts, and serviced apartments requiring fire-rated and heavy-use certified installations.
- Retail:Food retail backrooms and demonstration kitchen showrooms.
Residential absorbs volume leadership; hospitality commands the steepest per-unit margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium apartment developers and nuclear family buyers concentrate in Maharashtra, Karnataka, and Delhi NCR, while tier-2 cities present untapped conversion potential for certified modular suppliers.
Maharashtra
Mumbai's luxury residential towers and Pune's IT corridor drive specification-grade kitchen demand from nuclear families seeking space-efficient storage. BIS IS:710 certification mandates for marine-grade plywood filter supplier eligibility in RERA-registered projects. Thane and Navi Mumbai industrial clusters host panel pressing facilities that serve builder-direct procurement contracts.
Karnataka
Bangalore's premium housing developments and Whitefield tech campus expansions accelerate modern-style modular adoption among affluent professionals. State-level building codes align with central BIS standards to enforce moisture-resistance specifications in delivered apartment fit-outs. The Electronics City corridor concentrates laminate pressing operations backward-integrated from import-dependent supply chains.
Delhi NCR
Gurgaon and Noida high-rise residential complexes standardize modular vendor lists, consolidating procurement authority with developers rather than end consumers. Ministry of Environment emission norms for formaldehyde in composite boards pressure local manufacturers toward E1-grade adhesive reformulation. Faridabad industrial zones anchor metal-accented cabinetry production for contemporary-style apartment specifications.
Gujarat
Ahmedabad and Surat independent housing markets retain carpenter-fabricated kitchen demand resistant to modular conversion in traditional-style segments. BIS certification requirements for plywood quality create compliance barriers for unorganized sector suppliers serving price-sensitive buyers. Vadodara furniture manufacturing clusters experiment with particle board substitution for mid-income apartment projects.
Tamil Nadu
Chennai's coastal humidity conditions necessitate moisture-resistant material specifications that elevate certified supplier advantage over local fabricators. CDSCO-aligned quality benchmarks for imported hardware components affect premium fitting system availability in luxury residential developments. Sriperumbudur industrial corridor hosts emerging panel production capacity targeting Bangalore spillover demand.
India Kitchen Furniture Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between scale-driven manufacturers and precision-focused component suppliers. Consolidation pressure concentrates among builder-direct procurement channels while unorganized carpentry retains price-sensitive residential volume. Three archetypes dominate: pan-India distribution networks, premium hardware importers, and mid-market laminate specialists. Competitive moves center on backward integration into panel pressing and certification laboratory investments to secure BIS eligibility.
Among domestic distribution-anchored players, Godrej Interio occupies a position exemplifying scale-driven modular supply, while Johnson Kitchens represents mid-market laminate specialization. Hafele anchors the premium hardware tier, sitting within the imported-equivalent specification segment that differentiates through fitting system quality. These three companies illustrate how supplier archetypes map to buyer tiers: certified volume, price-accessible finish, and precision-engineered componentry.
| Leading Market Players |
|---|
| Sleek |
| Johnson Kitchens |
| Hafele |
| Haecker |
| Kohler |
| Godrej Interio |
| Ebco |
| Evok |
| Spacewood |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-JNPT freight corridor's container haulage costs transmit directly into landed plywood prices for Bangalore and Delhi NCR fabricators, amplifying the pricing power of Kerala and Gujarat panel producers while compressing margins for distant modular assemblers competing against certified suppliers.
Pricing Analysis
Cost-plus contracts with BIS laboratory testing indexation dominate builder-direct procurement in RERA-registered Maharashtra and Karnataka projects. Price differentiation rests on IS:710 marine-grade certification tier and laminate finish grade, with premium acrylic surfaces commanding substantial spreads over standard melamine. Cost compression in the mid-market laminate tier is intensifying because particle board substitution expands supply faster than certified installation capacity. Price sensitivity concentrates among first-time apartment buyers in Pune and Thane, while Delhi NCR luxury developers exhibit minimal elasticity for imported-equivalent hardware specifications.
Supply Chain Analysis
Upstream feedstock for moisture-resistant plywood draws from Kerala rubberwood plantations and Gujarat timber processing clusters, with adhesive chemicals sourced from Maharashtra petrochemical complexes. Engineered wood panels, decorative laminates, and precision hardware constitute the critical component trinity. Single-source vulnerability concentrates in monsoon-dependent Kerala plywood output, where logistics disruptions cascade through tier-1 assembler inventories. Distribution runs through builder-direct procurement channels in Mumbai and Bangalore, supplemented by franchise retail networks penetrating tier-2 urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to residential construction permit issuance in Maharashtra and Karnataka, where RERA-registered project completions drive replacement demand for certified modular installations.
For Market Incumbents: Harden certification laboratory investments to preempt BIS IS:303 amendment cycles that threaten mid-tier manufacturer eligibility. Deepen captive supply of E1-grade adhesive formulations to neutralize Ministry of Environment compliance cost pressure. Consolidate builder-direct procurement relationships in Gurgaon and Whitefield before laminate importers complete backward integration into local pressing operations.
For New Entrants and Emerging Players: Establish a beachhead in tier-2 Karnataka markets such as Mysore and Mangalore where certified installation technician scarcity has slowed incumbent rollout velocity. Target mid-income apartment segments in Ahmedabad and Surat where carpenter-fabricated alternatives retain share against weak modular penetration. Pursue franchise partnerships with regional distributors rather than capital-intensive manufacturing scale-up.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates seeking to divest non-core kitchen furniture divisions lacking pan-India distribution scale. Long-term viability favors vertically integrated panel producers with captive BIS testing infrastructure and established builder-direct relationships. Monitor Kerala plywood production volumes as an inflection indicator for upstream cost pressure transmission.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Pressing | Captures laminate margin and secures BIS certification control for Maharashtra assemblers. |
| Certified Installation Technician Training Programs | Addresses skill scarcity constraining tier-2 expansion in Karnataka and Gujarat markets. |
| Builder-Direct Procurement Partnerships | Locks specification authority in RERA-registered Delhi NCR and Mumbai residential towers. |
| E0 Adhesive Formulation Investment | Preempts Ministry of Environment emission norm tightening for composite board eligibility. |
| Commercial Hospitality Vertical Development | Accesses durability-premium margins in Bangalore cloud kitchen and hotel retrofit segments. |
Research Methodology
The analysis maps modular cabinet, shelf, and surface sub-sectors, each validated through manufacturing plant managers, residential developer procurement heads, laminate distribution channel partners, and certified installation technicians. Primary interviews combined with secondary validation against BIS certification registries, RERA project disclosure databases, Ministry of Environment emission compliance filings, and plywood import customs records. Bottom-up shipment data triangulated against top-down residential construction permit aggregates.
Assumptions held fixed include BIS IS:710 certification permanence and PLI scheme continuation for wood processing, while variables tested encompass monsoon severity impacts on Kerala logistics and tier-2 technician training velocity. Segmentation dimensions modeled span product type, material grade tier, style specification, end-user category, and regional urban cluster across the projection horizon. CAGRs derived from fitted growth curves applied to base-year shipment volumes, with nuclear family formation rates and premium housing inventory absorption as kitchen furniture-specific demand drivers.
Sensitivities concentrate around BIS amendment timing for formaldehyde emission standards and monsoon disruption severity affecting plywood supply concentration. Forecasts reflect documented assumptions regarding regulatory stability and residential construction cycle continuity. Cross-checking against state-level RERA project registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
India Modular Kitchen Market