
 US Buy Now Pay Later Services Market | 2026-2036
US Buy Now Pay Later Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Buy Now Pay Later Services Market Insights
Fintech lending capacity in the United States is repositioning around embedded checkout finance. Affirm Holdings Inc. dominates large-ticket merchant partnerships with airlines and electronics retailers. Klarna Bank AB leverages its AI-driven shopping app to sustain consumer engagement beyond pure transaction financing. Afterpay Ltd anchors its position through retail partnerships with fashion and beauty verticals.
Buy Now Pay Later Services constitute short-term consumer credit products that split purchase amounts into equal installments, typically bi-weekly or monthly, with automated repayment via linked bank accounts or debit cards and real-time risk assessment through proprietary algorithms. These instruments serve primarily to reduce purchase friction at digital points of sale and expand merchant conversion rates among credit-averse or underbanked shoppers. Point of Sale Financing leads transaction volume due to its direct integration with merchant checkout flows, while Pay in Installments captures the fastest expansion as travel and healthcare providers adopt the model. Mobile Apps concentrate the highest-margin user acquisition channel, whereas Banking Solutions face margin compression from regulatory capital requirements.
The Consumer Financial Protection Bureau supervises BNPL providers under emerging truth-in-lending standards, while state usury laws in New York and California cap effective interest rates on certain credit products. The Federal Trade Commission monitors marketing claims for deceptive installment advertising. Stakeholders must track pending state-level licensing regimes and decide whether to build in-house compliance infrastructure or absorb third-party origination costs.
Market Dynamics
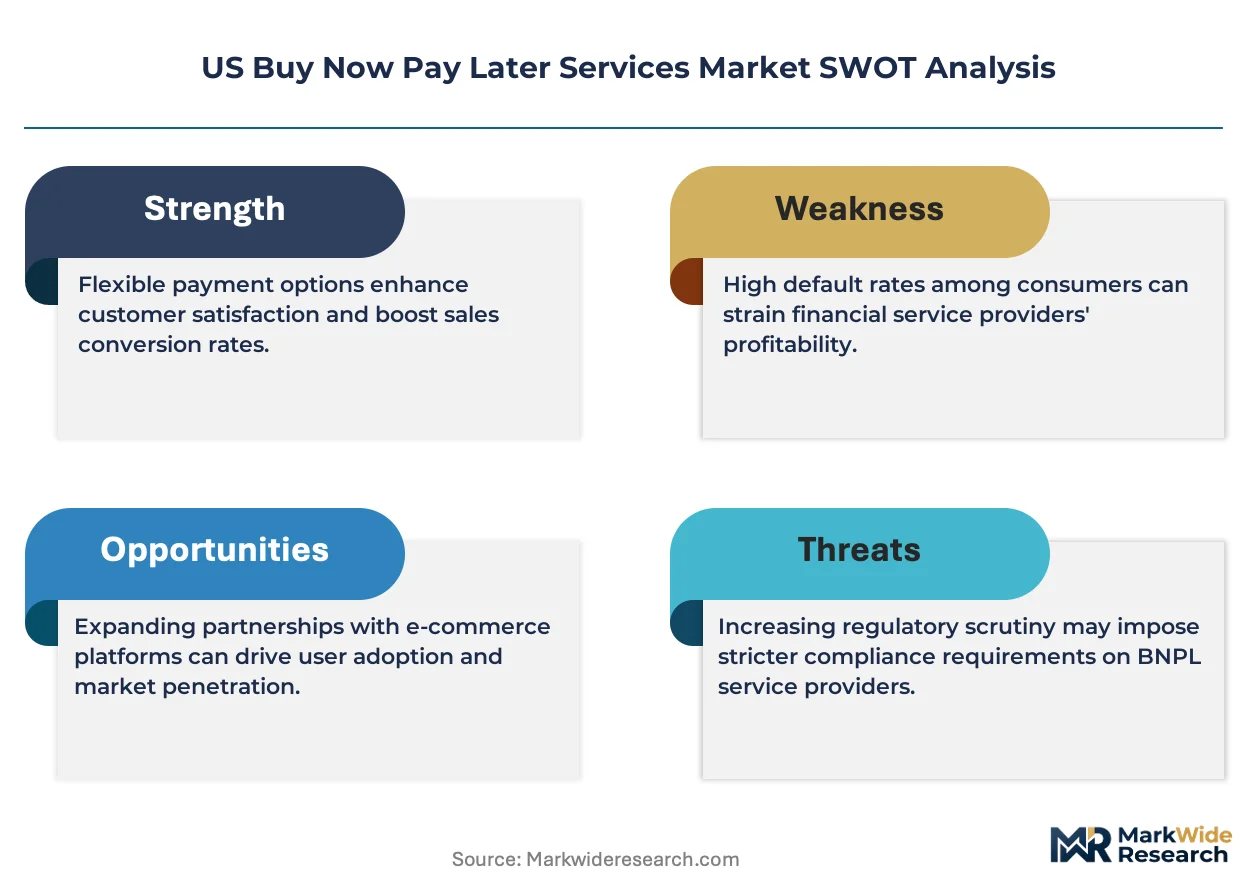
The Consumer Financial Protection Bureau's supervisory oversight is compressing underwriting margins while embedded checkout finance is electrifying merchant adoption across travel and healthcare verticals.
Growth Catalysts
- Gen Z Digital Native Demand:California and Texas metro corridors concentrate credit-averse shoppers seeking frictionless point-of-sale alternatives to traditional revolving credit.
- Merchant Conversion Optimization:Airlines and electronics retailers deploy automated installment splits to reduce cart abandonment at high-consideration purchase moments.
- CFPB Truth-in-Lending Standardization:Federal disclosure requirements are legitimizing BNPL products for risk-averse financial institutions seeking compliant partnership structures.
Market Restraints
- State Usury Rate Caps:New York and California statutory interest limits constrain revenue models on longer-duration installment products.
- Banking Capital Requirements:Regulatory reserve mandates compress margins for providers offering depository-linked repayment infrastructure.
- Debit Card Substitution Risk:Linked bank account automation faces displacement from real-time payment rails reducing installment necessity.
Strategic Opportunities
- Healthcare Procedure Financing:Elective medical and dental providers represent underpenetrated merchant categories for bi-weekly repayment structures.
- AI-Driven Risk Scoring Convergence:Machine learning algorithms combined with alternative data sources enable subprime borrower approval expansion.
- Payroll-Integrated Repayment:Employer benefit platforms offer direct wage deduction channels bypassing traditional banking friction.
Industry Challenges
- Compliance Infrastructure Buildout:Multi-state licensing regimes demand dedicated legal and risk management functions without scale economies.
- Legacy Core Banking Integration:Real-time repayment synchronization with established financial institution systems requires costly API development and maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Buy Now Pay Later Services Market |
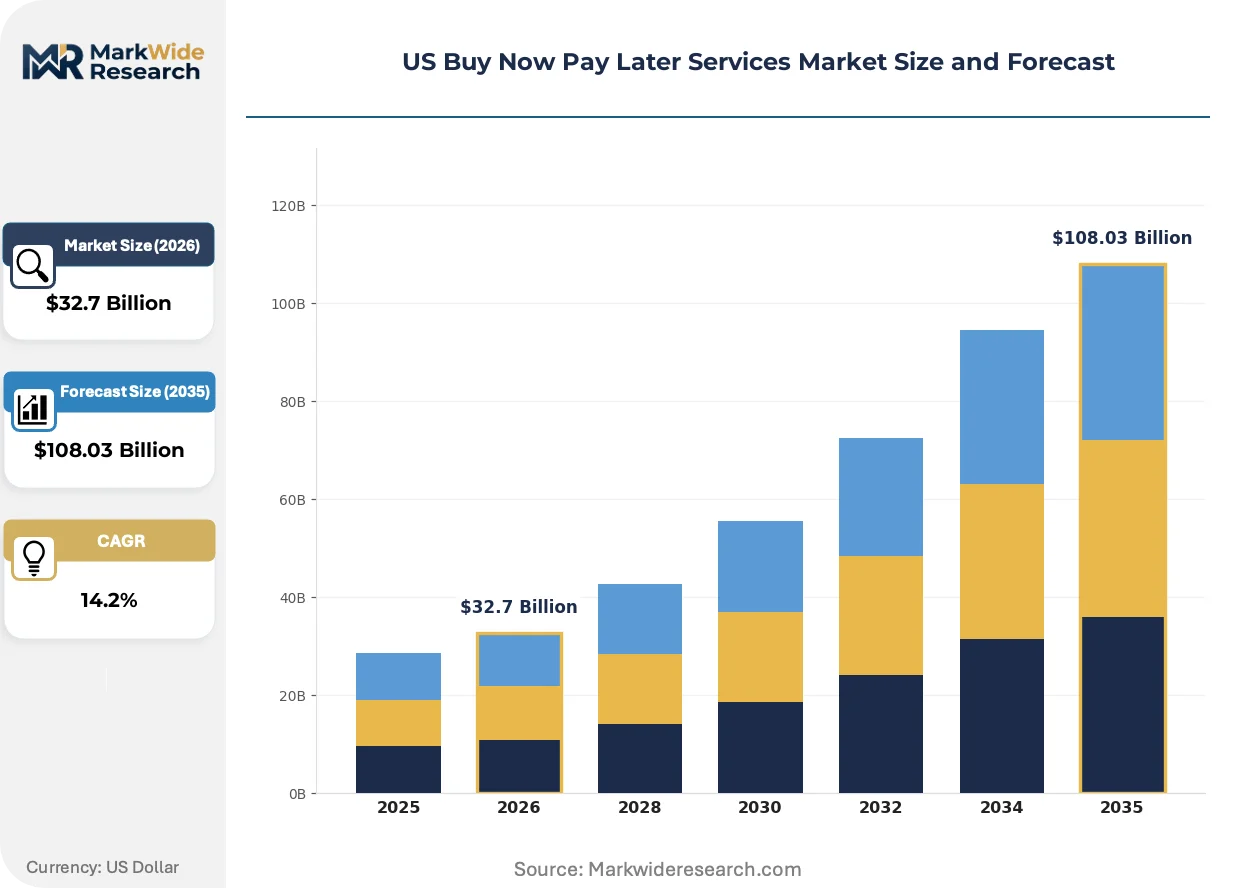
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $108.03 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Point of Sale Financing, Pay in Installments, Deferred Payment, Interest-Free Credit Customer Type: Millennials, Gen Z, Middle-Income Consumers, Online Shoppers Platform: Mobile Apps, E-commerce Integrations, Banking Solutions, Retail Partnerships Repayment Model: Fixed Schedule, Flexible Payments, Bi-weekly Payments, Late Fees |
| Companies Covered | PayPal Holdings Inc., Afterpay Ltd, Affirm Holdings Inc., Klarna Bank AB, Zip Co Ltd, Sezzle Inc., Bread Financial Holdings Inc., Splitit Payments Ltd, Katapult Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Buy Now Pay Later Services Market Trends and Innovations
Embedded finance architecture is collapsing the distinction between shopping and borrowing, while regulatory clarity and shifting consumer credit preferences restructure competitive positioning.
Proprietary algorithmic underwriting is electrifying real-time risk assessment at digital checkout points. Travel and healthcare merchants are adopting these systems fastest, compressing approval decisions from days to milliseconds. The technology is electrifying merchant willingness to offer interest-free installments on high-ticket purchases previously financed through traditional credit cards.
The Consumer Financial Protection Bureau's emerging truth-in-lending standards are mandating standardized fee disclosures across all installment products. This regulatory development forces providers to restructure revenue models away from late fee dependency toward merchant interchange economics. Point-of-sale financing segments face the steepest compliance adaptation costs as they retrofit legacy disclosure flows.
Credit-averse consumption patterns are fragmenting demand away from revolving credit products toward fixed-obligation installment structures. Younger demographics in suburban Texas and California markets are abandoning credit card applications entirely, substituting debit-linked pay-in-four products. This behavioral pivot concentrates highest-margin acquisition through mobile app channels rather than bank partnership distribution.
US Buy Now Pay Later Services Market Segmentation
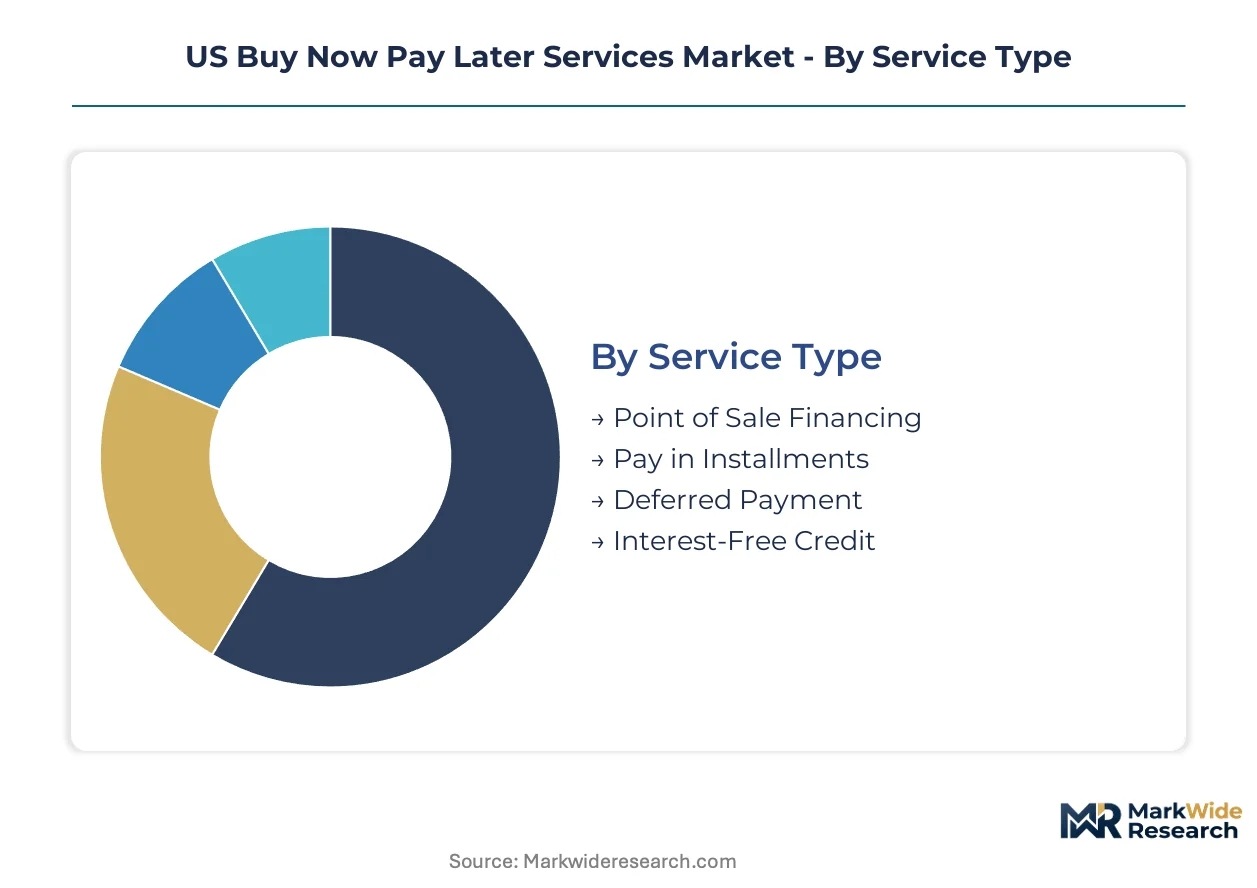
BNPL market segmentation reveals distinct profit pools across service architectures and user acquisition channels. Each dimension carries divergent regulatory exposure and unit economics that reshape competitive positioning.
Service Type:
Merchant checkout integration depth determines borrower acquisition cost and default risk exposure.
- Point of Sale Financing:Embedded checkout splits for high-ticket purchases with real-time merchant-funded subsidies. Airlines and electronics retailers concentrate demand here as cart abandonment reduction justifies interchange economics.
- Pay in Installments:Bi-weekly or monthly fixed obligations with automated debit pulls. Travel and healthcare providers are adopting this fastest as patient and passenger financing normalizes beyond traditional credit cards.
- Deferred Payment:Single future-due date structures common in seasonal retail cycles.
- Interest-Free Credit:Merchant-subsidized promotional periods with back-end fee conversion.
Point of Sale Financing leads on scale; Pay in Installments leads on momentum.
Customer Type:
Credit preference fragmentation across generational cohorts restructures underwriting algorithm design.
- Gen Z:Digital-native borrowers rejecting revolving credit entirely in favor of fixed-obligation transparency. California and Texas suburban corridors concentrate this cohort's debit-linked adoption.
- Millennials:Credit-score-conscious users seeking installment alternatives to preserve revolving capacity for emergencies.
- Middle-Income Consumers:Budget-constrained households using BNPL for predictable cash flow smoothing.
- Online Shoppers:Transaction-agnostic users activated purely through checkout friction reduction.
Gen Z dominates acquisition velocity; Millennials sustain higher per-user revenue.
Platform:
Distribution channel economics separate high-margin proprietary engagement from thin-margin banking partnerships.
- Mobile Apps:Direct-to-consumer interfaces with shopping discovery layers and highest lifetime value per install.
- E-commerce Integrations:Merchant-embedded checkout widgets converting browser sessions through one-click enrollment.
- Banking Solutions:White-labeled offerings through established depository institutions facing regulatory capital compression.
- Retail Partnerships:Co-branded programs with fashion and beauty verticals anchoring seasonal campaign cycles.
Mobile Apps command margin leadership; E-commerce Integrations drive transaction volume.
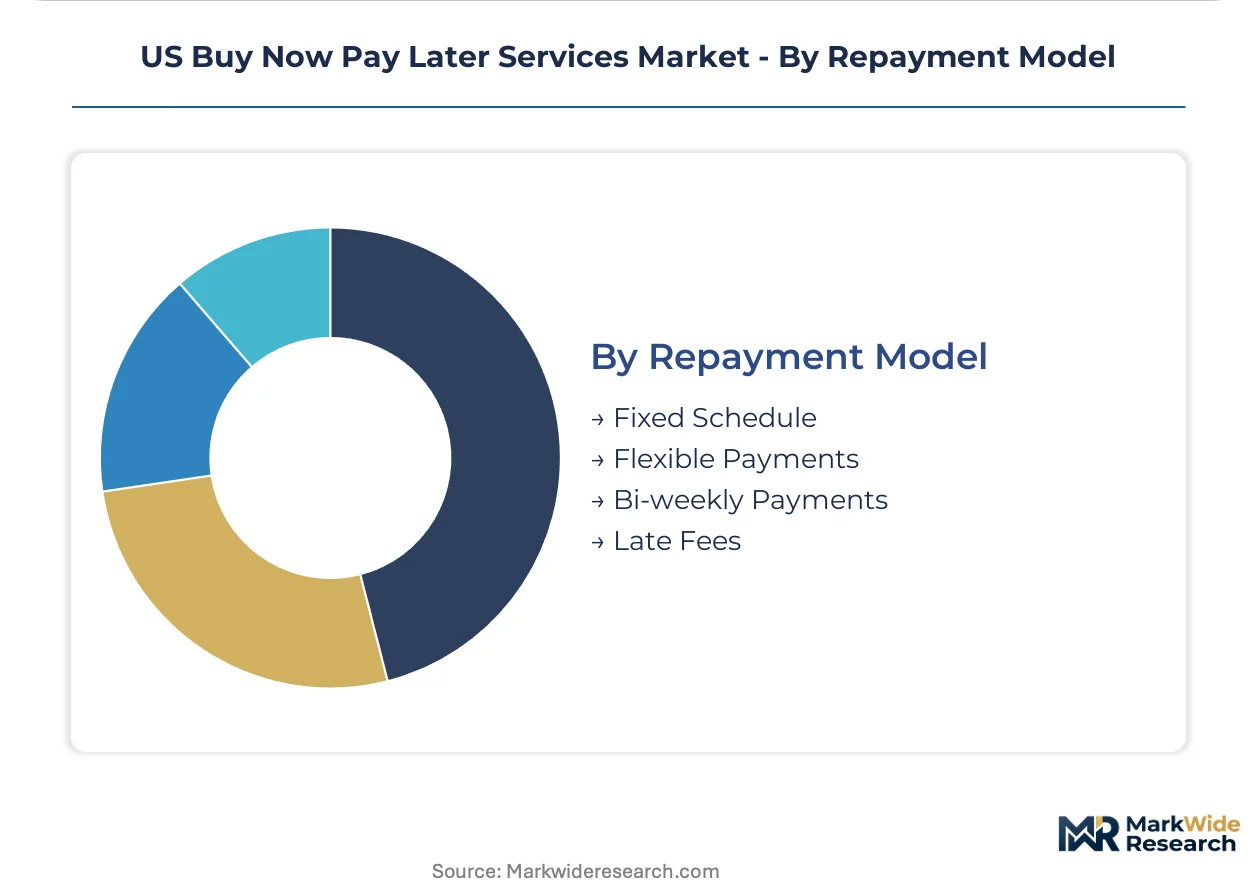
Repayment Model:
Collection infrastructure design determines operational cost and CFPB compliance exposure.
- Fixed Schedule:Predetermined equal installments with automated bank account debits reducing servicing overhead.
- Flexible Payments:User-adjusted dates and amounts requiring higher touch servicing and elevated default monitoring.
- Bi-weekly Payments:Paycheck-synchronized pulls aligning with payroll cycles for subprime borrower segments.
- Late Fees:Penalty revenue streams facing truth-in-lending disclosure mandates and state usury scrutiny.
Fixed Schedule dominates operational efficiency; Bi-weekly Payments expand fastest among underbanked populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between state usury regimes and federal disclosure standards is redistributing BNPL operational density toward jurisdictions with clearer compliance cost structures. Providers cluster where state-level licensing burdens remain manageable and consumer credit demand runs highest.
California
Los Angeles and San Francisco Bay Area corridors concentrate Gen Z debit-linked adoption for electronics and fashion purchases. The state's Department of Financial Protection and Innovation enforces stringent lending license requirements that elevate compliance overhead for non-bank providers. San Diego's healthcare provider networks are piloting installment financing for elective dental and cosmetic procedures.
Texas
Dallas-Fort Worth and Houston suburban markets sustain the fastest per-capita BNPL transaction growth among credit-averse Millennials. State usury exemptions for commercial transactions create regulatory breathing room for merchant-subsidized installment products. Austin's fintech employer density supports payroll-integrated repayment pilot programs with regional benefits platforms.
New York
New York City metro anchors merchant partnership origination for luxury retail and travel verticals. The state's statutory interest rate caps constrain longer-duration installment revenue models, pushing providers toward pay-in-four structures. Buffalo and Rochester regional banks are white-labeling BNPL infrastructure through third-party platform partnerships.
Florida
Miami-Dade and Orlando tourism corridors drive hospitality and experience-based installment adoption among seasonal service workers. The state's lighter-touch financial services regulatory framework attracts provider headquarters relocations from higher-burden jurisdictions. Tampa's healthcare systems are deploying patient financing for high-deductible plan out-of-pocket costs.
Illinois
Chicago's airline and corporate travel hub status concentrates B2B travel management platform integrations. The state's Consumer Installment Loan Act licensing requirements filter out thinly capitalized entrants. Peoria and Springfield regional healthcare networks are adopting dental and vision procedure financing through specialty BNPL vendors.
US Buy Now Pay Later Services Market Competitive Landscape
US-based fintech platforms anchor the merchant-integrated tier; European banking specialists hold the direct-to-consumer engagement layer. The market structures around three concentration nodes: large-ticket electronics and travel partnerships, fashion and beauty retail embedded checkout, and subprime-focused lease-to-own verticals. Consolidation pressure runs through merchant exclusivity battles and regulatory compliance scale economies. Technology licensing partnerships and white-label banking infrastructure deployments constitute the dominant competitive moves.
Within the merchant-integrated tier, Affirm Holdings Inc. and Afterpay Ltd exemplify divergent strategic positioning—one toward high-consideration purchase verticals, the other toward discretionary retail frequency. Klarna Bank AB occupies a position bridging direct consumer app engagement with embedded checkout presence. These three entities collectively represent the competitive archetypes now defining partnership terms across airline, electronics, and fashion merchant categories.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Afterpay Ltd |
| Affirm Holdings Inc. |
| Klarna Bank AB |
| Zip Co Ltd |
| Sezzle Inc. |
| Bread Financial Holdings Inc. |
| Splitit Payments Ltd |
| Katapult Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
The Consumer Financial Protection Bureau's truth-in-lending disclosure mandates gate access to premium merchant interchange rates, forcing providers to absorb compliance infrastructure costs or surrender margin to third-party originators. This regulatory filter concentrates pricing power among scaled platforms that can amortize multi-state licensing overhead across high-volume transaction flows.
Pricing Analysis
Merchant-funded subsidies anchor the dominant pricing structure, with airlines and electronics retailers absorbing interchange economics to reduce cart abandonment. Price differentiation rests on underwriting sophistication and real-time risk assessment speed, separating algorithmic-native platforms from legacy bank partnerships. Cost compression in longer-duration installment products is intensifying because New York and California usury caps constrain back-end fee conversion. Gen Z debit-linked users exhibit highest price sensitivity, while travel and healthcare merchants show least sensitivity due to conversion-optimization priorities.
Supply Chain Analysis
Returns and delinquency flows create reverse-logistics complexity as providers manage automated bank account debits, manual collection escalations, and third-party servicing handoffs. Technology infrastructure concentrates in the United States and Ireland, with cloud computing dependencies drawing from Amazon Web Services, Microsoft Azure, and Google Cloud platforms. Single-source vulnerability sits with proprietary credit decisioning engines trained on limited alternative data histories. Distribution runs through direct API integrations with merchant checkout systems, bypassing traditional banking branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on automation-driven servicing cost reduction and the shift toward merchant-subsidized interest-free products that command higher interchange capture.
For Market Incumbents: Extend algorithmic underwriting advantage into healthcare and travel verticals where patient and passenger financing normalizes fastest. Consolidate merchant exclusivity through dedicated compliance infrastructure that thinly capitalized entrants cannot replicate. Defensive positioning requires backward integration into payroll-linked repayment rails before employer benefit platforms lock in channel control. For New Entrants and Emerging Players: AI-driven risk scoring convergence offers entry wedge into subprime borrower segments underserved by legacy FICO-dependent models. White-space targets concentrate in elective medical and dental procedure financing across Texas and Florida metro corridors. Go-to-market execution should anchor through specialty healthcare vendor partnerships rather than competing for saturated retail checkout slots. For Investors and Strategic Acquirers: Valuations sit cheapest among regional banking partnerships seeking white-labeled BNPL infrastructure without in-house compliance buildout. Long-term viability favors platforms with direct consumer app engagement sustaining lifetime value beyond single transaction financing. Monitor CFPB rulemaking velocity as inflection indicator for regulatory capital requirement expansion that would compress thin-margin banking solution providers.| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Vertical Expansion | Elective dental and cosmetic procedure financing unlocks underpenetrated merchant categories in California and Texas. |
| Payroll Integration Partnership | Employer benefit platform alliances bypass traditional banking friction for subprime borrower segments. |
| AI Risk Model Development | Machine learning algorithms trained on alternative data sources expand approval rates for credit-averse Gen Z applicants. |
| Multi-State Licensing Buildout | Dedicated compliance infrastructure creates defensive moats against thinly capitalized entrants facing regulatory scale economies. |
| Merchant Exclusivity Lock-In | Airline and electronics retailer partnerships concentrate transaction volume and justify interchange economics. |
Research Methodology
Direct dialogue with BNPL platform risk officers, merchant partnership executives, CFPB policy specialists, and healthcare provider finance directors grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings, Consumer Financial Protection Bureau supervisory reports, state financial regulator licensing databases, and merchant adoption surveys. Bottom-up transaction volume estimates triangulated against top-down consumer credit flow data from the Federal Reserve.
Segment-level projections across service type, customer cohort, platform architecture, and repayment model dimensions fed into consolidated market sizing. CAGRs derived from regression analysis against demographic adoption curves, merchant penetration rates, and regulatory implementation timelines. Industry-specific inputs included Gen Z debit adoption velocity, healthcare provider financing pilot expansion, and state-level licensing cost trajectories.
The model holds under stable regulatory implementation pace; deviation in CFPB capital requirement mandates or state usury enforcement intensity would shift competitive positioning. Forecasts embed assumptions around merchant subsidy sustainability and alternative data availability for underwriting. Practitioners should monitor federal preemption debates and real-time payment rail adoption for early signals of installment product displacement risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Biometric Payment Market
Payments
Malta POS Terminal Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Indonesia Prepaid Cards Market
Payments
Japan POS Terminals Market
Payments
APAC Mobile Payments Market
Payments
Italy Payments Market
Payments
Cloud Billing Market
Payments
Hong Kong Credit Cards Market
Payments
North America Real Time Payment Market
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
Egypt Mobile Payments Market
Payments
Online Payment Gateway Market
Payments
P2P Payment Market
Payments
Mobile Payment Security Software Market
Payments
E-Commerce Payments Market