
 Portugal POS Terminals Market | 2026-2036
Portugal POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal POS Terminals Market Analytics
Software subscription revenue is rewriting margin distribution across the Portugal POS Terminals Market, pulling value from one-time hardware sales toward recurring platform fees. Ingenico Group (Worldline) leverages its European service infrastructure to sustain maintenance contracts across Iberian retail chains. SIBS Pay anchors domestic transaction processing through its proprietary Multibanco network integration. Verifone competes on terminal-agnostic software layers that reduce merchant switching costs.
A POS terminal constitutes an electronic device combining secure payment card readers, encryption modules, and connectivity interfaces to process retail transactions through integrated merchant acquiring networks. These systems typically incorporate PCI-DSS certified hardware, EMV chip compatibility, and NFC antennas to authenticate payment credentials while transmitting encrypted data to banking networks. Mobile terminals now lead product type dynamics as Portuguese food service operators prioritize tableside payment flexibility, while smart terminals represent the fastest-expanding technology segment where Android-based application platforms enable inventory and loyalty program integration. Contactless technology dominates transaction volume growth following pandemic-era behavioral shifts among Portuguese consumers.
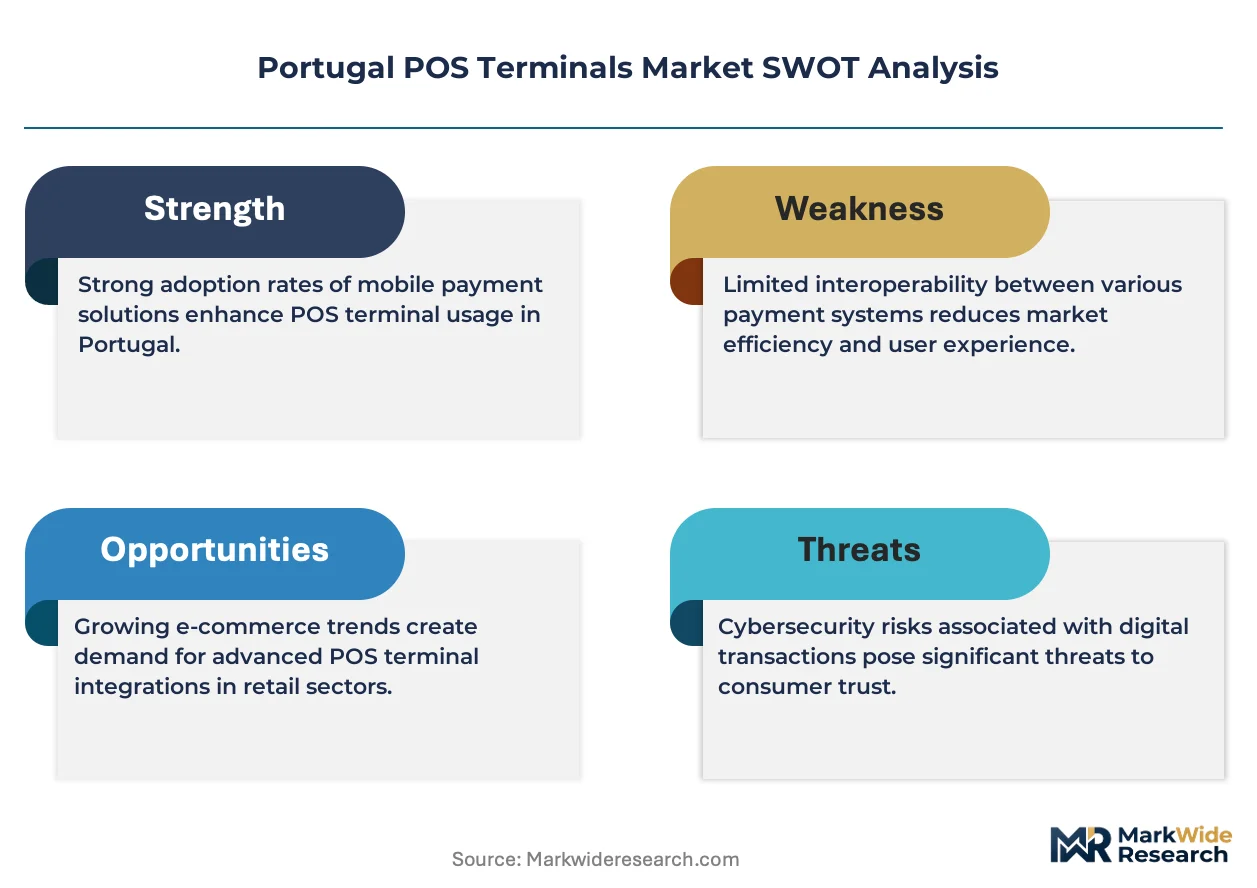
Banco de Portugal enforces payment system oversight that mandates terminal certification for domestic network compatibility, directly shaping hardware vendor market access requirements. The country's national data protection authority applies GDPR-derived standards to transaction data handling, compelling terminal manufacturers to embed privacy-by-design architectures. Portuguese central bank guidelines on instant payment infrastructure will determine whether stakeholders prioritize SEPA-compliant terminal upgrades or await next-generation protocol standardization before committing capital.
Market Dynamics
Restaurant operators across Greater Lisbon are compressing terminal replacement cycles from seven-year intervals to four-year cycles, driven by Banco de Portugal's evolving certification requirements for contactless and instant payment protocols.
Growth Catalysts
- Multibanco network integration mandates:SIBS Pay's proprietary infrastructure requires certified terminal compatibility, compelling merchants to upgrade hardware to maintain transaction access across Portugal's dominant domestic network.
- Tableside payment flexibility:Lisbon and Porto food service operators are deploying mobile terminals to reduce checkout friction during peak tourist dining hours.
- GDPR-derived data handling standards:Portugal's national data protection authority mandates privacy-by-design architectures, pushing vendors toward embedded encryption modules that command premium positioning.
Market Restraints
- EMV chip certification timelines:Banco de Portugal's terminal approval processes extend hardware launch windows by 8-14 months, delaying vendor revenue recognition.
- Semiconductor supply concentration:NFC antenna and secure element sourcing concentrates in East Asian foundries, exposing Portuguese distributors to logistics volatility.
- Smartphone-based soft POS substitution:Android tap-to-pay applications threaten dedicated terminal volumes among micro-merchants with sub-€50,000 annual card turnover.
Strategic Opportunities
- Algarve tourism corridor penetration:Seasonal hospitality operators in Lagos and Faro remain underpenetrated by integrated inventory-payment systems.
- Android application platform convergence:Smart terminals combining payment processing with loyalty program management open cross-sell revenue streams.
- SEPA instant payment infrastructure alignment:Portuguese central bank guidelines on real-time settlement create upgrade windows for SEPA-compliant terminal deployments.
Industry Challenges
- PCI-DSS certification backlog:Hardware vendors face extended laboratory queue times for encryption module validation.
- Legacy terminal integration complexity:Merchant acquiring systems in Porto retail chains require custom middleware to bridge 2015-era terminal estates with cloud-based reconciliation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal POS Terminals Market |
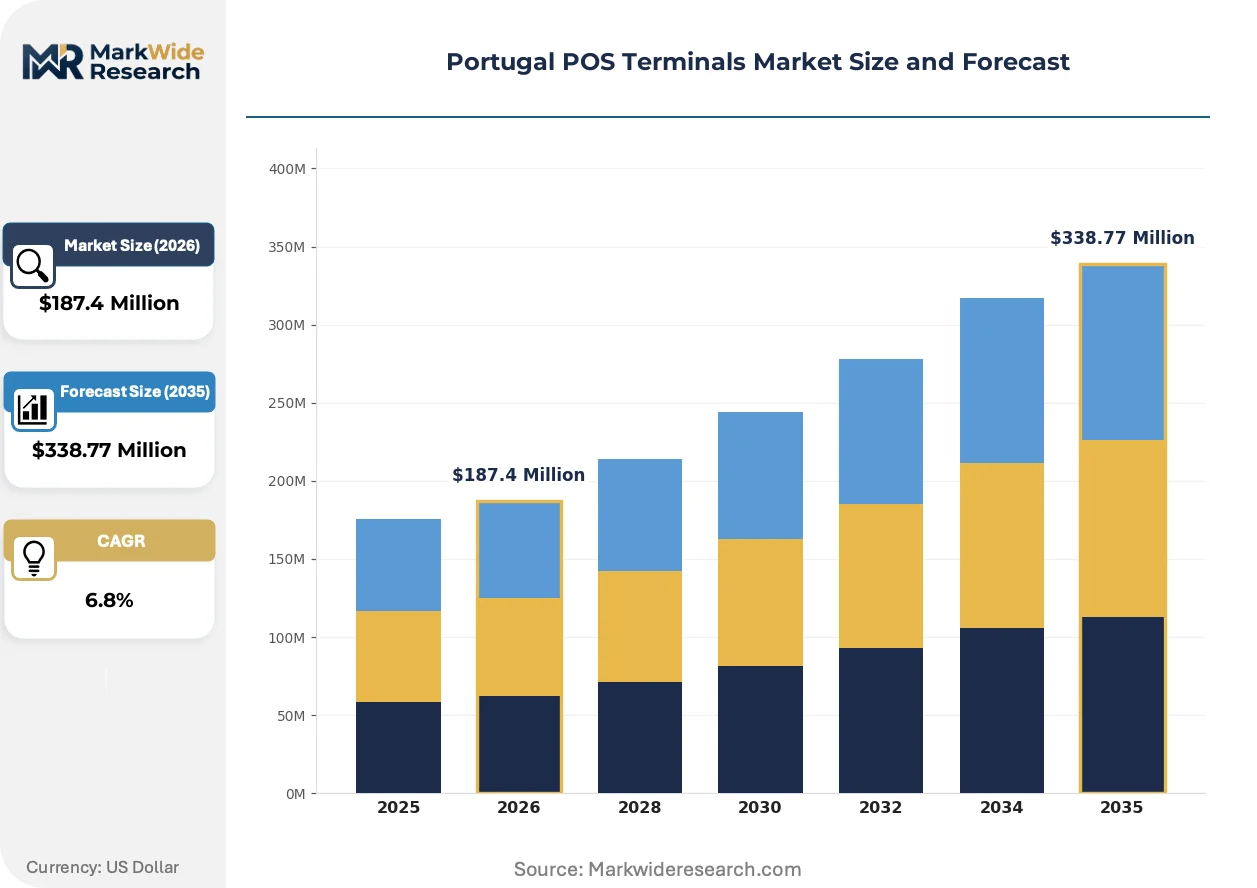
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Smart Terminals, Wireless Terminals Technology: Contactless, Chip & PIN, Magnetic Stripe, QR Code End User: Retail Stores, Restaurants, Hospitality, E-commerce Installation: On-site, Remote, Integrated, Standalone |
| Companies Covered | NCR Corporation, Mastercard Inc, Ingenico Group (Worldline), myPOS World Ltd, Sumup Inc, SIBS Pay, NEC Corporation, Vectron System AG, Verifone Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal POS Terminals Market Evolving Landscape
Software-defined functionality is collapsing the boundary between payment hardware and merchant management platforms, redirecting vendor investment from physical device engineering toward application ecosystem development.
Android-based smart terminal architectures are collapsing the traditional separation between payment acceptance and business operations software. Porto-based retail chains are deploying these systems to unify inventory tracking with transaction processing. The convergence is collapsing standalone POS software markets into bundled hardware-subscription offerings.
Banco de Portugal's oversight of instant payment infrastructure is accelerating terminal refresh timelines. The central bank's protocol roadmaps are compelling merchants to pre-position hardware capable of SEPA instant credit transfer acceptance. Greater Lisbon hospitality operators are prioritizing certified terminals to avoid network exclusion.
Merchant acquiring relationships are fragmenting as Portuguese food service operators unbundle hardware procurement from payment processing contracts. Independent software vendors are inserting themselves between terminal manufacturers and end users. This disintermediation concentrates in the Lisbon metropolitan corridor where operator sophistication and alternative vendor access intersect.
Portugal POS Terminals Market Segmentation
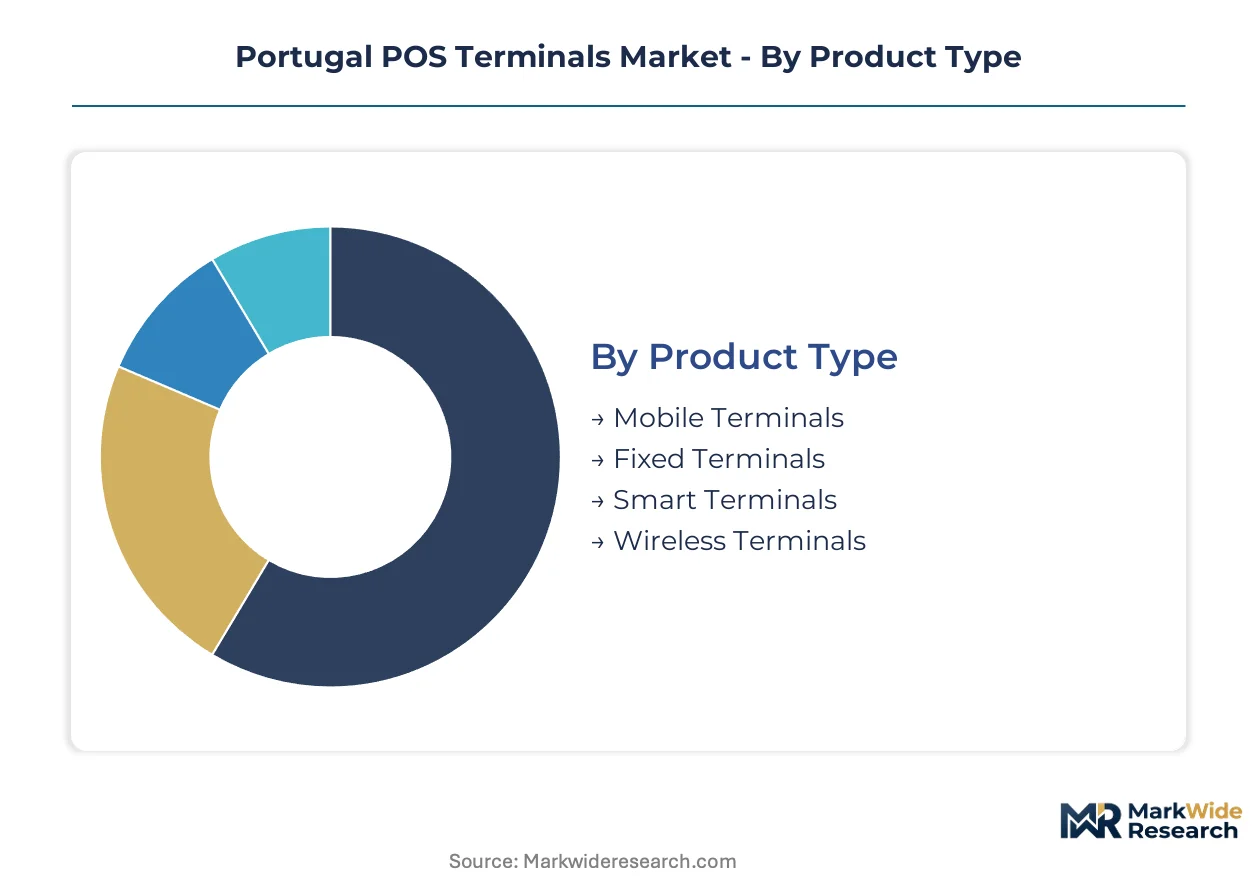
Segmentation in the Portugal POS Terminals Market reveals how hardware specifications, payment protocols, and deployment models align with distinct operational requirements across Portuguese commerce. Each dimension carries different service intensity profiles that reshape vendor profitability and customer lifetime value calculations.
Product Type:
After-sales service intensity varies sharply across terminal form factors, with mobile and smart terminals demanding firmware update cadences that fixed units rarely require.
- Mobile Terminals:Battery-powered units with integrated receipt printers and 4G/WiFi connectivity enable tableside payment acceptance. Lisbon restaurant operators deploy these devices during peak tourist dining hours to reduce checkout friction and improve table turnover rates.
- Smart Terminals:Android-based platforms support third-party applications for inventory management, loyalty programs, and staff scheduling. Porto retail chains prioritize these systems to consolidate operational software onto payment hardware, collapsing separate POS software subscriptions into bundled offerings.
- Fixed Terminals:Countertop units with Ethernet connectivity serve high-volume retail environments where transaction speed outweighs mobility requirements.
- Wireless Terminals:WiFi-dependent devices without cellular backup suit indoor retail footprints with reliable network infrastructure.
Fixed terminals hold the largest share; momentum sits with smart terminals.
Technology:
Certification complexity and hardware cost tiers separate payment authentication methods, with contactless commanding premium positioning due to Banco de Portugal's evolving protocol mandates.
- Contactless:NFC-enabled terminals supporting tap-to-pay cards and mobile wallets dominate transaction volume growth. Portuguese consumer behavior shifted permanently during pandemic-era hygiene concerns, and Banco de Portugal's instant payment infrastructure roadmap accelerates merchant upgrade timelines to maintain network access.
- Chip & PIN:EMV-compliant terminals with physical card insertion and PIN entry remain mandatory for high-value transactions. Retailers across Greater Lisbon maintain these capabilities alongside contactless to serve international tourists carrying non-NFC cards.
- Magnetic Stripe:Legacy swipe functionality persists for compatibility with foreign-issued cards from markets with slower EMV migration.
- QR Code:Camera-based payment acceptance enables integration with digital wallet applications and SEPA instant credit transfers.
Chip & PIN holds the largest installed base; contactless is climbing the fastest.
End User:
Application context dictates terminal durability requirements, software integration depth, and replacement cycle frequency across Portuguese commercial sectors.
- Restaurants:Food service operators in Lisbon and Porto compress replacement cycles from seven years to four years, driven by demand for mobile form factors and contactless certification compliance during peak tourist seasons.
- Retail Stores:High-volume merchants prioritize fixed terminals with rapid transaction processing and integrated barcode scanning for inventory synchronization.
- Hospitality:Algarve hotels and seasonal operators require ruggedized outdoor-capable terminals for poolside and event payment acceptance.
- E-commerce:Virtual terminal software enables card-not-present processing for online merchants without physical hardware deployment.
Retail stores hold the largest share; restaurants are gaining share fastest.
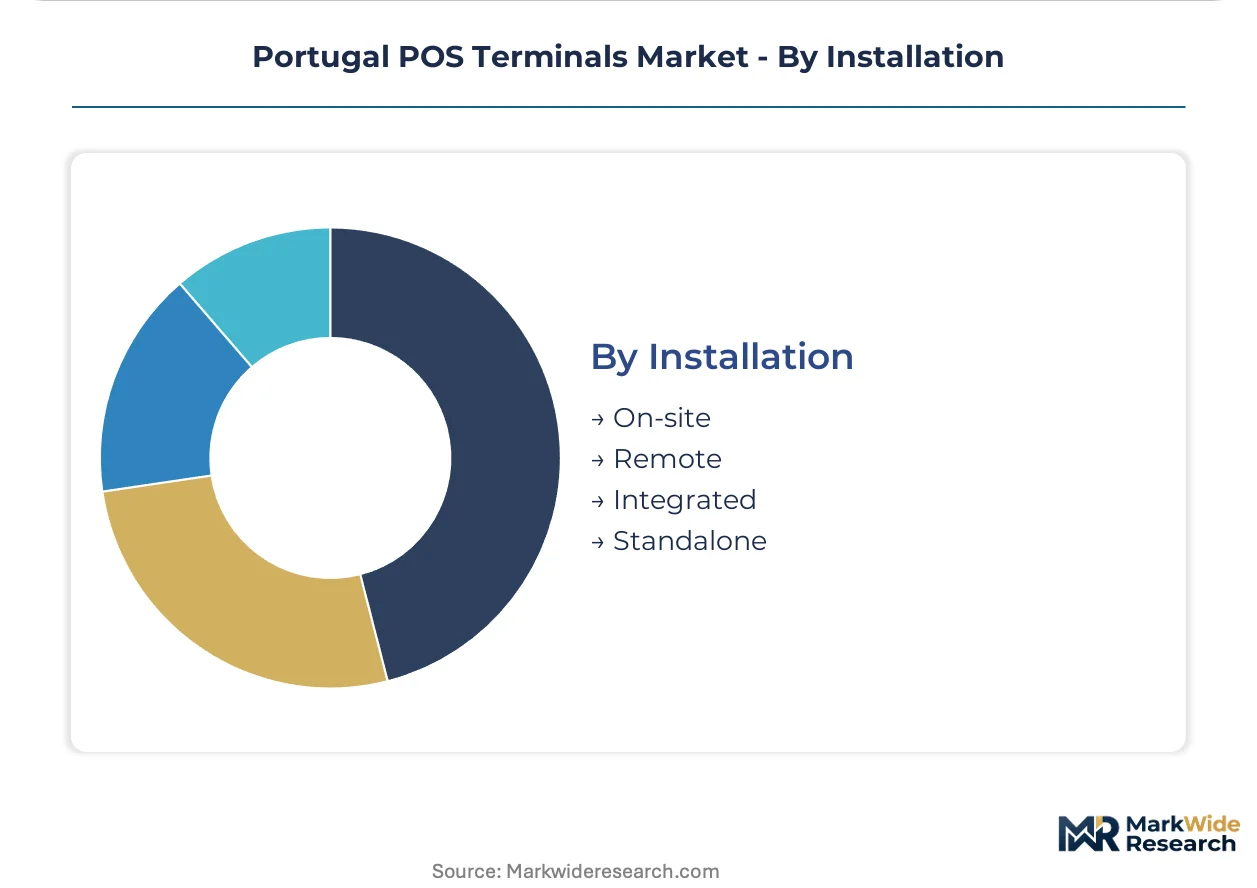
Installation:
Deployment architecture determines upfront capital allocation, ongoing technical support obligations, and integration complexity with existing merchant systems.
- Integrated:Terminals connected directly to ERP and inventory management systems dominate mid-market retail chains. Porto-based operators favor these configurations to unify transaction data with supply chain planning.
- On-site:Technician-assisted installation with local network configuration serves merchants lacking internal IT capabilities, common among Algarve seasonal hospitality operators.
- Remote:Cloud-based provisioning enables rapid deployment without physical site visits, accelerating time-to-revenue for software vendors.
- Standalone:Independent terminals without backend integration suit micro-merchants with simple reconciliation requirements.
On-site installation holds the largest share; integrated configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Portugal diverge sharply between metropolitan corridors and coastal tourism zones, with Greater Lisbon deploying smart terminals for integrated operations while Algarve operators prioritize ruggedized mobile units for seasonal flexibility.
Greater Lisbon
Lisbon's restaurant and retail density drives the fastest terminal replacement cycles nationwide. Banco de Portugal's certification requirements for contactless and instant payment protocols compress hardware lifespans from seven years to four. The city anchors national demand for Android-based smart terminals that unify inventory management with payment processing.
Porto Metropolitan Area
Porto's retail chains lead integrated terminal adoption, connecting payment hardware directly to ERP systems for supply chain synchronization. The national data protection authority's GDPR-derived standards push vendors toward embedded encryption modules. Mid-market operators here favor cloud-based reconciliation platforms over legacy standalone systems.
Algarve Tourism Corridor
Seasonal hospitality operators in Lagos and Faro remain underpenetrated by integrated inventory-payment systems. Poolside and outdoor event payment acceptance demands ruggedized, weather-resistant terminal form factors. Banco de Portugal's network compatibility mandates still apply, yet procurement concentrates in pre-season windows with compressed installation timelines.
Central Portugal
Coimbra and surrounding municipalities exhibit slower terminal refresh rates, with micro-merchants maintaining legacy EMV chip-and-PIN hardware beyond typical replacement cycles. The central bank's oversight extends certification requirements uniformly, yet distributor service density thins outside coastal corridors. Fixed countertop terminals dominate here where transaction mobility remains less critical.
Portugal POS Terminals Market Competitive Landscape
Capability concentration sits with specialized terminal manufacturers possessing Banco de Portugal certification expertise; scale advantage sits with European payment infrastructure conglomerates leveraging cross-border service networks. The market structures around three archetypes: domestic network-integrated specialists, European service infrastructure players, and software-agnostic hardware vendors. Consolidation pressures intensify as merchant acquiring relationships fragment and independent software vendors insert themselves between manufacturers and end users. Dominant competitive moves include geographic expansion through Iberian retail chain contracts and portfolio diversification into subscription-based software platforms.
Within the European service infrastructure tier, Ingenico Group (Worldline) and Verifone Inc occupy positions shaped by cross-border maintenance capabilities and terminal-agnostic software layers respectively. SIBS Pay represents the domestic network-integrated archetype, anchoring market access through proprietary Multibanco infrastructure requirements. These three exemplify how certification depth, service reach, and software flexibility define competitive positioning under Banco de Portugal's regulatory framework.
| Leading Market Players |
|---|
| NCR Corporation |
| Mastercard Inc |
| Ingenico Group (Worldline) |
| myPOS World Ltd |
| Sumup Inc |
| SIBS Pay |
| NEC Corporation |
| Vectron System AG |
| Verifone Inc |
| Others |
Value Network & Pricing Analysis
Semiconductor supply concentration in East Asian foundries exposes Portuguese distributors to logistics volatility that compresses pricing tiers between premium certified terminals and economy-grade alternatives while extending procurement lead times across all hardware categories.
Pricing Analysis
Long-term service contracts dominate terminal procurement across Iberian retail chains, with subscription-based SaaS tiers replacing one-time hardware sales as the primary revenue anchor. Price differentiation hinges on Banco de Portugal certification grade and after-sales service bundling intensity. Cost compression in economy-tier mobile terminals is intensifying because Android-based soft POS applications erode dedicated hardware demand among micro-merchants. Small hospitality operators in Algarve exhibit highest price sensitivity; Lisbon-based retail chains with ERP integration requirements show lowest.
Supply Chain Analysis
Extended payment terms from East Asian component suppliers strain working capital for Portuguese hardware distributors serving the terminal market. NFC antenna and secure element manufacturing concentrates in Taiwan, South Korea, and China. Raw material dependencies span semiconductor wafers, lithium-ion battery cells, and EMV-certified encryption modules. Single-source vulnerability persists for PCI-DSS certified security chipsets. Distribution runs through SIBS Pay's Multibanco-integrated channel network and independent value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portugal's POS terminal market sits in early-cycle expansion as SEPA instant payment infrastructure mandates force hardware refresh timelines across merchant categories previously content with seven-year replacement intervals.
For Market Incumbents: Entrench Banco de Portugal certification expertise as a defensive moat against software-agnostic challengers. Deepen backward integration into Android application platform development to capture recurring subscription revenue streams. Prioritize channel control through exclusive service contracts with SIBS Pay's Multibanco network infrastructure. For New Entrants and Emerging Players: Algarve's seasonal hospitality operators represent the most penetrable entry point, with poolside and event payment acceptance demanding ruggedized mobile terminals that incumbent portfolios underweight. Mid-market Porto retail chains seeking cloud-based reconciliation without legacy middleware complexity offer secondary beachhead. Lead with remote provisioning capabilities that compress installation timelines against technician-dependent competitors. For Investors and Strategic Acquirers: Banco de Portugal's instant payment protocol roadmap reshapes the acquisition landscape by privileging vendors with pre-certified SEPA-compliant hardware pipelines. Target vertically integrated specialists possessing both terminal manufacturing and embedded software development capabilities. Watch SIBS Pay's network integration requirements as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| SEPA Instant Payment Certification | Banco de Portugal protocol compliance secures merchant network access and accelerates replacement cycles. |
| Android Platform Integration | Smart terminal ecosystems collapse standalone POS software markets into bundled hardware-subscription offerings. |
| Algarve Distribution Partnership | Seasonal hospitality penetration captures underweighted tourism corridor demand with compressed pre-season windows. |
| Remote Provisioning Capability | Cloud-based deployment eliminates technician site visits and accelerates time-to-revenue for software vendors. |
| GDPR Privacy-by-Design Architecture | Embedded encryption modules command premium positioning under Portugal's national data protection authority mandates. |
Research Methodology
Initial hypotheses were tested against primary input from merchant acquiring executives, terminal hardware procurement managers, hospitality operations directors, and Banco de Portugal regulatory affairs specialists and refined through secondary validation against SEC filings, SIBS Pay network disclosure documents, European payment infrastructure trade data, and customs import records. Bottom-up terminal shipment estimates were triangulated with top-down payment transaction volume analysis.
Demand-supply balance across hardware form factors and certification tiers anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include terminal mobility class, payment authentication technology, end-use sector, and installation architecture. CAGRs were derived from installed base replacement velocity and merchant expansion patterns. SEPA instant payment infrastructure rollout timelines and Multibanco network integration requirements served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Portuguese tourism recovery trajectories, eurozone interest rate environments, or East Asian semiconductor export policies would shift the trajectory. Forecasts reflect assumptions about regulatory compliance timelines and merchant technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Gift Card and Incentive Card Market
Payments
United Arab Emirates Payment Market
Payments
Global Payments As a Service Market
Payments
Bus Card Reader Market
Payments
Digital Money Transfer Market
Payments
South Korea Digital Payments Market
Payments
Hungary POS Terminal Market
Payments
Enterprise Payment Software Market
Payments
Global Payments Market
Payments
Digital Transaction Management Market
Payments
Contactless Payment Ring Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
India Buy Now Pay Later Services Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Poland POS Terminal Market
Payments
Sweden Payments Market