
 Denmark Mobile Payments Market | 2026-2036
Denmark Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Mobile Payments Market Outlook
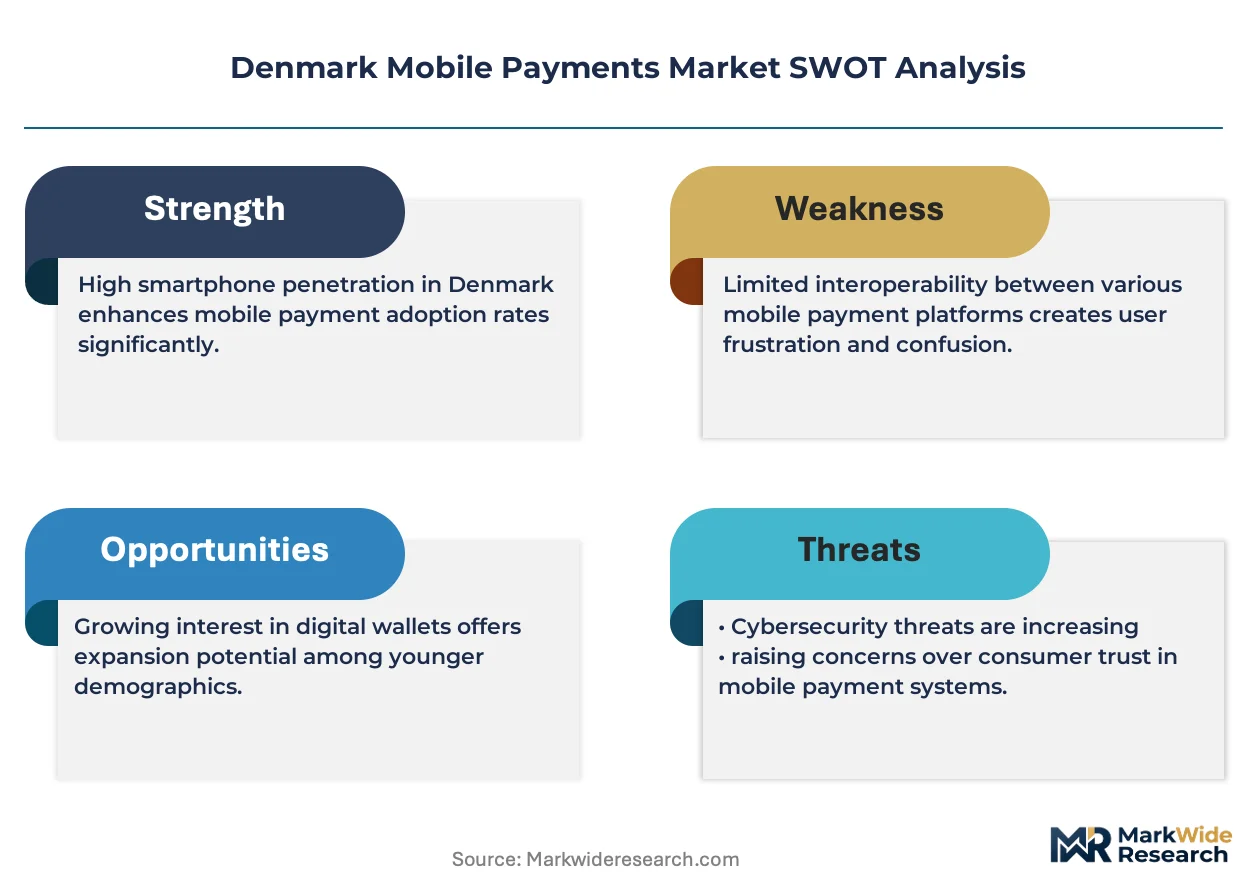
Merchant acquiring channels in Denmark is narrowing as contactless infrastructure consolidates around supermarket chains and transit operators. MobilePay A/S leverages its domestic bank consortium backing to sustain merchant loyalty across Jutland and Zealand. Mastercard Inc. competes through tokenization partnerships with Nordic card issuers. Apple Inc. anchors premium device-linked transactions via Apple Pay's integration with Danish NemID authentication protocols.
Denmark mobile payments encompass digital fund transfers initiated through portable computing devices, typically employing near-field communication chips operating at 13.56 MHz or encrypted host card emulation for transaction authorization. These systems serve commercial purpose by replacing physical card presentment with cryptogram-secured credential exchanges between consumer devices and point-of-sale terminals. NFC-based proximity payments dominate transaction volume in Copenhagen's retail core, while QR code methods extend into rural merchant environments with lower terminal investment capacity. Mobile wallet architectures capture the fastest expansion trajectory as tokenization standards harden against replay fraud. Bank transfer modalities retain structural importance for high-value B2B settlements where real-time gross settlement integration with Denmark's Straksclearing infrastructure reduces counterparty risk.
The Danish Financial Supervisory Authority enforces PSD2 strong customer authentication requirements that mandate two-factor validation for transactions exceeding designated thresholds. Danmarks Nationalbank oversees real-time payment infrastructure standards that constrain closed-loop wallet operators to interoperate with clearing systems. The Danish Data Protection Agency applies GDPR-level consent frameworks to transaction data monetization practices, limiting profiling-based revenue models. Stakeholders must monitor whether forthcoming central bank digital currency pilots alter merchant fee structures and wallet provider economics.
Market Dynamics
The Danish mobile payments sector is consolidating around real-time clearing infrastructure as Danmarks Nationalbank mandates interoperability between closed-loop wallets and the Straksclearing system, compressing margins for standalone wallet operators while favoring bank-backed platforms.
Growth Catalysts
- PSD2 Strong Customer Authentication:The Danish Financial Supervisory Authority's enforcement of two-factor validation for transactions above threshold limits is accelerating tokenization adoption among merchants seeking compliance-ready infrastructure.
- Transit operator digitization:Copenhagen's Rejsekort replacement programs and Aarhus light rail contactless rollout are embedding mobile payment habits across commuter demographics with high daily transaction frequency.
- NFC terminal saturation:Supermarket chains across Zealand and Jutland have completed point-of-sale upgrades, creating ubiquitous acceptance infrastructure that reduces consumer friction for proximity payments.
Market Restraints
- Clearing fee compression:Straksclearing's real-time gross settlement pricing structure caps wallet provider margins, constraining revenue models dependent on float or interchange arbitrage.
- GDPR consent frameworks:The Danish Data Protection Agency's strict transaction data monetization rules limit profiling-based ancillary revenue streams that subsidize payment services in less regulated jurisdictions.
- Legacy bank infrastructure:Rural merchant segments in North Jutland and South Denmark retain dial-up terminal dependencies that delay QR-code fallback deployment for smartphone-only consumers.
Strategic Opportunities
- Central bank digital currency pilots:Danmarks Nationalbank's exploratory e-krone program may alter merchant fee structures and create first-mover advantages for wallet providers integrating CBDC rails.
- B2B real-time settlements:High-value corporate treasury operations currently using batch-processed bank transfers represent conversion potential for mobile-integrated instant payment solutions.
- Rural merchant enablement:SoftPOS technology convergence with smartphone-based acceptance eliminates dedicated terminal capex, extending mobile payment penetration to lower-volume merchants in peripheral regions.
Industry Challenges
- Authentication architecture complexity:NemID integration requirements for high-value transactions demand specialized engineering talent scarce in the Danish fintech labor pool.
- Legacy core banking integration:Regional banks in Jutland operate on decades-old mainframe architectures that resist API-based wallet connectivity without expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Mobile Payments Market |
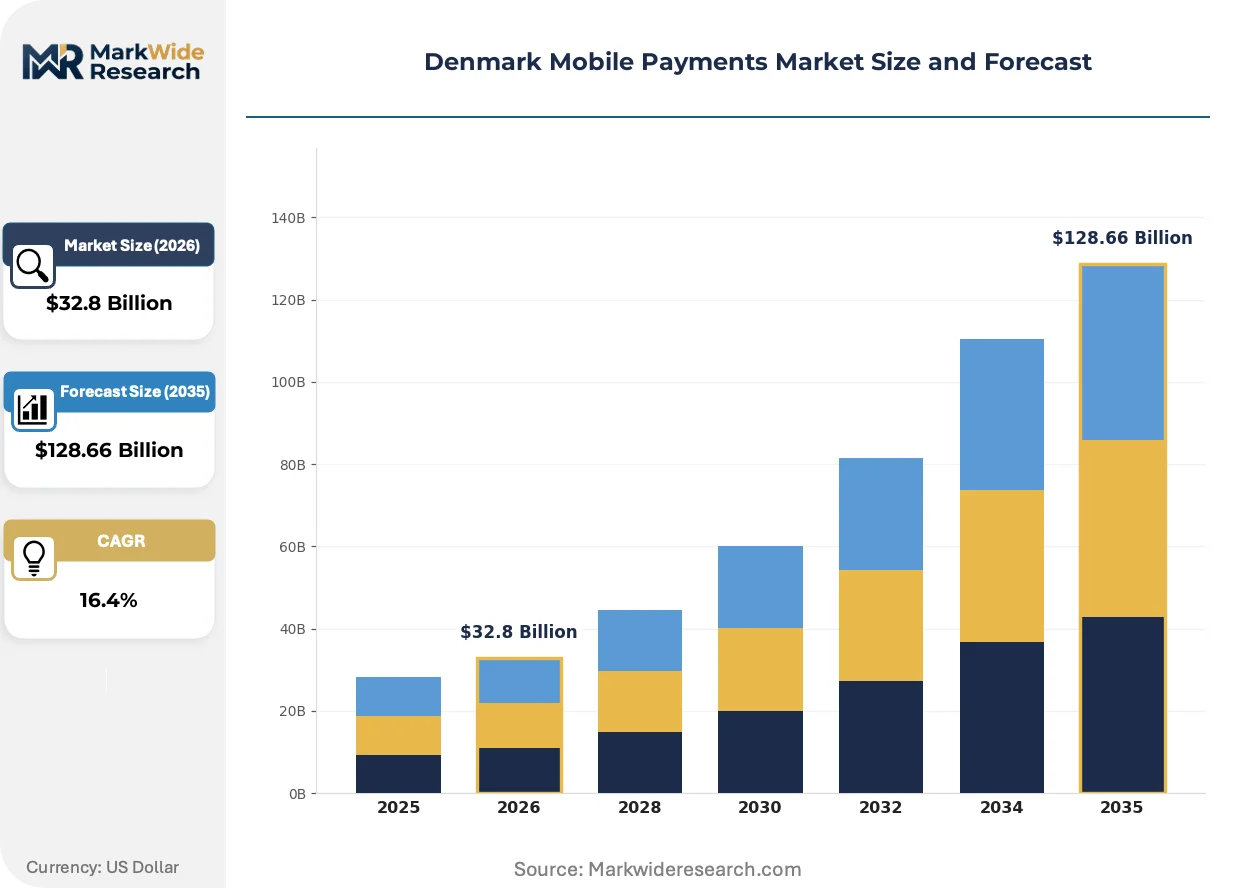
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $128.66 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Mobile Wallet, Bank Transfer, Direct Debit User Segment: Consumers, Retailers, E-commerce Platforms, Service Providers Technology: NFC, QR Code, Bluetooth, Tokenization Transaction Size: Small Value, Medium Value, High Value, Subscription |
| Companies Covered | Samsung Electronics, Mastercard Inc., MobilePay A/S, Nets Denmark A/S, PayPal Holdings, Inc., Apple Inc., Visa Inc., Amazon.com, Inc., Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Mobile Payments Market Strategic Shifts
Tokenization architectures are hardening security standards while softPOS solutions dismantle traditional terminal distribution economics. Regulatory pressure on data monetization is simultaneously forcing business model reinvention across the value chain.
Host card emulation technology enables smartphone-based payment acceptance without dedicated hardware investment. Small merchants in Aarhus and Odense are adopting softPOS at pace, bypassing traditional acquiring relationships. This capability is rendering obsolete the terminal leasing model that dominated Danish merchant services for two decades.
GDPR-level consent frameworks enforced by the Danish Data Protection Agency now govern transaction data monetization. Industrial consequence includes prohibition on behavioral profiling for advertising revenue without explicit opt-in. Wallet providers serving Copenhagen's retail core are pivoting toward subscription and SaaS models to replace lost data-driven income streams.
Merchant procurement of payment services is unbundling hardware from processing contracts. Independent software vendors and POS system integrators are displacing traditional bank-direct sales channels. This pattern concentrates in Zealand's urban corridor where merchant tech sophistication supports multi-vendor solution assembly.
Denmark Mobile Payments Market Segmentation
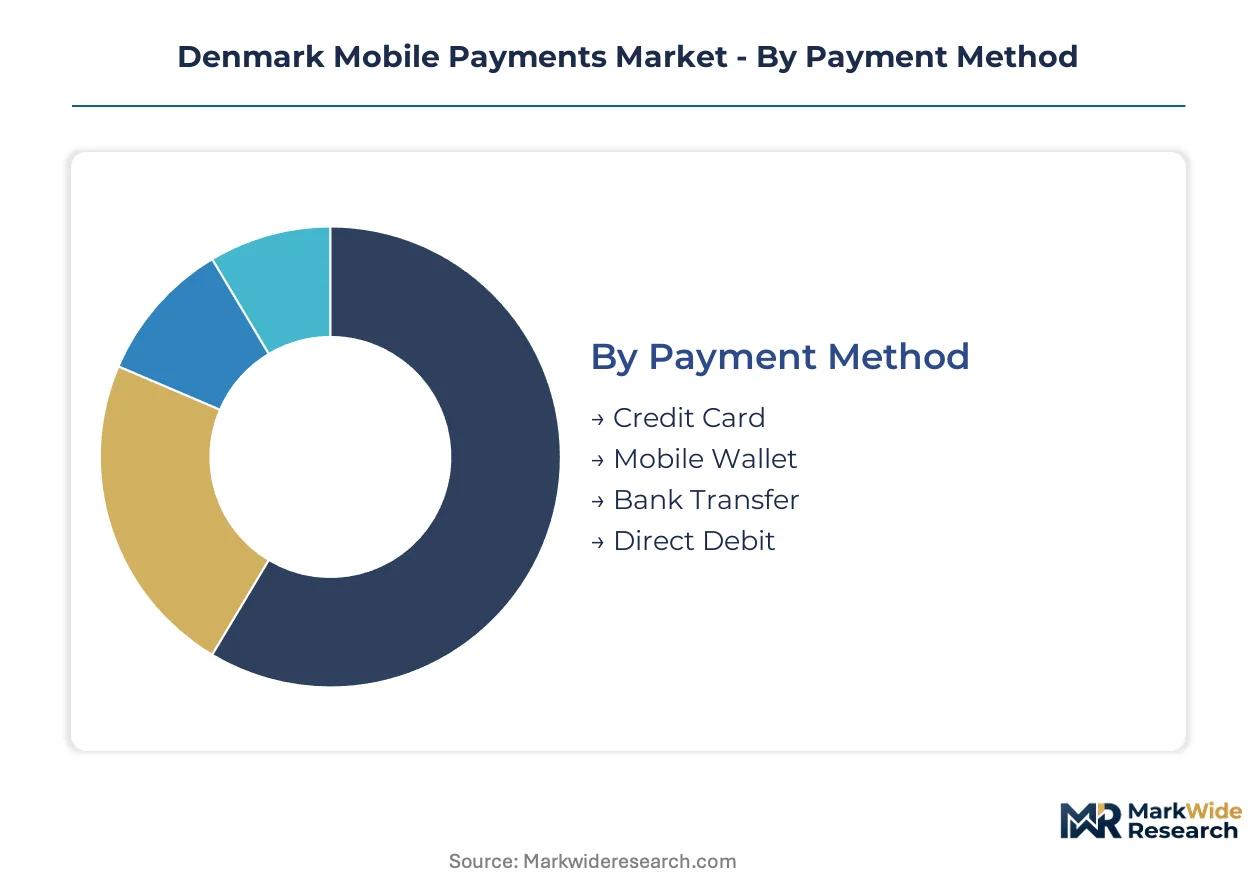
Mobile payment architectures in Denmark fragment across technical interfaces, user constituencies, and value thresholds. Each dimension carries distinct regulatory obligations and infrastructure requirements that shape provider economics.
Payment Method:
Cost tier differentiation separates card-linked instruments from account-based rails, with fee structures and settlement velocity driving merchant preferences.
- Credit Card:Tokenized card credentials routed through international schemes dominate Copenhagen's premium retail corridors. Danish merchants absorb interchange fees that scale with transaction value, pushing supermarkets toward alternative rails for high-frequency purchases.
- Mobile Wallet:Bank consortium-backed wallets leverage Straksclearing integration to bypass scheme fees. Jutland retailers favor these for instant settlement guarantees that improve working capital velocity.
- Bank Transfer:Real-time account-to-account transfers serve B2B settlements and invoice payments where PSD2 APIs enable automated reconciliation.
- Direct Debit:Pre-authorized pull transactions sustain subscription merchants and utility billers with predictable recurring revenue streams.
Credit card rails hold installed capacity. Mobile wallet is rotating up the share rankings.
User Segment:
Application context determines authentication rigor and interface design, with commercial use cases demanding stronger PSD2 compliance than peer-to-peer transfers.
- Consumers:Smartphone-toting individuals in Zealand urban centers execute proximity payments through NFC-enabled devices. NemID integration requirements for high-value purchases create friction that wallet providers address through biometric step-up authentication.
- Retailers:Physical merchants across Aarhus and Odense deploy softPOS solutions to accept payments without dedicated terminal investment. Supermarket chains maintain complex multi-acquirer relationships to optimize routing costs.
- E-commerce Platforms:Online merchants integrate MobilePay and card-on-file tokenization to reduce checkout abandonment. GDPR consent frameworks constrain their ability to monetize transaction data for targeted advertising.
- Service Providers:Gig economy platforms and professional services firms utilize mobile-integrated invoicing with real-time payment confirmation to reduce collection risk.
Retailers hold installed capacity. E-commerce platforms are rotating up the share rankings.
Technology:
Volume concentration follows terminal infrastructure deployment patterns, with proximity solutions saturating urban corridors while alternative interfaces penetrate peripheral markets.
- NFC:13.56 MHz near-field communication dominates Copenhagen's retail core where contactless terminal penetration exceeds ninety percent. Transit operator digitization programs embed daily payment habits across commuter demographics.
- QR Code:Optical scanning methods extend into rural North Jutland where merchants lack capital for NFC terminal upgrades. Lower technical barriers enable rapid merchant onboarding at minimal cost.
- Bluetooth:Low-energy beacon protocols enable proximity detection for venue-based payments in stadium and event contexts without consumer device positioning.
- Tokenization:Cryptographic credential substitution hardens security across all rails, with Danish issuers mandating dynamic cryptogram generation for card-present equivalence.
NFC holds installed capacity. QR code is rotating up the share rankings.
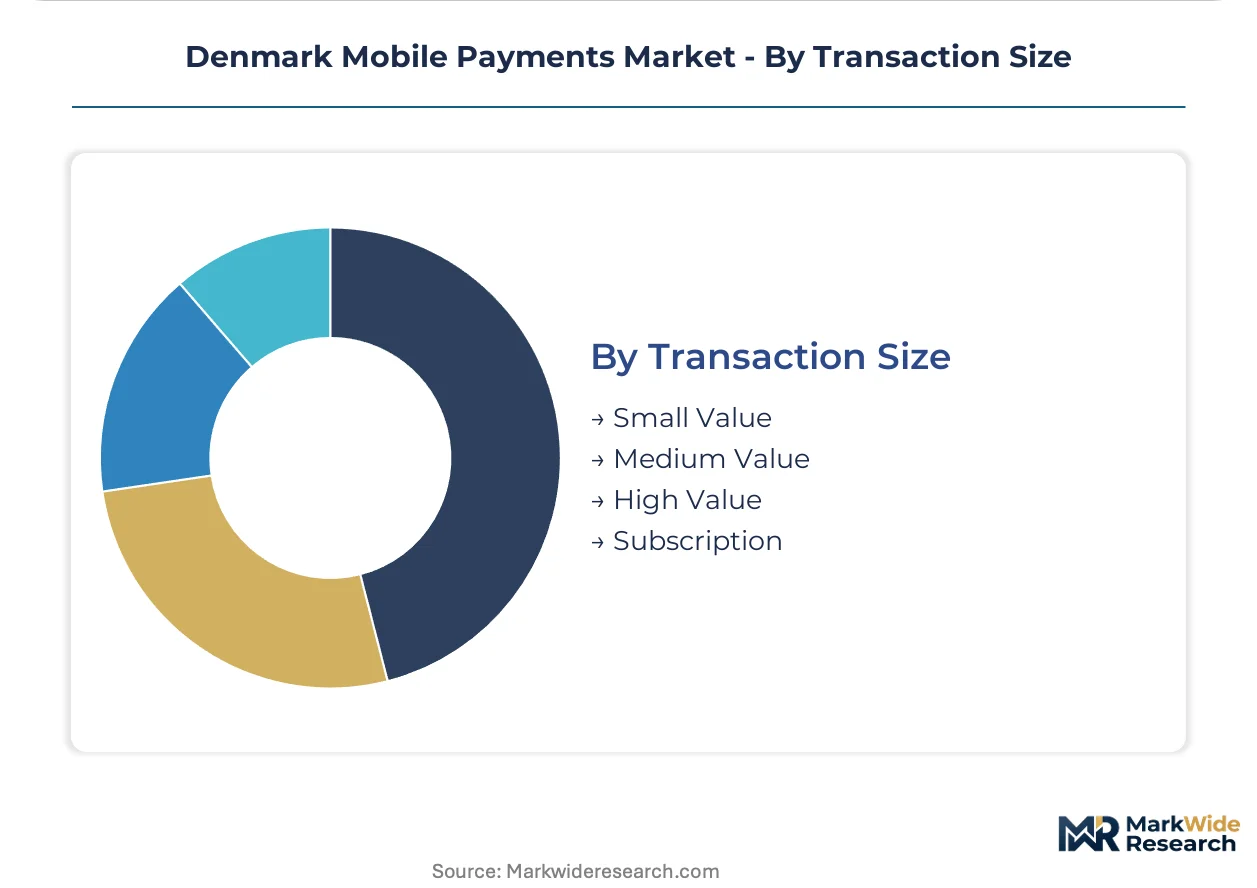
Transaction Size:
Customer type and value threshold dictate authentication intensity, with regulatory mandates stepping up verification requirements at designated monetary boundaries.
- Small Value:Sub-threshold purchases below PSD2 SCA limits execute with single-factor authentication, enabling frictionless coffee and transit payments across Zealand.
- Medium Value:Routine retail purchases trigger biometric or PIN confirmation, balancing security with throughput at supermarket checkouts.
- High Value:Corporate treasury and luxury goods transactions demand two-factor validation through NemID or bank app confirmation, extending settlement latency.
- Subscription:Recurring merchant-initiated payments operate under pre-established mandates with variable amount flexibility for utility and media services.
Small value holds installed capacity. Subscription is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Danish Financial Supervisory Authority's PSD2 mandates anchor Nordic payment infrastructure standards. Zealand and Jutland concentrate merchant terminal deployment. Copenhagen's transit digitization programs embed daily mobile payment habits across commuter demographics.
Zealand
Copenhagen's retail core drives NFC transaction density through supermarket chain terminal saturation. The Danish Financial Supervisory Authority enforces strong customer authentication thresholds above designated limits. Rejsekort replacement programs embed contactless payment habits across Greater Copenhagen's commuter rail network.
Central Jutland
Aarhus light rail contactless rollout accelerates merchant adoption across Denmark's second urban center. Danmarks Nationalbank mandates Straksclearing interoperability for closed-loop wallet operators. SoftPOS solutions penetrate Odense's small merchant base, eliminating dedicated terminal investment requirements.
North Jutland
Rural merchant segments retain dial-up terminal dependencies that delay QR-code fallback deployment. The Danish Data Protection Agency applies GDPR consent frameworks to transaction data monetization practices. Aalborg's regional banking infrastructure resists API-based wallet connectivity without expensive middleware layers.
South Denmark
Peripheral merchant enablement lags behind urban corridors in terminal infrastructure investment. NemID integration requirements for high-value transactions demand specialized engineering talent scarce in regional fintech labor pools. Esbjerg's port logistics operations represent conversion potential for mobile-integrated B2B instant payment solutions.
Capital Region
Corporate treasury operations in Copenhagen's financial district utilize real-time gross settlement for high-value settlements. Danmarks Nationalbank's exploratory e-krone program may alter merchant fee structures. Fintech clusters in Ørestad and Nordhavn develop authentication architectures compliant with national digital identity protocols.
Denmark Mobile Payments Market Competitive Environment
Domestic bank consortiums and international technology platforms split the market between closed-loop loyalty systems and open ecosystem interoperability. The vendor base concentrates around three strategic archetypes: bank-backed wallet operators leveraging clearing infrastructure, device-anchored payment systems with embedded authentication, and scheme-linked tokenization providers. Consolidation pressures favor platforms with direct Straksclearing integration. Competitive moves center on softPOS technology licensing and transit operator exclusivity agreements.
Within the domestic consortium tier, MobilePay A/S anchors merchant relationships across Jutland and Zealand through bank-backed clearing advantages. Samsung Electronics and Apple Inc. occupy positions at the device-anchored end, exemplifying premium hardware-linked transaction architectures. Mastercard Inc. represents the scheme-linked tokenization archetype, partnering with Nordic card issuers to secure credential exchanges.
| Leading Market Players |
|---|
| Samsung Electronics |
| Mastercard Inc. |
| MobilePay A/S |
| Nets Denmark A/S |
| PayPal Holdings, Inc. |
| Apple Inc. |
| Visa Inc. |
| Amazon.com, Inc. |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
Tokenization security module manufacturing concentrates in Germany and the Netherlands, anchoring cost structures for Danish wallet providers who compete downstream on SaaS attach rates rather than hardware margins. This upstream concentration compresses terminal equipment pricing while pushing margin pools toward recurring software layers.
Pricing Analysis
Copenhagen merchants pay premium acquiring rates compared to Aarhus counterparts due to higher NemID authentication complexity and faster settlement demands. Three-tier pricing structure across premium biometric-secured, standard tokenized, and economy QR-code tiers separates merchant segments by transaction volume and risk profile. Cost compression in the standard tier is intensifying because Straksclearing interoperability mandates eliminate float-based revenue arbitrage. Small rural merchants in North Jutland exhibit highest price sensitivity, while corporate treasury clients in the Capital Region prioritize settlement velocity over per-transaction cost.
Supply Chain Analysis
Foxconn and Jabil Electronics hold contract manufacturing capacity for NFC terminal chipsets serving the Nordic market. Component sourcing draws from Taiwan for semiconductor wafers, South Korea for memory modules, and Germany for precision authentication hardware. Single-source vulnerability concentrates in Taiwan-based secure element foundries where geopolitical disruption would constrain tokenization infrastructure deployment. Distribution runs through Copenhagen-based system integrators who bundle softPOS software with merchant acquiring relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards service-attach strategies as subscription-based fraud monitoring and real-time reconciliation tools expand faster than terminal hardware sales. Recurring SaaS layers now capture margin pools that transaction fees alone cannot sustain.
For Market Incumbents: Entrench clearing infrastructure advantages by deepening Straksclearing API integration before central bank digital currency pilots alter settlement economics. Acquire specialized NemID engineering talent to reduce authentication latency for high-value transactions. Defend against softPOS disintermediation by embedding merchant analytics dashboards that independent software vendors cannot replicate without core banking access. For New Entrants and Emerging Players: Rural merchant segments in South Denmark and North Jutland represent the most penetrable entry point where dial-up terminal dependencies delay incumbent QR-code deployment. SoftPOS technology licensing agreements with regional banks lacking in-house development capacity offer immediate distribution without direct acquiring licenses. Target gig economy platforms with mobile-integrated invoicing solutions that bypass traditional merchant onboarding friction. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated authentication specialists with proven NemID middleware capabilities and established Danmarks Nationalbank compliance relationships. Long-term viability hinges on positioning for central bank digital currency interoperability rather than closed-loop wallet economics. Monitor Danmarks Nationalbank e-krone pilot announcements as the critical inflection signal for fee structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| SoftPOS Technology Licensing | Eliminates dedicated terminal capex for Jutland merchants while capturing SaaS recurring revenue. |
| Straksclearing API Integration | Secures real-time settlement advantages that closed-loop competitors cannot replicate without bank consortium backing. |
| Biometric Authentication Investment | Reduces NemID friction for high-value transactions in Copenhagen's premium retail corridors. |
| Rural Merchant Enablement Program | Extends QR-code fallback penetration to North Jutland dial-up terminal dependencies. |
| CBDC Interoperability Development | Positions wallet architecture for Danmarks Nationalbank e-krone settlement rails before pilot completion. |
Study Parameters
Desk research of regulatory filings from the Danish Financial Supervisory Authority, Danmarks Nationalbank clearing statistics, and PSD2 implementation guidelines preceded structured interviews with mobile wallet product managers, merchant acquiring executives, transit authority procurement officers, and fintech compliance leads. Secondary validation drew from payment scheme disclosure documents, terminal infrastructure deployment databases, and GDPR enforcement case records from the Danish Data Protection Agency. Bottom-up merchant adoption modeling and top-down clearing volume analysis were triangulated against segment-level growth assumptions.
Assumptions regarding Straksclearing fee stability, NemID authentication latency improvements, and transit operator digitization timelines were held fixed across baseline scenarios while central bank digital currency pilot scope and GDPR enforcement intensity were varied in sensitivity testing. Segmentation modeling incorporated payment method, user segment, technology interface, and transaction size dimensions alongside regional infrastructure penetration rates. CAGRs were derived from logistic adoption curves fitted to terminal deployment data and consumer payment habit surveys.
Practitioners should monitor Danmarks Nationalbank e-krone pilot scope announcements, Danish Financial Supervisory Authority PSD3 consultation timelines, and transit operator procurement award decisions for early signals of infrastructure inflection. Quarterly review of Straksclearing volume disaggregations, merchant acquiring contract renegotiation patterns, and softPOS adoption rates across Aarhus and Odense is advised to detect competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Wearable Payment Device Market
Payments
Canada Prepaid Cards Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Latin America Retail Cash Management Market
Payments
New Zealand Payments Market
Payments
In Vehicles Payment Market
Payments
Social Media Payment Solution Market
Payments
Saudi Arabia Payments Market
Payments
Brazil POS Terminal Market
Payments
Germany Real Time Payments Market
Payments
Malaysia Payments Market
Payments
Indonesia Payments Infrastructure Market
Payments
Japan POS Terminals Market
Payments
Payment Orchestration Platform Market
Payments
China Mobile Payments Market
Payments
North America Payments Market