
 Electronic Payment Processing Software Market | 2026-2036
Electronic Payment Processing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Payment Processing Software Market Analysis
Merchant buyer concentration is realigning as mid-market e-commerce platforms aggregate transaction volumes across multiple storefronts, reducing direct relationships with individual payment processors. Fiserv leverages its merchant acquiring scale to sustain pricing power in integrated POS environments. Stripe competes through developer-centric API architectures that anchor its presence in subscription billing and marketplace platforms. Adyen differentiates via single-platform global acquiring licenses that span dozens of jurisdictions without correspondent banking fragmentation.
Electronic payment processing software constitutes a transaction orchestration layer that routes, authorizes, and settles digital payments between consumers, merchants, and financial institutions through encrypted API protocols and tokenized credential vaults. Its primary commercial purpose is reducing payment friction while minimizing fraud exposure and interchange cost leakage for merchants and payment service providers. Cloud-based deployment configurations command the dominant infrastructure share as SaaS delivery models reduce capital intensity for mid-tier merchants entering omnichannel commerce. Mobile payments and contactless payment modalities represent the fastest-expanding product type cluster, driven by NFC terminal penetration and wallet application proliferation in physical retail environments.
PCI DSS standards administered by the PCI Security Standards Council mandate encryption and tokenization architectures that shape product development roadmaps across the vendor landscape. The EU AI Act and GDPR frameworks impose algorithmic transparency and data localization requirements that constrain cross-border transaction routing and machine learning model deployment strategies. Stakeholders must monitor evolving central bank digital currency pilot programs and real-time payment infrastructure mandates that threaten to disintermediate traditional processing fee structures.
Market Dynamics
Merchant acquiring networks are consolidating around real-time payment rails, compressing interchange economics and forcing processors to differentiate through embedded financial services rather than transaction routing alone.
Growth Catalysts
- UPI infrastructure expansion:India's unified payments interface is electrifying merchant onboarding velocity, reducing settlement latency from T+1 to real-time and expanding acquiring reach into tier-2 and tier-3 cities.
- PCI DSS 4.0 compliance mandates:The updated security framework is accelerating tokenization architecture upgrades across merchant portfolios, creating replacement demand for legacy encryption stacks.
- Open banking APIs:The European Union's PSD2-driven data sharing protocols are enabling account-to-account payment initiation, reducing card network dependency for e-commerce checkout flows.
Market Restraints
- Interchange cost compression:Regulatory caps on merchant discount rates in Brazil and India are squeezing processor margins, forcing volume-dependent revenue models.
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud control the majority of payment processing workloads, creating single-point-of-failure exposure and vendor lock-in risk.
- CBDC disintermediation threat:Central bank digital currency pilot programs in China, India, and the European Union threaten to bypass traditional acquiring networks entirely.
Strategic Opportunities
- Embedded finance convergence:The intersection of payment processing with lending, insurance, and treasury management is opening white space for platform-integrated financial product distribution.
- B2B payment automation:Accounts payable digitization in manufacturing and logistics verticals remains underpenetrated, with manual invoice processing still dominating enterprise workflows.
- India's merchant acquisition gap:Micro-merchants and kirana stores represent millions of unserved acceptance points, with UPI QR infrastructure reducing deployment costs to near-zero.
Industry Challenges
- Token vault migration complexity:PCI DSS 4.0 requires credential re-tokenization across billions of stored cards, demanding multi-year engineering roadmaps without service interruption.
- Cross-border compliance fragmentation:Divergent data localization requirements across Brazil's LGPD, India's RBI mandates, and China's PIPL are forcing redundant infrastructure deployment.
- Legacy core system entanglement:Tier-1 banks operate on decades-old mainframe architectures, complicating API-first integration with modern orchestration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Payment Processing Software Market |
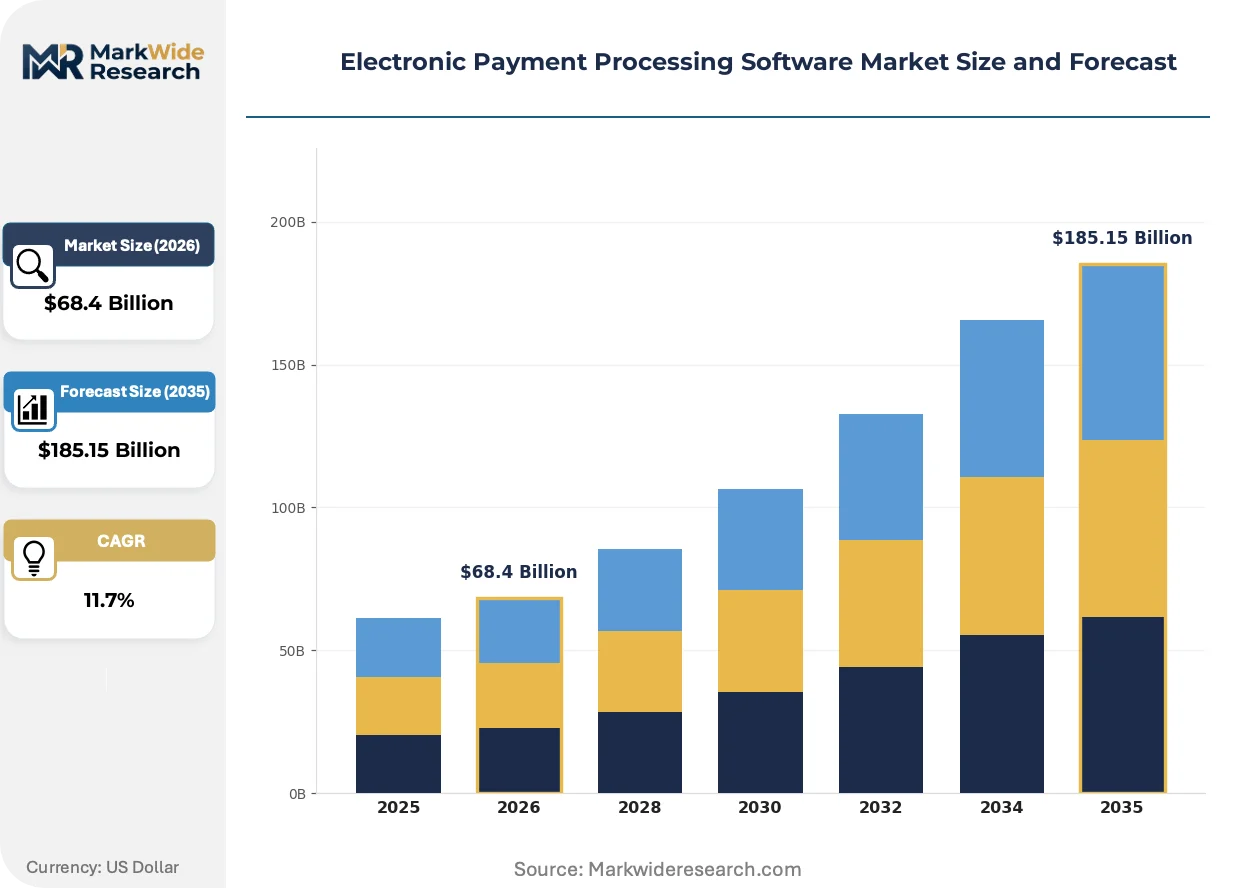
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Payment Gateway, Mobile Payments, Contactless Payments, Payment Processing Platform Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Retail, E-Commerce, Financial Institutions, Government Technology: Blockchain, Tokenization, Encryption, Artificial Intelligence |
| Companies Covered | PayPal, Fiserv, FIS, Global Payments, Stripe, Block, Adyen, Worldpay, ACI Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Payment Processing Software Market Emerging Trajectories
Payment orchestration is fragmenting into specialized layers, with merchants unbundling authorization, fraud detection, and settlement into best-of-breed components rather than monolithic platforms.
Network tokenization is electrifying credential security across e-commerce checkouts. The technology replaces primary account numbers with device-specific tokens, rendering intercepted data useless to attackers. Large merchants in travel and subscription verticals are adopting this at scale to reduce PCI scope and fraud chargebacks. This shift is compressing liability exposure for acquirers while shifting security investment toward token vault operators.
The EU AI Act is imposing algorithmic transparency requirements on fraud scoring models deployed in European transactions. Machine learning systems must now document training data provenance and decision logic for regulatory audit. High-risk payment authentication flows face the strictest scrutiny, with biometric verification systems requiring explicit consent frameworks and human oversight protocols.
Merchant procurement of payment services is fragmenting by transaction type rather than geography. Subscription businesses are selecting specialized recurring billing engines separate from one-time purchase processors. Marketplaces are adopting split-payment orchestrators that handle multi-party settlement. This unbundling is most advanced in North American SaaS and European platform economies, where technical integration costs have fallen below switching friction thresholds.
Electronic Payment Processing Software Market Segmentation
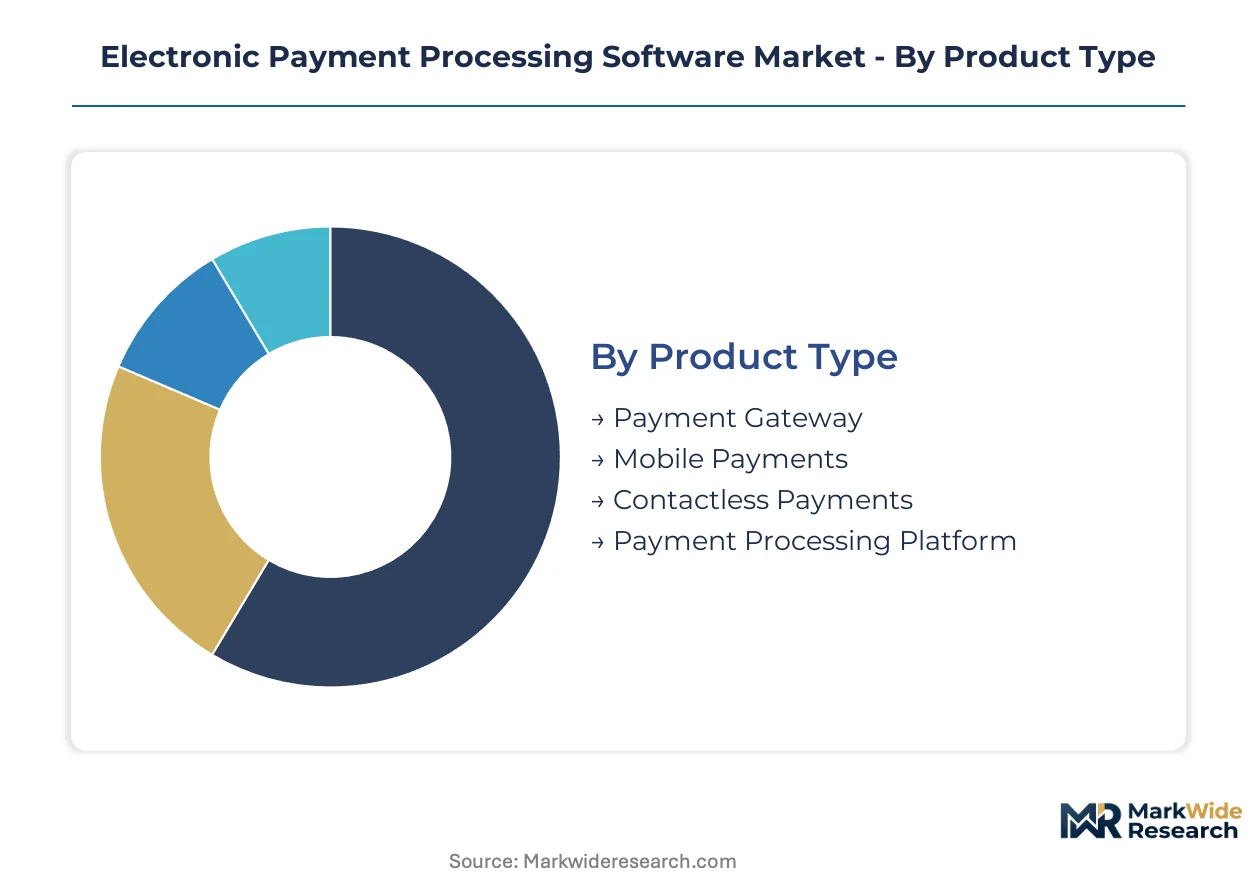
Payment processing software segments diverge sharply in infrastructure requirements and margin profiles. Cloud-native architectures command premium valuations against legacy on-premise deployments. Tokenization and AI-driven fraud layers attract specialized vendor investment distinct from core transaction routing.
Product Type:
Standardized gateway APIs serve commodity transaction volumes while bespoke platform builds capture enterprise complexity premiums.
- Payment Gateway:API middleware routing authorization requests between merchant carts and acquiring banks. Demand concentrates among mid-market e-commerce merchants in India seeking rapid UPI integration without direct RBI licensing overhead.
- Mobile Payments:Smartphone-native transaction initiation through NFC, QR codes, and in-app wallets. India's tier-2 and tier-3 cities drive merchant onboarding velocity as UPI QR infrastructure eliminates terminal hardware costs.
- Contactless Payments:Tap-to-pay card and wearable transactions via NFC protocols. European retailers under PSD2 mandate adoption.
- Payment Processing Platform:End-to-end acquiring stacks spanning authorization, settlement, and reconciliation. Large enterprises in Brazil seek modular alternatives to interchange-capped legacy processors.
Leading the category by volume: Payment Gateway. Growing fastest: Mobile Payments.
Deployment:
Capital intensity separates merchant tiers, with SaaS delivery eliminating upfront infrastructure investment for scaling businesses.
- Cloud-Based:Third-party hosted infrastructure with elastic compute scaling. Indian fintechs and Southeast Asian marketplaces favor AWS and Azure deployments for rapid geographic expansion without data center construction.
- On-Premise:Self-managed hardware in merchant or processor facilities. Tier-1 banks in China and state-owned financial institutions maintain captive stacks under data localization mandates from SAMR and PIPL frameworks.
- Hybrid:Split architectures keeping sensitive credentials on-premise while routing transactions through cloud orchestration. European merchants under GDPR and EU AI Act algorithmic transparency rules adopt this for fraud model hosting.
- SaaS:Fully managed software subscriptions with zero infrastructure ownership. Brazilian mid-market retailers leverage SaaS acquiring to bypass capital constraints from compressed interchange margins.
Dominant by merchant count: SaaS. Steepest expansion trajectory: Cloud-Based.
End User:
Transaction volume scale and fraud exposure profiles shape procurement specifications across buyer categories.
- Retail:Brick-and-mortar merchants with omnichannel integration requirements. India's kirana stores adopt UPI QR at scale under RBI's merchant acquisition push.
- E-Commerce:Digital-native merchants with subscription and marketplace complexity. European platforms unbundle payment orchestration from core commerce stacks under PSD2 open banking protocols.
- Financial Institutions:Banks and credit unions requiring white-label processing infrastructure. Brazilian institutions navigate central bank interchange caps by embedding lending products into payment flows.
- Government:Tax collection, benefits distribution, and procurement payment systems. India's state-level digital governance initiatives drive real-time settlement demand.
Highest transaction throughput: Financial Institutions. Gaining share fastest: E-Commerce.
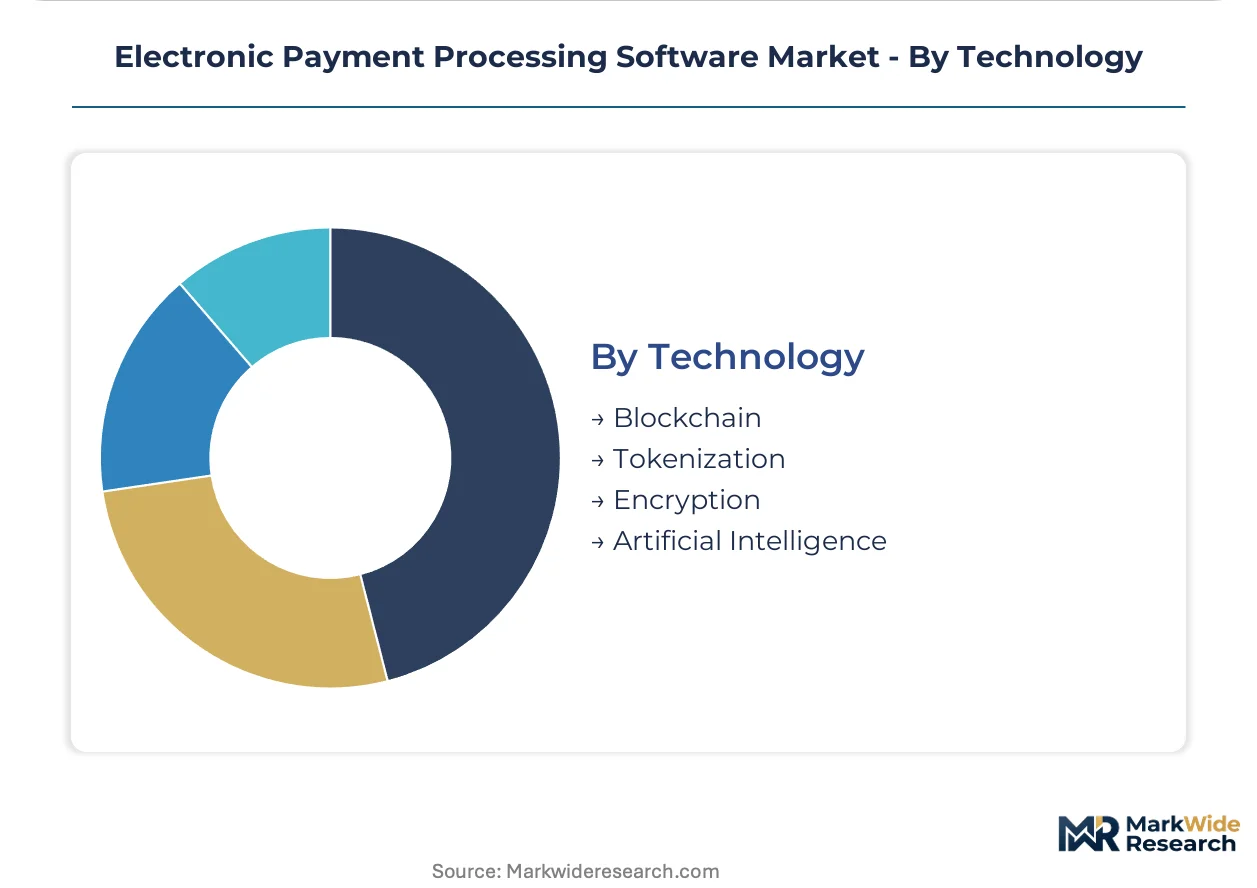
Technology:
Security architecture investments separate compliance-minimum deployments from fraud-loss reduction strategies.
- Blockchain:Distributed ledger settlement and cross-border remittance rails. China's digital yuan pilots test CBDC disintermediation of traditional acquiring networks.
- Tokenization:Credential vaulting replacing primary account numbers with device-specific tokens. PCI DSS 4.0 mandates drive replacement demand across European and North American merchant portfolios.
- Encryption:End-to-end cryptographic protection of transaction data in transit and at rest. Baseline requirement under PCI DSS across all deployment configurations.
- Artificial Intelligence:Machine learning models for real-time fraud scoring and transaction authorization optimization. EU AI Act imposes algorithmic transparency and human oversight requirements on European deployments.
Widest deployment base: Encryption. Climbing the fastest: Tokenization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates merchant acquisition velocity as UPI infrastructure electrifies tier-2 and tier-3 cities. Brazil navigates interchange compression through embedded finance convergence. Germany anchors European open banking adoption under PSD2 protocols.
India
RBI's merchant acquisition push and UPI QR infrastructure expansion drive onboarding of micro-merchants and kirana stores. The central bank's real-time settlement mandates compress latency from T+1 to instant. Mumbai and Bangalore fintech clusters concentrate developer talent for payment orchestration platforms.
Brazil
Central bank caps on merchant discount rates force processors toward volume-dependent revenue models and lending product embedding. ANVISA and Banco Central do Brasil regulate payment institution licensing. São Paulo's financial district hosts acquiring network headquarters navigating compressed interchange economics.
Germany
PSD2-driven account-to-account payment initiation reduces card network dependency for e-commerce checkout flows. BaFin supervision enforces strong customer authentication under EU regulatory frameworks. Frankfurt's banking cluster anchors white-label processing infrastructure for European financial institutions.
United States
Subscription billing complexity and marketplace platform proliferation sustain demand for developer-centric API architectures. FTC and CFPB oversight shapes consumer protection in digital payments. San Francisco and New York metro areas concentrate venture-backed fintechs unbundling payment orchestration layers.
China
Digital yuan pilot programs test CBDC disintermediation of traditional acquiring networks. SAMR and PIPL frameworks enforce data localization for payment processing workloads. Shanghai and Shenzhen technology corridors host state-affiliated institutions maintaining captive processing stacks under central bank direction.
Electronic Payment Processing Software Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance and B2B payment automation adjacencies. The vendor base stratifies across three tiers: global acquiring networks with direct banking licenses, developer-centric API platforms, and specialized fraud orchestration layers. Consolidation pressures intensify as real-time payment rails compress interchange economics. Dominant competitive moves include strategic partnerships for geographic expansion and portfolio diversification into lending and treasury management products.
Within the global acquiring tier, Fiserv and FIS occupy positions anchored by merchant scale and integrated POS environments. Stripe exemplifies the developer-centric archetype through API-first architectures serving subscription and marketplace verticals. Adyen sits within the single-platform licensing tier, spanning multi-jurisdictional acquiring without correspondent banking fragmentation.
| Leading Market Players |
|---|
| PayPal |
| Fiserv |
| FIS |
| Global Payments |
| Stripe |
| Block |
| Adyen |
| Worldpay |
| ACI Worldwide |
| Others |
Supply Flow & Price Mechanics
Merchant procurement consolidation around real-time payment rails is forcing processors to absorb interchange compression through volume-dependent SaaS tiers rather than per-transaction premiums. This demand-side shift toward embedded financial services bundles compresses standalone transaction routing margins while elevating platform-integrated pricing power.
Pricing Analysis
Volume-dependent SaaS tiers dominate the pricing architecture, separating high-transction merchants on elastic cloud infrastructure from micro-merchants on standardized gateway APIs. Price differentiation rests on PCI DSS certification level and geographic acquiring license breadth. Pricing pressure stems from regulatory interchange caps in Brazil and India squeezing processor margins. Micro-merchants and kirana stores exhibit highest price sensitivity, while enterprise marketplaces prioritize API flexibility over unit cost.
Supply Chain Analysis
Regional distribution of payment infrastructure concentrates cloud compute workloads across AWS, Microsoft Azure, and Google Cloud data centers in India, Germany, and the United States. Software development draws from semiconductor supply chains anchored in Taiwan and South Korea, with encryption hardware sourcing from Chinese and Japanese component manufacturers. Single-source vulnerability in hyperscaler concentration creates systemic failure exposure. Distribution runs through API-first developer portals and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
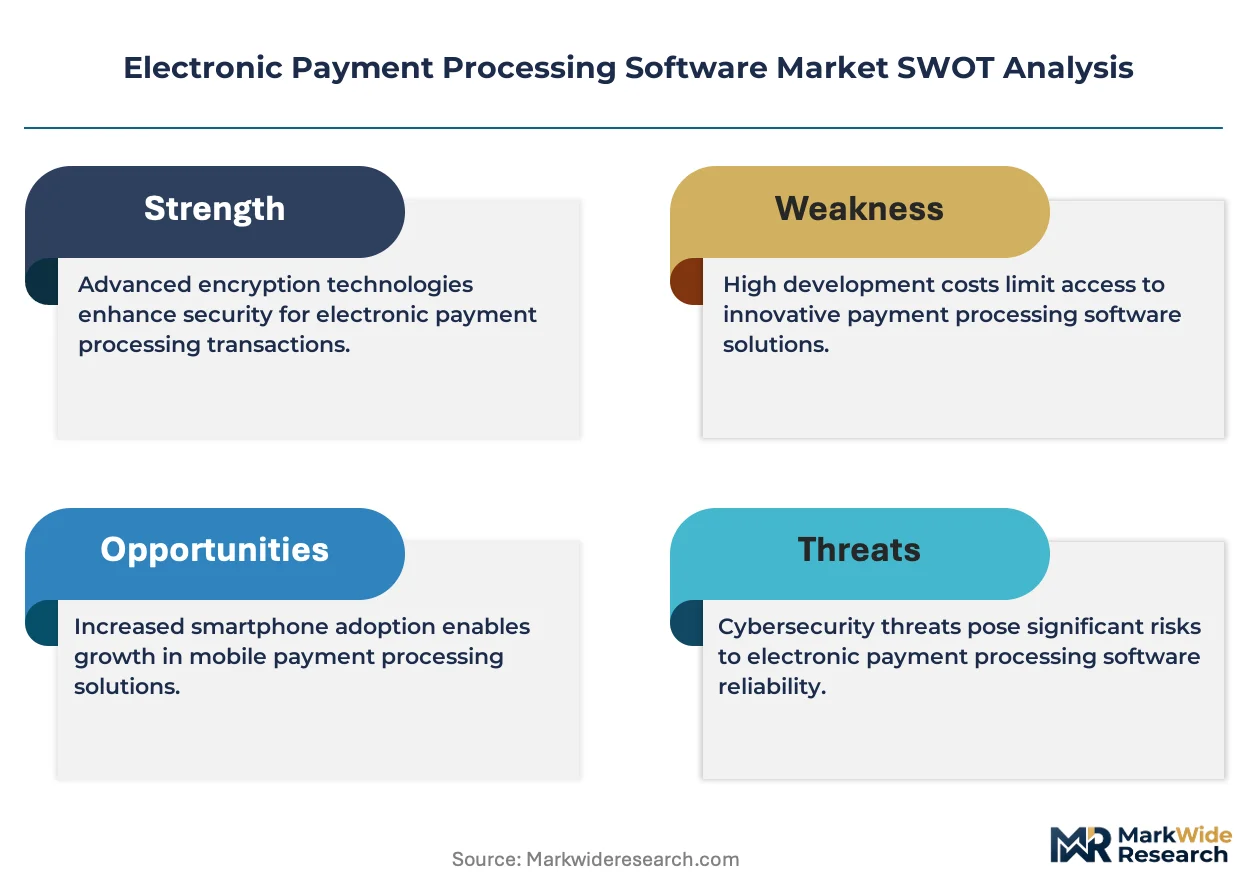
This market represents a consolidation play as real-time payment infrastructure mandates and interchange compression force sub-scale processors toward acquisition or exit. Regulatory compliance burdens and token vault migration complexity disproportionately burden capital-constrained competitors.
For Market Incumbents: Cement acquiring network density through UPI infrastructure partnerships in India's tier-2 and tier-3 cities. Deepen vertical integration into token vault operations to capture PCI DSS 4.0 compliance replacement cycles. Defend against embedded finance convergence by bundling lending and treasury products into merchant platforms.
For New Entrants and Emerging Players: Capture B2B payment automation white space in manufacturing and logistics verticals where manual invoice processing still dominates. India's micro-merchant acquisition gap offers the most penetrable entry point given UPI QR infrastructure eliminates terminal deployment costs. Pursue API-first developer evangelism to anchor subscription billing and marketplace platform relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized fraud orchestration layers given EU AI Act algorithmic transparency mandates forcing incumbent model redevelopment. Long-term viability favors vendors with multi-jurisdictional acquiring licenses and cloud-native architectures. Watch central bank digital currency pilot progression as disintermediation signal threatening traditional fee structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded finance convergence with lending products anchors merchant retention under interchange compression. |
| Geographic Expansion | UPI infrastructure partnerships in India electrify merchant onboarding velocity in underserved tier-2 cities. |
| Acquisition of Specialist Firm | Fraud orchestration layer consolidation addresses EU AI Act algorithmic transparency compliance requirements. |
| Product Launch | Token vault migration services capture PCI DSS 4.0 replacement demand across European merchant portfolios. |
| Strategic Partnership | Cloud provider alliances reduce infrastructure concentration risk for mid-tier processors seeking elastic scale. |
Methodological Framework
Document review covered regulatory filings from RBI, Banco Central do Brasil, and BaFin, complemented by interviews with payment platform CTOs, merchant acquiring executives, fraud engineering leads, and open banking integration specialists. Secondary validation drew from PCI Security Standards Council documentation, EU AI Act implementation guidance, and central bank digital currency pilot disclosures. Bottom-up merchant volume estimates triangulated against top-down infrastructure deployment data.
Historical transaction volume trajectories cross-referenced against panel input from processor executives and merchant procurement officers across the analysis window. Segmentation modeling incorporated deployment configuration, organization size tier, vertical application, geographic regulatory cluster, and technology architecture. CAGRs derived from elasticity-adjusted adoption curves and infrastructure penetration benchmarks. Forecast inputs included UPI transaction velocity data and interchange regulation implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CBDC disintermediation progression and cloud infrastructure regulatory fragmentation. Outputs reflect documented assumptions on merchant acquisition velocity and compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United States Payments Market
Payments
Bill Splitting Apps Market
Payments
Mobile Payment Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Outdoor Payment Terminal Market
Payments
Argentina Payments Market
Payments
Africa Virtual Cards Market
Payments
Contactless Payment Market
Payments
Global Accounts Payable Automation Market
Payments
Digital Remittance Service Market
Payments
Vietnam Mobile Payments Market
Payments
France POS Terminal Market
Payments
Global Prepaid Cards Market
Payments
China Payment Gateway Market
Payments
Taiwan Mobile Payments Market
Payments
Saudi Arabia Buy Now Pay Later Services Market