
 Wearable Payments Market | 2026-2036
Wearable Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Payments Market Outlook
Merchant acquirer consolidation among transit authorities and large retail chains is realigning procurement priorities for wearable payment terminals. Apple Inc. leverages its closed-loop ecosystem to control token provisioning and device authentication at scale. Samsung Electronics competes through Knox security architecture and broad smartwatch distribution across carrier channels. PayPal Holdings Inc. extends its merchant network by enabling wearable checkout integration for independent retailers without dedicated POS hardware.
Wearable payments encompass contactless transaction execution via wrist-worn or body-integrated devices using near-field communication, secure element chips, and biometric authentication sensors. The architecture combines ISO 14443-compliant RF interfaces with EMVCo tokenization to replace primary account numbers with dynamic credentials during transit or retail checkout. Smartwatches dominate transaction volume due to established consumer familiarity and multi-function utility, while smart jewelry captures premium positioning through precious metal form factors that mask payment functionality. NFC technology anchors the installed base because of its sub-100 millisecond transaction latency and compatibility with existing POS infrastructure, though biometric authentication represents the fastest-growing layer as vein-pattern and cardiac rhythm verification mature.
The PCI Security Standards Council governs token vault architecture and encryption key management for wearable form factors, while EMVCo certifies contactless kernel compliance across device manufacturers. The Federal Reserve's Regulation E provides US consumer liability protections for unauthorized wearable transactions, and the EU Payment Services Directive II mandates strong customer authentication for in-store wearable purchases exceeding contactless limits. Stakeholders must monitor biometric data governance frameworks as facial and vascular recognition migrate from smartphones to payment-enabled wearables.
Market Dynamics
Transit authority procurement consolidation is compressing vendor margins while forcing wearable payment terminal manufacturers to bundle software services with hardware contracts.
Growth Catalysts
- EMVCo Tokenization Standards:PCI SSC certification requirements for secure element chips are accelerating merchant acceptance of wrist-worn payment devices across retail networks.
- Seoul Metropolitan Integration:South Korea's T-money wearable coverage of subway, bus, and taxi systems demonstrates network-effect viability for multimodal transit payments.
- Biometric Sensor Maturation:Vein-pattern recognition and cardiac rhythm verification are reducing transaction friction below 100-millisecond latency thresholds.
Market Restraints
- Secure Element Supply Concentration:Foundry capacity for certified payment chips concentrates among three semiconductor manufacturers, creating procurement bottlenecks.
- ISO 14443 Interoperability Gaps:Legacy POS infrastructure in developing markets lacks firmware updates required for biometric-authenticated wearable transactions.
- Smartwatch Substitution Pressure:Smartphone-based contactless wallets retain consumer preference for high-value purchases due to larger screen verification.
Strategic Opportunities
- India Transit Modernization:The National Common Mobility Card framework creates procurement pathways for wearable payment terminals across 25 metro rail networks.
- EU Strong Customer Authentication Mandate:Payment Services Directive II requirements for biometric verification above contactless limits favor wearable form factors with embedded sensors.
- Smart Jewelry Distribution:Precious metal form factors masking payment functionality are penetrating luxury retail channels previously closed to technology products.
Industry Challenges
- Biometric Data Governance:Facial and vascular recognition migration to wearables requires compliance with fragmented national privacy frameworks including GDPR and state-level US regulations.
- EMVCo Certification Timelines:Contactless kernel compliance testing for new device manufacturers extends 14-18 months, delaying market entry.
- Merchant Acquirer Integration:Independent retailers lack technical resources to configure wearable checkout without dedicated POS hardware support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Payments Market |
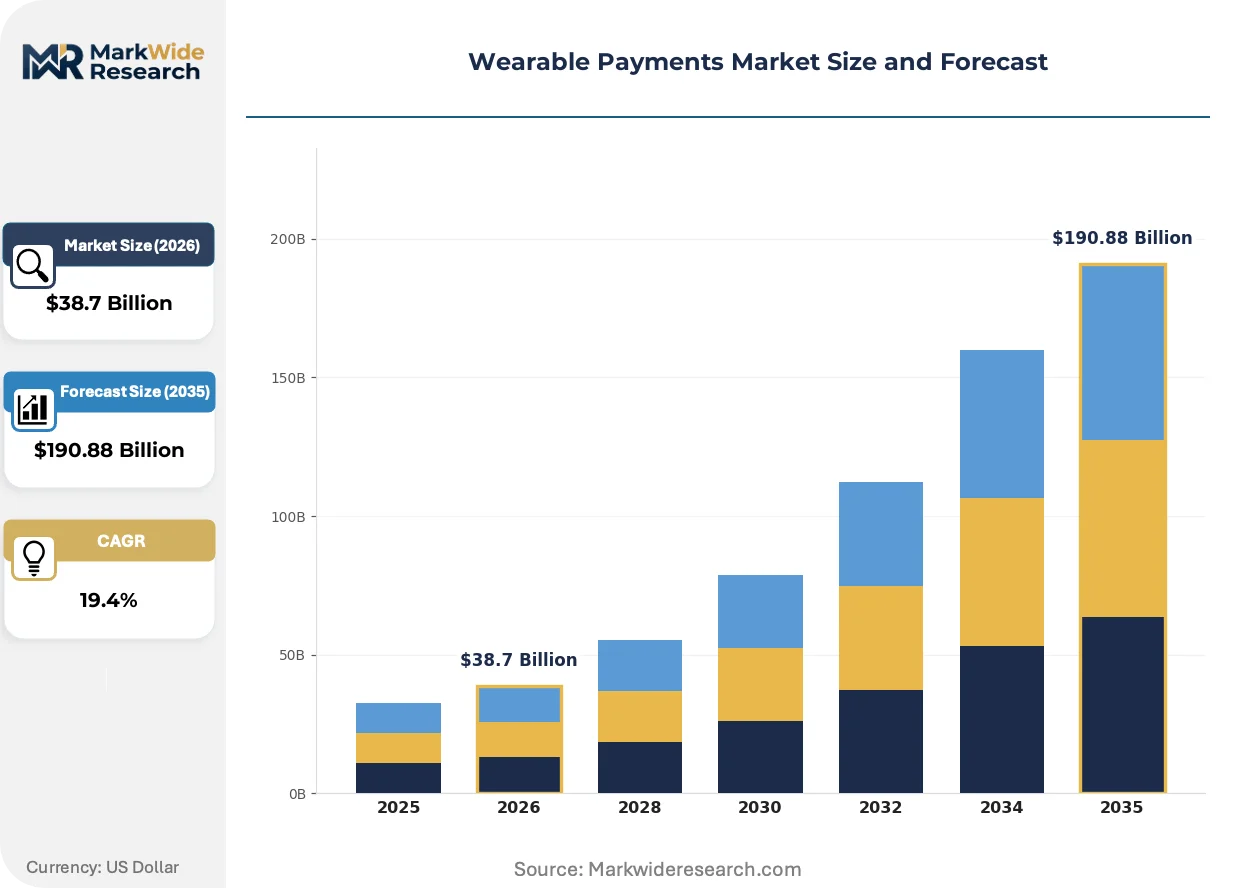
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Jewelry, Smart Glasses Technology: NFC, Bluetooth, RFID, Biometrics End User: Retail, Healthcare, Transportation, Entertainment Distribution Channel: Online, Offline, Third-Party Retailers, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics, Google LLC, Mastercard, Visa Inc., Garmin Ltd., Xiaomi Corporation, Barclays PLC, PayPal Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Payments Market Strategic Shifts
Payment credential architecture is fragmenting across multiple hardware security modules while transit authorities demand open-loop interoperability with closed-loop fare systems.
Biometric authentication is decentralizing transaction authorization from centralized token vaults to on-device secure elements. Transit operators in Tokyo and London are piloting vein-pattern verification for account-based fare collection. This architecture reduces network dependency for offline validation during subway tunnel passages.
The EU AI Act's risk classification for biometric identification systems is forcing wearable manufacturers to segregate payment authentication from health monitoring data streams. Device makers must maintain separate processing enclaves for financial credentials and physiological sensors. Premium smartwatch lines are absorbing compliance costs through hardware segmentation.
Transit authority procurement is consolidating terminal specifications across metropolitan networks, displacing fragmented municipal purchasing. New York MTA and Transport for London are harmonizing wearable acceptance standards through the Open Payment Framework. This concentration favors vendors with multi-city deployment experience over single-market specialists.
Wearable Payments Market Segmentation
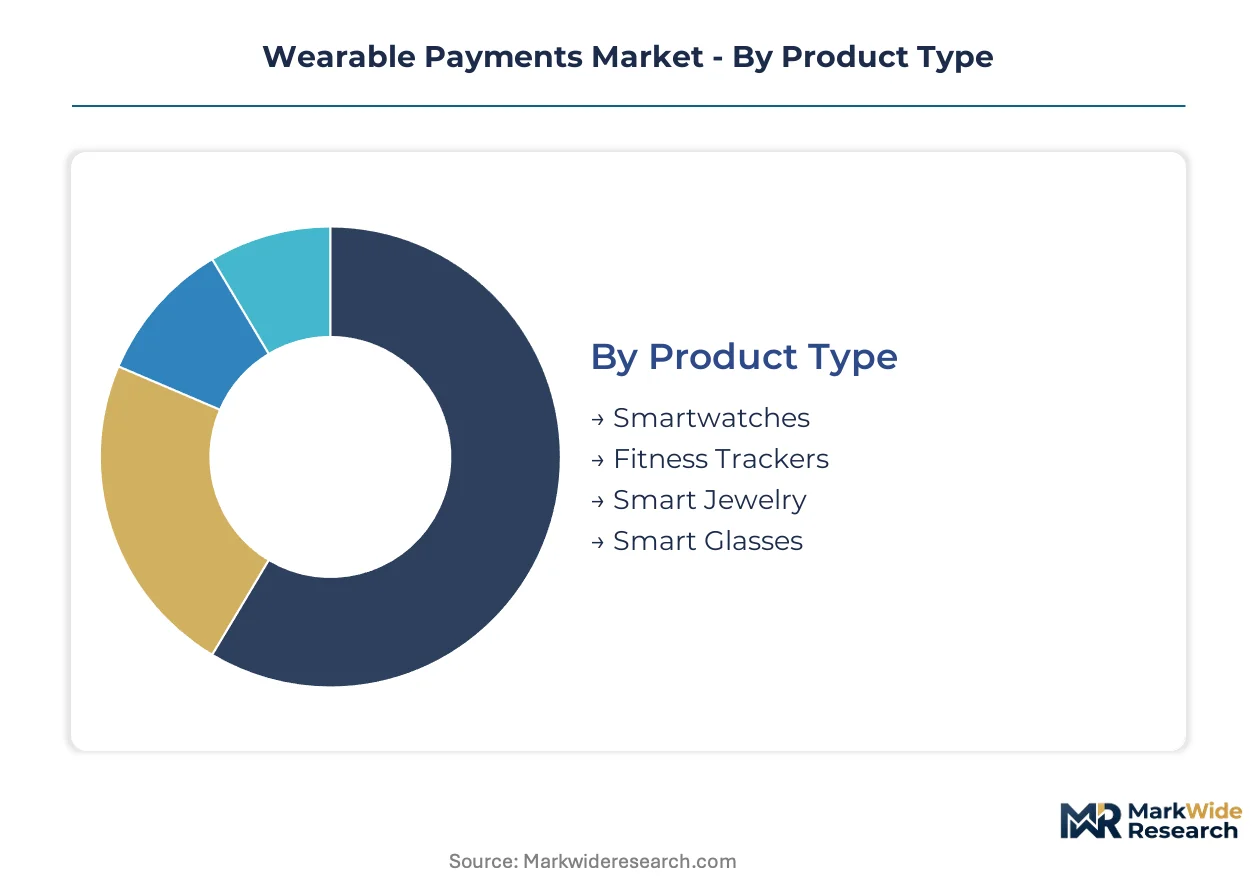
Wearable payment segmentation reveals how certification requirements fragment across form factors and connectivity standards. EMVCo and PCI SSC compliance timelines vary substantially by product architecture, creating tiered barriers to market entry.
Product Type:
Smartwatches and smart jewelry carry distinct certification burdens under EMVCo contactless kernel specifications, while fitness trackers face lighter NFC tokenization requirements. Smart glasses remain outside current PCI SSC guidance, creating regulatory ambiguity for payment-enabled optical wearables.
- Smartwatches:Multi-function wrist-worn devices integrate ISO 14443-compliant secure elements with biometric sensors. Demand concentrates in Seoul's T-money transit network and London's Open Payment Framework, where account-based fare collection rewards established device familiarity. EMVCo certification timelines extend 14-18 months for new manufacturers.
- Fitness Trackers:Health-focused wearables with payment modules use simplified token vault architectures. Procurement concentrates among transit authorities bundling wellness incentives with fare collection, particularly in Tokyo's pilot vein-pattern verification programs. These devices bypass full smartwatch certification through limited-transaction-amount protocols.
- Smart Jewelry:Precious metal form factors mask payment functionality for luxury retail channels. EMVCo compliance requires miniaturized secure elements that withstand plating and setting processes.
- Smart Glasses:Optical wearables with payment capability lack standardized certification pathways. PCI SSC has not issued specific guidance for head-mounted transaction interfaces.
Smartwatches sit at the top of the volume ranking, with smart jewelry climbing the fastest.
Technology:
Technology selection determines hardware cost tiers and merchant infrastructure compatibility. NFC anchors the installed base through sub-100 millisecond latency, while biometrics commands premium positioning through regulatory tailwinds.
- NFC:Near-field communication delivers sub-100 millisecond transaction latency using ISO 14443 RF interfaces. Demand concentrates in retail networks with existing contactless POS infrastructure, particularly where EMVCo tokenization has replaced primary account numbers with dynamic credentials.
- Biometrics:Vein-pattern recognition and cardiac rhythm verification enable offline transaction authorization within device secure elements. Procurement accelerates where EU Payment Services Directive II mandates strong customer authentication above contactless limits, favoring on-device sensor architectures over smartphone-dependent verification.
- Bluetooth:Extended-range connectivity supports wearable-to-terminal pairing for checkout scenarios beyond NFC proximity. Merchant acquirer integration complexity limits deployment.
- RFID:Passive identification technology enables closed-loop transit fare systems without active power management. T-money integration in South Korea demonstrates network viability.
NFC maintains dominant volume share, though biometrics gains share fastest through regulatory mandate alignment.
End User:
End-user segmentation tracks procurement authority concentration and transaction value thresholds. Transportation authorities consolidate terminal specifications across metropolitan networks, while retail fragmentation demands flexible integration pathways.
- Transportation:Transit authorities procure wearable payment terminals through consolidated specifications spanning multi-city deployments. New York MTA and Transport for London harmonize acceptance standards through the Open Payment Framework, favoring vendors with deployment experience across three or more metropolitan networks.
- Retail:Merchant chains and independent stores require wearable checkout integration without dedicated POS hardware. PayPal Holdings extends merchant network coverage by enabling smartphone-tethered transaction completion for small retailers lacking technical configuration resources.
- Healthcare:Medical facilities explore wearable payments for patient service transactions and pharmacy checkout. HIPAA compliance requirements complicate biometric data handling.
- Entertainment:Venues deploy wearable payments for concession and merchandise transactions. Seasonal demand patterns create procurement cyclicality.
Transportation commands the highest transaction volume, with retail expanding most quickly through independent merchant enablement.
Distribution Channel:
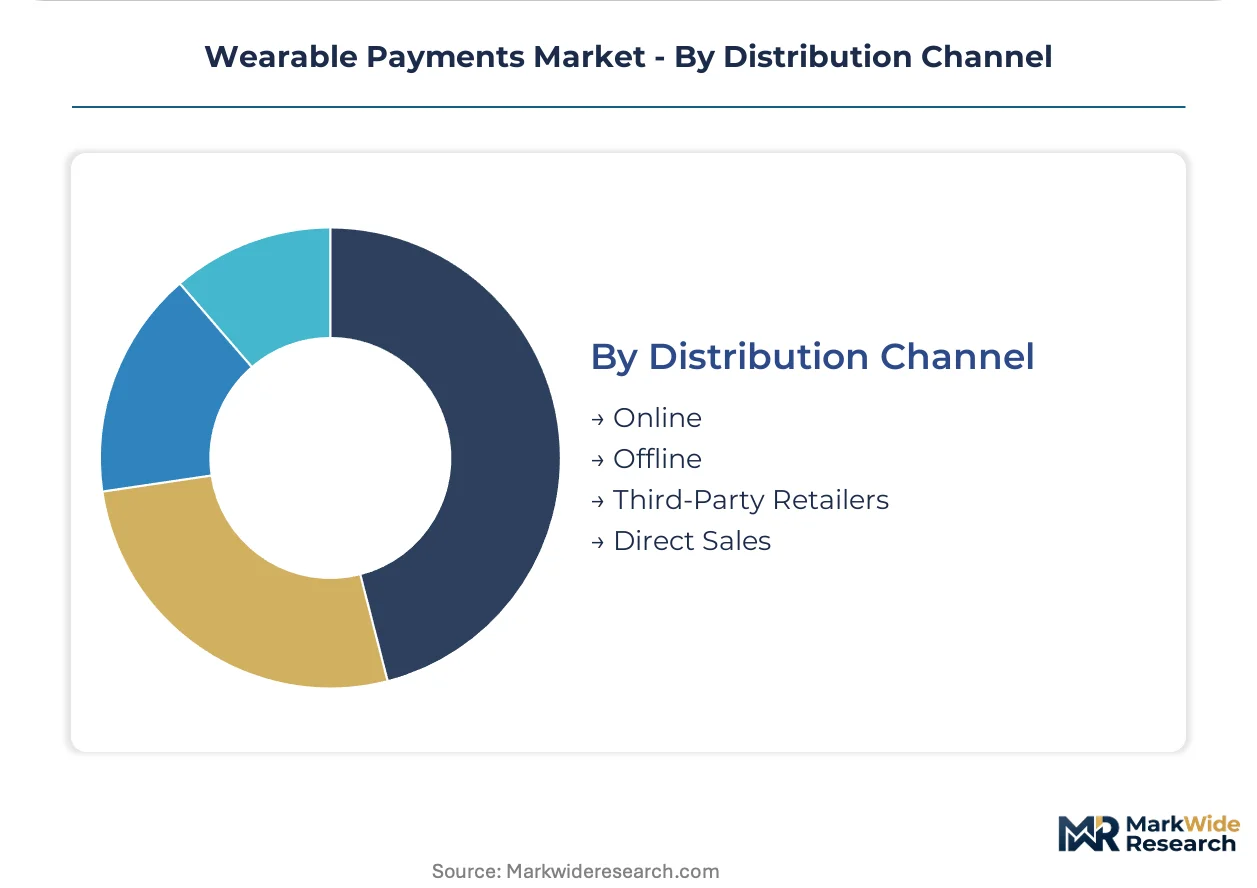
Channel structure reflects customer acquisition cost variation and technical support requirements. Direct sales capture enterprise procurement for transit authority deployments, while third-party retailers dominate consumer smartwatch distribution.
- Third-Party Retailers:Carrier channels and electronics retailers distribute Samsung Electronics smartwatches through Knox security architecture pre-certification. These partners bundle device activation with payment token provisioning, reducing consumer onboarding friction.
- Direct Sales:Apple Inc. controls token provisioning and device authentication through closed-loop ecosystem distribution. Enterprise procurement for transit authority terminal fleets runs through direct sales teams with multi-city deployment expertise.
- Online:E-commerce platforms enable smart jewelry penetration of luxury retail channels previously closed to technology products. Precious metal form factors require specialized photography and authentication services.
- Offline:Physical retail locations provide biometric sensor demonstration and fit verification. High-touch service justifies margin capture for premium wearable payment devices.
Third-party retailers lead volume distribution, with direct sales gaining fastest through transit authority procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's T-money transit integration outpaces Germany's retail contactless infrastructure, while India's National Common Mobility Card framework accelerates procurement timelines across metro networks.
South Korea
Seoul's metropolitan transit authority drives wearable payment volume through multimodal T-money integration spanning subway, bus, and taxi networks. The Financial Services Commission mandates biometric authentication for transactions exceeding contactless limits. Samsung Electronics anchors device supply from Suwon headquarters, leveraging Knox security architecture for token provisioning.
United States
New York MTA's Open Payment Framework harmonizes wearable acceptance standards with Transport for London, creating multi-city deployment demand. The Federal Reserve's Regulation E governs consumer liability protections for unauthorized transactions. Silicon Valley clusters concentrate secure element chip design, while Boston's transit authority pilots account-based fare collection.
India
The National Common Mobility Card framework creates procurement pathways across 25 metro rail networks in Delhi, Mumbai, and Bangalore. RBI mandates tokenization standards for wearable devices under payment and settlement regulations. Mumbai's suburban rail network integrates wearable terminals for 7.5 million daily commuters.
United Kingdom
Transport for London's contactless fare system processes wearable transactions across Underground, bus, and rail networks. The Financial Conduct Authority enforces Payment Services Directive II requirements for strong customer authentication. London's fintech cluster drives merchant acquirer integration for independent retailers.
Japan
Tokyo Metro pilots vein-pattern verification for account-based fare collection in subway tunnel environments. METI promotes NFC-F FeliCa standards for transit interoperability across JR East and private rail operators. Osaka's Kansai region extends wearable payment coverage to airport express services.
Wearable Payments Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and payment network layers. Apple Inc. and Samsung Electronics control device manufacturing through closed-loop ecosystems, while Mastercard and Visa Inc. govern token vault infrastructure. Strategic archetypes span ecosystem integrators, component suppliers, and merchant enablers. Competitive moves concentrate on transit authority procurement consolidation and biometric sensor integration partnerships.
Within the ecosystem integrator tier, Apple Inc. and Samsung Electronics occupy positions defined by secure element control and carrier channel distribution. PayPal Holdings Inc. exemplifies the merchant enablement archetype, extending network coverage to independent retailers lacking dedicated POS hardware. Google LLC represents the platform-layer competitor, leveraging Android distribution for wearable payment service integration. These three anchors illustrate how market structure rewards vertical control over token provisioning or horizontal reach across merchant categories.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Google LLC |
| Mastercard |
| Visa Inc. |
| Garmin Ltd. |
| Xiaomi Corporation |
| Barclays PLC |
| PayPal Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Secure element chip fabrication costs cascade through wearable payment terminal pricing tiers, with foundry capacity constraints in Taiwan and South Korea compressing margins for mid-tier smartwatch manufacturers while premium device makers absorb input volatility through hardware-software bundling.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for biometric-enabled wearables as Samsung Electronics expands Knox-certified production lines. Three-tier pricing structure across premium, standard, and economy levels separates EMVCo-certified devices with 14-18 month compliance timelines from simplified fitness tracker modules. Cost compression in the standard tier is intensifying because transit authority procurement consolidation forces bundled software service contracts. Transportation authorities exhibit lowest price sensitivity due to multi-city deployment mandates, while independent retailers face acute budget constraints without dedicated POS hardware support.
Supply Chain Analysis
EMVCo-certified secure element supply rests on Taiwanese and South Korean foundry output, with Dutch semiconductor equipment providers and Japanese substrate manufacturers feeding upstream tiers. Raw material dependencies span silicon wafers, gold wire bonding, and biometric sensor substrates. Single-source vulnerability concentrates in advanced node secure element production below 22 nanometers. Distribution runs through carrier channel partnerships for consumer smartwatches and direct enterprise sales for transit authority terminal fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable payments function as a stable compounder anchored by regulatory mandates for contactless transit modernization across metropolitan networks worldwide.
For Market Incumbents: Lock in transit authority procurement relationships through multi-city Open Payment Framework certifications before EMVCo compliance timelines extend further. Secure foundry allocation agreements in Taiwan and South Korea to defend against emerging fabless competitors. Vertical integration into biometric sensor design reduces dependency on external vein-pattern recognition module suppliers. For New Entrants and Emerging Players: The premium-to-economy price gap in smart jewelry opens white-space penetration of luxury retail channels previously closed to technology products. Target India's National Common Mobility Card framework across 25 metro rail networks where incumbent presence remains thin. Partner with PayPal Holdings' merchant enablement infrastructure to bypass independent retailer POS hardware configuration barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where EMVCo certification timelines extend 14-18 months and fabless wearable payment chip designers lack capital for compliance investment. Acquire specialist firms with existing contactless kernel approvals rather than funding de novo certification pathways. Watch for biometric data governance framework fragmentation between GDPR and emerging state-level US regulations as inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Investment | Accelerates market entry timelines for new device manufacturers competing against Apple and Samsung. |
| Transit Authority Partnership | Secures multi-city deployment contracts through Open Payment Framework harmonization with Transport for London. |
| Biometric Sensor Integration | Enables EU Payment Services Directive II compliance for transactions exceeding contactless limits. |
| Merchant Acquirer Integration | Extends network coverage to independent retailers lacking dedicated POS hardware configuration resources. |
| Foundry Capacity Allocation | Guarantees secure element chip supply from Taiwanese and South Korean semiconductor manufacturers. |
Study Parameters
Direct dialogue with transit authority procurement officers, wearable device engineering leads, merchant acquirer technical integration teams, and EMVCo certification consultants grounded qualitative findings. Secondary validation drew from PCI Security Standards Council publications, EMVCo specification documents, Federal Reserve Regulation E filings, and EU Payment Services Directive II implementation reports. Bottom-up smartwatch shipment estimates triangulated against top-down contactless transaction volume projections across Seoul, London, and New York metropolitan networks.
Segmentation outputs across product type, technology, end user, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical NFC adoption curves, biometric sensor cost reduction trajectories, and transit authority capital expenditure cycles. Industry-specific inputs included EMVCo certification queue lengths, secure element foundry utilization rates, and T-money integration deployment timelines.
Caveats apply where EMVCo certification timeline extensions, secure element supply disruptions, or biometric data governance framework fragmentation could materially shift the outlook. Forecasts embed assumptions regarding transit authority procurement consolidation continuity and NFC POS infrastructure upgrade rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Middle East Gift Card and Incentive Card Market
Payments
North America Mobile Payments Market
Payments
Contactless Payment Market
Payments
Credit Card Payments Market
Payments
Digital Payment Market
Payments
United States Mobile Payment Market
Payments
Mobile Point of Sale (POS) Market
Payments
Accelerator Card Market
Payments
Africa Mobile Money Market
Payments
China Real Time Payments Market
Payments
Digital Transfer Services Market
Payments
Mpos Terminals Market
Payments
APAC Mobile Payments Market
Payments
Transaction Monitoring Market
Payments
Saudi Arabia Payments Market
Payments
Croatia POS Terminals Market