
 Asia Pacific POS Terminal Market | 2026-2036
Asia Pacific POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific POS Terminal Market Outlook
Shenzhen is narrowing the gap between component sourcing and finished-device assembly for the regional POS terminal industry. PAX Technology Limited leverages its integrated manufacturing base to control cost structures across export markets. Fujian Newland Payment Technology Co., Ltd. anchors its position through specialized secure-module development. Shenzhen Xinguodu Technology Co., Ltd. competes aggressively on mobile POS form factors for emerging merchant segments.
Asia Pacific POS Terminal systems comprise electronic payment acceptance devices integrating card readers, near-field communication modules, and secure encryption processors to authenticate and process commercial transactions at the point of sale. These terminals employ EMV chip certification standards and PCI-DSS compliance architectures to protect cardholder data during transmission. Mobile POS and cloud-based POS configurations are expanding fastest as micro-merchants and food-service operators abandon fixed countertop infrastructure. NFC technology adoption within the technology dimension is displacing magnetic-stripe reliance as contactless payment volumes surge across urban transit and quick-service retail.
China's SAMR enforces GB standards for payment terminal electromagnetic compatibility and data security, while India's BIS mandates product certification for imported electronic payment devices. Japan's METI promotes cashless payment infrastructure through merchant subsidy programs that directly stimulate terminal procurement. Stakeholders must monitor how divergent national encryption standards and data-localization requirements reshape cross-border product strategies and certification budgets.
Market Dynamics
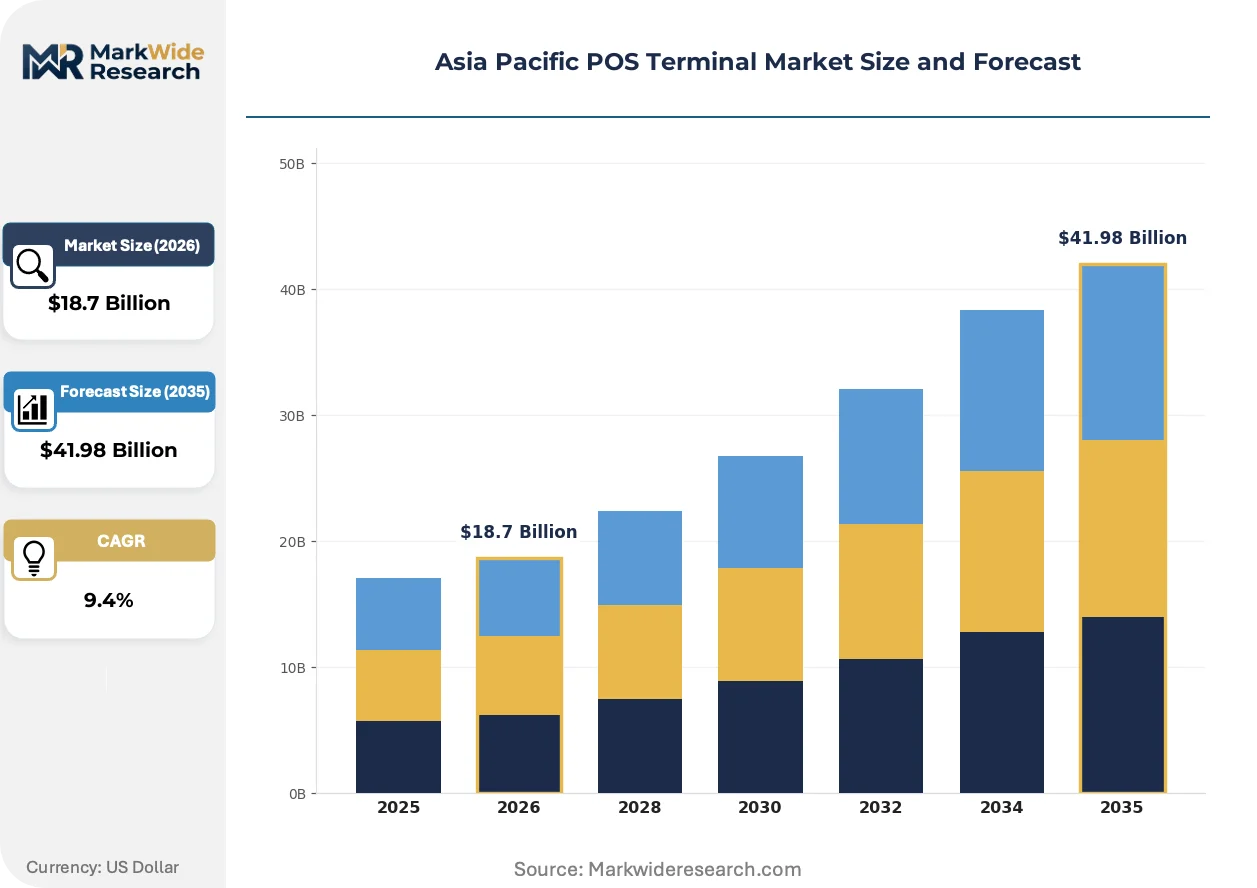
Contactless payment volumes are compressing hardware replacement cycles across Asia Pacific POS Terminal markets, forcing manufacturers to accelerate EMV and NFC certification pipelines while absorbing tighter margin structures.
Growth Catalysts
- Merchant subsidy frameworks:Japan's METI cashless payment infrastructure programs directly stimulate terminal procurement across small retail and food-service operators. Merchant enrollment drives hardware refresh demand.
- Biometric authentication modules:Fingerprint and facial recognition integration is expanding payment security layers for high-transit-volume environments. Transit authorities in Singapore and Hong Kong deploy these configurations.
- Cloud-native architectures:Software-as-a-service POS platforms reduce upfront capital barriers for micro-merchants across Indonesia and Vietnam. Subscription models accelerate merchant acquisition.
Market Restraints
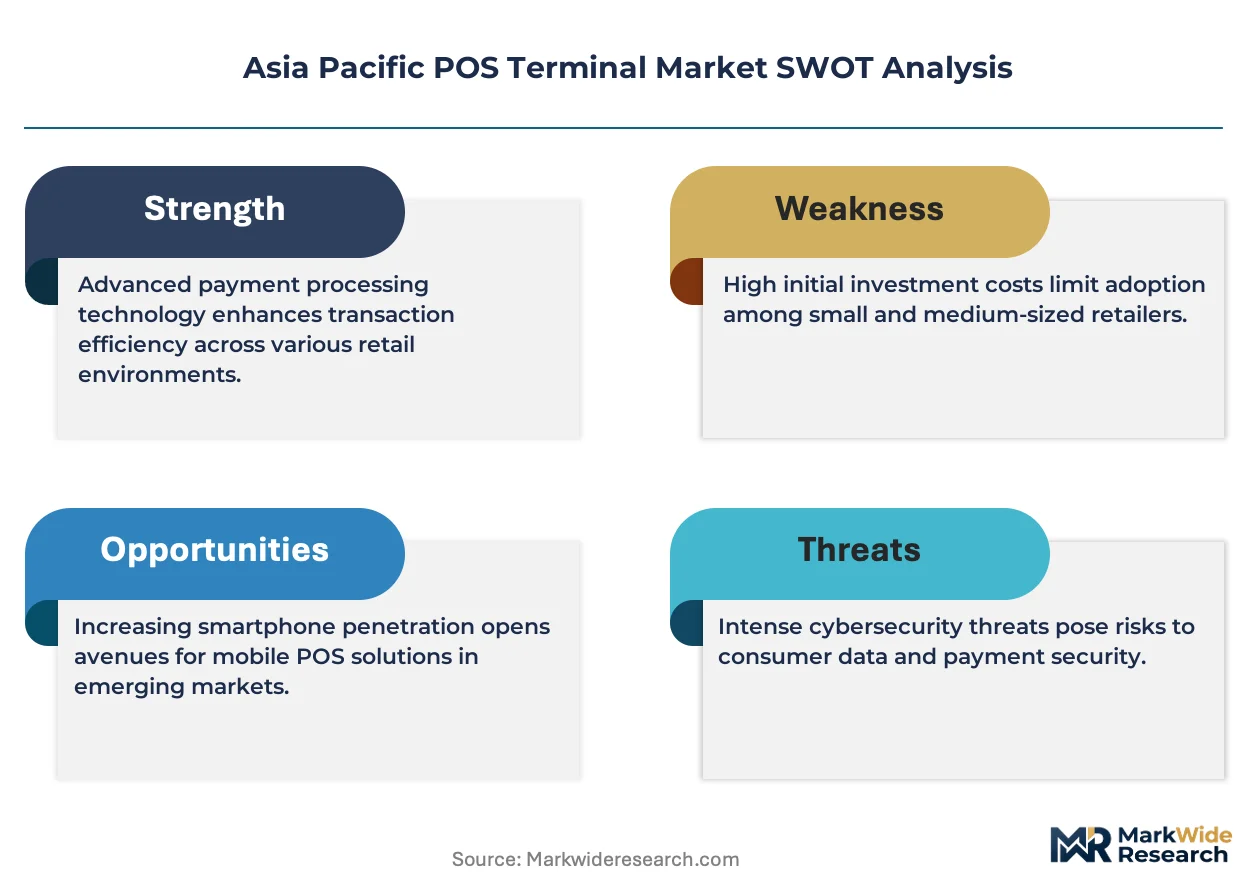
- Secure element supply concentration:EMV chip and cryptographic processor sourcing concentrates among a limited set of semiconductor foundries. Foundry capacity constraints create procurement bottlenecks.
- Input cost volatility:Memory component and display panel pricing fluctuations compress hardware margins for terminal assemblers. Shenzhen manufacturing clusters absorb these swings.
- Regulatory fragmentation:Divergent national encryption standards across China, India, and Southeast Asian markets multiply certification costs. SAMR GB standards, BIS mandates, and country-specific data-localization rules create compliance friction.
Strategic Opportunities
- Underpenetrated rural India:Tier-3 and Tier-4 urban centers remain underserved by formal payment infrastructure. Jan Dhan Yojana-linked merchant accounts create addressable merchant bases.
- SoftPOS technology convergence:Near-field communication modules and tokenization protocols enable smartphone-based acceptance without dedicated hardware. Food delivery platforms and gig-economy workers adopt these configurations.
- Cross-border payment corridors:ASEAN economic integration and RCEP tariff structures facilitate regional terminal standardization. Harmonized certification pathways reduce market entry costs.
Industry Challenges
- EMV certification timelines:Laboratory testing queues and documentation requirements extend product launch windows. Certification backlogs delay revenue recognition.
- Legacy system integration:Established retail chains operate proprietary settlement architectures that resist cloud-POS migration. Middleware development consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific POS Terminal Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Countertop POS, Self-service Kiosks, Cloud-based POS End User: Retail, Hospitality, Healthcare, Transportation Technology: Card Reader, NFC, Bluetooth, EMV Chip Installation: On-premises, Cloud-based, Hybrid, Remote |
| Companies Covered | Fujian Newland Payment Technology Co., Ltd., PAX Technology Limited, Ingenico Group (WorldLine), VeriFone, Inc., NCR Corporation, Shenzhen Xinguodu Technology Co., Ltd., Beijing Shenzhou Anfu Technology Co. Ltd., Fujian Centerm Information Co., Ltd., Shenzhen Itron Electronics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific POS Terminal Market Strategic Shifts
Hardware commoditization is pushing Asia Pacific POS Terminal value creation toward software layers and payment-network integration, compressing standalone device economics while expanding recurring revenue pools.
Android-based operating systems are migrating from niche mobile-POS segments toward mainstream countertop and portable terminal categories. Mid-market retail chains in Thailand and Malaysia favor these open-platform configurations for application flexibility. The shift is migrating from proprietary embedded systems toward standardized OS environments that reduce development fragmentation.
India's BIS certification mandates for imported electronic payment devices are tightening electromagnetic compatibility and data-security testing protocols. Domestic assembly requirements and local-value-add thresholds are reshaping supply chain configurations. Importers are responding by establishing certified manufacturing facilities within Indian special economic zones.
Food-service operators are unbundling after-sales service contracts from hardware procurement, purchasing terminal maintenance through independent software vendors rather than original equipment manufacturers. This procurement pattern shift compresses OEM service revenue while expanding third-party managed-service opportunities. The trend is most visible across quick-service restaurant chains in South Korea and Australia.
Asia Pacific POS Terminal Market Segmentation
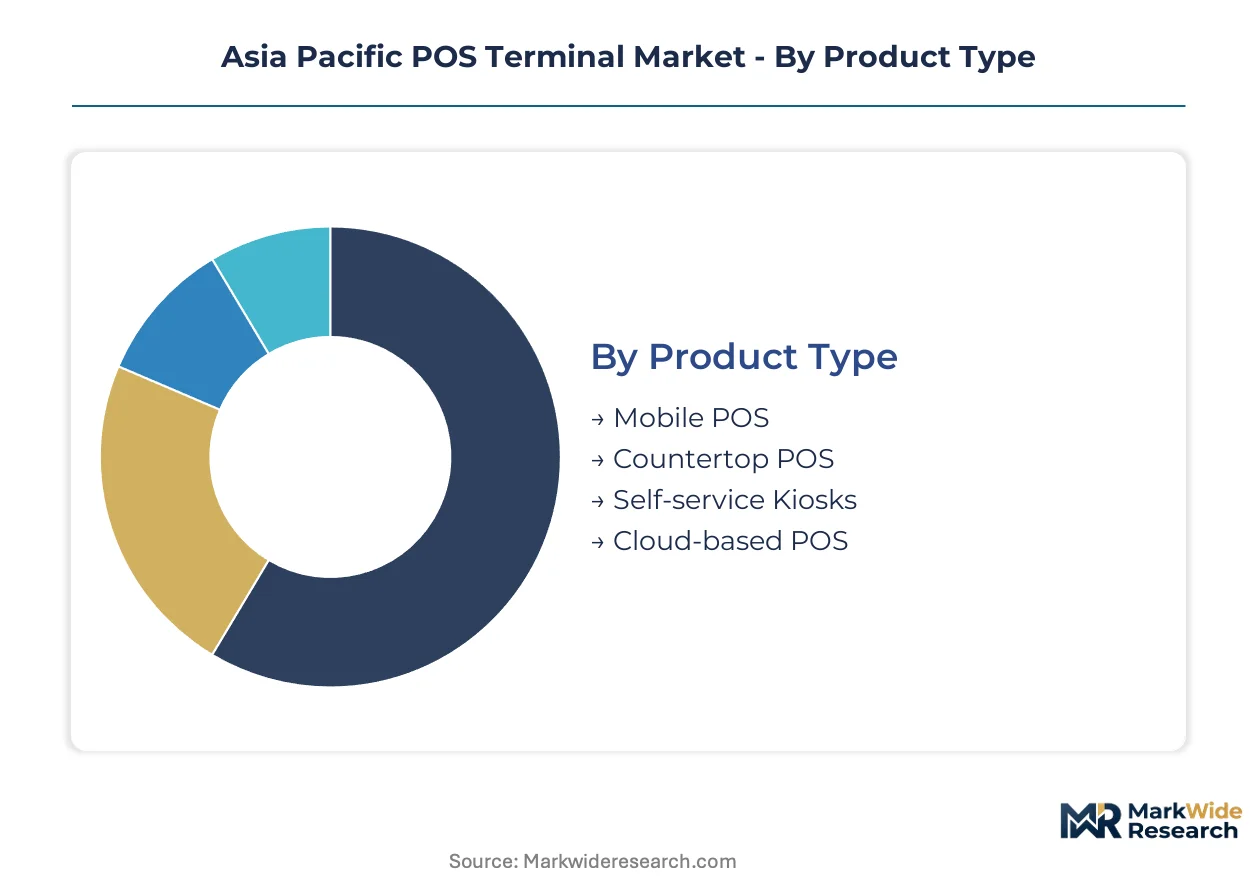
POS terminal segmentation across Asia Pacific reflects divergent merchant sophistication levels and regulatory maturity across national markets. Hardware configurations and deployment architectures cluster around specific compliance frameworks and infrastructure readiness.
Product Type:
Mature countertop installations coexist with emerging form factors as merchant segments stratify by transaction volume and mobility requirements.
- Countertop POS:Fixed-location terminals integrate EMV chip readers, PIN pads, and receipt printers for high-volume retail environments. Department stores in Shanghai and Bangkok deploy these units for checkout lane standardization under SAMR and local banking authority mandates.
- Mobile POS:Battery-powered handheld units connect via cellular or Wi-Fi networks to process payments at tableside or pop-up locations. Street vendors and food trucks across Jakarta and Manila adopt these configurations to bypass fixed infrastructure costs.
- Self-service Kiosks:Interactive touchscreen terminals enable unassisted ordering and payment in quick-service environments.
- Cloud-based POS:Software-centric platforms run on generic tablets with peripheral card readers attached.
Countertop POS retains volume leadership; Mobile POS holds the steepest expansion curve.
End User:
Customer-type segmentation tracks payment acceptance penetration across sector-specific regulatory and operational environments.
- Retail:Supermarkets, convenience chains, and specialty stores operate multi-lane checkout systems with inventory integration requirements. India's BIS-certified terminals dominate procurement for formal sector merchants under RBI payment aggregator guidelines.
- Hospitality:Restaurants, hotels, and entertainment venues require split-payment functionality and tip-adjustment capabilities. Japan's METI subsidy programs accelerate terminal deployment across ryokan and izakaya establishments transitioning from cash-dominant operations.
- Healthcare:Clinics and pharmacies prioritize HIPAA-aligned data handling and insurance claim integration.
- Transportation:Transit authorities mandate millisecond transaction speeds for fare gates and onboard systems.
Retail commands the largest installed base; Transportation is climbing the fastest as contactless fare collection expands.
Technology:
Technology layers stack from legacy magnetic-stripe compatibility through contactless protocols and cryptographic authentication modules.
- EMV Chip:Embedded secure elements store encrypted card credentials to prevent counterfeit fraud. China's GB standards mandate EMV compliance for all domestic payment terminals, driving foundry capacity allocation toward cryptographic processor production.
- NFC:Near-field communication enables tap-to-pay transactions under 500 milliseconds for transit and quick-service applications. Singapore's LTA and Hong Kong's MTR deploy NFC-enabled terminals across rail networks and retail concessions.
- Card Reader:Magnetic-stripe and chip-card hybrid slots persist for backward compatibility.
- Bluetooth:Short-range wireless connects peripheral PIN pads and receipt printers to host devices.
EMV Chip dominates certification pipelines; NFC is gaining share fastest as contactless volume thresholds accelerate hardware refresh cycles.
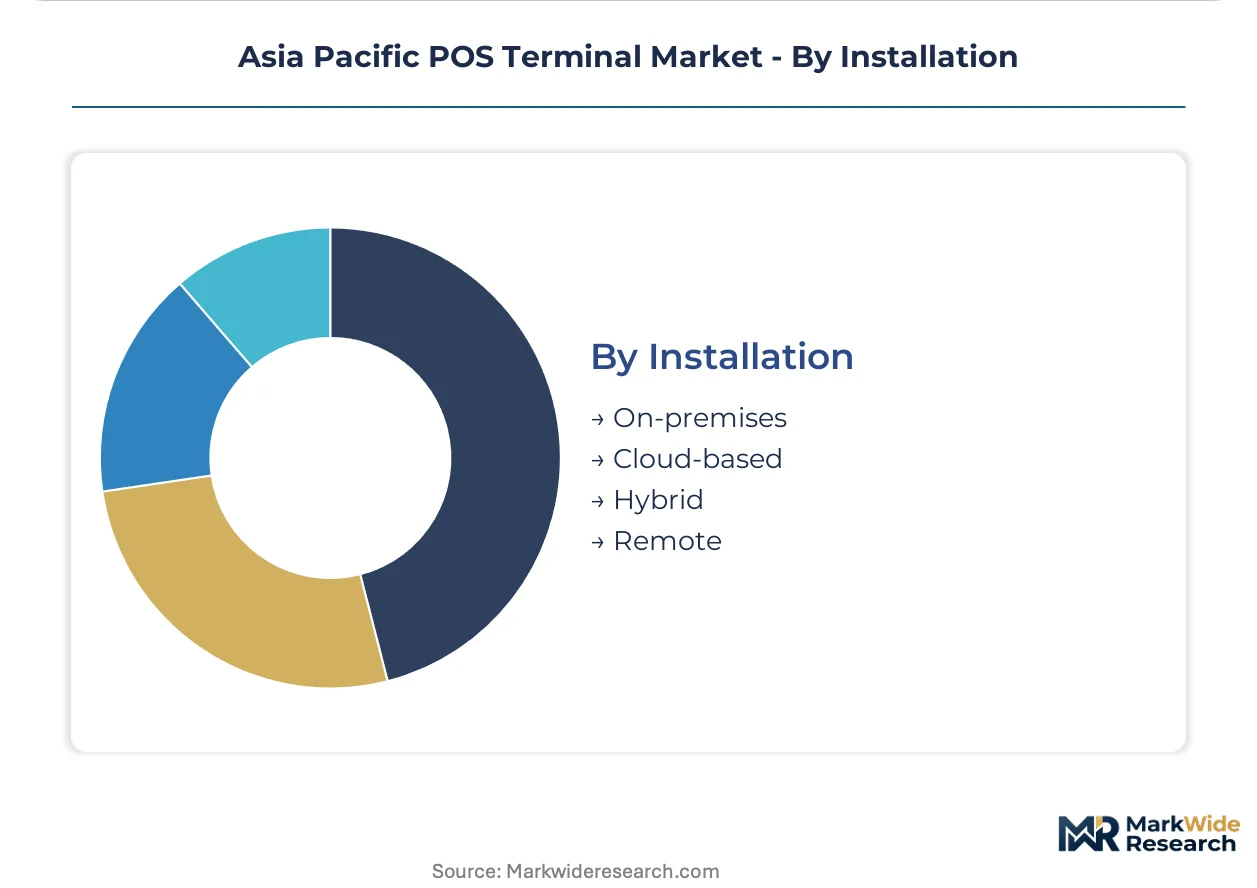
Installation:
Deployment architecture selection hinges on data sovereignty requirements and merchant IT resource availability.
- Cloud-based:Subscription software platforms centralize transaction processing and analytics on remote servers. Vietnamese and Indonesian micro-merchants favor these configurations for zero upfront capital requirements and automatic compliance updates.
- On-premises:Local server installations retain transaction data within merchant-controlled environments. South Korean and Australian mid-market chains deploy these systems to satisfy internal audit protocols and legacy ERP integration demands.
- Hybrid:Split architectures process sensitive authentication locally while routing settlement data to cloud endpoints.
- Remote:Fully distributed configurations enable centralized management of geographically dispersed terminal fleets.
On-premises retains volume leadership among established chains; Cloud-based is expanding most quickly across emerging merchant segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Shenzhen and Guangzhou supply cryptographic processors and secure modules to terminal assemblers across the region. India's BIS certification mandates and Japan's METI subsidy programs are reshaping procurement patterns and supply chain configurations.
China
Shenzhen manufacturing clusters integrate EMV chip sourcing with finished-device assembly for export markets. SAMR enforces GB standards for electromagnetic compatibility and data security across all domestic payment terminals. Guangzhou-based foundries allocate capacity toward cryptographic processor production to meet certification pipelines.
India
Jan Dhan Yojana-linked merchant accounts in Tier-3 and Tier-4 urban centers create addressable bases for terminal deployment. BIS mandates tighten electromagnetic compatibility testing for imported electronic payment devices. Domestic assembly requirements are pushing importers to establish certified manufacturing facilities within Indian special economic zones.
Japan
METI cashless payment infrastructure programs directly stimulate terminal procurement across small retail and food-service operators. Merchant enrollment drives hardware refresh demand across ryokan and izakaya establishments transitioning from cash-dominant operations. Tokyo-based payment networks coordinate subsidy distribution to accelerate contactless adoption.
South Korea
Mid-market retail chains favor cloud-native POS platforms with legacy ERP integration capabilities. Domestic audit protocols retain transaction data within merchant-controlled environments. Seoul Capital Area hosts food-service operators unbundling after-sales service contracts from hardware procurement.
Singapore
Transit authorities deploy NFC-enabled terminals across rail networks and retail concessions for sub-500 millisecond transaction speeds. LTA specifications drive contactless fare collection expansion. The city-state's financial district concentrates merchant demand for biometric authentication modules in high-transit-volume environments.
Asia Pacific POS Terminal Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying secure modules and cryptographic processors. The vendor base stratifies between scale-driven manufacturers with integrated production and niche specialists focused on mobile form factors. Three archetypes dominate: Shenzhen-based integrated assemblers, secure-module developers, and cloud-native platform providers. Capacity expansion and strategic partnerships constitute the primary competitive moves as certification backlogs compress launch windows.
Among China-based fabricators, PAX Technology Limited and Shenzhen Xinguodu Technology Co., Ltd. exemplify the integrated assembler archetype, while Fujian Newland Payment Technology Co., Ltd. occupies a position within the secure-module specialist tier. These entities anchor the regional supply structure through distinct capability concentrations rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Fujian Newland Payment Technology Co., Ltd. |
| PAX Technology Limited |
| Ingenico Group (WorldLine) |
| VeriFone, Inc. |
| NCR Corporation |
| Shenzhen Xinguodu Technology Co., Ltd. |
| Beijing Shenzhou Anfu Technology Co. Ltd. |
| Fujian Centerm Information Co., Ltd. |
| Shenzhen Itron Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Regulatory fragmentation across SAMR GB standards, India's BIS mandates, and Japan's METI frameworks compresses margin structures while forcing certification cost allocation into tiered pricing architectures. Terminal assemblers in Shenzhen manufacturing clusters absorb input cost volatility through backward integration into cryptographic processor sourcing, creating pricing spreads between certified and non-certified product tiers.
Pricing Analysis
India's BIS certification mandates dictate the pricing tier structure across the Asia Pacific POS Terminal Market. Three-tier pricing structure across premium, standard, and economy levels separates EMV-certified terminals with full cryptographic compliance from basic mobile-POS units lacking secure-element integration. Cost compression in economy-tier mobile configurations is intensifying because memory component and display panel pricing fluctuations erode assembler margins. Micro-merchants in Indonesia and Vietnam exhibit highest price sensitivity, while Japanese hospitality operators under METI subsidy programs demonstrate lowest sensitivity due to direct procurement support.
Supply Chain Analysis
Cryptographic processors and EMV secure elements feed from semiconductor foundries concentrated in Taiwan, South Korea, and China. Terminal assembly draws from Shenzhen and Guangzhou manufacturing clusters for component integration and finished-device production. Single-source vulnerability concentrates in secure-element supply, where limited foundry capacity creates procurement bottlenecks. Distribution runs through OEM direct sales for large retail chains, independent software vendors for cloud-POS platforms, and regional distributors for micro-merchant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SoftPOS technology convergence represents a substitution threat that hardware incumbents must neutralize through platform integration and service-layer value capture.
For Market Incumbents: Harden cloud-native platform capabilities to defend against smartphone-based acceptance technologies that eliminate dedicated hardware requirements. Deepen backward integration into secure-module production to control cryptographic processor allocation during foundry capacity constraints. Prioritize certification pipeline investment to compress EMV laboratory testing queues that delay revenue recognition. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-3 and Tier-4 urban centers where Jan Dhan Yojana-linked merchant accounts remain underserved by formal payment infrastructure. Target cloud-POS subscription models for Vietnamese and Indonesian micro-merchants seeking zero upfront capital deployment. Pursue partnership pathways with food delivery platforms seeking integrated payment acceptance for gig-economy worker fleets. For Investors and Strategic Acquirers: India's BIS domestic assembly requirements reshape the acquisition landscape toward certified manufacturing facilities within Indian special economic zones. Long-term viability across the projection horizon rests on positioning for ASEAN economic integration and RCEP tariff harmonization that facilitates regional terminal standardization. Monitor cross-border payment corridor development as the signal indicating accelerated regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Module Backward Integration | Cryptographic processor captive supply insulates PAX Technology and Fujian Newland from foundry allocation constraints. |
| Cloud-Native Platform Migration | Android-based open-platform configurations reduce development fragmentation for Thailand and Malaysia mid-market retail chains. |
| BIS Certification Facility Establishment | Domestic assembly within Indian special economic zones satisfies local-value-add thresholds for imported electronic payment devices. |
| SoftPOS Technology Convergence | NFC module and tokenization protocol integration enables smartphone-based acceptance without dedicated hardware deployment. |
| Cross-Border Corridor Standardization | ASEAN economic integration and RCEP tariff structures reduce market entry costs through harmonized certification pathways. |
Study Parameters
Initial hypotheses were tested against primary input from terminal OEM procurement directors, payment network compliance officers, semiconductor foundry account managers, and micro-merchant platform operators and refined through secondary validation. Bottom-up and top-down triangulation combined SEC filings from publicly traded terminal manufacturers, SAMR GB standard documentation, BIS certification registries, and METI subsidy distribution records with customs data tracking component flows through Shenzhen and Guangzhou ports.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user sector, technology layer, and installation architecture alongside regional regulatory cluster differentiation. CAGRs were derived through installed base replacement cycle analysis and merchant enrollment trajectory assessment. Forecast inputs incorporated contactless payment volume thresholds accelerating hardware refresh cycles and cloud-POS subscription adoption curves across emerging merchant segments.
Stress conditions across secure-element foundry capacity allocation, memory component pricing bands, and regulatory certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMV laboratory queue durations and METI subsidy program continuity. Material shifts in India's domestic assembly requirement thresholds or ASEAN tariff harmonization schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Saudi Arabia POS Terminal Market
Payments
Global Utility Billing Software Market
Payments
Japan Credit Cards Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Forex Prepaid Cards Market
Payments
France Payments Market
Payments
B2B Payments Market
Payments
Consumer Mobile Payment Market
Payments
P2P Payment Market
Payments
Hungary POS Terminal Market
Payments
Indonesia Payments Infrastructure Market
Payments
Saudi Arabia Payment Gateway Market
Payments
United States Payment Gateways Market
Payments
Cash Management System Market
Payments
Global Accounts Payable Software Market
Payments
Subscription Billing Management Market