
 Nigeria Mobile Money Market | 2026-2036
Nigeria Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Mobile Money Market Intelligence
Agent banking networks across Nigeria's northern and southwestern corridors is reconfiguring last-mile financial access. OPay leverages its extensive agent footprint to dominate cash-in/cash-out liquidity in urban centers. Moniepoint anchors merchant payment acceptance through point-of-sale hardware and software integration. Paga competes through sustained investment in agent training and rural network density.
Nigeria mobile money encompasses digital financial services delivered via mobile devices, enabling fund storage, transfer, and payment execution through encrypted communication protocols on GSM and data networks. The system relies on SIM toolkit applications, unstructured supplementary service data sessions, and internet-connected mobile applications to authenticate users and settle transactions in real time. Wallet services and payment solutions lead transaction volume due to everyday peer-to-peer transfers and merchant settlement needs. Microloans represent the fastest-growing segment as alternative credit scoring from transaction history displaces traditional collateral requirements. USSD technology occupies the largest user base among connectivity modes, while mobile apps capture higher-value transactions from smartphone-enabled demographics.
The Central Bank of Nigeria governs licensing, capital adequacy, and consumer protection through its Payments System Management Department, while the Nigeria Communications Commission regulates telecom infrastructure underpinning mobile money channels. Tiered KYC requirements from the CBN expand financial inclusion by permitting limited-value accounts with reduced documentation. Stakeholders must monitor interoperability mandates and evolving agent commission structures to anticipate margin compression and partnership realignments.
Market Dynamics
The Central Bank of Nigeria's tiered KYC framework is compressing account-opening friction while expanding addressable populations beyond traditional banking coverage, creating simultaneous volume expansion and margin pressure across agent networks.
Growth Catalysts
- Agent Banking Guidelines:The CBN's regulatory framework permits non-bank entities to perform cash-in/cash-out services, extending financial access into rural corridors previously excluded from formal banking infrastructure.
- Small Business Digital Migration:Merchants in Lagos and Kano trade zones are abandoning cash acceptance for QR-code and USSD settlement, generating recurring transaction fee pools for platform operators.
- Alternative Credit Scoring:Transaction history analytics from wallet usage is displacing traditional collateral requirements, enabling microloan origination at scale for underbanked demographics.
Market Restraints
- Telecom Infrastructure Concentration:GSM network reliability gaps in northern Nigeria create settlement failure risks during peak agricultural trading periods.
- Agent Liquidity Constraints:Cash float management absorbs working capital that informal agents often cannot access through formal credit channels.
- Interoperability Mandates:CBN directives requiring cross-platform transaction compatibility compress proprietary network advantages and standardize commission structures.
Strategic Opportunities
- Rural Northern Corridors:Kano and surrounding states exhibit dense agricultural commerce with minimal banking penetration, creating first-mover advantages for agent network builders.
- Microloan Integration:Embedded lending within wallet interfaces captures interest income streams while deepening user engagement beyond pure payment functionality.
- API Banking Convergence:Mobile money platforms connecting with accounting software and inventory management systems are capturing merchant ecosystem lock-in.
Industry Challenges
- Agent Training and Retention:High churn among commission-based agents degrades service consistency and increases recruitment costs for network operators.
- Fraud Detection Systems:Real-time transaction monitoring requires capital investment in machine learning infrastructure that smaller licensees struggle to fund.
- Legacy Bank Integration:Settlement delays between mobile wallets and traditional banking rails create liquidity mismatches during high-volume periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Mobile Money Market |
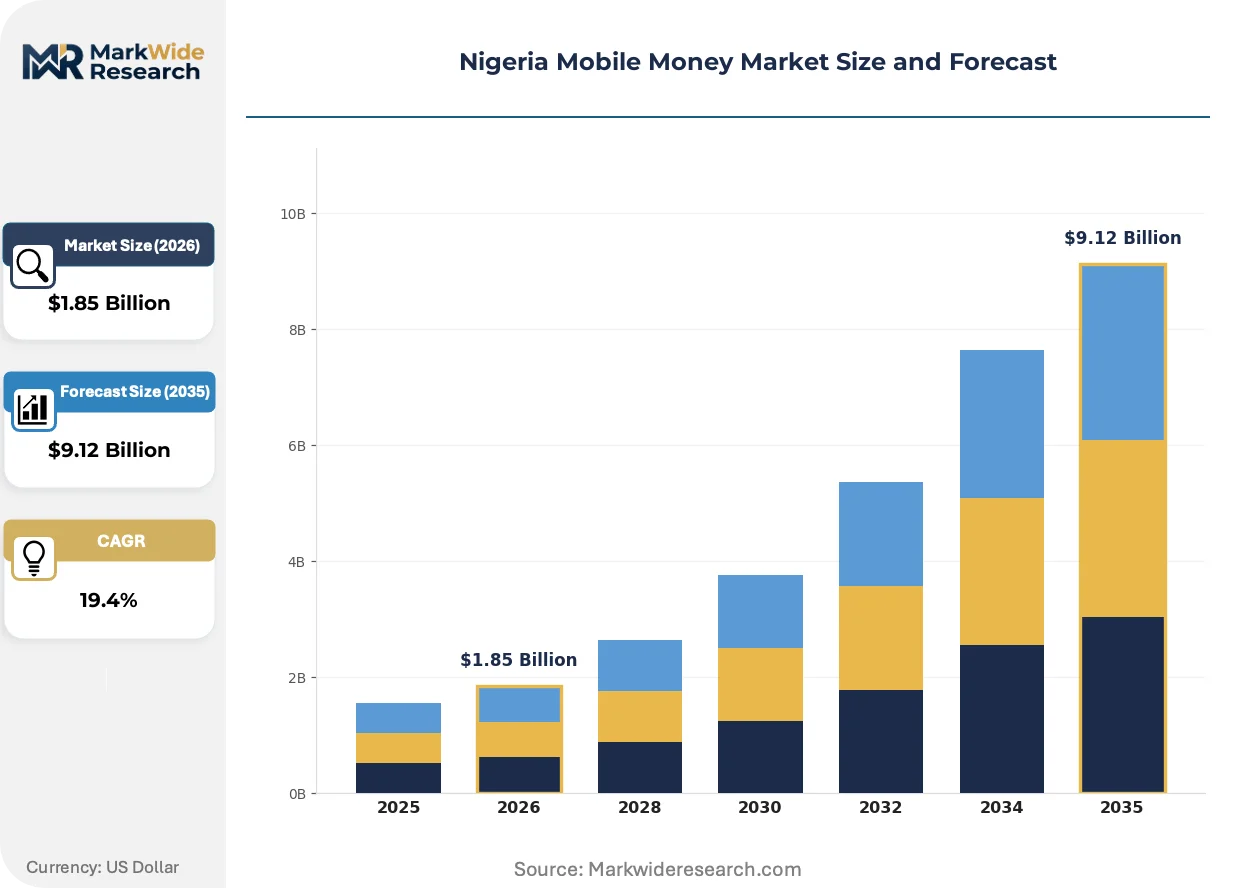
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $9.12 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wallet Services, Payment Solutions, Remittances, Microloans Customer Type: Retail Consumers, Small Businesses, Enterprises, Government Technology: USSD, QR Code, Mobile Apps, NFC End User: Urban Users, Rural Users, Youth, Senior Citizens |
| Companies Covered | Interswitch, Flutterwave, OPay, FairMoney, Paystack, Moniepoint, Paga, Nomba, PalmPay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Mobile Money Market Strategic Shifts & Innovations
Mobile money infrastructure in Nigeria is fragmenting across connectivity modes as smartphone penetration diverges from feature-phone dependence, forcing platform architectures to serve dual user bases simultaneously.
Biometric authentication layered atop USSD sessions is hybridizing security protocols for feature-phone users without requiring smartphone hardware. Rural agents and agricultural traders in northern states are adopting fingerprint-verified transactions fastest, as cash-handling risks exceed technology learning curves. This convergence is compressing fraud rates while extending service reach into demographics previously excluded by password complexity.
The Central Bank of Nigeria's Payments System Management Department has tightened capital adequacy buffers for mobile money operators, forcing balance sheet restructuring among mid-tier licensees. Tier-1 players with deeper equity reserves are absorbing compliance costs while smaller entrants face consolidation pressure. Lagos-based operators with diversified revenue streams are responding fastest through microloan and savings product expansion.
Merchant procurement of payment acceptance tools is rotating from hardware-heavy POS terminals toward software-embedded QR solutions. Small traders in urban markets are abandoning monthly rental contracts for commission-only settlement models, shifting vendor revenue from fixed fees to transaction volume shares. This behavioral pivot is most visible among informal sector participants in southwestern commercial corridors where smartphone penetration enables code-based acceptance.
Nigeria Mobile Money Market Segmentation
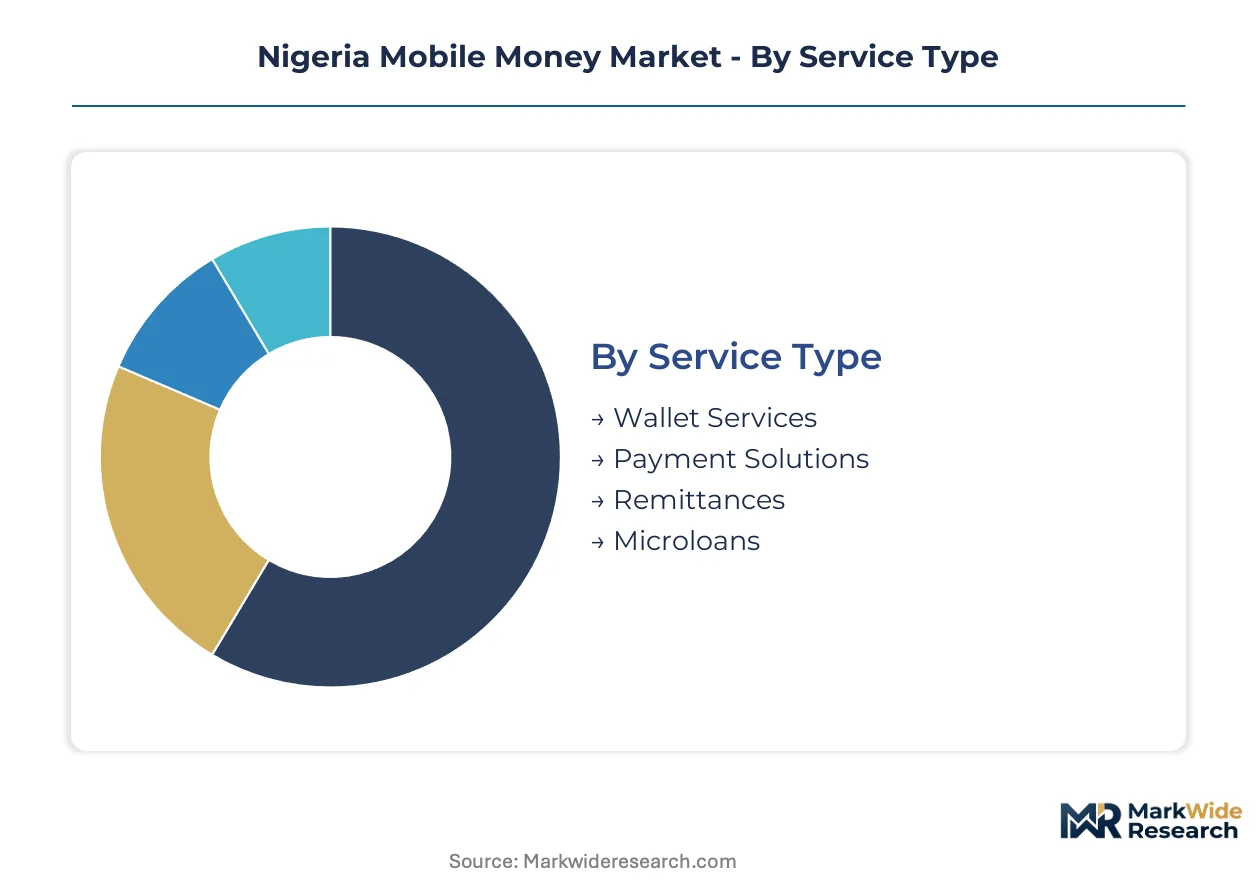
Nigeria's mobile money architecture fragments across four intersecting dimensions that determine platform design, commission structures, and regulatory treatment. Understanding these segment boundaries clarifies why USSD dominates rural penetration while mobile apps capture urban transaction value, and why wallet services anchor volume while microloans drive margin expansion.
Service Type:
The use-case spectrum spans everyday liquidity management through formal credit origination, with each service tier demanding distinct capital reserves and partnership structures.
- Wallet Services:Digital storage and balance maintenance functions enable peer-to-peer transfers and merchant settlement through encrypted mobile interfaces. Demand concentrates among Lagos traders and Kano market operators where cash-handling risks exceed technology adoption friction, driven by Central Bank tiered KYC rules that permit limited-value accounts with minimal documentation.
- Payment Solutions:Merchant acceptance infrastructure processes QR-code and USSD settlement for retail transactions, integrating with inventory systems through API connections. Small businesses in southwestern commercial corridors are abandoning cash for digital settlement, generating recurring fee pools for platform operators while compressing hardware rental revenue.
- Remittances:Cross-border fund transfers connect diaspora senders with domestic recipients through licensed corridors.
- Microloans:Embedded credit origination leverages transaction history analytics to displace traditional collateral requirements for underbanked borrowers.
The dominant share belongs to Wallet Services, while Microloans is closing the gap fastest.
Customer Type:
Customer segmentation follows documentation capacity and transaction scale, with regulatory treatment varying by capital reserves and compliance infrastructure.
- Retail Consumers:Individual users executing peer-to-peer transfers, bill payments, and merchant purchases through mobile interfaces. Northern agricultural communities and urban informal workers in Lagos represent the densest adoption clusters, where agent banking networks substitute for absent branch infrastructure.
- Small Businesses:Informal sector merchants and microenterprises accepting digital payments and managing working capital through integrated wallet and accounting tools. Kano trading zones and southwestern market corridors exhibit the steepest migration from cash acceptance, driven by Central Bank agent banking guidelines that permit non-bank cash-in/cash-out services.
- Enterprises:Formal sector organizations with treasury management needs and bulk disbursement requirements.
- Government:Public sector entities distributing social transfers and collecting revenue through mobile rails.
Retail Consumers command the largest user base, though Small Businesses is expanding most quickly as merchant acceptance spreads.
Technology:
Connectivity mode selection shapes security architecture, transaction limits, and addressable population reach.
- USSD:Session-based communication protocols enable feature-phone access through unstructured supplementary service data menus without internet connectivity. Rural northern corridors and agricultural trading periods depend on GSM network reliability, constrained by infrastructure gaps that create settlement failure risks during peak commerce windows.
- QR Code:Optical scanning technology embedded in smartphone cameras and printed merchant displays facilitates low-cost acceptance without dedicated hardware. Urban traders in Lagos and southwestern cities are rotating from POS terminals toward commission-only software solutions, shifting vendor economics from fixed fees to volume shares.
- Mobile Apps:Internet-connected smartphone applications deliver enhanced interfaces and higher transaction limits for digitally enabled demographics.
- NFC:Near-field communication protocols enable contactless tap-to-pay functionality at equipped merchant terminals.
USSD retains the broadest reach, while QR Code is gaining share fastest among merchant acceptance tools.
End User:
Demographic and geographic segmentation determines interface complexity, agent density requirements, and product bundling strategies.
- Urban Users:City-dwelling populations in Lagos, Kano, and other major centers with denser agent networks and higher smartphone penetration. These users generate higher-value transactions through mobile apps while demanding integrated microloan and savings product expansion from Tier-1 operators with deeper equity reserves.
- Rural Users:Agricultural and remote community populations dependent on agent banking infrastructure and USSD connectivity. Northern states exhibit minimal banking penetration alongside dense commerce, creating first-mover advantages for network builders investing in agent training and liquidity management.
- Youth:Digitally native demographics with higher smartphone adoption and appetite for embedded financial services.
- Senior Citizens:Older populations requiring simplified interfaces and biometric authentication to overcome password complexity barriers.
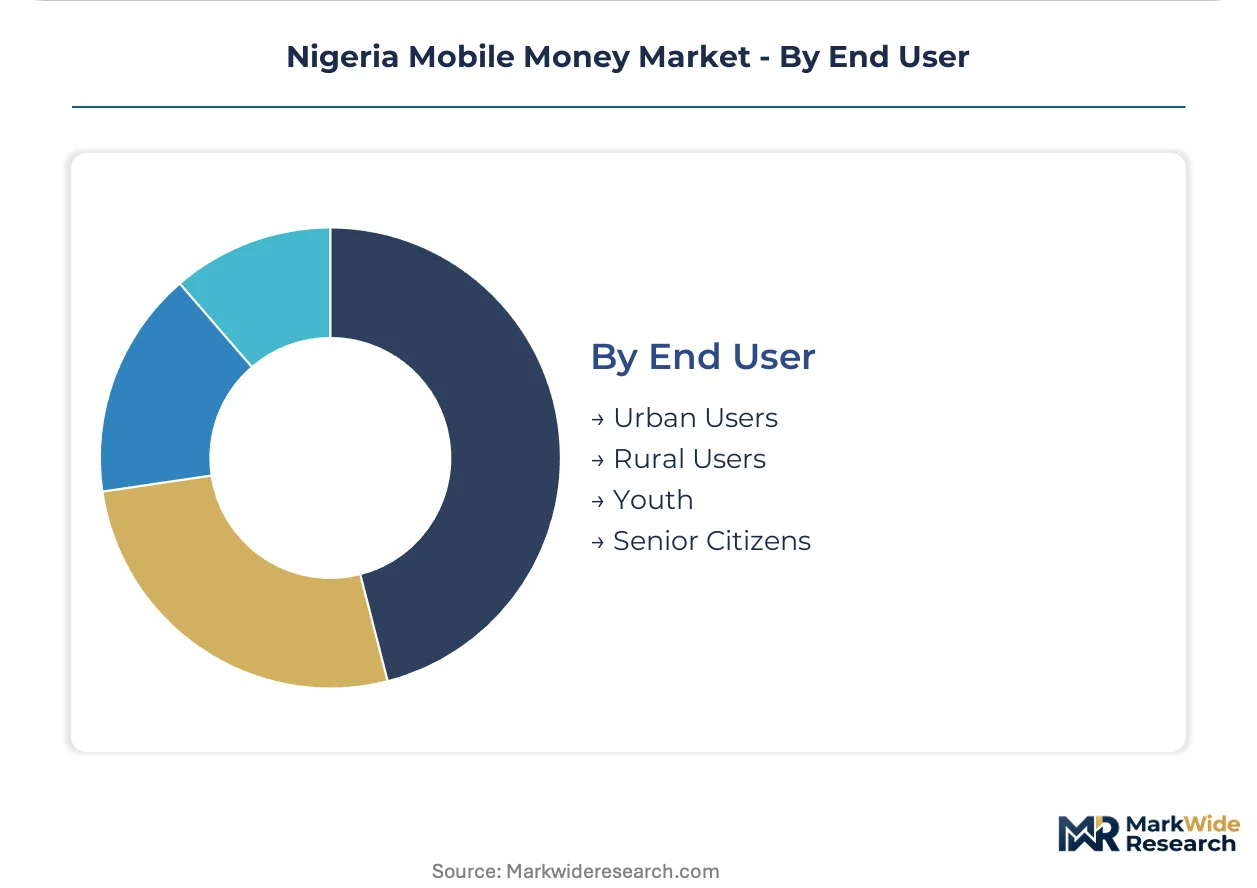
Urban Users generate the highest transaction values, yet Rural Users represent the steepest expansion trajectory as agent networks extend into agricultural corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Bank of Nigeria's tiered KYC framework and agent banking guidelines have expanded financial access across Nigeria's six geopolitical zones. Lagos and Kano anchor transaction volume through dense agent networks and urban commerce density.
Lagos State
Lagos generates the highest mobile money transaction values through its concentration of small businesses and informal traders. The CBN's Payments System Management Department enforces capital adequacy requirements that Tier-1 operators absorb more readily than smaller entrants. Ikeja and Lagos Island commercial districts exhibit steepest merchant migration from cash to QR-code and USSD settlement.
Kano State
Kano anchors northern Nigeria's mobile money adoption through dense agricultural commerce and minimal traditional banking penetration. CBN agent banking guidelines permit non-bank entities to perform cash-in/cash-out services throughout rural corridors surrounding the metropolis. Sabon Gari market and Dawanau grain market clusters drive peak transaction volumes during harvest trading periods.
Southwest Corridor
Oyo, Osun, and Ogun states extend Lagos-driven adoption patterns into secondary urban centers. The CBN's tiered KYC rules enable limited-value accounts with reduced documentation for informal sector workers across Ibadan and Abeokuta. Dugbe market in Ibadan and Lafenwa commercial district in Abeokuta concentrate merchant payment acceptance growth.
Niger Delta
Rivers and Delta states exhibit rising mobile money penetration through oil sector wage disbursement digitization and urban commerce expansion. The CBN regulates interoperability mandates that compress proprietary network advantages across Port Harcourt and Warri. Mile 1 and Mile 3 markets in Port Harcourt generate recurring transaction fee pools for platform operators.
North-Central Belt
Plateau and Kaduna states bridge northern and southern adoption patterns through agricultural trading and transnational commerce routes. CBN capital adequacy buffers force balance sheet restructuring among mid-tier licensees operating in Jos and Kaduna metropolitan areas. Terminus and Central markets in Jos concentrate agent network density for cash-in/cash-out liquidity.
Nigeria Mobile Money Market Key Industry Players
On the supply side, the industry is consolidating around three distinct operational archetypes: telecom-integrated super-agents, fintech-native payment orchestrators, and bank-sponsored wallet providers. Tier-1 players with deeper equity reserves absorb compliance costs while smaller entrants face consolidation pressure. Dominant competitive moves include geographic expansion through agent network density and portfolio diversification into microloans and savings products.
Within the super-agent tier, OPay and Moniepoint exemplify divergent path dependencies—one leveraging extensive agent footprints for cash liquidity, the other anchoring merchant acceptance through hardware-software integration. Paga occupies a position emphasizing rural network density and sustained agent training investment. Flutterwave and Paystack represent the payment orchestration archetype, connecting international and domestic settlement rails.
| Leading Market Players |
|---|
| Interswitch |
| Flutterwave |
| OPay |
| FairMoney |
| Paystack |
| Moniepoint |
| Paga |
| Nomba |
| PalmPay |
| Others |
Cost & Logistics Intelligence
Telecom infrastructure providers in South Africa, Nigeria, and Kenya anchor the upstream layer where licensing fees and spectrum costs concentrate, compressing margin pools downstream toward agent network operators and merchant acquirers who must absorb connectivity tariffs while competing on transaction commissions.
Pricing Analysis
Volume-discount tiering structures dominate agent commission arrangements, with large-scale merchants capturing preferential settlement rates unavailable to informal traders. Price differentiation rests on transaction frequency and float management capacity, where high-volume agents negotiate reduced cash-in/cash-out spreads. Cost compression in rural corridors is intensifying because GSM network reliability gaps force redundant connectivity investments. Small agricultural traders in northern Nigeria exhibit the highest price sensitivity, while Lagos-based merchant aggregators with integrated accounting software show the least.
Supply Chain Analysis
Upstream feedstock for mobile money infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and China, where POS terminal chipsets and smartphone components originate. Critical inputs include SIM toolkit modules, biometric sensors, and encrypted security processors. Single-source vulnerability around GSM base station equipment creates settlement failure risks during peak agricultural trading periods. Distribution runs through licensed super-agents who maintain cash float reserves across dispersed rural networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's mobile money sector sits at a platform-economics inflection where Central Bank interoperability mandates are dissolving proprietary network moats and redistributing margin pools toward open-architecture orchestrators.
For Market Incumbents: Entrench merchant ecosystem lock-in through API banking convergence with inventory management and accounting software platforms. Deepen agent liquidity provisioning through formal credit channel partnerships that address working capital constraints degrading rural network stability. The threat of commission compression from interoperability mandates demands defensive portfolio diversification into microloans and savings products. For New Entrants and Emerging Players: Rural northern corridors surrounding Kano represent the most penetrable entry point, where dense agricultural commerce and minimal banking penetration create first-mover advantages for agent network builders. Agricultural trading periods during harvest windows offer concentrated transaction volume capture. A biometric-authentication-first go-to-market angle bypasses smartphone dependence and accelerates trust formation among feature-phone-dependent demographics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech-native payment orchestrators seeking exit liquidity before interoperability standardization erodes proprietary advantages. Long-term viability over the coming decade hinges on embedded lending capabilities and merchant ecosystem integration depth. Watch Central Bank capital adequacy buffer adjustments as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Agent Network Density Expansion | Establishes cash-in/cash-out liquidity dominance in underserved agricultural corridors surrounding Kano. |
| API Banking Convergence | Captures merchant ecosystem lock-in through integration with inventory management and accounting software platforms. |
| Microloan Product Embedding | Generates interest income streams while deepening user engagement beyond pure payment functionality. |
| Biometric Authentication Layering | Compresses fraud rates while extending service reach into demographics excluded by password complexity. |
| Regulatory Compliance Investment | Absorbs Central Bank capital adequacy requirements that force consolidation among undercapitalized mid-tier licensees. |
Research Approach
A standing panel of mobile money platform executives, agent network operators, Central Bank regulatory officers, and merchant acquiring specialists provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from CBN Payments System Management Department circulars, NCC spectrum licensing records, and GSM network operator tariff disclosures. Bottom-up transaction volume modeling triangulated against top-down addressable population estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning service type, customer category, connectivity technology, and geographic end-user profile. CAGRs derived from trend extrapolation of agent network expansion rates, smartphone penetration curves, and merchant digital migration patterns. Industry-specific forecast inputs included tiered KYC account adoption velocity and interoperability mandate implementation timelines.
Practitioners should monitor Central Bank regulatory circulars, GSM infrastructure investment announcements, and agent commission structure revisions for early signals of forecast deviation. Cross-checking against Central Bank of Nigeria published financial inclusion metrics and NCC subscriber data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Latin America Payment Gateway Market
Payments
Slovakia POS Terminal Market
Payments
Australia Mobile Payment Market
Payments
North America Payments Market
Payments
Japan POS Terminals Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
India POS Terminals Market
Payments
France Payments Market
Payments
Fuel Cards Market
Payments
US Gift Card and Incentive Card Market
Payments
Cryptocurrency Payment Apps Market
Payments
Wearable Payments Market
Payments
United States Payments Market
Payments
United States Payment Gateways Market
Payments
United States Mobile Payment Market
Payments
Saudi Arabia Mobile Payments Market