
 Middle East Gift Card and Incentive Card Market | 2026-2036
Middle East Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Gift Card and Incentive Card Market Foresight
Subscription-based reloadable card platforms is restructuring how gift card value gets monetized beyond initial purchase. Edenred leverages corporate incentive program management to sustain enterprise client retention across Gulf states. YouGotaGift anchors consumer digital gifting through mobile-first redemption infrastructure. NymCard competes on embedded-finance APIs that let non-bank brands issue branded stored-value instruments.
Gift cards and incentive cards constitute prepaid stored-value instruments issued by retailers, financial institutions, or program operators, typically encoded with magnetic stripes, EMV chips, or virtual token credentials for redemption at designated acceptance locations. Their primary commercial purpose is to transfer purchasing power from giver to recipient while enabling issuers to capture float revenue and behavioral data. E-commerce redemption channel growth outpaces in-store volume as Gulf logistics networks mature, while corporate client targeting commands premium program fees due to bulk issuance and customization requirements. Retail gift card types retain the largest value pool, though entertainment and restaurant categories are expanding fastest among younger demographics.
Saudi Arabian Monetary Authority (SAMA) stored-value facility rules, UAE Central Bank retail payment regulations, and Qatar Central Bank e-money licensing frameworks collectively govern issuance standards, consumer protection, and anti-money laundering compliance across the Gulf Cooperation Council. These regulations shape demand by mandating KYC integration, fund segregation, and transaction monitoring that elevates operational barriers for new entrants. Stakeholders must monitor evolving central bank digital currency interoperability mandates that could redirect prepaid instrument architectures toward wallet-native formats.
Market Dynamics
Digital wallet interoperability mandates from SAMA and the UAE Central Bank are forcing issuers to rebuild prepaid card architectures around API-native tokenization standards rather than legacy magnetic-stripe infrastructure.
Growth Catalysts
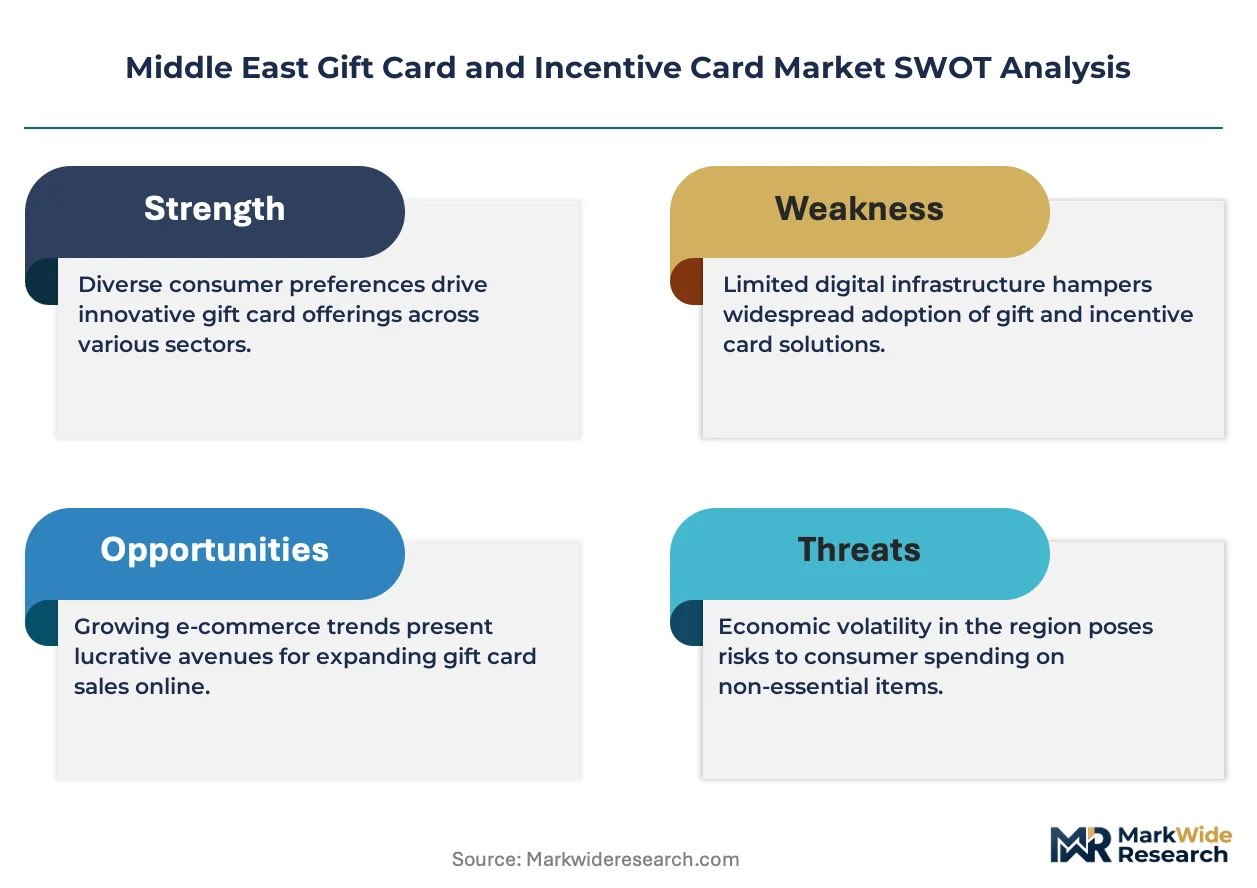
- Vision 2030 workforce localization:Saudi government mandates expand corporate employee reward program budgets across banking and telecom sectors.
- SAMA stored-value facility rules:Regulatory clarity reduces licensing friction for non-bank fintech issuers entering the prepaid market.
- Mobile-first redemption infrastructure:Smartphone penetration above 95% across Gulf Cooperation Council states accelerates digital gift card adoption.
Market Restraints
- Fund segregation requirements:Central bank mandates force issuers to maintain ring-fenced accounts that compress float revenue yields.
- KYC integration costs:Biometric identity verification systems add per-account onboarding expenses that disadvantage small-scale program operators.
- Cross-border settlement friction:Dirham-riyal exchange rate volatility and correspondent banking restrictions complicate multi-currency card programs.
Strategic Opportunities
- Qatar hospitality sector:FIFA World Cup legacy infrastructure and year-round tourism create underpenetrated demand for experience-based gift cards.
- Embedded finance convergence:API layering between prepaid card platforms and ride-hailing or food delivery apps enables branded stored-value issuance.
- Kuwait expatriate remittance corridor:Payroll-linked incentive cards targeting South Asian workers represent white-space demand outside traditional retail gifting.
Industry Challenges
- API talent scarcity:Shortage of developers experienced in SAMR-aligned tokenization standards delays platform migration timelines.
- Legacy system integration:Core banking modernization projects at Gulf incumbents create procurement bottlenecks for prepaid program management software.
- Compliance timeline compression:Accelerated central bank digital currency pilots force simultaneous architecture pivots without grandfathering periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Gift Card and Incentive Card Market |
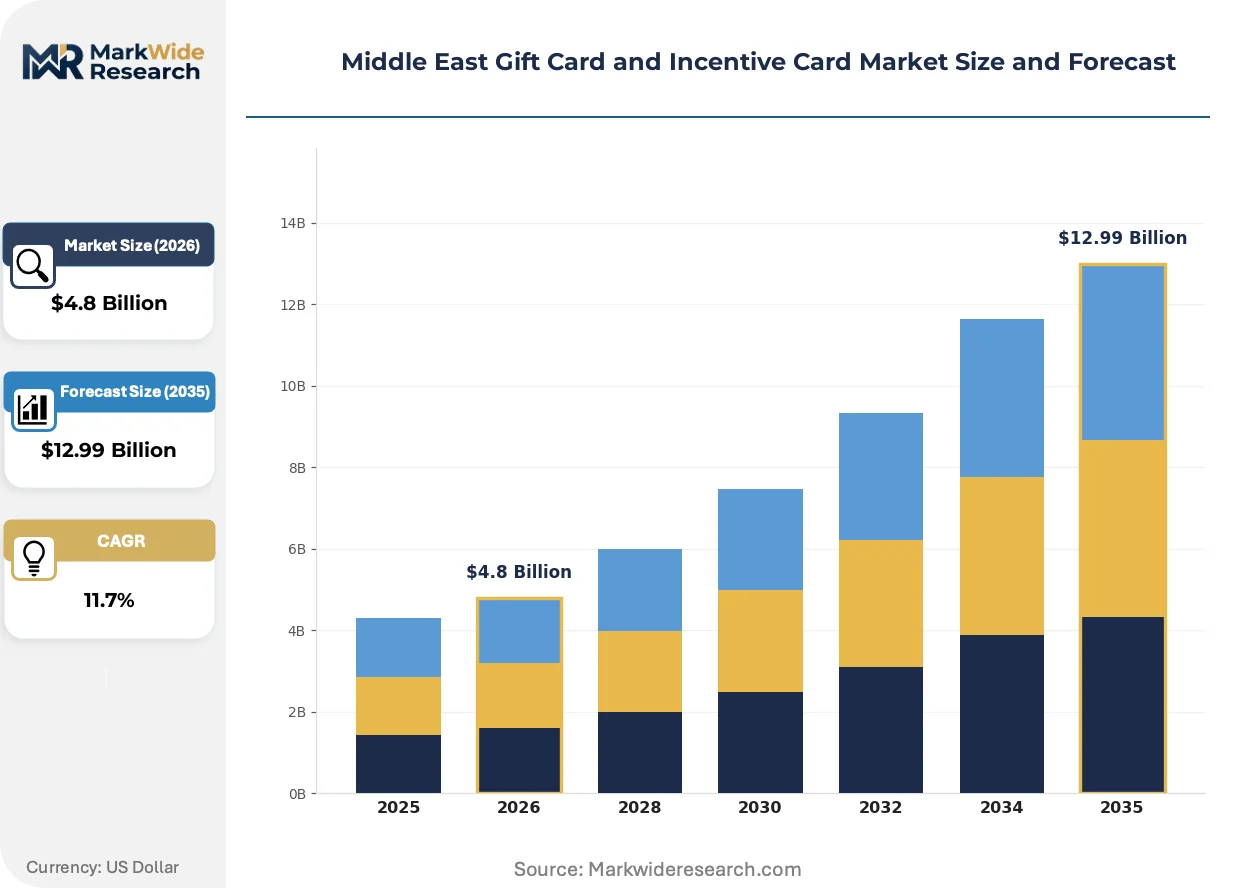
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gift Card Type: Retail, Restaurant, Entertainment, E-commerce Redemption Channel: Online, In-store, Mobile App, Kiosk Target Audience: Corporate Clients, Millennials, Families, Students Incentive Type: Promotional, Reward, Loyalty, Employee |
| Companies Covered | Merit Incentives, Giftit.me, Edenred, Blackhawk Network ME, NymCard, YouGotaGift, STC Pay, Majid Al Futtaim, Resal, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Gift Card and Incentive Card Market Shifts & Advancements
Tokenized virtual card credentials are displacing physical plastic issuance as the default instrument format, while corporate program operators demand real-time analytics dashboards that merge redemption data with workforce performance metrics.
EMV chip-to-cloud tokenization is expanding into the corporate incentive segment as the dominant security architecture. Large Gulf banking groups are migrating enterprise reward programs to virtual-only issuance within eighteen-month windows. This shift compresses manufacturing demand for physical card bodies while elevating API infrastructure spending.
SAMA and UAE Central Bank digital wallet interoperability standards are mandating common token formats across issuer platforms. Program operators must rebuild redemption networks to accept cross-wallet credentials or face exclusion from government-linked employee benefit schemes. Retail gift card categories face the steepest compliance recertification timelines.
Corporate procurement teams are consolidating vendor relationships around full-stack incentive program managers. Bulk issuance contracts now bundle card production, digital delivery, and redemption analytics into single-source agreements. Saudi Arabia and UAE enterprise banking sectors show the fastest consolidation velocity.
Middle East Gift Card and Incentive Card Market Segmentation
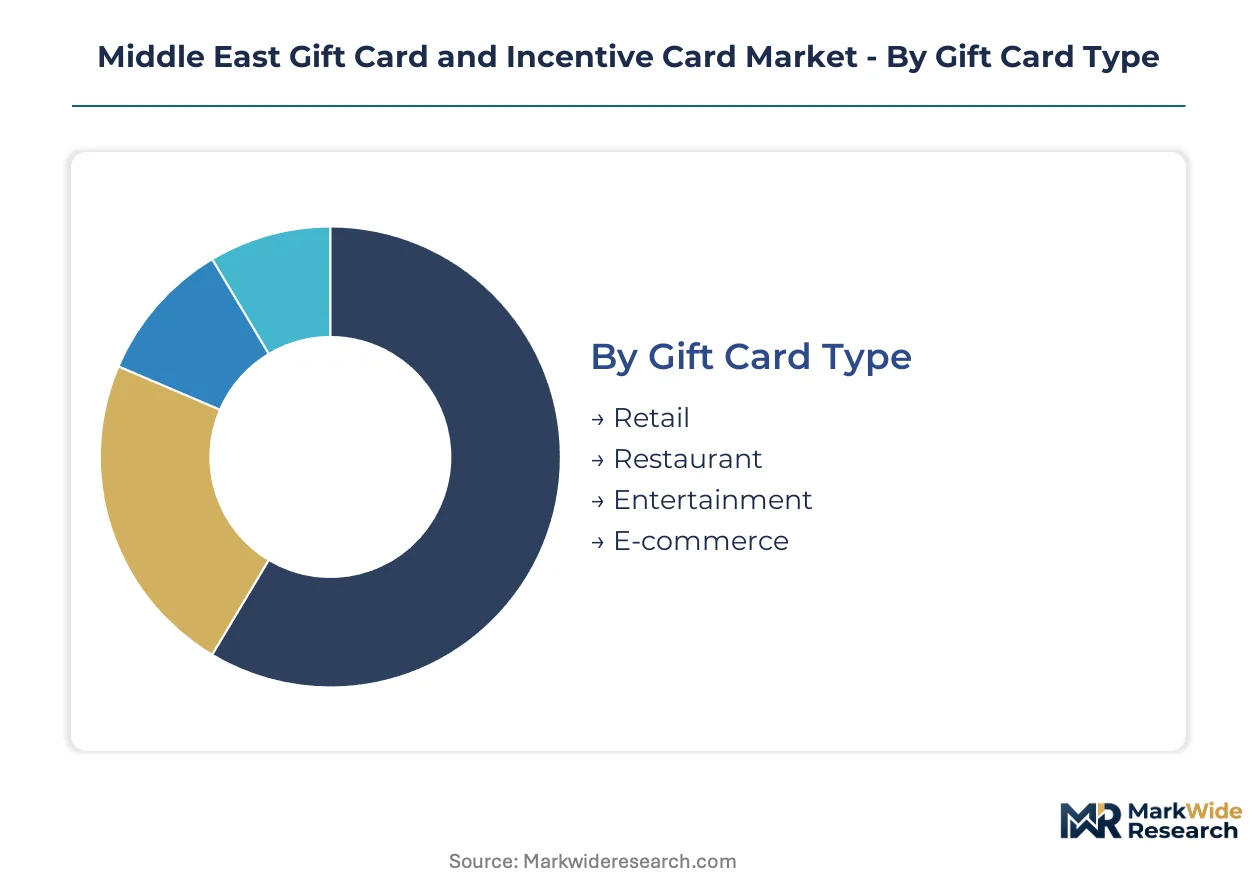
Prepaid instrument architectures in the Middle East diverge sharply between standalone retail products and embedded corporate incentive systems. SAMA and UAE Central Bank interoperability mandates force issuers to map each segment against API-native tokenization requirements. Procurement teams select categories based on whether redemption networks require physical acceptance infrastructure or virtual-only credentialing.
Gift Card Type:
Retail gift cards operate as standalone stored-value products with broad merchant acceptance, while entertainment and restaurant categories embed more narrowly into specific experience ecosystems. Integration depth varies: retail spans multi-brand redemption networks, whereas entertainment locks into venue-specific token systems.
- Retail:Open-loop magnetic stripe and EMV chip instruments redeemable across department stores, supermarkets, and fuel stations. Saudi banking groups concentrate bulk issuance here for Ramadan and Eid corporate gifting programs. SAMA fund segregation rules compress float yields on high-volume retail float.
- Restaurant:Closed-loop credentials tied to quick-service and fine-dining chains, increasingly virtual-only for delivery app integration. UAE food delivery platforms embed these as checkout payment options, expanding redemption beyond physical locations. Younger demographics in Dubai and Riyadh drive frequency.
- Entertainment:Cinema, gaming, and experience venue tokens with limited interoperability.
- E-commerce:Platform-locked digital credentials for marketplace checkout.
Volume placements concentrate in Retail; the faster expansion belongs to Restaurant.
Redemption Channel:
Channel selection determines technical architecture costs: mobile app and online redemption demand cloud tokenization infrastructure, while in-store and kiosk channels retain legacy POS integration requirements. Gulf smartphone penetration above 95 percent tilts new issuance toward virtual-first credentialing.
- Online:Browser-based redemption through issuer portals and merchant checkout pages. Saudi telecom sector employee reward programs prioritize this channel for remote workforce distribution. API latency requirements shape vendor selection.
- Mobile App:Wallet-native token storage with QR code or NFC presentation at point of acceptance. UAE Central Bank digital wallet interoperability standards mandate cross-app credential recognition. Edenred and YouGotaGift compete on app UX.
- In-store:Physical card presentation at EMV terminals.
- Kiosk:Self-service terminal dispensing and redemption.
Corporate procurement favors Mobile App; In-store retains legacy volume in older demographic segments.
Target Audience:
Audience segmentation aligns issuance economics with behavioral redemption patterns. Corporate clients command bulk pricing and analytics dashboards, while consumer segments prioritize convenience and brand prestige.
- Corporate Clients:Enterprise procurement of bulk incentive instruments for employee rewards and channel partner motivation. Saudi Vision 2030 workforce localization mandates expand banking and telecom program budgets. Customization requirements elevate per-unit program fees.
- Millennials:Digital-native recipients favoring instant mobile delivery and social sharing features.
- Families:Multi-recipient gifting occasions with denomination flexibility.
- Students:Campus-linked programs with restricted merchant acceptance.
Revenue concentration sits with Corporate Clients; steepest expansion trajectory appears in Millennials.
Incentive Type:
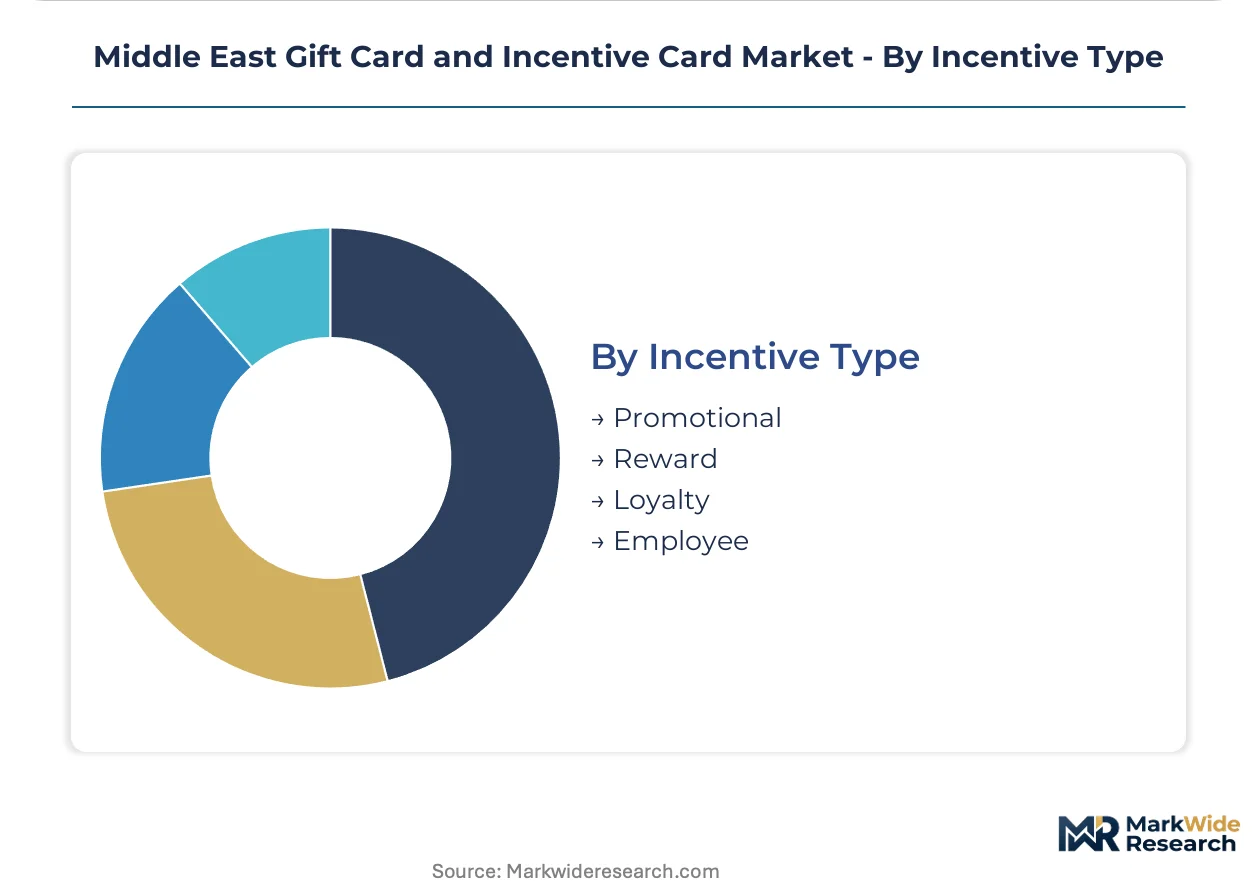
Incentive architecture determines float duration and breakage economics. Promotional instruments expire quickly with high breakage, while employee incentives carry longer validity and higher redemption rates.
- Employee:Payroll-linked or performance-triggered rewards with extended validity periods. Saudi banking sector adoption deepens through SAMA-regulated stored-value facility licensing. Fund segregation compliance adds operational overhead.
- Loyalty:Points-to-currency conversion programs integrated with retail CRM systems.
- Promotional:Campaign-tied instruments with short expiration windows.
- Reward:Discretionary recognition programs with moderate validity.
Program management complexity peaks in Employee; Promotional delivers highest breakage yields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors prepaid instrument issuance across the Gulf Cooperation Council, with King Abdullah Financial District hosting the densest concentration of corporate incentive program operators and SAMA-licensed stored-value facilities.
Saudi Arabia
Vision 2030 workforce localization mandates expand banking and telecom employee reward budgets. SAMA stored-value facility licensing creates regulatory clarity for non-bank fintech entrants. Jeddah's commercial district hosts emerging program management hubs serving Red Sea tourism projects.
United Arab Emirates
UAE Central Bank digital wallet interoperability standards force API-native tokenization rebuilds. Dubai International Financial Centre concentrates Edenred and YouGotaGift regional headquarters. Abu Dhabi sovereign wealth-linked entities drive bulk corporate procurement consolidation.
Qatar
FIFA World Cup legacy infrastructure sustains hospitality sector gift card demand. Qatar Central Bank e-money licensing frameworks govern issuance standards. Lusail's entertainment district anchors experience-based credential redemption networks.
Kuwait
Expatriate payroll-linked incentive cards target South Asian worker remittance corridors. The country's central bank mandates fund segregation for stored-value instruments. Kuwait City's financial district hosts legacy banking groups modernizing prepaid program infrastructure.
Bahrain
Fintech sandbox regulations attract digital gift card platform testing. The Bahrain Economic Development Board licenses payment service providers under lighter-touch frameworks. Manama's financial harbor clusters regulatory technology vendors serving Gulf-wide compliance needs.
Middle East Gift Card and Incentive Card Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East prepaid instrument space. Full-stack program managers with captive banking licenses dominate enterprise corporate incentive contracts, while API-native platforms capture fintech-issuer relationships. Three archetypes define competitive positioning: legacy banking groups with stored-value facility licenses, technology platforms offering embedded-finance infrastructure, and specialized incentive program operators with workforce analytics capabilities. M&A activity concentrates on API talent acquisition, while strategic partnerships between card processors and ride-hailing or food delivery apps expand redemption network reach.
Within the full-stack incentive tier, Edenred exemplifies corporate program management depth across Gulf states, while YouGotaGift anchors consumer digital gifting through mobile-first redemption infrastructure. NymCard occupies a position among API-native platforms enabling non-bank brands to issue stored-value instruments, representing the embedded-finance convergence archetype reshaping competitive positioning.
| Leading Market Players |
|---|
| Merit Incentives |
| Giftit.me |
| Edenred |
| Blackhawk Network ME |
| NymCard |
| YouGotaGift |
| STC Pay |
| Majid Al Futtaim |
| Resal |
| Others |
Supply & Pricing Matrix
Bulk corporate procurement teams in Saudi banking and telecom sectors command volume-based discounts that compress per-unit margins for program operators while sustaining contract lock-in. SAMA fund segregation mandates elevate operational overhead that issuers recover through tiered program management fees tied to float duration and analytics depth.
Pricing Analysis
Value-based pricing anchored to employee retention outcomes dominates corporate incentive contracts, with fees scaling against workforce performance metrics rather than card volume alone. Price differentiation rests on API integration complexity and real-time dashboard customization, with premium tiers commanding higher margins for biometric KYC bundling. Cost compression in standard retail gift card issuance is intensifying because virtual-only delivery eliminates physical production overhead. Small-scale fintech entrants exhibit highest price sensitivity, while sovereign wealth-linked enterprise buyers prioritize compliance assurance over unit economics.
Supply Chain Analysis
Cross-border logistics and correspondent banking friction between UAE dirham and Saudi riyal corridors elevate settlement costs for multi-currency program operators. Tokenization infrastructure draws from cloud service concentration in UAE and Saudi Arabia, with EMV chip sourcing anchored in Taiwan and South Korea. Single-source vulnerability around SAMA-aligned API developer talent creates procurement bottlenecks for platform migration timelines. Distribution runs through direct enterprise sales teams for corporate contracts and mobile app stores for consumer digital delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMA stored-value facility licensing operates as a cost-of-compliance moat that elevates barriers for unlicensed entrants while granting compliant incumbents preferential access to government-linked employee benefit schemes.
For Market Incumbents: Acquire API-native tokenization platforms to accelerate architecture migration ahead of central bank digital currency interoperability mandates. Defensive consolidation around embedded-finance partnerships with ride-hailing and food delivery apps neutralizes fintech-issuer competitive threats. Captive banking licenses in Saudi Arabia and UAE anchor enterprise contract renewal rates against unlicensed challengers. For New Entrants and Emerging Players: Ride-hailing and food delivery platforms represent the most penetrable channel partners for white-space entry, given their appetite for branded stored-value issuance without legacy banking infrastructure. Qatar hospitality networks and Kuwait expatriate payroll corridors offer underexploited demand pockets outside Saudi-UAE competitive density. A mobile-first redemption infrastructure play bypasses physical POS integration costs that burden legacy operators. For Investors and Strategic Acquirers: The window for entry favors API-native fintech platforms with SAMA-aligned tokenization capabilities and existing stored-value facility licenses. Long-term viability hinges on central bank digital currency interoperability readiness across the projection horizon. Watch SAMA and UAE Central Bank pilot announcements as inflection signals for architecture consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Migration | SAMA interoperability mandates force tokenization rebuilds that exclude legacy magnetic-stripe operators from government contracts. |
| Embedded-Finance Partnership | Food delivery and ride-hailing app integrations expand redemption network reach beyond traditional merchant acceptance infrastructure. |
| SAMA License Acquisition | Stored-value facility licensing creates regulatory moats that gate access to Vision 2030 workforce localization program budgets. |
| Virtual-Only Issuance Transition | Corporate procurement consolidation favors program managers eliminating physical card production costs within eighteen-month windows. |
| Cross-Wallet Credential Standardization | UAE Central Bank digital wallet interoperability rules mandate common token formats across issuer platforms or face scheme exclusion. |
Research Methodology
Central bank regulatory filings, stored-value facility licensing databases, and corporate incentive program procurement records formed the secondary backbone for market sizing validation. Primary interviews with SAMA-licensed program operators, UAE Central Bank compliance officers, Edenred and YouGotaGift product directors, and Saudi banking sector procurement leads supplied forward-looking contract velocity data. Bottom-up triangulation across issuer-reported float volumes and top-down reconciliation against central bank payment system statistics anchored value estimates.
Historical trendline analysis across prepaid instrument issuance volumes informed baseline trajectory modeling over the projection horizon. Segmentation dimensions spanned gift card type, redemption channel architecture, target audience procurement behavior, and incentive duration economics. CAGRs were derived from regression analysis against workforce localization policy spend, smartphone penetration trajectories, and digital wallet adoption curves. Forecast inputs incorporated SAMA and UAE Central Bank regulatory timeline assumptions without grandfathering provisions.
Caveats apply where accelerated central bank digital currency pilots or correspondent banking restriction tightening could materially shift the outlook for multi-currency program economics. Forecasts reflect assumptions around API talent availability and interoperability standard implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Saudi Arabia Mobile Payments Market
Payments
Estonia POS Terminal Market
Payments
Singapore Payments Market
Payments
China Real Time Payments Market
Payments
Luxembourg POS Terminals Market
Payments
Hungary POS Terminal Market
Payments
Transit Cards Market
Payments
Israel Credit Cards Market
Payments
Canada Gift Card and Incentive Card Market
Payments
Contactless Payment Terminals Market
Payments
South Korea Mobile Payment Market
Payments
Finland POS Terminals Market
Payments
Latin America Retail Cash Management Market
Payments
Cash Management System Market
Payments
Retail Cash Management Market
Payments
Instant Payments Market