
 North America Real Time Payment Market | 2026-2036
North America Real Time Payment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Real Time Payment Market Analytics
Merchant demand across North America is decoupling from traditional batch-processing relationships as smaller retailers and gig-economy platforms seek instant settlement. Fiserv, Inc anchors its position through embedded banking partnerships that push real-time disbursements into payroll and merchant funding workflows. Mastercard, Inc competes by leveraging its vocalink acquisition to power faster payment rails for financial institutions seeking 24/7 clearing capabilities.
Real-time payment systems in North America constitute electronic fund transfer networks that clear and settle transactions within seconds through ISO 20022 messaging protocols, operating continuously without batch windows. These systems serve commercial and consumer purposes by eliminating float periods and reducing counterparty risk in high-velocity transactions. Mobile wallets and bank transfers are gaining structural prominence as faster payment adoption pushes consumers away from card-dependent checkout flows, while peer-to-peer transfers and merchant payments capture disproportionate growth in transaction volume as instant settlement becomes default expectation rather than premium feature.
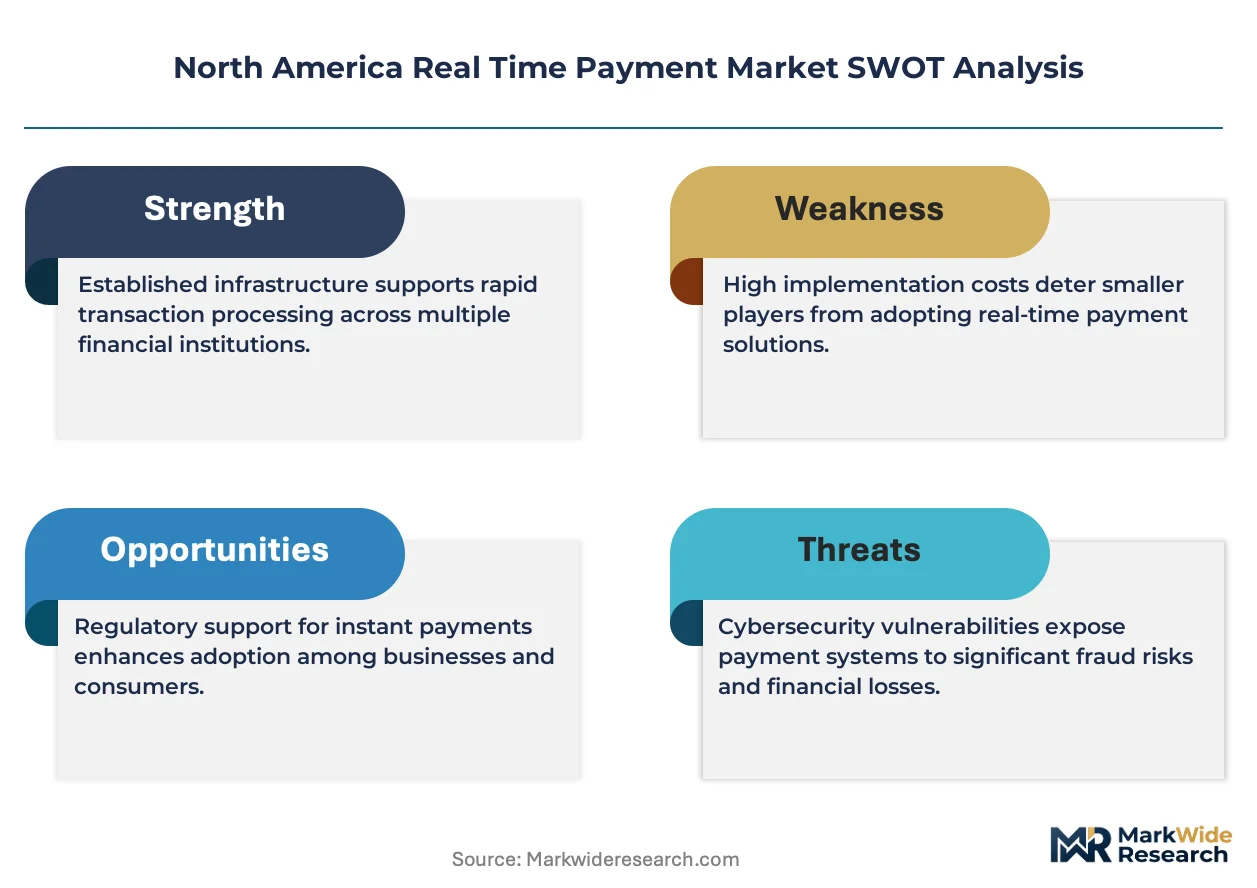
The Federal Reserve's FedNow Service and Payments Canada's Real-Time Rail framework are reshaping infrastructure requirements for participating institutions, mandating 24/7 operational readiness and API-native connectivity. NACHA operating rules for same-day ACH and state-level money transmission licensing regimes create layered compliance obligations that favor institutions with existing regulatory scale. Stakeholders must evaluate whether their core banking architectures can sustain sub-second clearing requirements without wholesale replacement of legacy payment engines.
Market Dynamics
The Federal Reserve's FedNow Service launch is forcing banks to replace legacy batch-processing cores with 24/7 ISO 20022-native architectures, compressing settlement windows from days to seconds and eliminating float-based revenue models across the region.
Growth Catalysts
- FedNow Service:The Federal Reserve's instant payment rail mandates API connectivity for depository institutions, creating immediate infrastructure pull-through for core banking modernization across the United States.
- Mid-market treasury optimization:Businesses with $50M-$500M revenue seek working capital efficiency through immediate fund availability, bypassing traditional ACH float periods.
- ISO 20022 messaging:Rich data standards enable straight-through processing for remittance information, reducing manual reconciliation costs for accounts-payable departments.
Market Restraints
- Core banking replacement costs:Legacy mainframe architectures require $50M-$200M capital commitments for real-time clearing capability, freezing regional bank participation.
- State money transmission licensing:Fintechs face 48-state compliance patchworks with varying net worth requirements, creating friction for cross-border disbursement products.
- Same-day ACH substitution:NACHA's enhanced batch system satisfies non-urgent settlement needs at lower cost, limiting RTP premium pricing power.
Strategic Opportunities
- Canadian Real-Time Rail:Payments Canada's 2025 infrastructure launch creates first-mover positioning for institutions with existing ISO 20022 capabilities.
- Embedded payroll disbursements:Gig-economy platforms and staffing firms require instant earned-wage access, opening B2B2C distribution channels.
- Request-for-Pay messaging:ISO 20022's RFP functionality enables bill-presentment-with-payment, displacing paper check and ACH debit workflows.
Industry Challenges
- 24/7 operational staffing:Continuous clearing mandates require fraud monitoring and exception handling outside traditional banking hours, straining mid-tier institutions.
- Core vendor dependency:Three legacy core processors dominate bank technology stacks, creating concentration risk for API integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Real Time Payment Market |
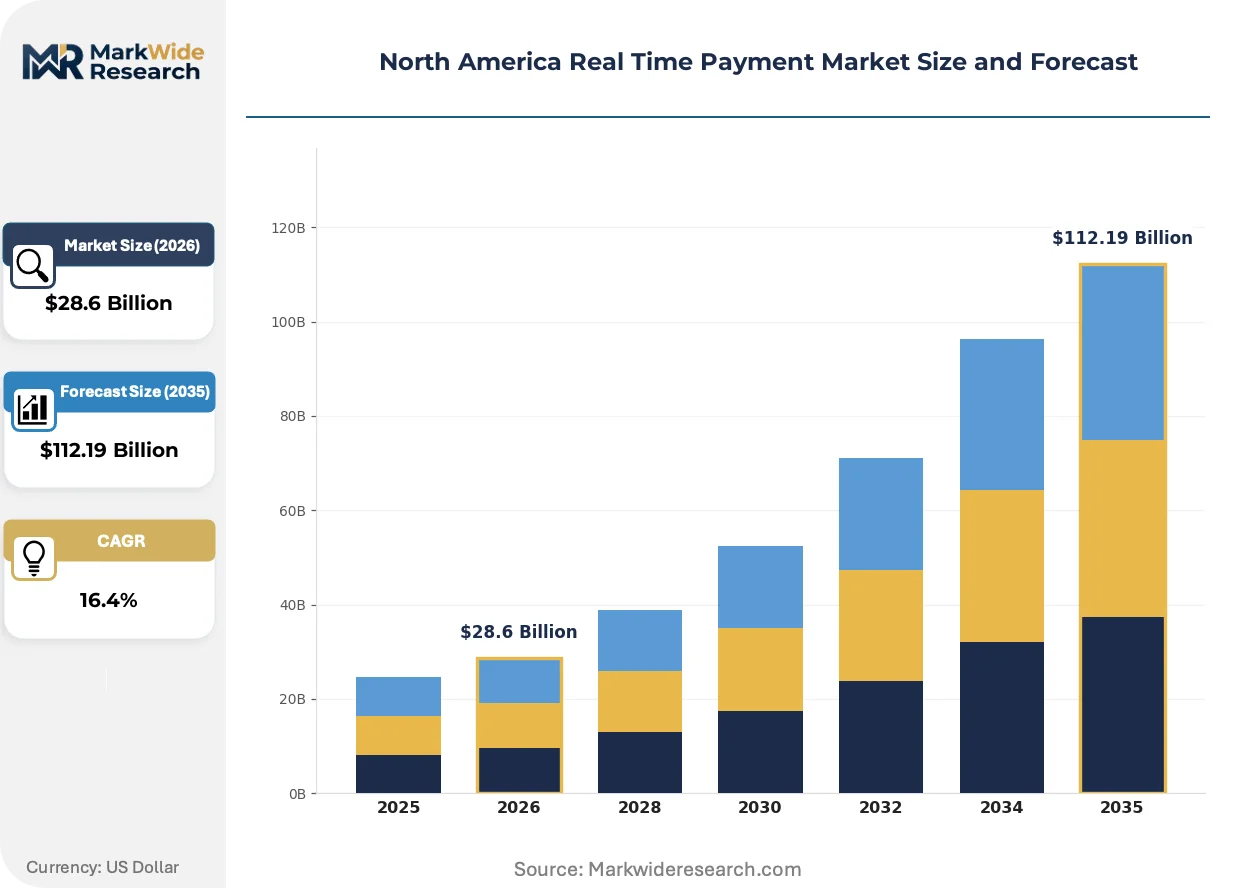
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallets, Bank Transfers End User: Retail Customers, Businesses, Financial Institutions, Government Entities Transaction Type: Peer-to-Peer Transfers, Merchant Payments, Bill Payments, Cross-Border Transactions Service Provider: Payment Processors, Banks, Fintech Companies, Payment Gateways |
| Companies Covered | ACI Worldwide, Inc, Fiserv, Inc, PayPal Holdings, Inc, Mastercard, Inc, FIS, Visa, Inc, Volante Technologies, Inc, Finastra, NovoPayment, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Real Time Payment Market Evolving Landscape
Real-time payment infrastructure is compressing the value chain between transaction initiation and final settlement, eliminating traditional float-based business models while forcing convergence between banking cores and fintech front-ends.
Cloud-native core banking platforms are consolidating payment processing onto elastic infrastructure that scales with transaction velocity. Mid-market banks in the United States and Canada are migrating from on-premise mainframes to API-first architectures, collapsing implementation timelines from 36 months to under 12. This consolidation is enabling smaller institutions to offer 24/7 clearing without proportional operational overhead.
The Federal Reserve's FedNow Service and Payments Canada's Real-Time Rail are mandating ISO 20022 messaging standards for all participating institutions. Regulatory compliance now requires rich-data remittance fields that support straight-through reconciliation for corporate treasury departments. Commercial banking units face the steepest adaptation curves as they retrofit legacy ERP integrations.
Merchant settlement expectations are compressing from next-day to instant across retail and service verticals. Point-of-sale providers and e-commerce platforms embed real-time disbursement as default, displacing traditional merchant-acquirer holdback practices. Food delivery and ride-share marketplaces in the United States demonstrate the strongest adoption velocity, using instant payout as driver-retention leverage.
North America Real Time Payment Market Segmentation
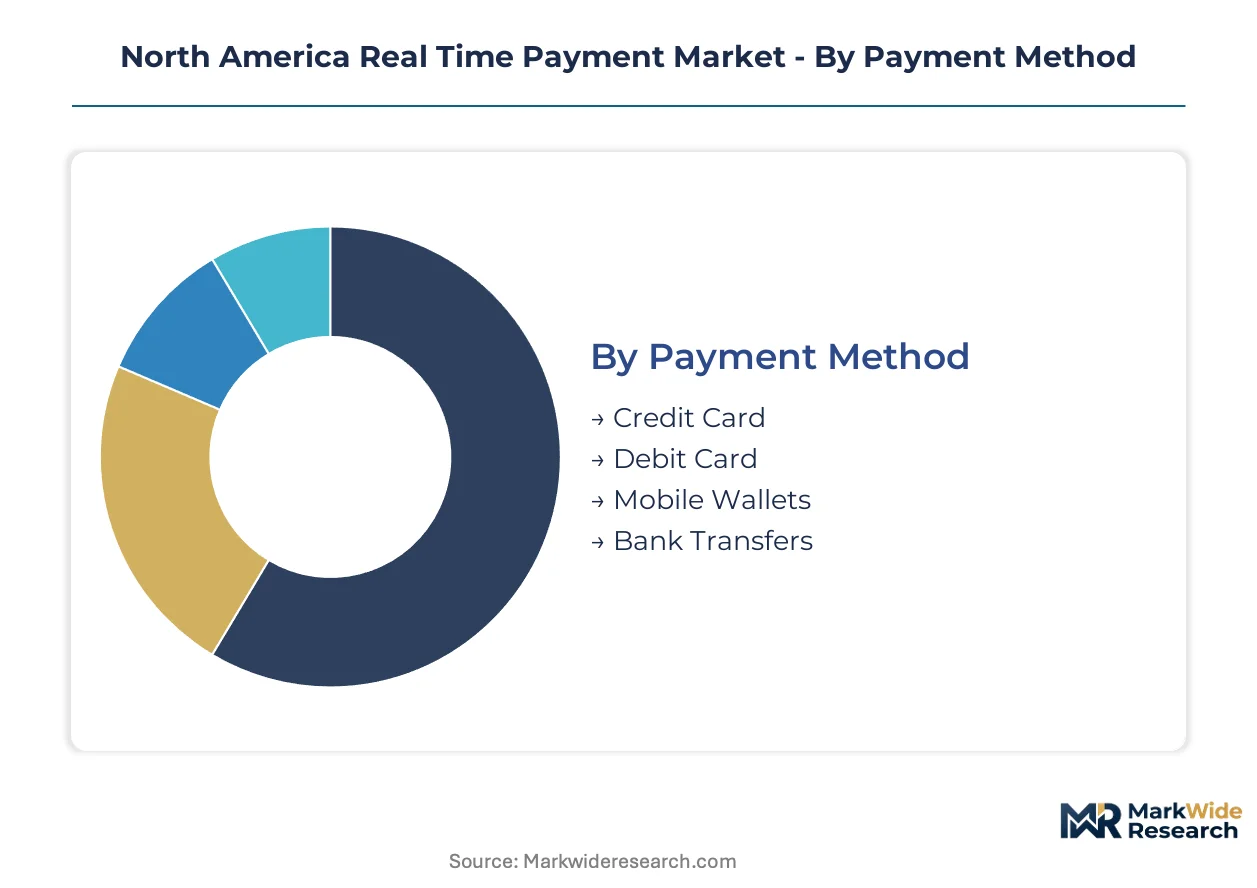
Real-time payment segmentation reveals how infrastructure investments align with distinct liquidity requirements across transaction types and user categories. Payment method selection and end-user profiles determine ISO 20022 implementation priorities for participating institutions.
Payment Method:
Volume concentration sits with card rails, while premium growth flows to account-based alternatives that bypass interchange fees.
- Credit Card:Existing networks leverage established fraud scoring and chargeback protections for high-value consumer purchases. Demand concentrates among e-commerce merchants in the United States seeking buyer protection guarantees during the FedNow transition period.
- Debit Card:Direct account access eliminates credit risk for issuers while offering consumers immediate fund verification. Mid-market retailers across Canada favor debit for its lower acceptance costs compared to credit rails.
- Mobile Wallets:Tokenized credentials enable biometric authentication and push-to-card disbursements.
- Bank Transfers:Account-to-account settlement through FedNow and RTP networks removes card network intermediaries entirely.
Today's leader: Credit Card. Tomorrow's challenger: Bank Transfers.
End User:
Commercial treasury departments drive premium pricing, while retail volume funds infrastructure amortization.
- Retail Customers:Consumers demand instant peer-to-peer transfers and merchant refunds through mobile banking applications. Gig-economy workers in California and Texas prioritize earned-wage access as a retention tool.
- Businesses:Corporate treasury teams optimize working capital through immediate supplier payments and automated receivables reconciliation. Mid-market manufacturers across the Midwest adopt Request-for-Pay messaging to accelerate cash conversion cycles.
- Financial Institutions:Banks and credit unions require 24/7 operational readiness for FedNow participation.
- Government Entities:State and federal agencies disburse emergency benefits and tax refunds through instant rails.
Commercial adoption is climbing the fastest as CFOs quantify float elimination savings.
Transaction Type:
Person-to-person transfers established initial utility, while B2B workflows now capture implementation resources.
- Peer-to-Peer Transfers:Splitting expenses and informal remittances between individuals created early consumer familiarity with instant settlement. Younger demographics in urban United States markets treat real-time availability as baseline expectation.
- Merchant Payments:Point-of-sale and e-commerce checkout flows embed instant settlement as default for seller fund availability. Food delivery platforms operating across North America leverage immediate driver payout as competitive differentiation.
- Bill Payments:Request-for-Pay messaging enables billers to present invoices with embedded payment authorization.
- Cross-Border Transactions:Remittance corridors between the United States and Mexico test real-time connectivity with correspondent banking networks.
Merchant Payments anchor current volume. Cross-Border Transactions face the steepest regulatory climb.
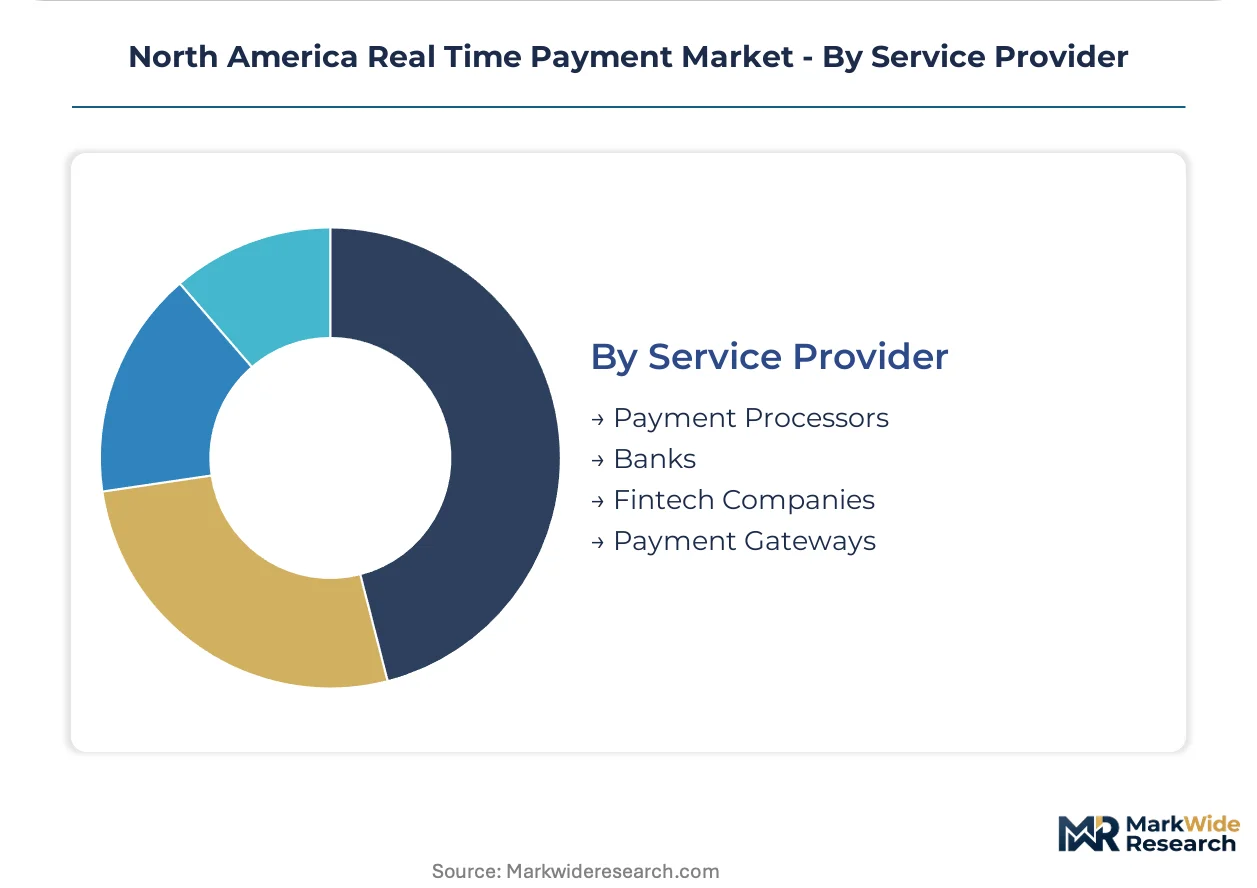
Service Provider:
Incumbent banks control regulatory access, while fintechs capture user experience innovation.
- Payment Processors:Merchant acquirers integrate real-time disbursement APIs into existing terminal and gateway infrastructure. Processors serving quick-service restaurants across the United States report strongest demand for instant settlement features.
- Banks:Depository institutions hold exclusive FedNow master account access and settlement finality guarantees. Regional banks in the Southeastern United States face core replacement decisions to meet 24/7 operational mandates.
- Fintech Companies:Neobanks and payment apps build front-end experiences atop bank-sponsored infrastructure.
- Payment Gateways:E-commerce platform integrations route transactions between merchant sites and acquiring banks.
Banks retain infrastructure control. Fintech Companies are gaining share fastest on user interface investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of real-time payment infrastructure investment, while Canada accelerates modernization through Payments Canada's Real-Time Rail initiative. Mexico's cross-border corridors with the United States are testing instant settlement connectivity, creating a three-country interoperability challenge across the continent.
United States
Mid-market businesses and gig-economy platforms drive FedNow adoption, seeking working capital optimization through immediate fund availability. The Federal Reserve mandates 24/7 operational readiness and ISO 20022 messaging for all participating depository institutions. New York and California anchor implementation, with fintech clusters in San Francisco and Manhattan pushing embedded banking partnerships into payroll and merchant funding workflows.
Canada
Corporate treasury departments and retail merchants demand instant settlement rails to eliminate traditional batch-processing delays. Payments Canada's Real-Time Rail framework mandates API-native connectivity and rich-data remittance standards for participating institutions. Toronto and Vancouver concentrate fintech innovation, with banks in Ontario retrofitting legacy ERP integrations to meet 2025 infrastructure launch timelines.
Mexico
Remittance corridors and cross-border trade finance test real-time connectivity with United States correspondent banking networks. Banco de México oversees payment system stability while coordinating interoperability standards with North American counterparts. Mexico City and Monterrey serve as operational hubs, with financial institutions in the northern border states piloting instant settlement for manufacturing supply chains.
North America Real Time Payment Market Competitive Landscape
United States-based technology providers anchor the infrastructure tier; Canadian and Mexican specialists hold regional integration positions. The vendor structure concentrates around legacy core processors and cloud-native challengers, with three strategic archetypes dominating: incumbent payment networks, core banking modernizers, and embedded finance enablers. Consolidation proceeds through strategic partnerships between banks and fintechs, while technology licensing agreements accelerate ISO 20022 adoption timelines.
Within the infrastructure tier, Fiserv, Inc and Mastercard, Inc exemplify divergent competitive approaches. ACI Worldwide, Inc occupies a position bridging legacy modernization and real-time clearing capabilities. These entities represent how incumbent scale and vocalink-acquired network technology anchor market positioning without guaranteeing front-end user experience dominance.
| Leading Market Players |
|---|
| ACI Worldwide, Inc |
| Fiserv, Inc |
| PayPal Holdings, Inc |
| Mastercard, Inc |
| FIS |
| Visa, Inc |
| Volante Technologies, Inc |
| Finastra |
| NovoPayment, Inc |
| Others |
Value Network & Pricing Analysis
ISO 20022 certification tiers bifurcate the vendor landscape into premium API-native platforms and legacy core-dependent service providers, with FedNow compliance timelines compressing both pricing premiums and implementation cycles across the United States and Canada. This divergence concentrates margin capture among cloud-native challengers while forcing incumbent processors into defensive bundling strategies that subsidize core modernization through transactional volume commitments.
Pricing Analysis
Capacity additions in cloud-native core banking platforms are reshaping price floors for real-time payment infrastructure across North American financial institutions. Three-tier pricing structure across premium API-native, standard hybrid, and economy legacy-dependent levels dominates vendor contracts, with ISO 20022 certification grade and 24/7 operational uptime guarantees serving as primary price differentiation drivers. Cost compression in mid-market bank segments is intensifying because FedNow mandates eliminate batch-processing alternatives, while regional banks with $10B-$50B assets exhibit highest price sensitivity versus money-center institutions with captive technology units.
Supply Chain Analysis
Freight costs for specialized hardware components supporting 24/7 payment clearing infrastructure remain marginal compared to software licensing and implementation labor, which dominate total cost structures. Technology sourcing concentrates in the United States, Canada, and Ireland, with core banking software development anchored in financial services clusters near Toronto, New York, and Dublin. Raw material dependencies center on semiconductor components for payment terminals, cloud compute capacity from hyperscalers, and specialized engineering talent for ISO 20022 messaging integration. Single-source vulnerability in legacy core processor relationships creates concentration risk for regional banks facing FedNow deadlines. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving depository institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America real-time payment market functions as a geographic-arbitrage play between United States FedNow infrastructure investments and Canada's lagging 2025 Real-Time Rail timeline, with regulatory compliance cost differentials creating 18-24 month implementation windows for cross-border platform deployments.
For Market Incumbents: Cement defensible positioning through backward integration into cloud-native core processing capabilities, acquiring ISO 20022-specialist engineering teams before talent scarcity intensifies. FedNow master account exclusivity for depository institutions creates a structural moat, yet fintech front-end disintermediation threatens direct customer relationships—incumbents must control API gateway infrastructure to preserve transactional data flows and cross-sell opportunities.
For New Entrants and Emerging Players: Payments Canada's Real-Time Rail framework in Ontario and British Columbia opens a window for first-mover positioning among mid-market credit unions lacking internal modernization capacity. White-space targets include embedded payroll disbursement platforms for gig-economy staffing firms and Request-for-Pay bill presentment solutions for municipal utilities. A regulatory sandbox go-to-market angle accelerates pilot deployments with tier-2 banks seeking risk-mitigated FedNow participation.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional banks face $50M-plus core replacement decisions without proportional balance sheet scale to amortize investments. Long-term viability favors platform providers with recurring revenue models tied to transaction volume rather than project-based implementation fees. Acquisition target archetype: cloud-native core banking specialists with existing FedNow certifications and credit union client bases. The signal to watch is mid-market bank merger acceleration, which concentrates purchasing power among fewer institutions capable of demanding vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Master Account Acquisition | Unlocks 24/7 settlement finality for depository institutions competing with fintech disbursement speeds. |
| ISO 20022 Messaging Platform Integration | Enables straight-through reconciliation for corporate treasury departments automating accounts-payable workflows. |
| Embedded Banking Partnership Expansion | Distributes real-time disbursement capabilities into gig-economy payroll and merchant funding verticals. |
| Cloud-Native Core Migration | Collapses implementation timelines from 36 months to under 12 for mid-market bank FedNow readiness. |
| Request-for-Pay Product Launch | Displaces paper check and ACH debit workflows through bill-presentment-with-payment functionality. |
Research Methodology
Bottom-up depository institution modeling reconciled against top-down payment processor revenue tracking forms the analytical core of this study. Primary interviews with core banking executives, FedNow implementation leads at regional banks, fintech product managers, and corporate treasury officers combined with secondary validation against Federal Reserve payment system disclosures, Payments Canada infrastructure timelines, SEC 10-K filings from publicly traded processors, and NACHA operating rule amendments. Triangulation between transaction volume projections from financial institutions and infrastructure capacity investments from technology vendors ensures consistency across demand and supply-side estimates.
Input-output matrix framing connects macroeconomic variables to segment-specific transaction velocity assumptions across the projection horizon. Segmentation dimensions modeled include payment method, end-user category, transaction type, and service provider archetype, with ISO 20022 adoption curves and FedNow participation rates serving as industry-specific forecast inputs. CAGRs derive from logistic diffusion models applied to real-time payment adoption patterns, calibrated against historical ACH and wire transfer migration timelines.
Revisions become necessary when macroeconomic liquidity conditions shift corporate treasury behavior, regulatory timelines for Canadian Real-Time Rail slip, or core processor consolidation alters vendor pricing power. Forecasts reflect assumptions about continuous 24/7 operational readiness mandates and API-native infrastructure requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
APAC Mobile Payments Market
Payments
Bitcoin Payments Market
Payments
Japan Mobile Payments Market
Payments
Africa Virtual Cards Market
Payments
Retail Point of Sale (POS) Market
Payments
Japan Virtual Cards Market
Payments
Contactless Payment Ring Market
Payments
Mexico Real Time Payments Market
Payments
UK Virtual Cards Market
Payments
Malta POS Terminal Market
Payments
Digital Payment Market
Payments
Europe Payments Market
Payments
Vietnam E-Wallet Market
Payments
MENA Digital Payments Market
Payments
LAMEA Payment Gateway Market
Payments
Cyprus POS Terminals Market