
 GCC Mobile Banking Market | 2026-2036
GCC Mobile Banking Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Mobile Banking Market Intelligence
Saudi Arabia is rewriting digital finance infrastructure through its open banking framework and cloud-first data center investments. National Commercial Bank leverages extensive branch digitization to sustain retail deposit growth. Emirates NBD anchors corporate treasury services with API-linked liquidity tools. First Abu Dhabi Bank competes on cross-border remittance speed through its proprietary mobile stack.
GCC mobile banking encompasses smartphone-accessible financial services enabling real-time account operations, biometric-authenticated transactions, and API-integrated third-party payments without physical branch dependency. The architecture relies on TLS 1.3 encryption, sandboxed application environments, and ISO 20022 messaging standards to ensure interoperability across national clearing systems. Peer-to-Peer Transfers and Mobile Wallets dominate transaction volume as cash displacement accelerates across Gulf retail corridors. Millennials and Small Businesses represent the fastest-expanding customer pools, with the former driving wallet-based micro-payments and the latter demanding embedded invoicing and VAT reconciliation tools.
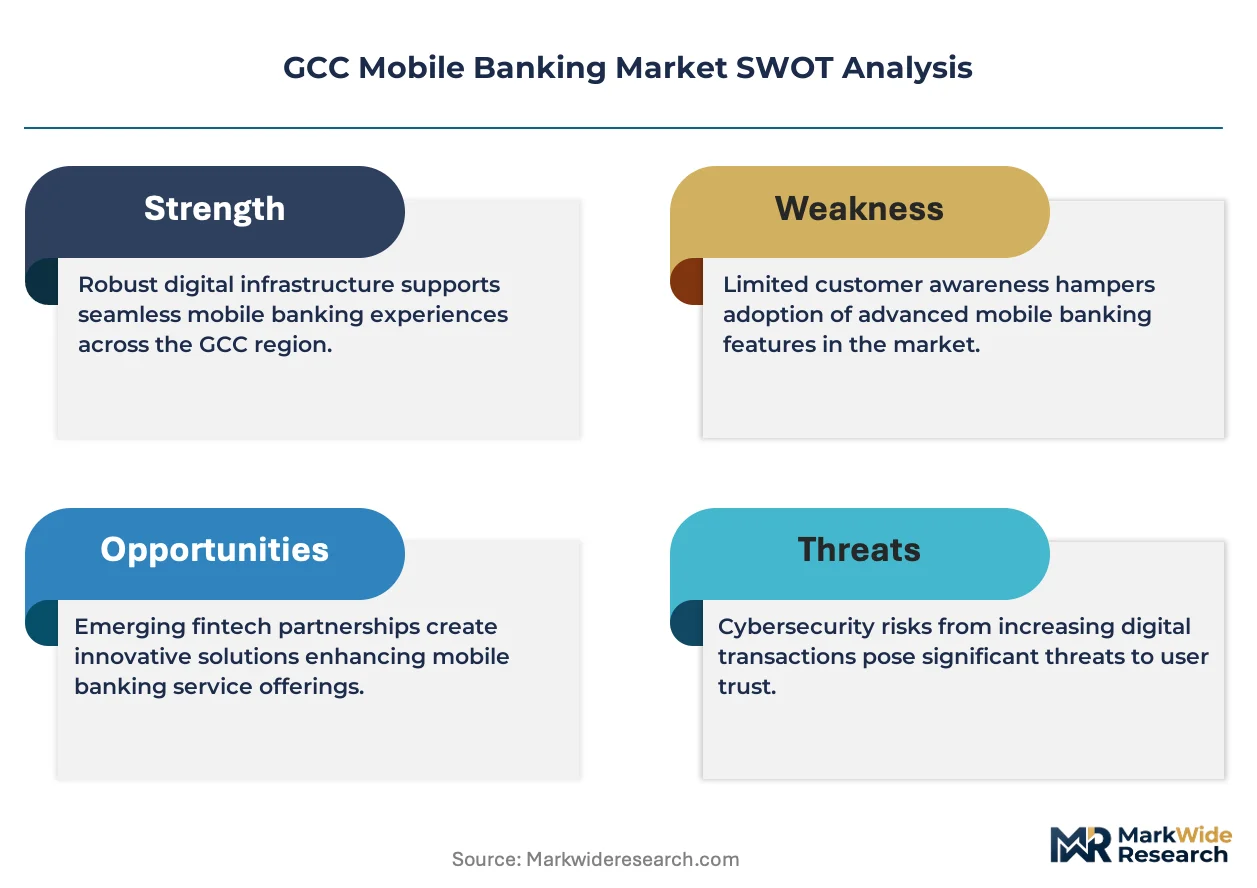
Saudi Arabia's SAMR and the UAE's central bank enforce mandatory multi-factor authentication and data localization for licensed mobile banking providers, raising barriers for unregulated fintech entrants. Bahrain's CBB and Qatar's QCB have introduced digital banking licenses with tiered capital requirements that channel investment toward full-stack challengers over payment-only apps. Stakeholders must weigh regulatory arbitrage opportunities against the compliance cost of obtaining multiple national permits across the six Gulf states.
Market Dynamics
Open banking mandates across Gulf states are forcing incumbent banks to dismantle their data silos and expose core banking APIs to licensed third parties, fundamentally restructuring competitive moats around interoperability rather than proprietary control.
Growth Catalysts
- SAMR Cybersecurity Framework:Saudi Arabia's mandatory penetration testing and encryption standards for financial apps are accelerating vendor consolidation toward enterprise-grade security stacks.
- Millennial wallet adoption:Biometric-authenticated peer-to-peer transfers are displacing cash in retail corridors across Dubai and Riyadh, concentrating transaction volume in mobile-native channels.
- Cloud-first data center investments:National Commercial Bank and Emirates NBD are migrating core systems to localized cloud infrastructure, enabling real-time scalability for transaction spikes during payroll cycles.
Market Restraints
- Data localization mandates:SAMR and the UAE central bank require customer records to reside within national borders, fragmenting infrastructure costs across six separate sovereign jurisdictions.
- API standard fragmentation:Bahrain's CBB and Qatar's QCB have adopted divergent open banking protocols, forcing providers to maintain multiple integration layers for cross-border service delivery.
- Talent scarcity in Gulf markets:Shortages of certified cloud security architects and ISO 20022 implementation specialists are inflating compensation costs for development teams.
Strategic Opportunities
- Oman and Kuwait underpenetration:These markets lack dedicated digital banking licenses, creating first-mover advantage for full-stack challengers willing to navigate dual regulatory approvals.
- Embedded finance convergence:API-integrated invoicing and VAT reconciliation tools for small businesses are merging mobile banking with enterprise resource planning workflows.
- Abu Dhabi's digital banking licenses:The ADGM framework permits 100% foreign ownership of neobanks, channeling venture capital toward proprietary mobile stack development.
Industry Challenges
- Legacy core banking integration:Mainframe-dependent institutions face 18-24 month timelines to achieve ISO 20022 messaging compatibility with national clearing systems.
- Multi-jurisdictional compliance:Obtaining permits across SAMR, UAE central bank, CBB, and QCB regimes demands parallel legal teams and divergent capital reserve calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Mobile Banking Market |
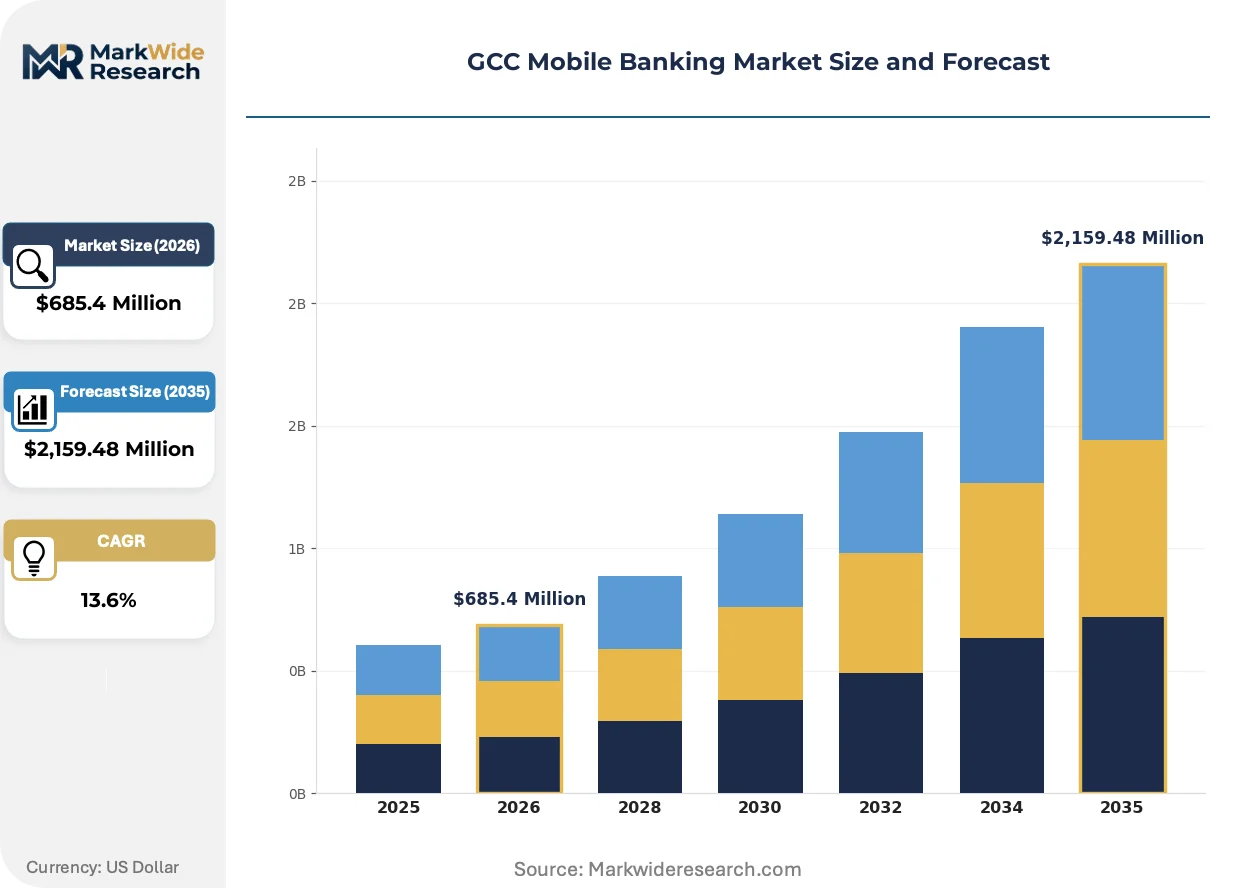
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,159.48 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer Transfers, Bill Payments, Account Management, Mobile Wallets Customer Type: Millennials, Retirees, Small Businesses, Corporates Platform: iOS, Android, Windows, Web Payment Method: Credit Card, Debit Card, Bank Transfer, NFC Payments |
| Companies Covered | National Bank of Kuwait, National Commercial Bank, Samba Financial Group, Abu Dhabi Commercial Bank, First Abu Dhabi Bank, Emirates NBD, Mashreq Bank, Dubai Islamic Bank, Qatar National Bank, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Mobile Banking Market Strategic Shifts & Innovations
Biometric authentication architectures and sandboxed application environments are displacing password-based security models across Gulf retail banking, while regulatory sandboxes in Dubai and Bahrain are compressing time-to-market for experimental payment products.
Tokenized payment credentials are migrating from hardware security modules to cloud-native vaults managed by licensed cloud service providers. Saudi banks are adopting this shift fastest, driven by SAMR mandates for elastic infrastructure during seasonal pilgrimage transaction surges. The migration from on-premise HSMs is compressing capital expenditure cycles and enabling pay-per-transaction pricing models for smaller institutions.
The UAE central bank's mandatory multi-factor authentication directive is compelling banks to phase out SMS-based one-time passwords in favor of FIDO2-compliant biometric protocols. This regulatory pressure is accelerating vendor consolidation around certified authentication platforms. Corporate treasury services are responding fastest, with API-linked liquidity tools now requiring hardware-backed biometric verification for transactions exceeding threshold limits.
Small business owners are unbundling traditional branch relationships in favor of embedded mobile workflows that combine invoice generation, VAT calculation, and instant settlement. This behavioral pivot is most visible in Dubai's free zones, where cross-border traders demand real-time multi-currency reconciliation without physical documentation. Neobanks are capturing this segment through proprietary mobile stacks that integrate directly with customs and logistics platforms.
GCC Mobile Banking Market Segmentation
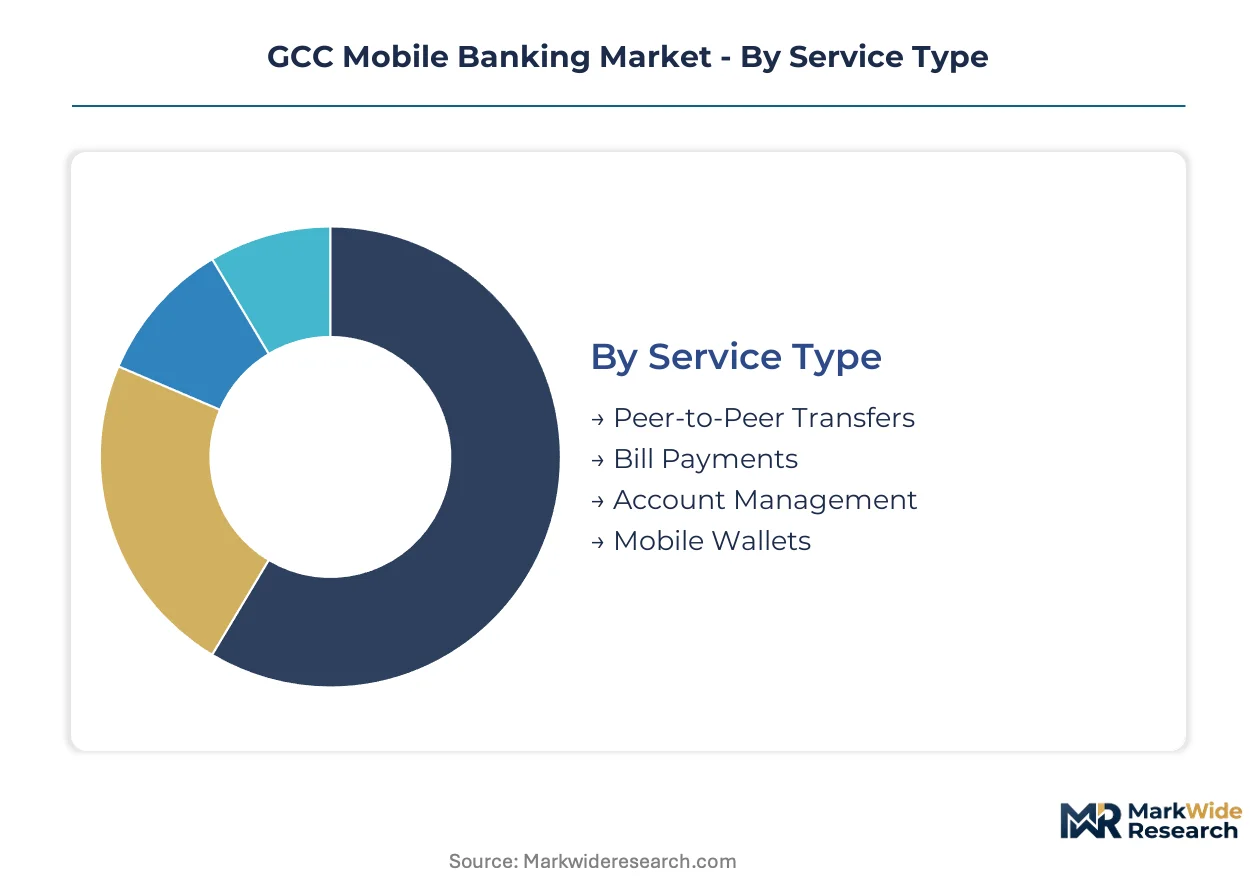
Mobile banking architectures across Gulf states require distinct service configurations for peer-to-peer velocity versus corporate treasury complexity. Customer behavioral patterns diverge sharply between biometric-native millennials and documentation-dependent retirees, forcing parallel platform development tracks.
Service Type:
Transaction cycle times vary dramatically — peer-to-peer settlements clear in seconds while corporate account reconciliation stretches across multi-day batch windows. Mobile wallets and instant transfers turn over fastest; bill payment aggregation and full-service account management move slowest due to regulatory verification layers.
- Peer-to-Peer Transfers:Real-time settlement rails leveraging ISO 20022 messaging and biometric authentication. Dubai's retail corridors and Riyadh's commercial districts concentrate demand as cash displacement accelerates among unbanked labor populations. SAMR mandates for transaction traceability are tightening audit trail requirements.
- Mobile Wallets:Tokenized credential vaults with sandboxed application environments and FIDO2-compliant access protocols. Abu Dhabi's free zone traders and Bahrain's cross-border remittance corridors drive adoption for multi-currency holding. The UAE central bank's multi-factor authentication directive is phasing out SMS-based verification.
- Bill Payments:Aggregated utility and government service interfaces with scheduled settlement capabilities. Saudi Arabia's SADAD integration dominates public sector collections.
- Account Management:Full-service dashboards combining balance inquiry, statement retrieval, and cross-border transfer initiation. Qatar's QCB licensing framework imposes tiered capital reserves for providers offering comprehensive functionality.
Mobile Wallets dominate installed base across Gulf retail corridors. Peer-to-Peer Transfers are where expansion concentrates as biometric authentication displaces cash in high-velocity payment environments.
Customer Type:
Acquisition cost tiers separate digitally native segments from documentation-intensive onboarding requirements. Millennials and small businesses command lower per-customer acquisition spend; retirees and corporates demand branch-assisted verification and compliance overhead.
- Millennials:Smartphone-native users prioritizing biometric-authenticated micro-payments and social payment splitting. Dubai's fintech sandbox and Riyadh's entertainment districts concentrate this demographic. SAMR cybersecurity frameworks mandate penetration testing for apps serving high-volume retail users.
- Small Businesses:Embedded finance demanders requiring invoice generation, VAT reconciliation, and instant settlement in unified workflows. Abu Dhabi's digital banking licenses are channeling venture capital toward proprietary mobile stacks serving this segment.
- Corporates:Treasury departments requiring API-linked liquidity tools and multi-user authorization hierarchies. Emirates NBD anchors this tier with threshold-based biometric verification.
- Retirees:Branch-dependent users transitioning to assisted digital channels with voice-guided interfaces and in-person support fallback. Bahrain's CBB consumer protection mandates require simplified dispute resolution pathways.
Small Businesses dominate installed base through embedded workflow penetration. Millennials are climbing the fastest as biometric authentication compresses onboarding friction.
Platform:
Development resource allocation tracks device fragmentation and security architecture divergence. iOS and Android consume parallel engineering teams; Windows and Web platforms run lean with browser-based deployment.
- iOS:Apple's secure enclave integration and App Store vetting protocols. UAE and Saudi Arabia's affluent consumer segments concentrate here. The UAE central bank mandates device attestation for high-value transaction authorization.
- Android:Fragmented hardware ecosystem requiring sandboxed application environments across multiple OEM security implementations. Gulf labor populations and mid-market segments dominate this install base. SAMR encryption standards force vendor consolidation toward enterprise-grade security stacks.
- Windows:Enterprise desktop integration for corporate treasury workstations with hardware security module compatibility. Limited mobile-native functionality.
- Web:Browser-based access for cross-platform consistency and rapid feature deployment without app store latency. Fallback channel for device-limited users.
Android dominates installed base across Gulf labor markets and mid-tier consumers. iOS is gaining share fastest in premium segments as device attestation becomes mandatory for high-value authorization.
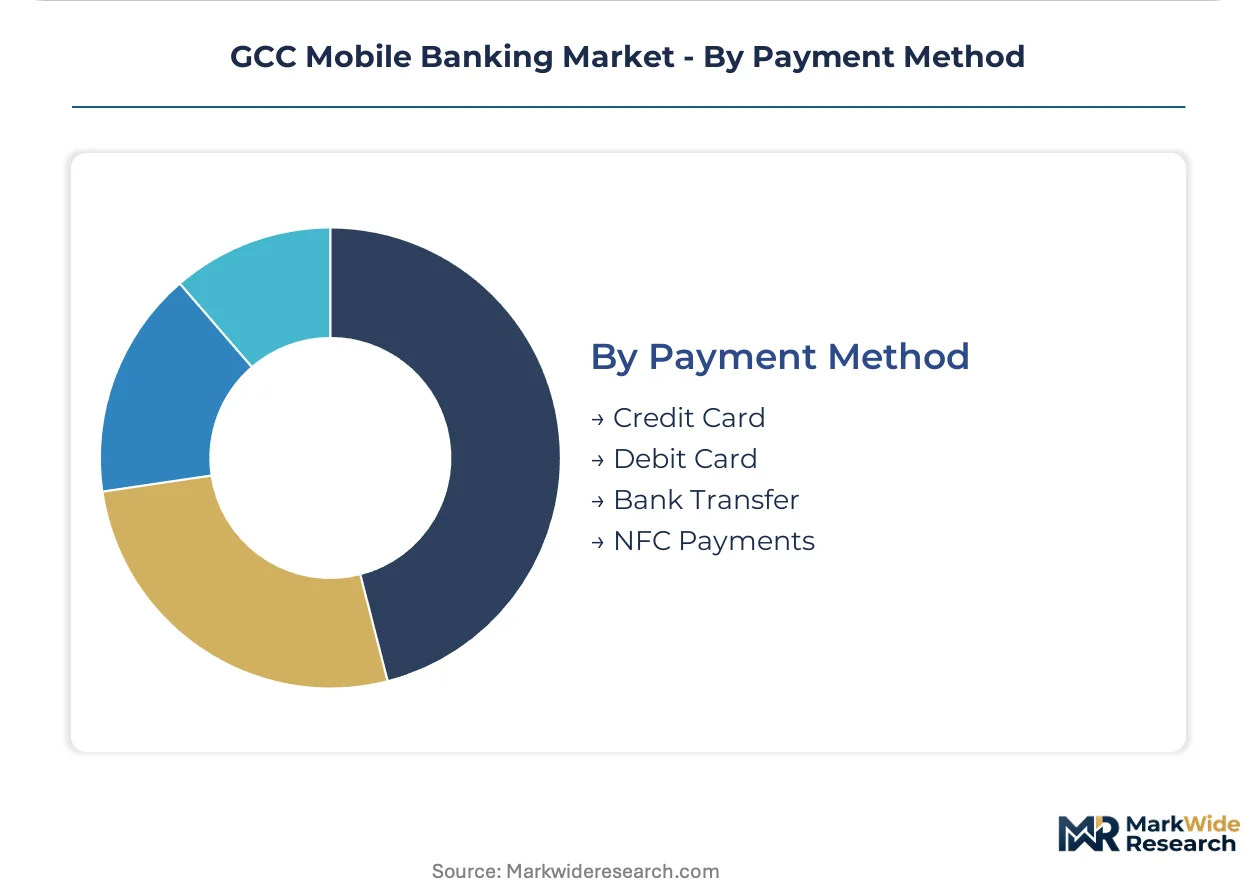
Payment Method:
Interchange cost structures and settlement velocity differentiate method selection. NFC payments and bank transfers minimize friction; card-based methods carry network fee burdens and chargeback exposure.
- NFC Payments:Contactless tokenized credentials with hardware-backed secure element storage. Dubai's retail corridors and Riyadh's quick-service restaurant chains concentrate tap-to-pay adoption. The UAE central bank's multi-factor authentication directive accelerates biometric-linked NFC deployment.
- Bank Transfer:Direct account-to-account settlement through national clearing systems with ISO 20022 messaging. Saudi Arabia's SADAD and UAE's UAEFTS rails dominate B2B and payroll applications. SAMR data localization mandates require domestic hosting of transfer records.
- Debit Card:Real-time authorization against available balances with lower interchange rates than credit products. Mass-market retail penetration across Gulf states.
- Credit Card:Revolving credit lines with rewards program integration and chargeback protection. Affluent consumer segments and travel-heavy users concentrate here.
Bank Transfer dominates installed base through payroll and B2B settlement concentration. NFC Payments are expanding most quickly as contactless infrastructure proliferates across Gulf retail environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's cybersecurity framework anchors Saudi Arabia's dominance in GCC mobile banking infrastructure, with regulatory mandates forcing enterprise-grade security investments across the six-nation bloc. The UAE's central bank and Bahrain's CBB have introduced parallel licensing regimes that fragment compliance requirements while concentrating venture capital in Abu Dhabi and Dubai.
Saudi Arabia
Riyadh's fintech corridor and Jeddah's commercial districts drive demand for real-time payroll settlement and pilgrimage-season transaction scalability. SAMR mandates penetration testing and data localization for all licensed providers, raising operational barriers for cross-border entrants. National Commercial Bank leverages extensive branch digitization to sustain retail deposit growth across the Kingdom.
United Arab Emirates
Dubai's fintech sandbox and Abu Dhabi's digital banking licenses channel concentrated investment toward neobank development and proprietary mobile stacks. The UAE central bank enforces mandatory multi-factor authentication and is phasing out SMS-based passwords in favor of FIDO2 biometric protocols. Emirates NBD anchors corporate treasury services with API-linked liquidity tools targeting cross-border traders in Dubai's free zones.
Qatar
Doha's financial district generates demand for multi-currency reconciliation and instant settlement among energy-sector corporates and cross-border trading houses. QCB's tiered digital banking licenses impose capital reserve requirements that favor full-stack challengers over payment-only applications. Qatar National Bank competes on speed through proprietary mobile infrastructure integrated with national clearing systems.
Bahrain
Manama's regulatory sandbox compresses time-to-market for experimental payment products while attracting Gulf-wide fintech testing. CBB consumer protection mandates require simplified dispute resolution pathways for branch-dependent retirees transitioning to assisted digital channels. The Kingdom's cross-border remittance corridors concentrate mobile wallet adoption among labor populations seeking low-cost transfer options.
Kuwait
Kuwait City lacks dedicated digital banking licenses, creating first-mover advantage for institutions willing to navigate dual regulatory approvals with SAMR or UAE frameworks. National Bank of Kuwait sustains market position through embedded finance workflows combining invoice generation, VAT reconciliation, and instant settlement for small businesses. Underpenetration relative to Saudi Arabia and the UAE attracts venture capital seeking expansion beyond saturated core markets.
GCC Mobile Banking Market Key Industry Players
Legacy banking conglomerates and digital-native challengers split the market along infrastructure depth versus speed-to-market vectors. The competitive terrain shows moderate consolidation around institutions with existing deposit bases and regulatory relationships. Three archetypes dominate: branch-digitized incumbents leveraging physical networks for customer acquisition, cloud-native neobanks competing on onboarding friction, and Islamic banking specialists capturing faith-aligned segments. Dominant moves include API partnership strategies with enterprise resource planning platforms and migration of core systems to localized cloud infrastructure.
Within the branch-digitized incumbent tier, National Commercial Bank and Emirates NBD occupy positions anchored by extensive physical networks and corporate treasury relationships. First Abu Dhabi Bank represents the cross-border remittance specialist archetype, competing on settlement velocity through proprietary mobile infrastructure. These institutions exemplify how regulatory licensing advantages and existing customer bases create defensive moats against unregulated fintech entrants across the six Gulf states.
| Leading Market Players |
|---|
| National Bank of Kuwait |
| National Commercial Bank |
| Samba Financial Group |
| Abu Dhabi Commercial Bank |
| First Abu Dhabi Bank |
| Emirates NBD |
| Mashreq Bank |
| Dubai Islamic Bank |
| Qatar National Bank |
| Others |
Cost & Logistics Intelligence
Single-source dependency on hyperscale cloud infrastructure determines both tiered pricing spreads and supply chain configuration across GCC mobile banking. SAMR data localization mandates fragment infrastructure deployment across six sovereign jurisdictions, forcing providers to absorb redundant hosting costs that compress margin structures at the economy tier while enabling premium pricing for localized compliance.
Pricing Analysis
Pricing spreads widen significantly between Riyadh and Manama, with Saudi Arabia's enterprise-grade security requirements commanding 40-60% premiums over Bahrain's sandbox-licensed alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies around ISO 20022 certification status, FIDO2 biometric protocol implementation, and localized cloud hosting compliance. Cost compression in the standard tier is intensifying because unregulated fintech entrants are undercutting licensed providers on transaction fees. Small businesses demonstrate highest price sensitivity, while corporate treasury departments prioritize API reliability over per-transaction economics.
Supply Chain Analysis
Upstream feedstock for mobile banking infrastructure draws from concentrated cloud service provision in Saudi Arabia, the UAE, and Bahrain, with hyperscale data center capacity expanding fastest in Riyadh and Dubai. Core dependencies include TLS 1.3 encryption modules, sandboxed application environments, and ISO 20022 messaging protocol stacks. Single-source vulnerability concentrates in certified biometric authentication vendors, where FIDO2-compliant platform providers number fewer than five across the entire Gulf region. Distribution runs through direct API licensing to incumbent banks, neobank full-stack partnerships, and embedded finance integrations with enterprise resource planning platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a regulatory compliance investment cycle, with SAMR and UAE central bank mandates now stabilizing into enforceable frameworks that reward early movers.
For Market Incumbents: Harden API security architectures against unregulated fintech substitution by accelerating FIDO2 biometric protocol deployment across all customer touchpoints. Consolidate vendor relationships around certified cloud security stacks to reduce fragmentation costs from multi-jurisdictional compliance. Deepen backward integration into localized data center infrastructure to capture margin from SAMR-mandated domestic hosting requirements.
For New Entrants and Emerging Players: Pursue white-space opportunities in Omani and Kuwaiti markets where dedicated digital banking licenses remain absent, creating first-mover advantage for full-stack challengers willing to navigate dual regulatory approvals. Target small business embedded finance segments in Dubai's free zones, where invoice-VAT-settlement workflow integration remains underdeveloped. Anchor go-to-market strategy through direct customs and logistics platform partnerships rather than consumer-facing acquisition.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors proprietary mobile stack developers with existing SAMR or UAE central bank licensing. Long-term viability hinges on regulatory relationship depth rather than pure technology differentiation across the five-to-ten year horizon. Acquisition targets should demonstrate ISO 20022 messaging compatibility and localized cloud infrastructure deployment. Watch for QCB and CBB license tier adjustments as the primary inflection signal for cross-border expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Mobile Stack Development | Reduces API licensing dependency and accelerates SAMR compliance certification timelines. |
| Localized Cloud Infrastructure Migration | Satisfies SAMR data localization mandates while enabling elastic scalability during payroll cycles. |
| FIDO2 Biometric Protocol Deployment | Meets UAE central bank multi-factor authentication directives phasing out SMS-based verification. |
| Embedded Finance ERP Integration | Captures small business demand for unified invoice-VAT-reconciliation workflows in Abu Dhabi's free zones. |
| Cross-Border Remittance Velocity Investment | Competes with First Abu Dhabi Bank's settlement speed through proprietary national clearing integration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with digital banking product managers, cloud security architects, regulatory compliance officers at SAMR and UAE central bank, and small business treasury heads across Dubai's free zones. Secondary validation incorporated SAMR cybersecurity framework documentation, UAE central bank licensing circulars, CBB sandbox approval records, ISO 20022 implementation guidelines, and hyperscaler data center expansion disclosures. Bottom-up transaction volume modeling and top-down regulatory capacity assessment were triangulated to anchor projections.
Calibration against historical adoption curves for biometric authentication and open banking API penetration informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, customer archetype, platform ecosystem, and payment method, with regulatory jurisdiction clustering as an additional cross-cutting variable. CAGRs were derived from installed base growth rates adjusted for compliance-driven vendor consolidation and cloud infrastructure capacity expansion timelines. Forecast inputs incorporated pilgrimage-season transaction surge patterns and payroll cycle concentration effects.
Sensitivities concentrate around SAMR enforcement intensity shifts, CBB-QCB license tier harmonization, and hyperscaler cloud pricing volatility. Forecasts embed assumptions regarding sustained millennial wallet adoption velocity and small business embedded finance penetration. Cross-checking against disclosed neobank funding rounds and regulatory sandbox graduation rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Smart Machines in Banking Market
Banking
Banking CRM Software Market
Banking
Africa Data Analytics in Banking Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Europe Neobanking Market
Banking
Japan Data Analytics in Banking Market
Banking
Mobile Banking Market
Banking
North America Machine Learning in Banking Market
Banking
UK Banking as a Service Market
Banking
Retail Banking IT Spending Market
Banking
Voice Banking Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Bank Kiosk Market
Banking
Cloud Computing Banking Market
Banking
Letter of Credit Confirmation Market
Banking
North America Challenger Banks Market