
 Smart Machines in Banking Market | 2026-2036
Smart Machines in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Machines in Banking Market Analysis
Buyer concentration among retail banks is shifting as tier-one institutions consolidate vendor relationships while mid-tier banks fragment procurement across specialized providers. SAP leverages its enterprise resource planning footprint to anchor large-scale core banking transformations. Temenos competes through cloud-native architecture designed for modular deployment. Infosys sustains delivery scale across AI-powered fraud detection and customer analytics engagements.
Smart machines in banking encompass autonomous software and hardware systems that process transactions, assess risk, and interact with customers through natural language interfaces operating at sub-second response thresholds. These systems serve the primary commercial purpose of reducing operational cost intensity while maintaining regulatory compliance across high-volume financial workflows. The technology dimension shows AI and machine learning commanding the dominant share of new investment as banks replace rules-based engines with adaptive models. Within applications, fraud detection occupies the deepest margin pools due to quantifiable return on investment from loss prevention, while customer service automation represents the fastest expansion trajectory as conversational agents handle routine inquiries.
The Federal Reserve, SEC, and EU AI Act collectively shape product standards by mandating auditability of algorithmic credit decisions and transparency in automated customer interactions. Banks must demonstrate human oversight mechanisms and bias testing protocols to satisfy supervisory examinations in both jurisdictions. Stakeholders should monitor evolving guidance on model risk management as regulators tighten expectations for third-party AI vendor accountability.
Market Dynamics
Core banking modernization is compressing deployment cycles as institutions replace legacy mainframes with cloud-native platforms capable of real-time transaction processing and embedded AI decisioning.
Growth Catalysts
- EU AI Act compliance mandates:Banks across Germany, France, and Italy are procuring explainable AI systems to satisfy auditability requirements for automated credit decisions, creating immediate demand for transparent machine learning architectures.
- Real-time payment infrastructure:The Federal Reserve's FedNow service and equivalent instant payment schemes in Japan and India are forcing banks to deploy sub-second fraud detection engines that only smart machine architectures can sustain.
- Conversational banking interfaces:Natural language processing capabilities are electrifying customer service automation as retail banks seek to deflect routine inquiries from high-cost branch and call center operations.
Market Restraints
- Specialized AI talent scarcity:Machine learning engineers with financial domain expertise command compensation premiums that mid-tier banks struggle to match, constraining in-house development capacity.
- Cloud infrastructure concentration:Hyperscaler dominance in compute and storage services creates vendor lock-in risks and cost volatility for banks building smart machine deployments.
- Model interpretability limitations:Deep neural networks for fraud detection often resist explanation, creating regulatory friction under SEC and EU AI Act transparency mandates.
Strategic Opportunities
- Mid-tier bank automation gap:Regional institutions in Spain, Canada, and Australia lag tier-one peers in intelligent automation deployment, presenting vendor expansion opportunities.
- Embedded finance convergence:Smart machines enabling real-time risk scoring are facilitating partnerships between banks and non-financial platforms for point-of-sale lending and BNPL services.
- Regulatory sandbox participation:Japan's FSA and the UK's FCA are offering supervised testing environments for novel AI-driven compliance tools, accelerating time-to-market for validated solutions.
Industry Challenges
- Legacy system integration complexity:COBOL-based core banking platforms resist API connectivity, forcing expensive middleware layers that degrade smart machine response times.
- Model risk management skill gaps:Banks lack sufficient personnel trained in SR 11-7 and EU AI Act model validation protocols, delaying production deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Machines in Banking Market |
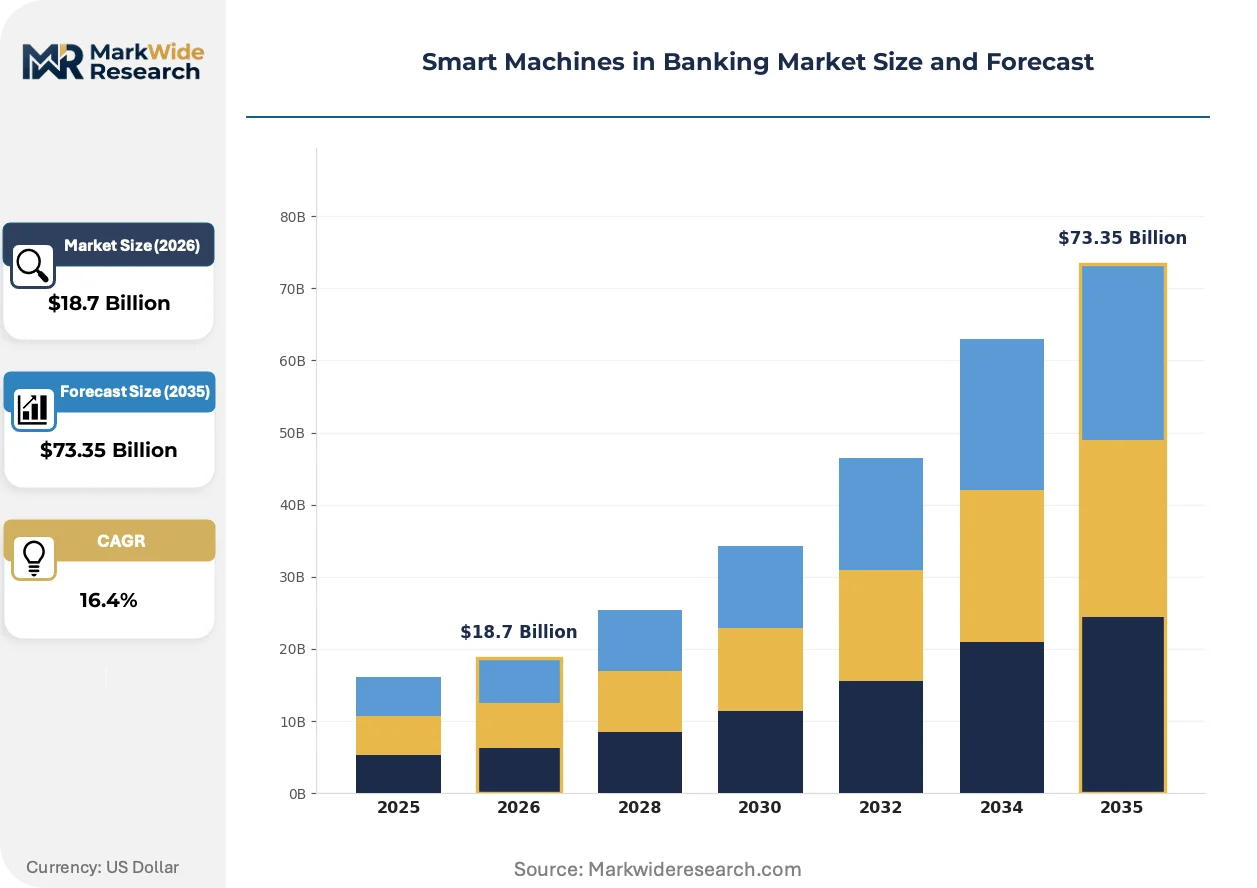
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Machine Learning, Robotics, Blockchain Service Type: Consulting, Maintenance, Support, Integration Application: Fraud Detection, Customer Service, Risk Management, Compliance End User: Retail Banks, Investment Banks, Credit Unions, Payment Processors |
| Companies Covered | Backbase, Q2, SAP, Technisys, Alkami, Infosys, Temenos, Urban FT, Finastra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Machines in Banking Market Emerging Trajectories
Adaptive AI architectures are displacing static rules engines across transaction processing, risk assessment, and customer interaction workflows. Three developments are compressing competitive timelines.
Neural network-based fraud detection is electrifying loss prevention capabilities by identifying anomalous patterns across payment streams in milliseconds. Tier-one retail banks in the United States and Germany are deploying these systems at scale. The technology is compressing fraud-to-detection latency from minutes to sub-second intervals, reducing recoverable loss exposure.
The EU AI Act's risk-based classification framework is forcing banks to restructure algorithmic governance. High-risk credit scoring systems now require human oversight mechanisms and bias testing documentation. Institutions are responding by establishing dedicated model risk committees and third-party validation partnerships.
Conversational agents are displacing interactive voice response systems in customer service channels. Retail banks in Japan and the United Kingdom are deploying multilingual natural language interfaces for routine account inquiries. This shift is most visible in mobile banking applications where resolution rates for password resets and balance queries now exceed automated thresholds without human escalation.
Smart Machines in Banking Market Segmentation
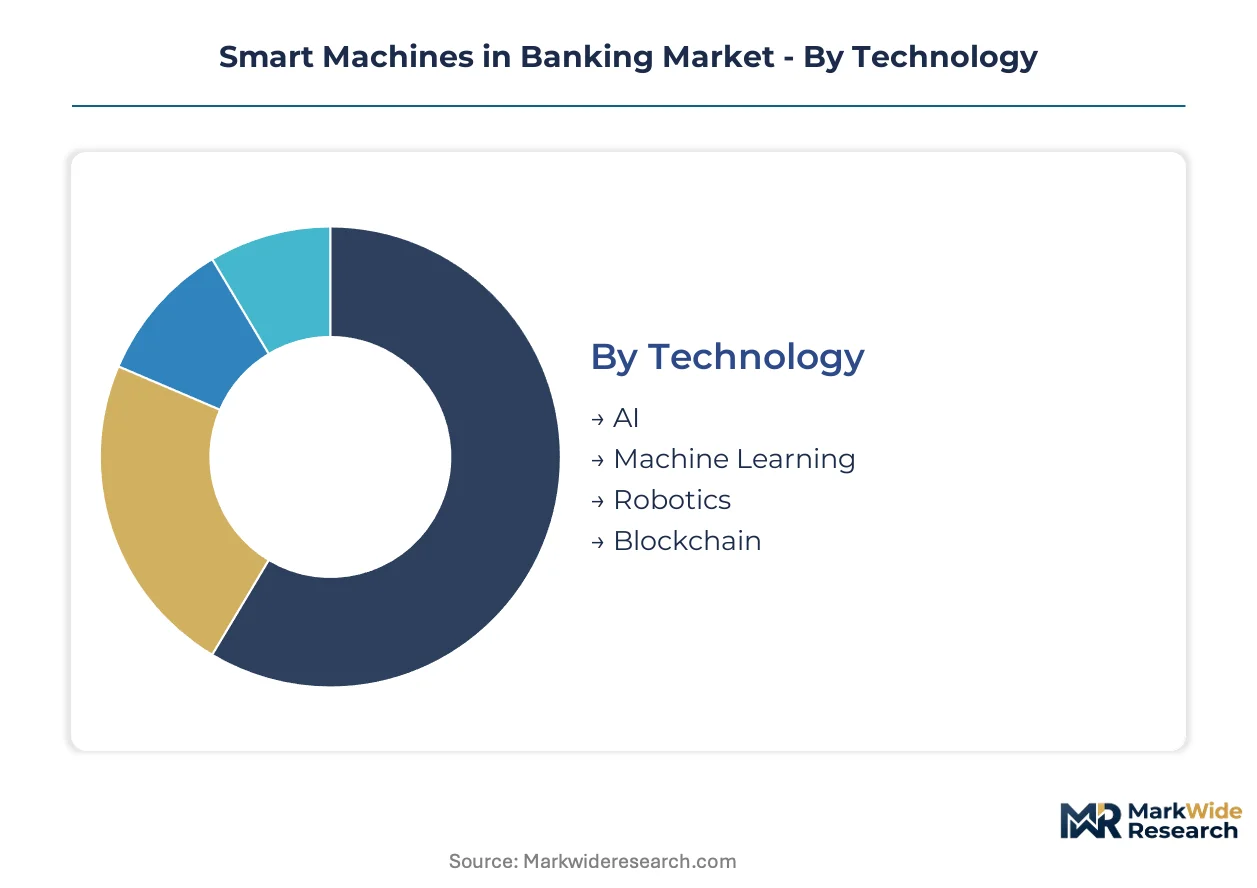
Segmentation in smart machines for banking reveals how technology architecture, service delivery models, and institutional use cases create distinct procurement patterns. Banks prioritize segments offering measurable operational leverage against regulatory compliance costs.
Technology:
Standardization dominates foundational layers while customization concentrates at the application tier where competitive differentiation resides.
- AI:Neural networks and large language models power real-time credit scoring and conversational interfaces. United States retail banks deploy these systems most aggressively as FedNow infrastructure demands sub-second decisioning.
- Machine Learning:Supervised learning algorithms for transaction pattern recognition and anomaly detection require continuous retraining on proprietary bank data. German institutions lead procurement volumes driven by EU AI Act documentation requirements for model interpretability.
- Robotics:Physical automation in cash handling and branch operations.
- Blockchain:Distributed ledger architectures for cross-border settlement and identity verification.
Most installed capacity flows through Machine Learning. Expansion is steepest in AI.
Service Type:
Cost tier stratification separates high-touch advisory engagements from commoditized operational support, with integration services commanding premium pricing due to legacy system complexity.
- Consulting:Strategic advisory for AI governance framework design and model risk committee structuring. Japanese banks utilize these services heavily as the FSA tightens third-party vendor accountability guidelines.
- Integration:Middleware development connecting cloud-native smart machines to COBOL core banking platforms. Mid-tier banks in Spain and Australia drive demand as they modernize without full core replacement.
- Maintenance:Continuous model monitoring and drift detection services.
- Support:Technical assistance for API connectivity and runtime troubleshooting.
Integration services capture the largest contract values. Support services are expanding most quickly as deployment scale increases.
Application:
Application maturity varies sharply, with fraud detection offering proven ROI while compliance automation navigates evolving regulatory specifications.
- Fraud Detection:Real-time transaction scoring using ensemble models across payment streams. Investment banks in the United States deploy these most intensively as SEC examination priorities elevate cybersecurity expectations.
- Customer Service:Conversational agents and virtual assistants handling routine inquiries. Credit unions in Canada adopt these fastest to offset limited branch network coverage.
- Risk Management:Credit portfolio stress testing and market risk calculation engines.
- Compliance:Automated regulatory reporting and audit trail generation systems.
Fraud Detection absorbs the deepest technology investment. Customer Service is gaining share fastest as resolution thresholds improve.
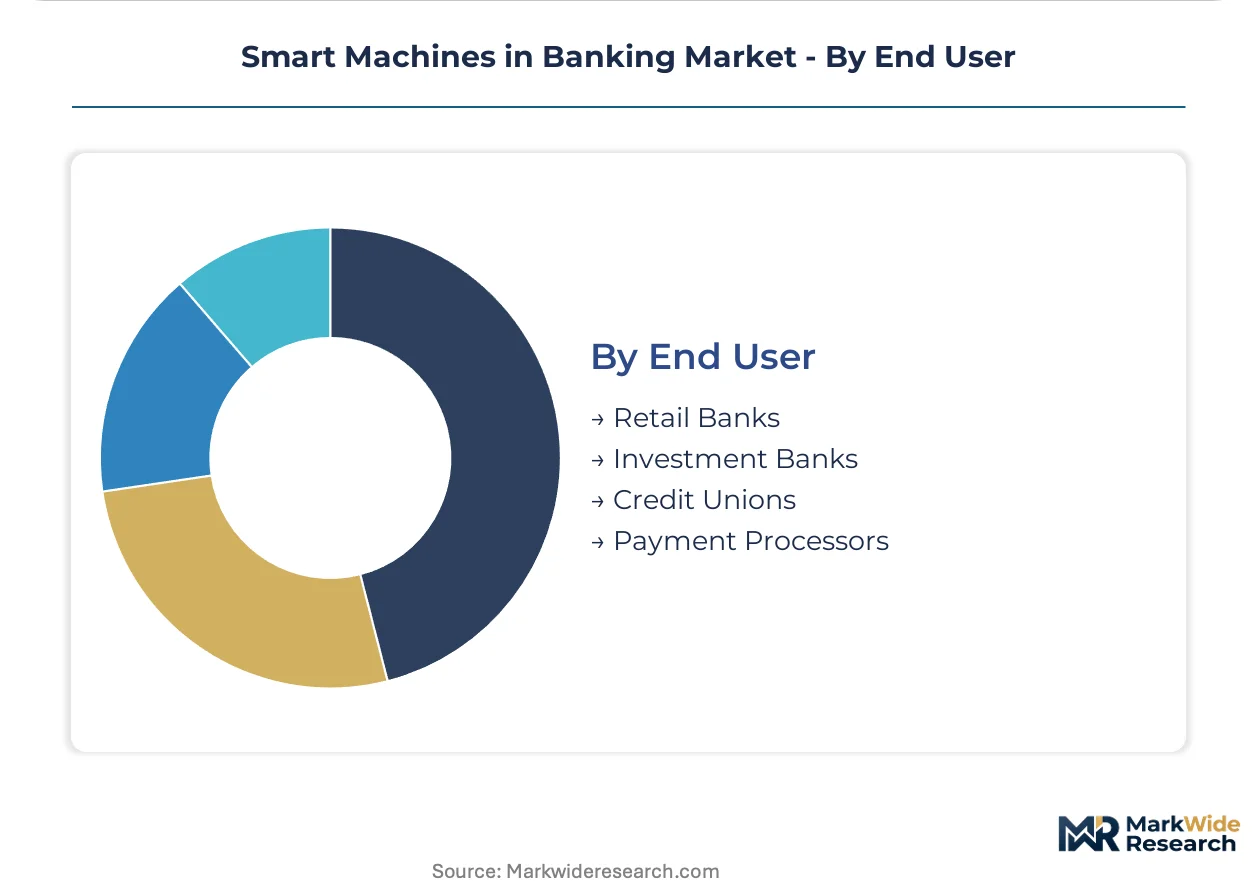
End User:
Customer type determines procurement sophistication, with tier-one retail banks consolidating vendors while specialized players seek modular solutions.
- Retail Banks:Full-stack smart machine deployments spanning branches, digital channels, and back-office operations. These institutions dominate absolute spending volumes across Germany, Japan, and the United States.
- Payment Processors:High-velocity fraud detection and settlement optimization systems. Real-time payment infrastructure mandates in India and Brazil accelerate their technology refresh cycles.
- Investment Banks:Algorithmic trading surveillance and market abuse detection platforms.
- Credit Unions:Limited-scope automation targeting member service and loan origination efficiency.
Retail Banks command the majority of installed systems. Payment Processors show the steepest expansion trajectory as instant payment networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail banks outpace Japanese institutions in explainable AI procurement volumes, while the United States dominates absolute spending on real-time fraud detection infrastructure. Regulatory divergence between the EU AI Act and SEC examination priorities is creating distinct technology deployment patterns across these three markets. Canada and Australia represent emerging demand centers where mid-tier institutions are accelerating modernization timelines.
United States
FedNow instant payment infrastructure is forcing sub-second fraud detection deployment across tier-one retail banks. The SEC's elevated cybersecurity examination priorities are accelerating investment in algorithmic surveillance systems. New York and Charlotte banking clusters are consolidating vendor relationships around cloud-native core transformation platforms.
Germany
EU AI Act documentation requirements for automated credit decisions are driving procurement of interpretable machine learning architectures. BaFin's tightening third-party vendor accountability guidelines are reshaping model risk committee structures. Frankfurt's concentration of universal banks is establishing dedicated AI governance frameworks ahead of supervisory deadlines.
Japan
FSA regulatory sandbox participation is accelerating time-to-market for novel AI-driven compliance tools among megabanks. Real-time payment infrastructure mandates are forcing legacy mainframe modernization in Tokyo and Osaka. Kanto region institutions are deploying multilingual conversational agents for routine customer service automation.
Canada
Credit unions are adopting customer service automation fastest to offset limited branch network coverage in Prairie Provinces. OSFI guidance on model risk management is elevating third-party validation partnerships. Toronto and Vancouver banking clusters are procuring modular smart machine solutions rather than full-stack replacements.
Australia
APRA's tightening expectations for operational resilience are driving investment in real-time transaction monitoring systems. Mid-tier banks in Sydney and Melbourne are lagging tier-one peers in intelligent automation deployment. Regional institutions are fragmenting procurement across specialized providers rather than consolidating around single vendors.
Smart Machines in Banking Market Vendor Landscape
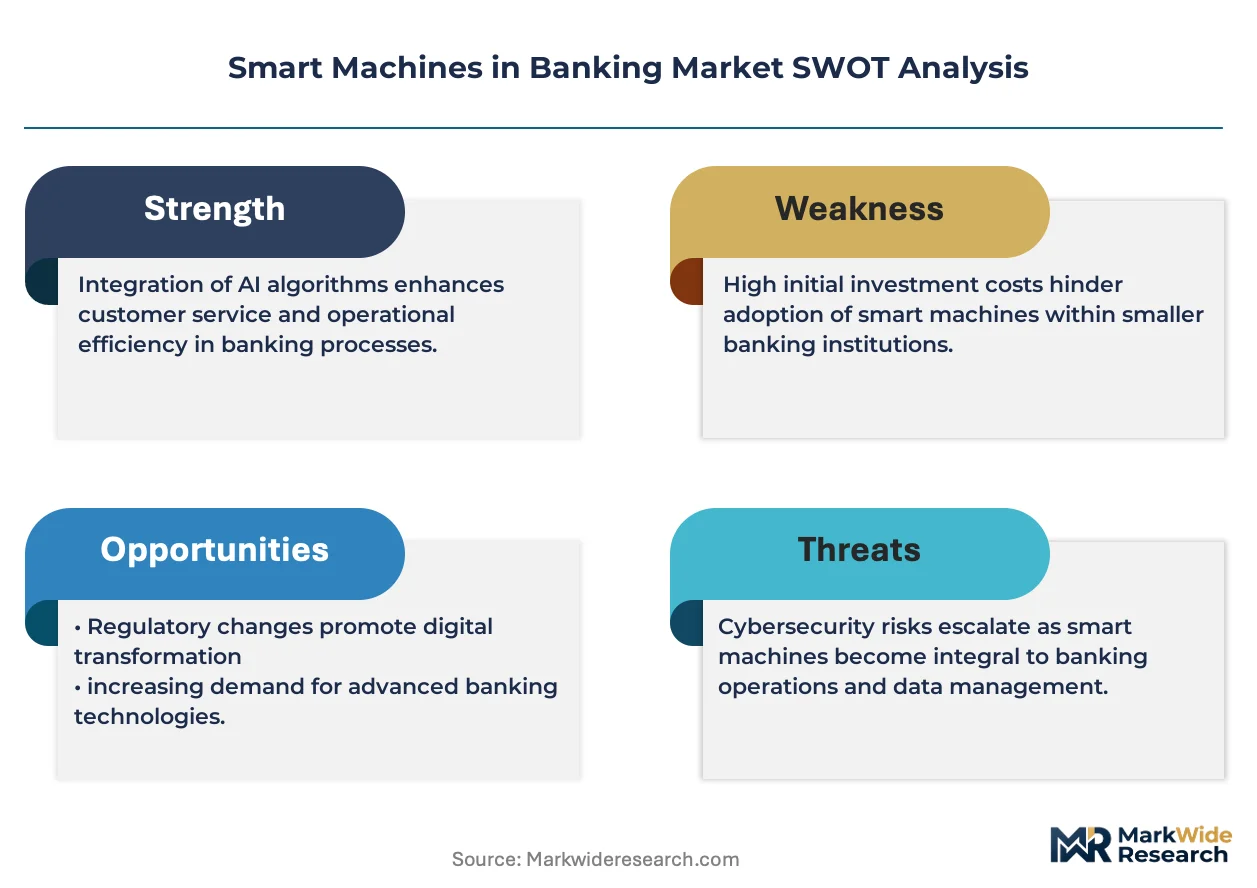
Diversified conglomerates compete with focused pure-play specialists across the smart machines in banking landscape. The market exhibits tiered consolidation where enterprise resource planning incumbents anchor large-scale transformations while cloud-native challengers capture modular deployment opportunities. Three archetypes dominate: full-stack platform providers, specialized AI engine developers, and system integration specialists. Competitive moves concentrate on strategic partnerships with hyperscalers and vertical integration into model risk management services.
Within the full-stack platform tier, SAP and Temenos represent contrasting architectural philosophies for core banking transformation. SAP leverages its enterprise resource planning footprint to anchor comprehensive modernization programs, while Temenos competes through modular cloud-native deployment options. Infosys occupies a distinct position as a system integration specialist sustaining delivery scale across AI-powered fraud detection and customer analytics engagements. These three entities exemplify how vendor selection increasingly hinges on legacy system complexity rather than feature differentiation alone.
| Leading Market Players |
|---|
| Backbase |
| Q2 |
| SAP |
| Technisys |
| Alkami |
| Infosys |
| Temenos |
| Urban FT |
| Finastra |
| Others |
Supply Flow & Price Mechanics
EU AI Act documentation mandates gate qualified supply access and premium-tier pricing for explainable AI architectures, as vendors must demonstrate bias testing protocols and human oversight mechanisms to serve German and French retail banks. Compliance-certified machine learning engines command substantial premiums over black-box alternatives, while non-compliant providers face exclusion from procurement shortlists at tier-one institutions.
Pricing Analysis
Capacity additions in cloud-native core banking platforms are reshaping price floors for integration services as hyperscaler competition intensifies. Three-tier pricing structure across premium, standard, and economy levels separates FedNow-compliant sub-second fraud detection from batch-processing legacy systems. Price differentiation centers on model interpretability certification and real-time processing guarantees. Cost compression in standard-tier maintenance contracts is intensifying because mid-tier banks fragment procurement across specialized providers rather than consolidating vendors.
Supply Chain Analysis
GPU and specialized AI accelerator supply rests on Taiwanese semiconductor foundries and South Korean memory producers, with United States-based chip design houses anchoring upstream IP. Smart machine deployment draws from cloud compute infrastructure, proprietary banking data lakes, and open-source machine learning frameworks. Single-source vulnerability concentrates in hyperscaler compute services where AWS, Azure, and GCP dominate bank infrastructure decisions. Distribution runs through direct enterprise sales teams and systems integration partners with financial domain expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart machines in banking represent a stable compounder underpinned by regulatory mandates that perpetually refresh technology replacement cycles. Compliance-driven procurement creates durable demand visibility regardless of macroeconomic credit cycles.
For Market Incumbents: Deploy model risk management service extensions to capture recurring revenue from EU AI Act validation requirements. SAP and Temenos should deepen API connectivity layers for COBOL core banking platforms to defend against cloud-native challengers. Incumbents face substitution threat from modular AI engine developers unburdened by legacy architecture constraints.
For New Entrants and Emerging Players: Regional system integrators in Spain and Australia present the most penetrable channel partner type for mid-tier bank automation gaps. New entrants should target credit unions in Canada seeking customer service automation without full-stack vendor dependency. A compliance-as-a-service go-to-market angle bypasses incumbent scale advantages in core banking transformation.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized fraud detection engine developers lacking platform breadth. Long-term viability over a five-to-ten-year window favors vendors with FedNow certification and EU AI Act interpretability documentation. Acquisition target archetype: machine learning shops with financial domain expertise and established model validation partnerships. Watch regulatory sandbox graduation rates from Japan's FSA as inflection indicator for novel AI compliance tool commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Certification Investment | BaFin and SEC auditability requirements force documentation capabilities into competitive table stakes. |
| FedNow Integration Partnership | Real-time payment infrastructure mandates create exclusive vendor relationships with early-certified fraud detection providers. |
| Model Risk Committee Outsourcing | Mid-tier banks lacking SR 11-7 expertise purchase governance-as-a-service from specialized consultancies. |
| Regulatory Sandbox Participation | Japan's FSA supervised testing environments accelerate time-to-market for novel compliance automation tools. |
| COBOL Middleware Acquisition | Legacy system connectivity expertise commands premium valuations as cloud-native deployment depends on mainframe bridges. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Canada, and Australia, with primary inputs from each market informing demand segmentation. The analysis combines structured interviews with chief information officers at retail banks, model risk officers, procurement leads at payment processors, and regulatory affairs specialists with secondary validation against SEC examination priorities, EU AI Act implementation guidance, and FSA sandbox disclosures. Bottom-up deployment estimates triangulate against top-down banking IT spending benchmarks from central bank statistical releases and industry association surveys.
Granularity-level modeling distinguishes technology architecture choices, service delivery models, and institutional use cases across the projection horizon. The analytical framework segments by AI, machine learning, and robotics technology types; consulting, integration, maintenance, and support service tiers; fraud detection, customer service, risk management, and compliance applications; and retail banks, payment processors, investment banks, and credit unions as end users. CAGRs derive from fitted growth curves anchored to documented modernization timelines and regulatory compliance deadlines. Forecast inputs include FedNow adoption trajectories, EU AI Act enforcement phase-ins, and real-time payment infrastructure buildouts across target markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement intensity and hyperscaler pricing volatility. Forecasts reflect assumptions about sustained compliance investment appetite and cloud migration continuity that could revise materially if macroeconomic credit contraction freezes discretionary IT spending. A small set of triggers—SEC cybersecurity examination priority shifts, EU AI Act high-risk system designation expansions, and FSA sandbox program modifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Predictive Analytics in Banking Market
Banking
E-Banking Market
Banking
North America Machine Learning in Banking Market
Banking
Biometric Banking Wristband Market
Banking
Australia Neobanking Market
Banking
Disaster Recovery in Banking Market
Banking
Global Certificate of Deposit Market
Banking
Germany Banking As a Service Market
Banking
North America Challenger Banks Market
Banking
Cardless ATM Market
Banking
UK Retail Banking Market
Banking
Data Analytics in Banking Market
Banking
Merchant Banking Services Market
Banking
Blockchain in Retail Banking Market
Banking
Global Neo and Challenger Bank Market
Banking
Global Banking Systems Software Market