
 Europe Neobanking Market | 2026-2036
Europe Neobanking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Neobanking Market Foresight
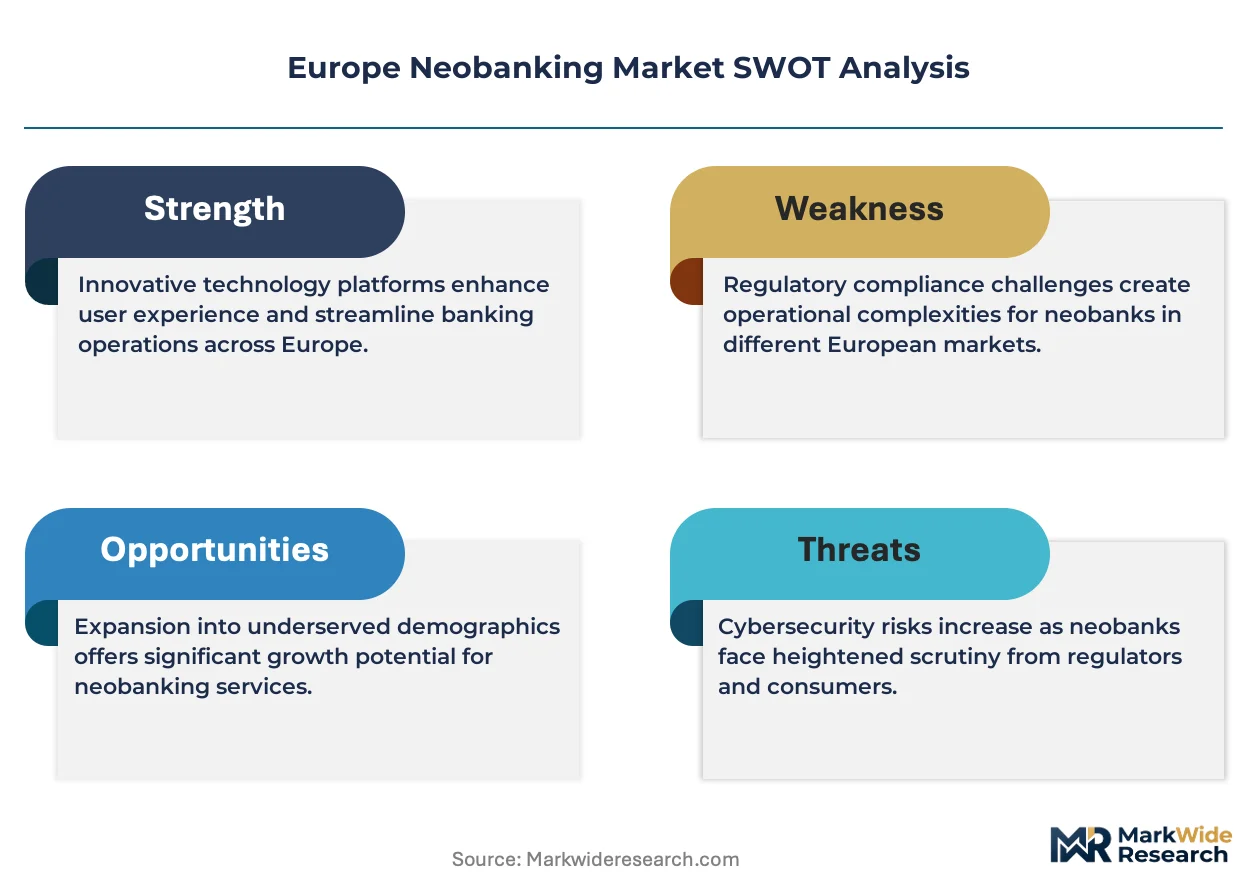
SME banking engagement is restructuring how European neobanks allocate product development resources. Revolut leverages its multi-currency infrastructure to serve cross-border traders. Bunq anchors its growth in the Netherlands and Belgium through sustainability-linked deposit products. N26 competes aggressively on user experience simplicity across German-speaking markets.
A neobank operates as a licensed financial institution delivering deposit, payment, and lending services through software-native channels without physical branch networks, typically provisioning accounts via mobile applications with real-time transaction processing and API-based third-party integrations. Personal banking services dominate current revenue pools across the Europe Neobanking Market, though payment solutions extract higher transaction-frequency margins. Business accounts represent the fastest-expanding service type as sole proprietors and micro-enterprises abandon legacy branch relationships. Mobile apps remain the primary technology interface, while blockchain-based settlement infrastructure still occupies niche pilot status among established players.
PSD2 and the EU AI Act shape product roadmaps by mandating transparent algorithmic decision-making for credit and fraud systems. The European Banking Authority's supervisory standards on digital operational resilience force neobanks to elevate cybersecurity expenditure. EBA stress-testing protocols and national deposit guarantee schemes determine market access sequencing across member states. Stakeholders must weigh licensing jurisdiction selection against passporting complexity as regulatory divergence between EU and post-Brexit UK frameworks deepens.
Market Dynamics
PSD2-mandated open banking interfaces are forcing legacy institutions to expose customer data APIs, eroding their deposit-gathering advantage and accelerating account migration toward software-native competitors.
Growth Catalysts
- PSD2 Data Sharing Mandates:The EU directive compels traditional banks to open customer transaction histories via standardized APIs. Neobanks leverage this feedstock to deliver faster credit decisions and personalized financial management tools.
- Millennial Digital-First Preference:German consumers under age 40 demonstrate the continent's highest mobile banking penetration rates. This cohort's rejection of branch-based relationships concentrates demand in Berlin, Munich, and Hamburg metropolitan corridors.
- Embedded Finance Infrastructure:Banking-as-a-Service platforms enable non-financial brands to embed deposit and payment products. Retailers and logistics firms across the Netherlands and Belgium now white-label neobank cores.
Market Restraints
- Deposit Guarantee Scheme Fragmentation:National guarantee ceilings vary between €100,000 and lower thresholds in select member states. This divergence complicates cross-border marketing and passporting strategies.
- Core Banking Software Concentration:Three vendors dominate cloud-native core systems for European neobanks. Supply bottlenecks in Frankfurt and London data centers constrain scaling velocity.
- Interest Rate Compression:Prolonged low-rate environments compress net interest margins on floating-rate deposit products. Treasury teams struggle to generate yield without duration risk exposure.
Strategic Opportunities
- Polish and Romanian SME Banking:Business account penetration in Warsaw and Bucharest remains below Western European benchmarks. Local regulatory sandboxes now permit restricted licensing for foreign entrants.
- EU AI Act Algorithmic Transparency:The regulation mandates explainable credit scoring models. Early compliance investments position neobanks to capture risk-averse corporate treasury clients.
- Blockchain Settlement Pilots:Convergence between distributed ledger infrastructure and real-time gross settlement systems is modularizing correspondent banking relationships. Estonia and Lithuania host active central bank digital currency experiments.
Industry Challenges
- Cloud Infrastructure Talent Scarcity:Kubernetes and zero-trust architecture specialists command premium compensation in Berlin and Amsterdam. Recruitment timelines stretch to six months for senior platform engineers.
- EBA Digital Operational Resilience Certification:The European Banking Authority's DORA framework demands redundant data center architectures. Compliance capex burdens early-stage entrants disproportionately.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Neobanking Market |
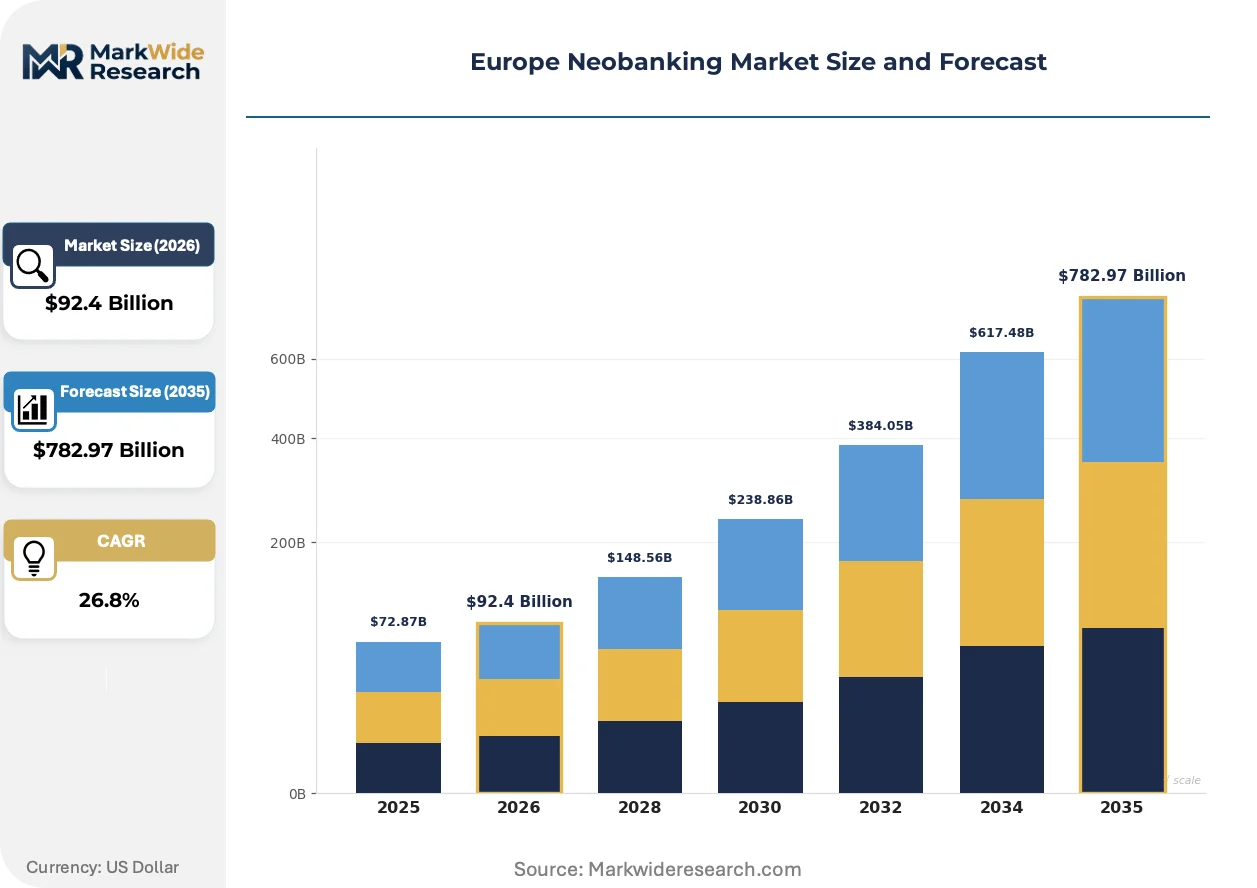
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $782.97 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Individuals, Small Businesses, Startups, Enterprises Service Type: Personal Banking, Business Accounts, Payment Solutions, Investment Services Technology: Mobile Apps, Web Platforms, APIs, Blockchain Offering: Loans, Savings Accounts, Insurance, Wealth Management |
| Companies Covered | Bunq, Starling Bank, Revolut, Viva Wallet, Trade Republic, Nubank, N26, Raisin, Monzo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Neobanking Market Shifts & Advancements
Real-time payment infrastructure and AI-native fraud detection are compressing the feature gap between neobanks and legacy institutions, while sustainability-linked deposit products capture ESG-conscious retail flows.
Embedded finance orchestration layers are modularizing how non-bank brands provision financial services. E-commerce platforms and mobility apps in Stockholm and Copenhagen now integrate deposit-taking and lending through API-connected neobank infrastructure. This disintermediation compresses customer acquisition costs while fragmenting deposit ownership across sector boundaries.
The EU AI Act's risk-classification framework for algorithmic credit decisions is forcing model governance investments. Automated decision systems scoring SME loans face mandatory human-in-the-loop requirements and audit trail obligations. German and French neobanks are responding by hiring ethics officers and retraining decision trees to satisfy supervisory scrutiny.
Subscription-based pricing for premium banking features is displacing free basic-tier models across Nordic markets. Young professionals in Oslo and Helsinki demonstrate willingness to pay monthly fees for enhanced analytics and cryptocurrency trading access. This behavioral shift reduces reliance on interchange revenue and stabilizes recurring income streams.
Europe Neobanking Market Segmentation
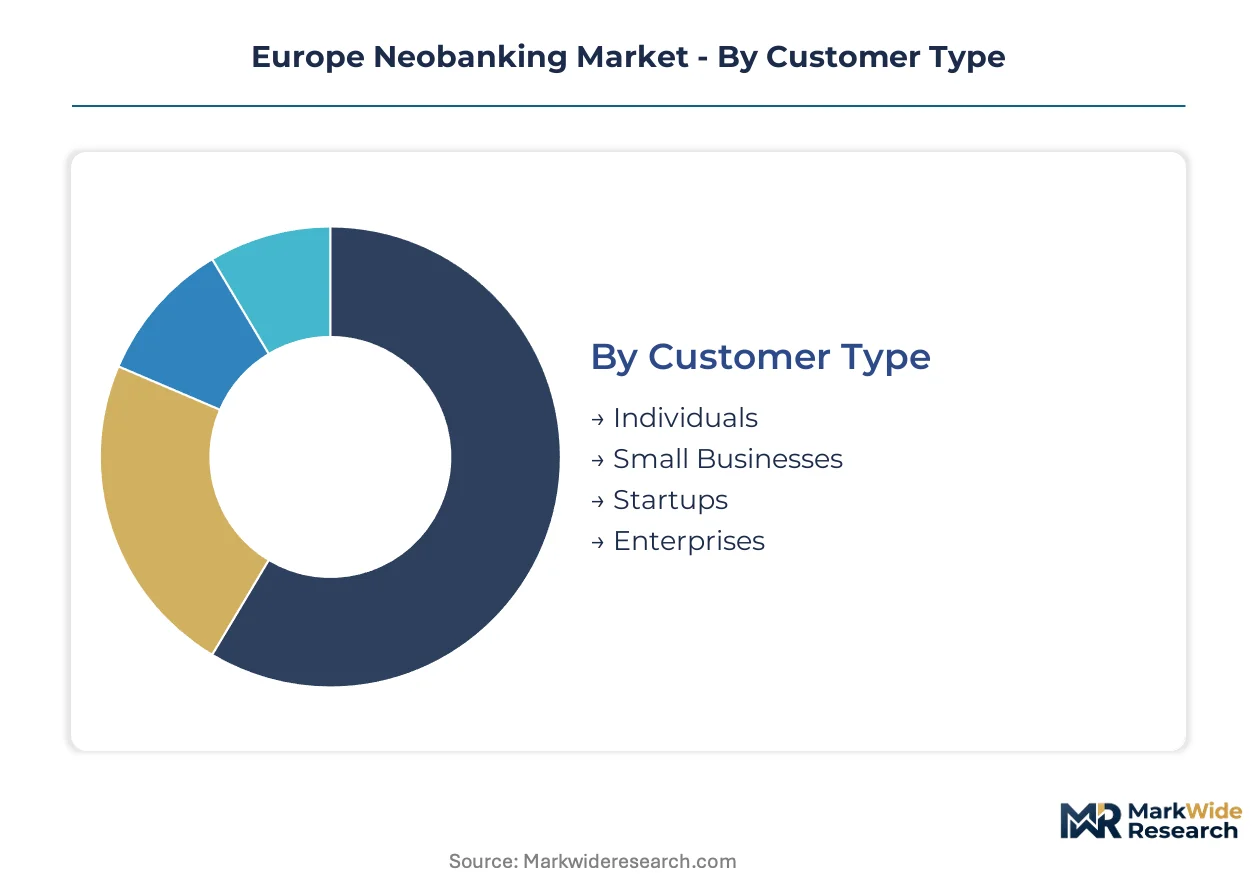
Neobank product portfolios fragment across customer lifecycle stages and technical delivery modes. Each segment demands distinct regulatory compliance postures and capital allocation strategies. Understanding these divides clarifies where software-native institutions concentrate development resources against legacy competition.
Customer Type:
Upgrade cycles vary sharply across customer sophistication tiers, with retail users migrating fastest from branch-based relationships while enterprise procurement demands extended due diligence.
- Individuals:Digital-native consumers under 40 in Berlin, Munich, and Hamburg drive mobile-first account openings. Their rejection of physical branch networks concentrates marketing spend on app store optimization and referral incentives.
- Small Businesses:Sole proprietors and micro-enterprises abandon legacy relationships for real-time invoicing and multi-currency capabilities. Polish and Romanian SME penetration remains below Western benchmarks, creating expansion corridors for licensed entrants.
- Startups:Venture-backed companies prioritize API-first treasury infrastructure and instant cap table management. Regulatory sandboxes in Estonia and Lithuania permit restricted licensing for foreign players targeting this cohort.
- Enterprises:Corporate treasury departments demand explainable credit scoring under EU AI Act mandates. Human-in-the-loop requirements and audit trail obligations extend sales cycles but yield stickier deposit relationships.
Individuals sits at the top of the volume ranking, with Small Businesses climbing the fastest.
Service Type:
Application intensity determines margin structure, with high-frequency payment solutions extracting transaction-based revenue while lending products require heavier capital reserves.
- Personal Banking:Deposit and payment services dominate current revenue pools across the European market. German millennials demonstrate the continent's highest mobile banking penetration, concentrating demand in metropolitan corridors.
- Business Accounts:Fastest-expanding service type as micro-enterprises abandon branch relationships. Real-time invoicing and automated tax categorization displace manual bookkeeping workflows.
- Payment Solutions:Higher transaction-frequency margins than deposit products. PSD2-mandated APIs enable neobanks to aggregate legacy bank data for consolidated financial management.
- Investment Services:Subscription-based pricing for cryptocurrency trading and fractional equity access is displacing free basic-tier models across Nordic markets. Oslo and Helsinki professionals demonstrate willingness to pay monthly fees for enhanced analytics.
Personal Banking captures the largest revenue base, though Business Accounts are expanding most quickly.
Technology:
Maturity curves separate proven delivery channels from experimental infrastructure, with mobile dominance established and blockchain still occupying pilot status.
- Mobile Apps:Primary technology interface for account provisioning and real-time transaction processing. User experience simplicity drives competitive positioning in German-speaking markets.
- Web Platforms:Secondary access point for complex treasury operations and bulk payment approvals. Corporate clients in Amsterdam and Frankfurt demand desktop-optimized workflows.
- APIs:Banking-as-a-Service platforms enable non-financial brands to embed deposit products. Retailers and logistics firms across the Netherlands and Belgium now white-label neobank cores.
- Blockchain:Distributed ledger infrastructure occupies niche pilot status among established players. Estonia and Lithuania host active central bank digital currency experiments.
Mobile Apps leads deployment volume, with APIs gaining share fastest through embedded finance proliferation.
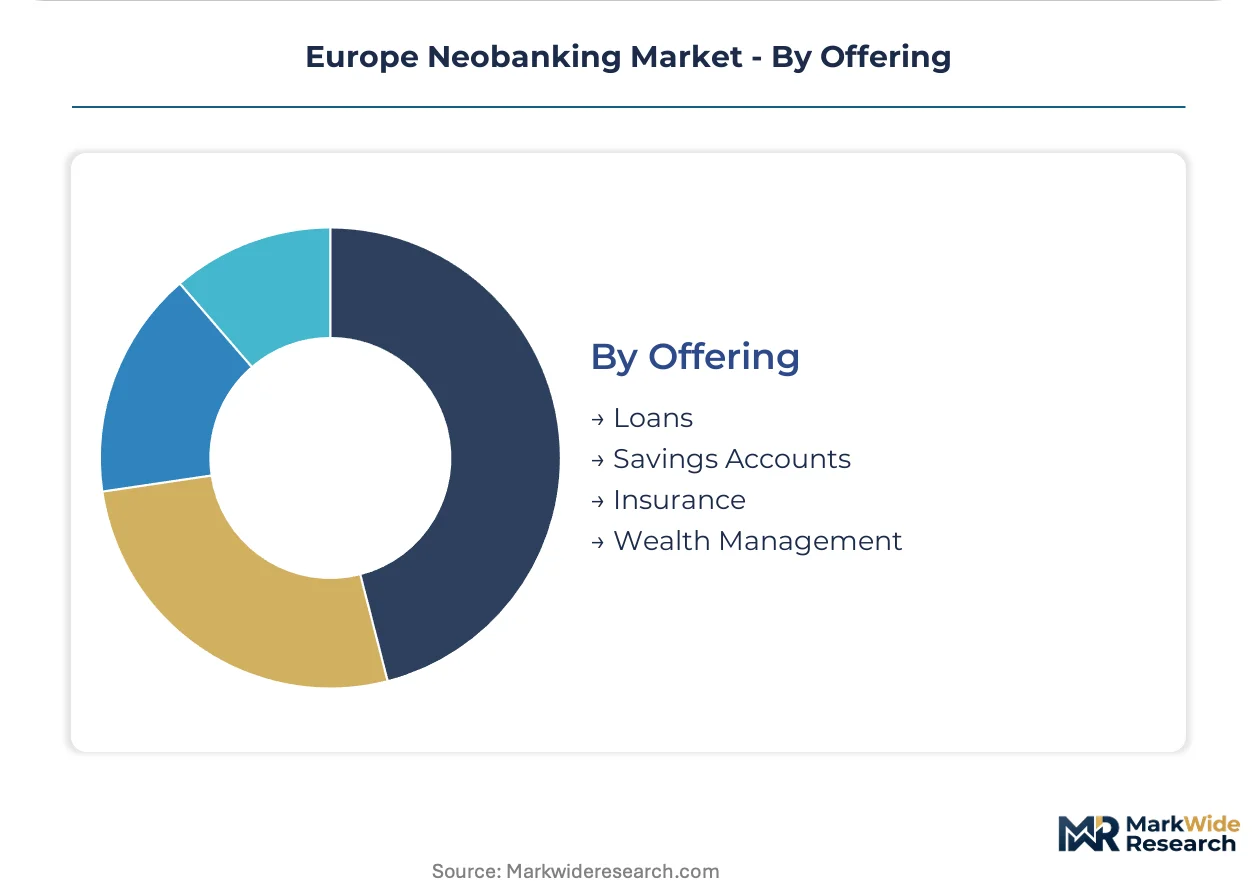
Offering:
Margin concentration follows regulatory complexity, with simple deposit products facing rate compression and wealth management requiring specialized licensing.
- Loans:Algorithmic credit decisions face mandatory human-in-the-loop requirements under EU AI Act risk-classification frameworks. German and French neobanks hire ethics officers to satisfy supervisory scrutiny.
- Savings Accounts:Sustainability-linked deposit products capture ESG-conscious retail flows in the Netherlands and Belgium. Bunq anchors growth through carbon-footprint-linked interest tiers.
- Insurance:Embedded distribution through mobile interfaces displaces traditional broker relationships. Partnership models with licensed underwriters limit capital intensity.
- Wealth Management:Automated portfolio construction and tax-loss harvesting attract high-net-worth segments. Subscription pricing reduces reliance on interchange revenue and stabilizes recurring income.
Savings Accounts holds the largest deposit base, with Wealth Management following the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where neobanks domicile their licensed entities, with Lithuania and Estonia attracting restricted-license applicants seeking lower compliance burdens than Germany or France. This migration concentrates operational hubs in Baltic capitals while revenue-generating customer bases remain in Western European metropolitan corridors.
Germany
Millennial and Gen Z consumers in Berlin, Munich, and Hamburg demonstrate Europe's highest mobile banking penetration rates. BaFin's supervisory standards on digital operational resilience force substantial cybersecurity expenditure from licensed entrants. Frankfurt's fintech cluster anchors back-office infrastructure for passporting strategies across the single market.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks complicates passporting for UK-domiciled neobanks serving continental customers. The Financial Conduct Authority's open banking standards preceded PSD2 implementation, creating early-mover API infrastructure advantages. London's Square Mile and Shoreditch tech corridor concentrate product development and regulatory compliance functions.
Netherlands
ESG-conscious retail deposit flows concentrate in Amsterdam and Rotterdam metropolitan areas, driving sustainability-linked product innovation. De Nederlandsche Bank's national deposit guarantee scheme operates at the standard €100,000 ceiling. Eindhoven's embedded finance ecosystem enables retailers and logistics firms to white-label neobank cores.
France
Corporate treasury departments in Paris and Lyon demand explainable credit scoring under EU AI Act mandates, extending sales cycles but yielding stickier relationships. Autorité de Contrôle Prudentiel et de Résolution supervision requires human-in-the-loop requirements for automated lending decisions. La Défense financial district hosts compliance and risk management operations.
Poland
SME business account penetration in Warsaw remains below Western European benchmarks, creating expansion corridors for foreign entrants. The Polish Financial Supervision Authority's regulatory sandbox permits restricted licensing experiments. Kraków's technology outsourcing cluster supplies cloud infrastructure and platform engineering talent.
Europe Neobanking Market Competitive Landscape
Strategic partnerships dominate the current landscape as software-native institutions seek distribution through non-financial brands. The vendor base fragments across three tiers: pan-European passporting specialists, single-market sustainability-focused deposit gatherers, and embedded finance infrastructure providers. Two strategic archetypes predominate: API-first platforms enabling white-label banking services, and mobile-native consumer apps competing on user experience simplicity. Geographic expansion through regulatory passporting and portfolio diversification into wealth management represent the dominant competitive moves.
Within the pan-European passporting tier, Revolut and N26 exemplify multi-jurisdiction licensing strategies that leverage single-market authorization for cross-border customer acquisition. Bunq occupies a position within the sustainability-linked deposit segment, anchoring growth through ESG-conscious product differentiation in the Netherlands and Belgium. Starling Bank represents the embedded finance infrastructure archetype, supplying Banking-as-a-Service capabilities to non-financial brands seeking modular financial service integration.
| Leading Market Players |
|---|
| Bunq |
| Starling Bank |
| Revolut |
| Viva Wallet |
| Trade Republic |
| Nubank |
| N26 |
| Raisin |
| Monzo |
| Others |
Supply & Pricing Matrix
Millennial and Gen Z demand for instant account provisioning and zero-fee foreign exchange is compressing subscription pricing tiers while forcing neobanks to renegotiate cloud infrastructure contracts and API gateway fees. This procurement pressure cascades through Banking-as-a-Service intermediaries, squeezing margin pools at the platform layer and accelerating consolidation among core banking software vendors.
Pricing Analysis
Direct-to-consumer subscription tiers anchor the pricing architecture, with three-tier pricing structure across premium, standard, and economy levels differentiating by feature depth and customer support access. Price differentiation hinges on API call volume allowances and multi-currency transaction ceilings. Cost compression in the standard tier is intensifying because embedded finance providers are white-labeling neobank infrastructure at scale. Micro-enterprises and sole proprietors demonstrate highest price sensitivity, while venture-backed startups show lowest sensitivity due to treasury automation priorities.
Supply Chain Analysis
Single-source vulnerability sits with Frankfurt and London data centers, where three cloud-native core banking vendors concentrate licensed capacity. Geographic supply concentration centers on Germany, the Netherlands, and Estonia for regulatory sandbox access and passporting infrastructure. Raw material dependencies include Kubernetes orchestration platforms, zero-trust security frameworks, and real-time payment gateway APIs. Tariff exposure on cross-border data flows threatens scaling economics. Distribution runs through mobile app stores and API-enabled embedded finance partnerships with retailers and logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European neobanking rests on automation-driven cost reduction in customer acquisition and compliance operations, alongside subscription tier upgrades among Nordic professional segments.
For Market Incumbents: Lock in regulatory moats by accelerating EU AI Act compliance investments in explainable credit scoring before supervisory deadlines tighten. Deepen core banking software partnerships through equity stakes or exclusive capacity reservations in Frankfurt and London data centers. The DORA framework's redundant infrastructure mandates threaten smaller competitors with disproportionate capex burdens. For New Entrants and Emerging Players: PSD2 in the European Union opens a window for algorithmic credit products that aggregate legacy bank transaction data for faster SME lending decisions. Polish and Romanian SME banking corridors offer lowest competitive density and highest regulatory sandbox receptivity. White-label Banking-as-a-Service distribution through Eindhoven's embedded finance ecosystem accelerates customer acquisition without direct consumer marketing spend. For Investors and Strategic Acquirers: Asymmetric upside sits with API-first infrastructure providers serving multiple neobank brands through single-tenant deployments. Five-to-ten year viability favors platforms with demonstrated DORA compliance and diversified data center footprints across Baltic and Nordic jurisdictions. Watch for EBA stress-test failures among deposit-heavy entrants as an inflection signal for consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Licensing | Estonia and Lithuania's restricted permits enable foreign entrants to test SME products before full BaFin authorization. |
| Core Banking Software Partnership | Exclusive capacity agreements with Frankfurt data center operators secure scaling velocity as supply bottlenecks intensify. |
| Embedded Finance Integration | API connections to Dutch retailers and logistics platforms fragment deposit ownership while compressing acquisition costs. |
| EU AI Act Compliance Investment | Explainable model governance positions neobanks for corporate treasury clients demanding audit trail transparency. |
| Sustainability-Linked Deposit Products | Carbon-footprint-linked interest tiers capture ESG-conscious flows concentrated in Amsterdam and Rotterdam corridors. |
Research Methodology
Bottom-up customer segment modeling reconciled against top-down regulatory tracking forms the analytical core of this study. Primary interviews with neobank product executives, BaFin supervisory officials, embedded finance platform engineers, and corporate treasury managers in Berlin, Amsterdam, and Paris informed demand-side assumptions. Secondary validation drew from EBA digital operational resilience disclosures, De Nederlandsche Bank licensing registers, PSD2 API performance benchmarks, and national deposit guarantee scheme filings. Triangulation between these sources anchored volume and value estimates.
Historical trendline analysis of account opening velocity and deposit migration patterns established baseline growth trajectories across the modeling period. The forecast framework segments by customer type, service type, technology interface, and regulatory jurisdiction to capture divergent compliance burdens and passporting strategies. CAGRs were derived from slope analysis of mobile banking penetration curves and SME account adoption rates, cross-referenced against cloud infrastructure scaling constraints and interest rate environment assumptions.
Revisions become necessary when EBA stress-test protocols tighten, DORA implementation deadlines shift, or central bank digital currency pilots in Estonia and Lithuania alter settlement infrastructure economics. Forecasts reflect documented assumptions about regulatory divergence between EU and UK frameworks, cloud vendor concentration risk, and millennial preference stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Investment Banking and Trading Services Market
Banking
South Korea Data Analytics in Banking Market
Banking
Banking Wearable Market
Banking
Global AI in Banking Market
Banking
UK Retail Banking Market
Banking
Singapore Neobanking Market
Banking
Banking Smart Cards Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Mobile Banking Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Spain Data Analytics in Banking Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Bank Kiosk Market
Banking
Armenia Banking Market
Banking
Biometric Banking Wristband Market