
 North America Machine Learning in Banking Market | 2026-2036
North America Machine Learning in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
North America Machine Learning in Banking Market Analytics
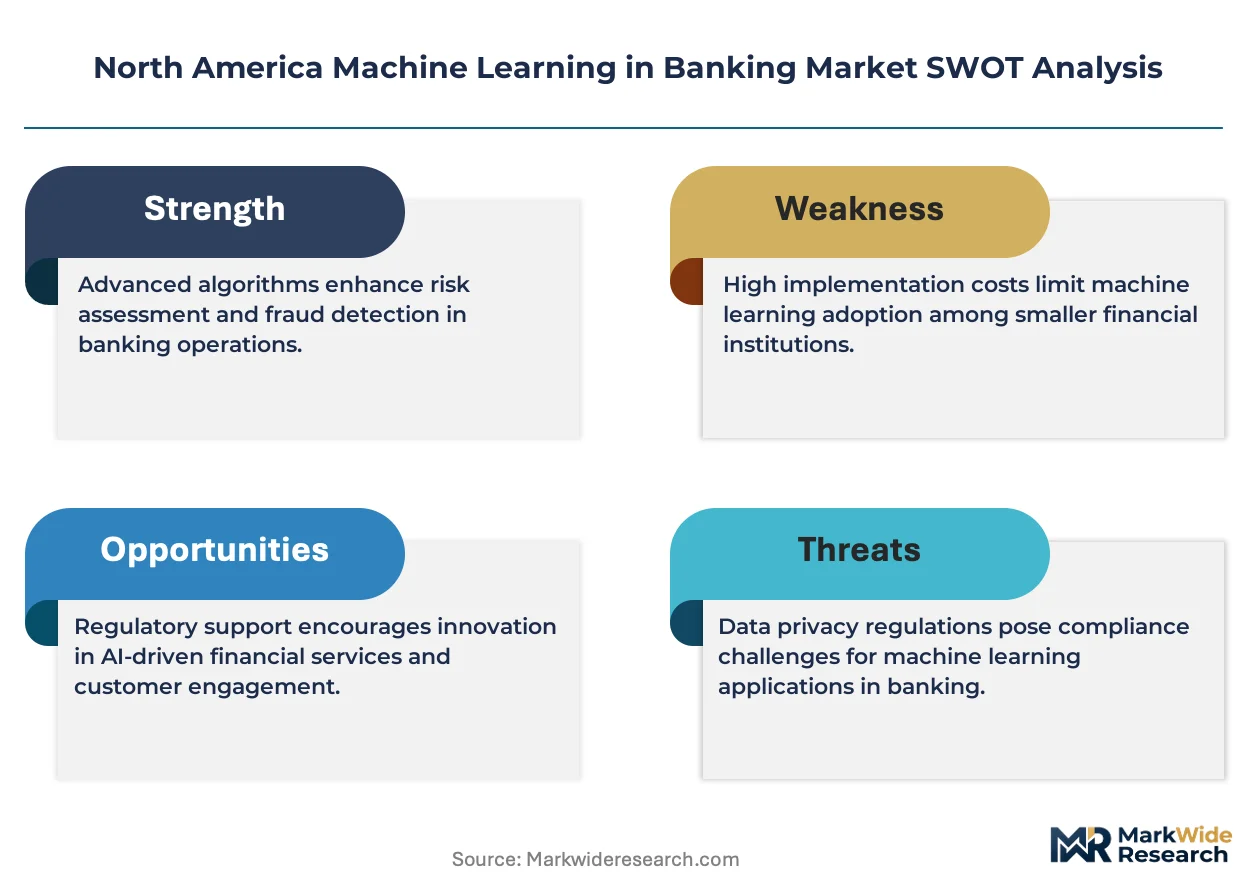
A shortage of qualified machine learning engineers is unwinding deployment timelines at major financial institutions. JPMorgan Chase leverages its proprietary AI research division to sustain talent retention through dedicated academic partnerships. Bank of America anchors its competitive stance through extensive in-house model governance infrastructure. Microsoft Corporation dominates cloud-based AI tooling for mid-tier banks seeking rapid capability deployment.
North America Machine Learning in Banking encompasses algorithmic systems that process transactional data, customer behavior patterns, and market signals to automate decision-making across lending, fraud prevention, and portfolio management functions. These systems typically operate through supervised learning pipelines trained on historical banking datasets with inference latency requirements under 100 milliseconds for real-time payment screening. Fraud Detection commands the largest share of deployed capital due to regulatory pressure on real-time transaction monitoring, while Natural Language Processing is expanding fastest as conversational AI replaces legacy customer service workflows. Cloud-Based deployment leads among online lenders seeking elastic compute scaling, though Hybrid architectures are gaining traction at investment firms managing sensitive proprietary trading data.
The US Federal Reserve, OCC, and CFPB collectively shape market access through model risk management guidance, fair lending enforcement, and consumer protection audits that mandate explainable AI outputs. Canadian banks face parallel scrutiny from OSFI regarding algorithmic transparency in credit decisions. Stakeholders must monitor evolving supervisory expectations around generative AI applications in advisory services as enforcement frameworks crystallize.
Market Dynamics
The US Federal Reserve's SR 11-7 model risk management guidance is forcing banks to rebuild governance infrastructure around AI decision systems, compressing deployment timelines while elevating compliance spend as a permanent cost center.
Growth Catalysts
- Real-time payment infrastructure:The FedNow Service rollout mandates sub-100 millisecond fraud screening, accelerating investment in low-latency inference pipelines across retail payment networks.
- SR 11-7 supervisory expectations:The Federal Reserve's model validation requirements create procurement pull for explainable AI tooling that satisfies documentation and audit trail mandates.
- Generative AI convergence:Large language models are penetrating customer service workflows, with banks deploying conversational agents to displace tier-one support staffing.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for large banking models depend on concentrated semiconductor supply from Taiwan and South Korea, exposing cost structures to geopolitical disruption.
- Hybrid architecture complexity:Investment firms managing proprietary trading data face technical limitations in synchronizing on-premise sensitive workloads with cloud-based model development pipelines.
- OSFI algorithmic transparency mandates:Canadian banks confront regulatory friction from parallel fair lending audits that extend model validation cycles and compress vendor selection flexibility.
Strategic Opportunities
- Underpenetrated mid-tier credit unions:Community banks across the US Southeast and Midwest lack dedicated ML engineering functions, creating white space for managed service providers offering pre-validated fraud detection modules.
- Conversational AI advisory services:Emerging applications in wealth management robo-advisory face evolving CFPB scrutiny, but early movers capturing compliance documentation advantages will secure distribution partnerships.
- Federated learning architectures:Technology convergence between differential privacy and edge computing enables consortium models where competing banks train shared fraud detection without centralizing sensitive transaction data.
Industry Challenges
- ML engineering talent scarcity:Production-grade MLOps expertise combining financial domain knowledge with low-latency system design remains concentrated in New York and Boston corridors, unwinding deployment timelines at institutions outside these clusters.
- Core banking integration complexity:Legacy mainframe architectures at established institutions require expensive API middleware development to feed real-time data streams into modern inference pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Machine Learning in Banking Market |
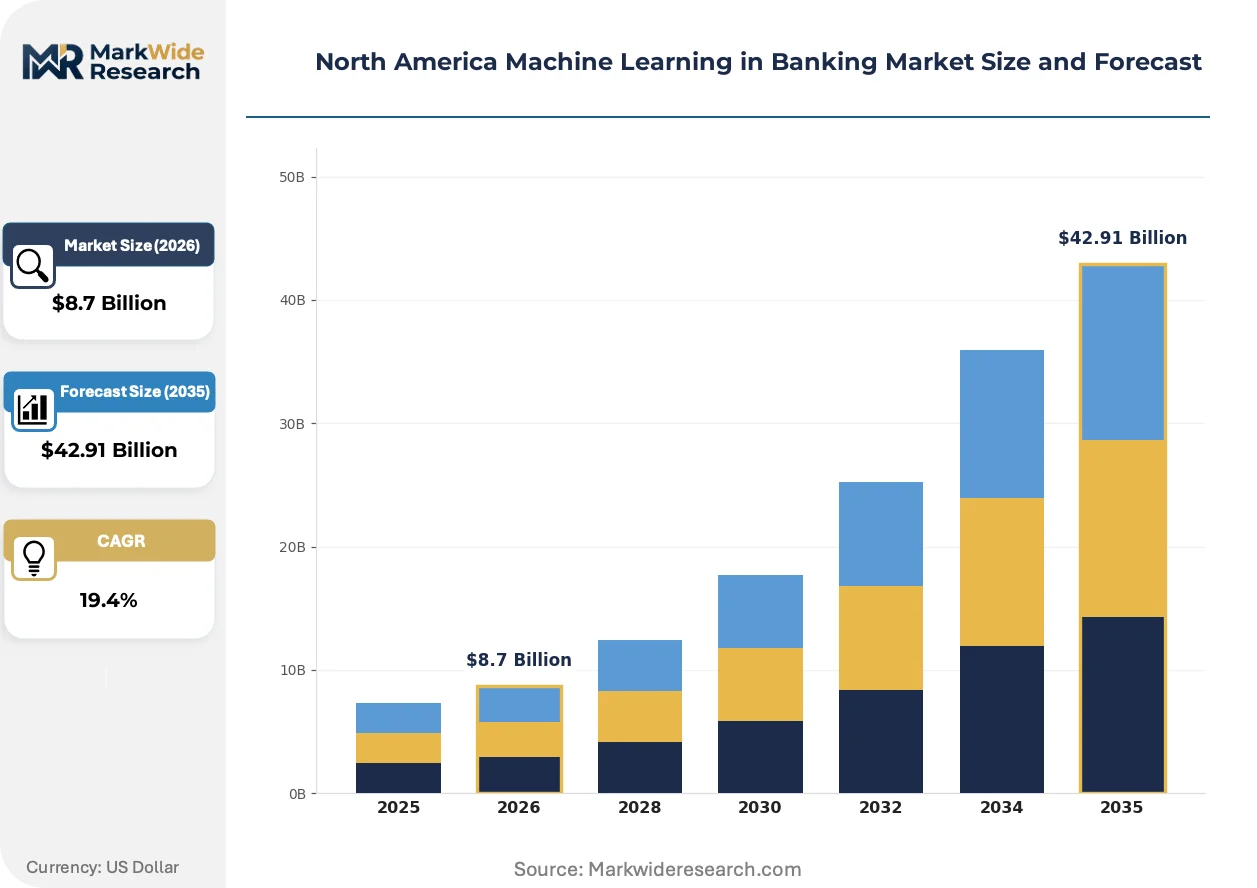
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Use Case: Fraud Detection, Credit Scoring, Customer Support, Risk Management Technology: Natural Language Processing, Predictive Analytics, Neural Networks, Deep Learning End User: Retail Banks, Investment Firms, Credit Unions, Online Lenders Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | JPMorgan Chase, Bank of America, Microsoft Corporation, IBM Corporation, Google LLC, Amazon Web Services, Wells Fargo, Oracle Corporation, Accenture PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Machine Learning in Banking Market Evolving Landscape
Explainability tooling is becoming the decisive procurement criterion as supervisory audits intensify scrutiny of black-box credit decisions. Banks now prioritize vendors demonstrating documented model lineage and bias testing protocols over raw predictive accuracy.
Transformer-based natural language processing is fragmenting traditional customer service cost structures. JPMorgan Chase and Bank of America deploy large language models for document classification and compliance query resolution, compressing headcount in middle-office legal and risk functions while elevating technical staffing ratios.
The CFPB's fair lending enforcement posture is hardening documentation requirements for algorithmic credit decisions. Banks must now maintain adverse action reason codes and disparate impact testing for ML-powered underwriting, with the US Northeast corridor institutions investing most heavily in automated bias detection pipelines to preempt examination findings.
Mid-tier banks are consolidating vendor relationships around integrated cloud platforms rather than best-of-breed point solutions. Procurement teams at regional institutions prioritize Microsoft Azure and Amazon Web Services bundles offering pre-certified model governance tooling, displacing specialized fraud detection vendors lacking embedded compliance automation.
North America Machine Learning in Banking Market Segmentation
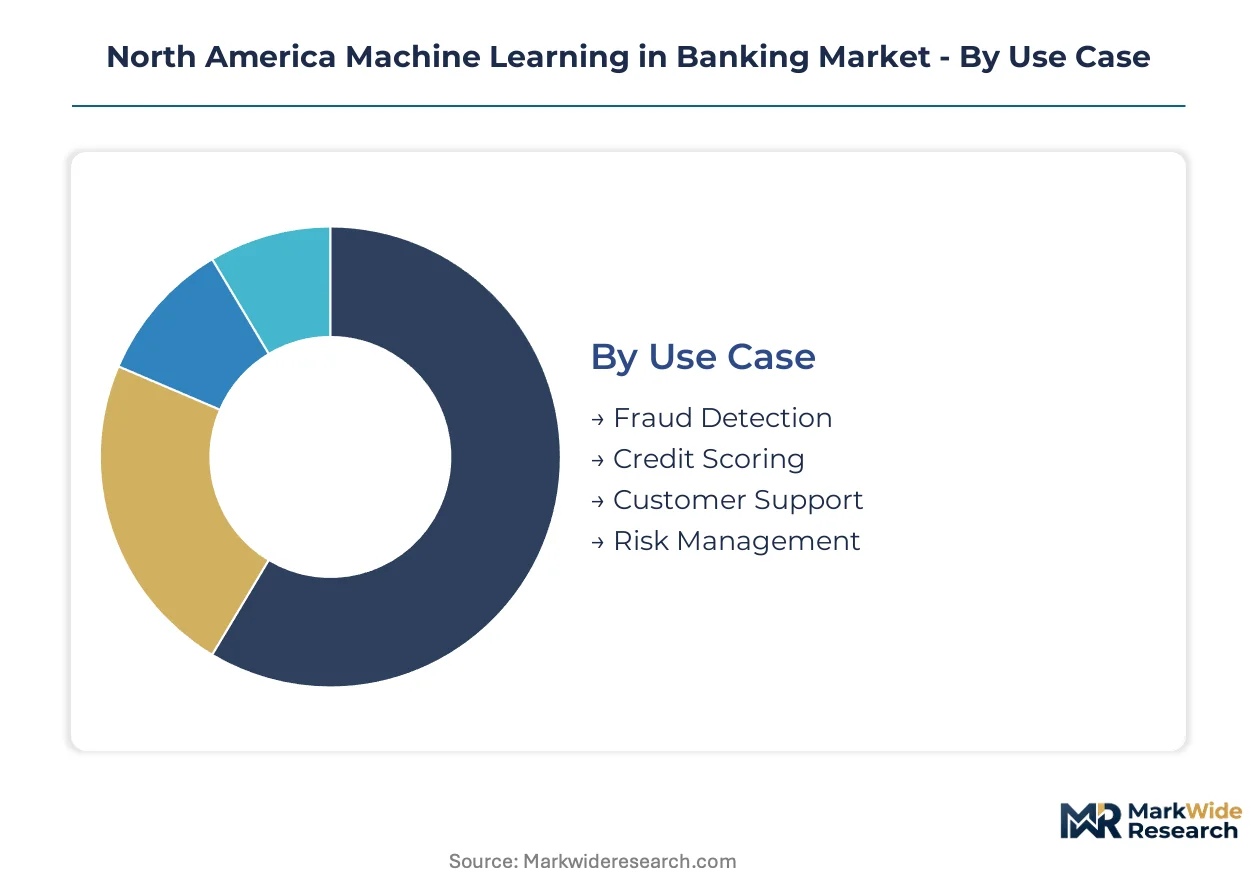
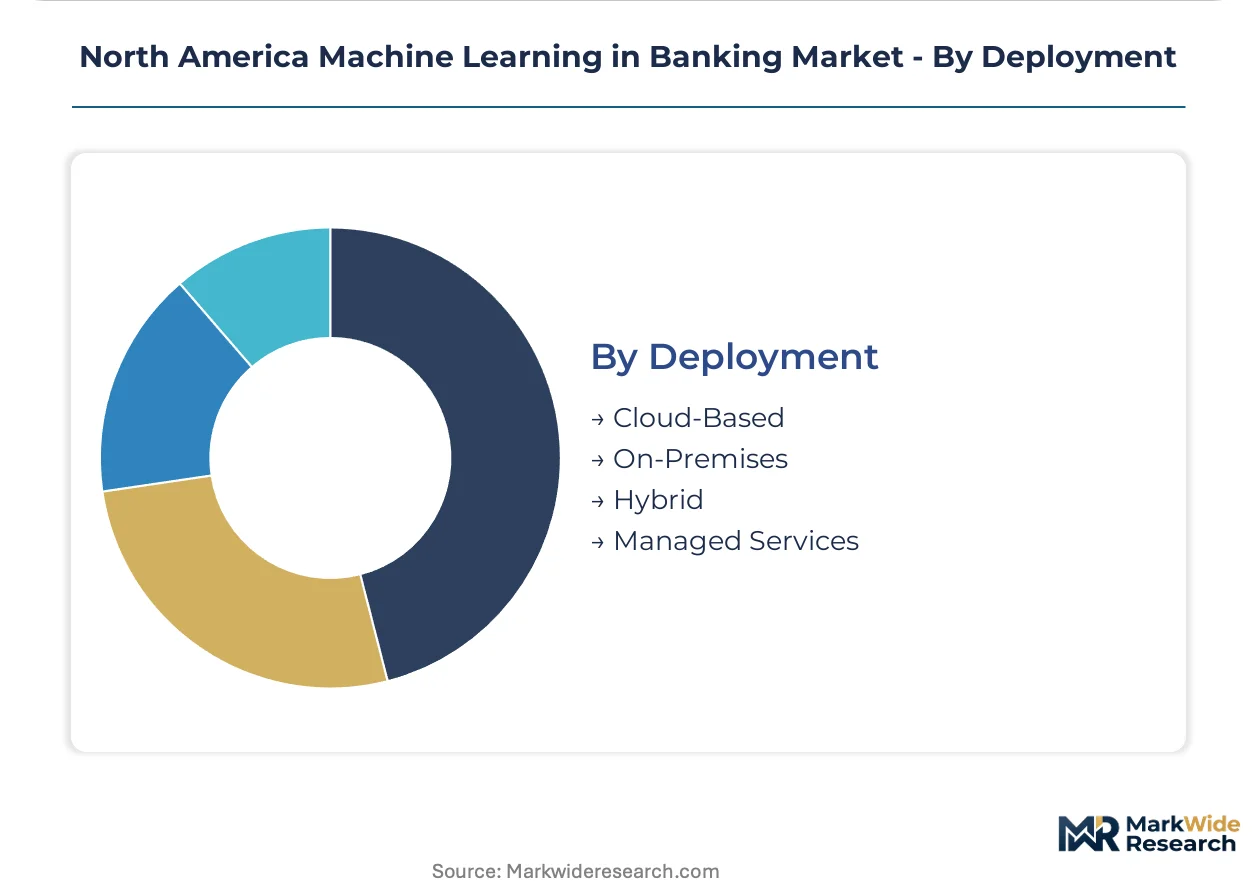
Machine learning deployment in North American banking fragments across four intersecting dimensions that determine procurement priorities and vendor selection criteria. Each segmentation axis carries distinct regulatory, technical, and commercial imperatives that reshape competitive positioning across the value chain.
Use Case:
Fraud Detection faces the most acute substitution pressure from real-time payment infrastructure mandates, forcing incumbent rule-based systems into accelerated replacement cycles.
- Fraud Detection:Supervised learning pipelines trained on transactional histories identify anomalous payment patterns with inference latency under 100 milliseconds. Demand concentrates in retail payment networks across the US Northeast corridor, driven by FedNow Service compliance deadlines that mandate sub-second screening capabilities.
- Credit Scoring:Alternative data models incorporating cash flow patterns and digital footprints supplement traditional FICO methodologies. Adoption clusters at online lenders in California and Texas seeking expansion into thin-file borrower segments underserved by conventional underwriting.
- Customer Support:Conversational AI and intent classification systems automate tier-one inquiry resolution. Deployment accelerates at mid-tier institutions facing cost compression in high-volume service environments.
- Risk Management:Portfolio-level stress testing and counterparty exposure models integrate macroeconomic scenario inputs. Investment firms in Chicago and Toronto anchor demand for proprietary model governance infrastructure.
Fraud Detection anchors the volume base while Credit Scoring gains share at the steepest rate.
Technology:
Technology selection stratifies by customer maturity, with established institutions prioritizing interpretable methods over black-box performance.
- Natural Language Processing:Transformer architectures process regulatory filings, customer correspondence, and compliance documentation. Bank of America and JPMorgan Chase deploy large language models for legal and risk function automation, compressing middle-office headcount while elevating technical staffing ratios.
- Predictive Analytics:Gradient-boosted decision trees and logistic regression models deliver explainable outputs for credit and fraud applications. Regional banks across the US Southeast prefer these methods for their audit trail transparency and SR 11-7 documentation compliance.
- Neural Networks:Feedforward and recurrent architectures handle time-series forecasting for trading and treasury operations. Hedge funds in Connecticut and Illinois drive specialized demand for low-latency inference on proprietary market data.
- Deep Learning:Convolutional and attention-based models extract patterns from unstructured document and image data. Adoption remains concentrated among top-tier institutions with dedicated MLOps infrastructure and GPU compute budgets.
Predictive Analytics retains the largest installed base while Natural Language Processing climbs the fastest.
End User:
End user type determines deployment architecture, with regulatory intensity scaling inversely with institutional size.
- Retail Banks:Branch networks and digital channels deploy omnichannel fraud detection and personalized product recommendation engines. The US Northeast corridor institutions invest most heavily in automated bias detection pipelines to preempt CFPB examination findings.
- Investment Firms:Proprietary trading desks and asset managers require hybrid architectures separating sensitive alpha-generating models from cloud-based development environments. Chicago and Toronto clusters face technical limitations in synchronizing on-premise workloads with elastic compute scaling.
- Credit Unions:Community-focused institutions across the US Midwest and Southeast lack dedicated ML engineering functions, creating white space for managed service providers offering pre-validated compliance modules.
- Online Lenders:Digital-native originators prioritize cloud-native infrastructure for elastic scaling during application volume spikes. California and Texas operators lead in alternative data integration for thin-file underwriting expansion.
Retail Banks dominate current procurement volumes while Online Lenders expand most quickly.
Deployment:
Deployment mode selection reflects data sensitivity trade-offs against time-to-market pressures.
- Cloud-Based:Fully managed infrastructure from Microsoft Azure and Amazon Web Services enables rapid capability deployment without capital expenditure. Mid-tier banks across the US Southeast and Midwest consolidate procurement around pre-certified governance bundles.
- On-Premises:Dedicated hardware installations satisfy proprietary data requirements at investment firms and large retail banks. New York and Boston institutions maintain captive infrastructure for alpha-generating trading models.
- Hybrid:Split architectures process sensitive workloads on-premise while leveraging cloud elasticity for model development and training. Canadian banks under OSFI scrutiny favor this mode for algorithmic transparency documentation.
- Managed Services:Third-party operators deliver pre-validated fraud detection and credit decisioning modules on subscription terms. Credit unions and community banks adopt this model to bypass ML engineering talent scarcity.
Cloud-Based deployment holds the largest share while Hybrid architectures gain traction fastest among regulated entities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Reserve's SR 11-7 guidance anchors supervisory expectations across North America, while Canadian banks navigate parallel OSFI mandates. Mexico's financial sector lags in adoption due to infrastructure constraints. Regional demand concentrates in established financial corridors with dense regulatory and talent ecosystems.
United States
The US Northeast corridor spanning New York and Boston drives the majority of ML engineering talent concentration and procurement volume. JPMorgan Chase and Bank of America anchor investment in proprietary model governance infrastructure to satisfy CFPB fair lending audits. The Federal Reserve's model risk management expectations compress deployment timelines while elevating compliance spend as a permanent cost center.
Canada
Toronto's financial district hosts concentrated demand for hybrid deployment architectures among investment firms managing proprietary trading data. OSFI algorithmic transparency mandates extend model validation cycles and compress vendor selection flexibility for domestic banks. Canadian institutions favor split architectures that process sensitive workloads on-premise while leveraging cloud elasticity for development pipelines.
California
Online lenders in California and Texas lead alternative data integration for thin-file borrower segments underserved by conventional underwriting. Digital-native originators prioritize cloud-native infrastructure for elastic scaling during application volume spikes. The state's technology sector supplies MLOps expertise to financial institutions nationwide, though production-grade talent combining domain knowledge with low-latency system design remains scarce.
Illinois
Chicago anchors demand for portfolio-level stress testing and counterparty exposure models among asset managers and hedge funds. Investment firms in the metropolitan area require hybrid architectures separating sensitive alpha-generating models from cloud-based development environments. Technical limitations in synchronizing on-premise workloads with elastic compute scaling constrain deployment velocity.
Texas
Dallas and Austin clusters support expanding credit scoring operations as online lenders penetrate thin-file segments. The state's regulatory environment attracts fintech operators seeking operational flexibility absent in Northeast corridors. Regional banks across the US Southeast and Midwest lack dedicated ML engineering functions, creating white space for managed service providers.
North America Machine Learning in Banking Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American banking ML. Tier-one money-center banks deploy captive AI research divisions and proprietary governance infrastructure to satisfy regulatory scrutiny. Cloud hyperscalers and global consultancies occupy the specialist tier, delivering pre-certified tooling bundles to mid-tier institutions lacking internal engineering capacity. Consolidation pressure intensifies as regional banks consolidate vendor relationships around integrated platforms rather than point solutions.
Within the integrated banking tier, JPMorgan Chase and Bank of America exemplify institutions that have built vertical AI capabilities through dedicated research divisions and extensive in-house model governance infrastructure. Microsoft Corporation anchors the cloud-platform vector, occupying a dominant position in Azure-based AI tooling for mid-tier banks seeking rapid capability deployment without capital expenditure. These three entities represent the primary competitive archetypes: captive bank-led development, hybrid infrastructure provision, and fully managed cloud service delivery.
| Leading Market Players |
|---|
| JPMorgan Chase |
| Bank of America |
| Microsoft Corporation |
| IBM Corporation |
| Google LLC |
| Amazon Web Services |
| Wells Fargo |
| Oracle Corporation |
| Accenture PLC |
| Others |
Value Network & Pricing Analysis
GPU cluster utilization rates above 80% at Taiwan Semiconductor Manufacturing Company and Samsung Electronics create steep scale economies that compress inference-as-a-service price floors for North American banking clients. This concentration of advanced semiconductor fabrication shapes procurement negotiations, as cloud hyperscalers pass through wafer cost volatility to financial institutions locked into long-term training contracts.
Pricing Analysis
US Northeast corridor institutions pay 15-25% premiums over Midwest credit unions for identical Azure ML governance bundles due to proximity-biased vendor pricing. Three-tier pricing structure across enterprise, professional, and standard levels dominates cloud-based AI tooling, with differentiation anchored in model lineage documentation depth and automated bias testing inclusion. Pricing pressure stems from GPU compute cost volatility tied to Taiwan and South Korea semiconductor supply exposure. Regional banks across the US Southeast exhibit highest price sensitivity, while investment firms in New York and Chicago absorb premiums for hybrid architecture flexibility.
Supply Chain Analysis
Taiwan and South Korea anchor advanced GPU and high-bandwidth memory fabrication for banking AI training workloads. Taiwan Semiconductor Manufacturing Company and Samsung Electronics supply the A100 and H100 processors that power real-time fraud detection pipelines. Supply chain risk centers on single-source vulnerability for 4nm and 3nm process nodes concentrated at TSMC's Hsinchu facilities. Distribution runs through cloud hyperscalers—Microsoft Azure, Amazon Web Services, Google Cloud—delivering managed inference endpoints to financial institutions lacking captive infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the 2022-2023 GPU supply shock as Taiwan Semiconductor expands CoWoS packaging capacity. The Federal Reserve's SR 11-7 enforcement cycle is compressing deployment timelines, creating procurement urgency that favors pre-certified vendors.
For Market Incumbents: Fortify model governance infrastructure investments to preempt CFPB fair lending examination findings. Bank of America and JPMorgan Chase have built proprietary validation pipelines that compress vendor selection cycles—regional banks must replicate this capability or cede procurement autonomy to cloud hyperscalers. Vertical integration into MLOps talent pools through Boston and New York academic partnerships is the critical defensive lever against deployment timeline slippage. For New Entrants and Emerging Players: Managed service gaps at credit unions across the US Midwest and Southeast represent the most penetrable white space. These institutions lack dedicated ML engineering functions and face SR 11-7 compliance deadlines without internal validation capacity. Pre-certified fraud detection modules delivered on subscription terms bypass the talent scarcity constraining incumbent deployment. Target OSFI-regulated Canadian banks with hybrid architecture expertise, as these institutions favor split deployment models that incumbent cloud vendors under-serve. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers delivering pre-validated compliance modules to credit unions and community banks. Long-term viability over the next decade hinges on federated learning consortium participation, where competing institutions train shared models without centralizing sensitive data. Acquisition targets should demonstrate documented model lineage capabilities and existing distribution partnerships with regional banking associations. The signal to watch is CFPB guidance crystallization around generative AI advisory services, which will trigger compliance-driven procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Consortium Formation | Enables competing banks to share fraud detection training without centralizing sensitive FedNow transaction data. |
| Pre-Certified Model Governance Bundles | Microsoft Azure and Amazon Web Services displace point-solution vendors by embedding SR 11-7 documentation automation. |
| Academic Partnership Programs | JPMorgan Chase sustains ML engineering retention through MIT and Stanford research collaborations. |
| Hybrid Architecture Deployment | Canadian banks under OSFI scrutiny process sensitive workloads on-premise while leveraging cloud elasticity. |
| Conversational AI Advisory Services | Wealth management robo-advisory applications face evolving CFPB scrutiny requiring adverse action documentation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ML engineering directors at tier-one money-center banks, model risk officers at regional institutions, procurement leads at credit unions, and cloud platform specialists at Microsoft Azure and Amazon Web Services. Secondary validation drew from Federal Reserve SR 11-7 guidance documents, CFPB fair lending enforcement actions, OSFI algorithmic transparency advisories, SEC 10-K disclosures from major financial institutions, and hyperscaler AI infrastructure capex reports. Bottom-up deployment estimates triangulated against top-down banking IT spend projections.
Across the analysis window, the analytical framework modeled four intersecting segmentation dimensions: use case trajectory from fraud detection through conversational AI, technology migration from predictive analytics to natural language processing, end-user procurement patterns across retail banks and online lenders, and deployment architecture evolution from cloud-native to hybrid. CAGRs were derived from scenario-weighted probability distributions anchored to FedNow Service compliance deadlines and OSFI examination cycle intensity. Industry-specific inputs included real-time payment infrastructure rollout timelines and GPU cluster utilization rates at Taiwan Semiconductor Manufacturing Company.
Forecasts assume regulatory continuity in US Federal Reserve, OCC, and CFPB supervisory frameworks; material policy shifts around generative AI advisory services would require re-modeling adoption curves. Forecasts also assume Taiwan semiconductor supply stability; geopolitical disruption to Hsinchu fabrication capacity would compress deployment timelines and elevate compliance spend estimates. Recalibration cycles align with material shifts in SR 11-7 enforcement posture and FedNow transaction volume thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Third-Party Banking Software Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Brazil Retail Banking Market
Banking
China Bank Kiosk Market
Banking
Performance Bank Guarantee Market
Banking
Global Banking Systems Software Market
Banking
Data Analytics in Banking Market
Banking
Machine Learning in Banking Market
Banking
Europe Neobanking Market
Banking
Cybersecurity in Banking Market
Banking
API Banking Market
Banking
Corporate Banking Market
Banking
Southeast Asia Commercial Banking Market
Banking
Banking Wearable Devices Market
Banking
Italy Data Analytics in Banking Market
Banking
GCC Mobile Banking Market