
 Mobile Banking Market | 2026-2036
Mobile Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Banking Market Outlook
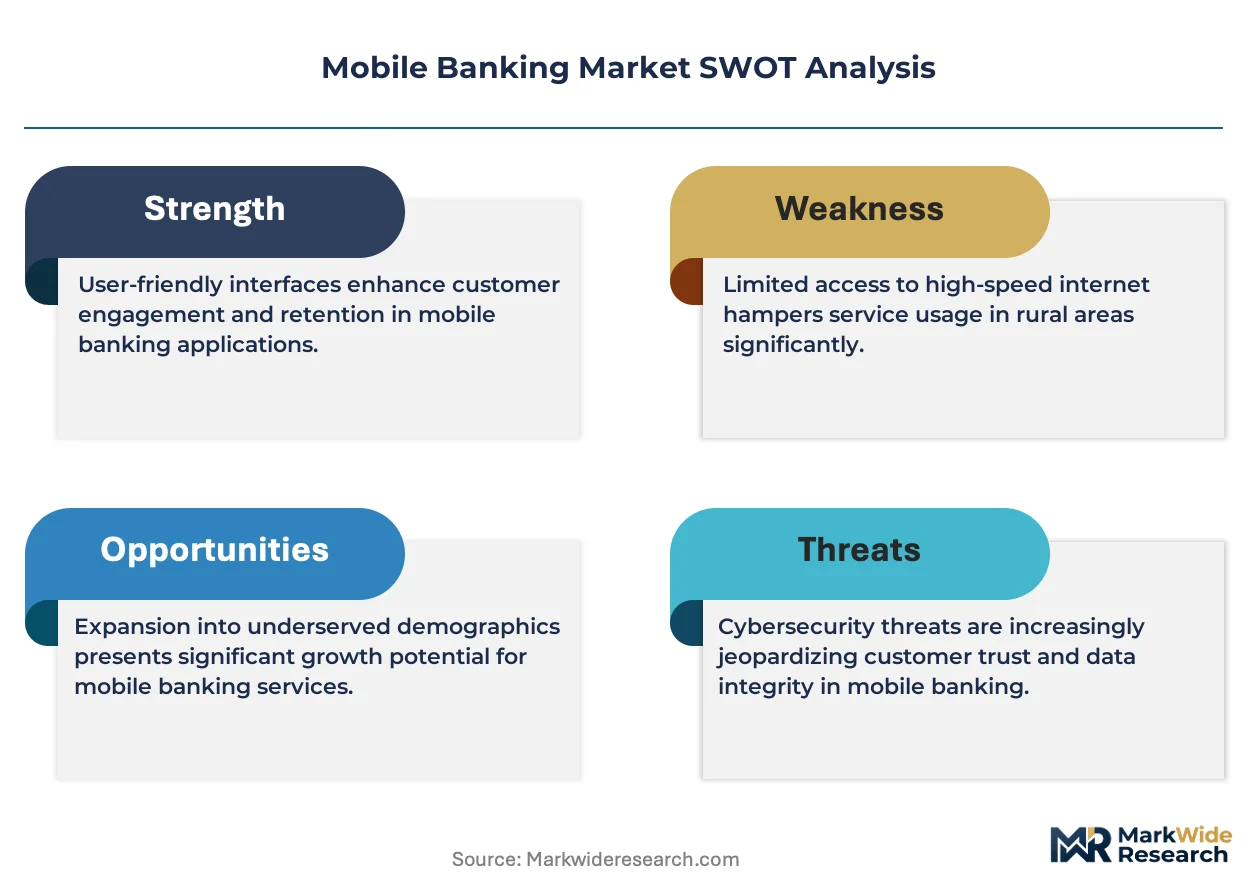
API-first architecture is hardening as the default substrate for mobile banking platforms, displacing legacy screen-scraping protocols that once dominated third-party connectivity. Fiserv leverages its core banking heritage to anchor enterprise-grade processing infrastructure across North American credit unions. Revolut competes through multi-currency wallets and cryptocurrency trading modules embedded within its mobile interface. Nubank specializes in Latin America's underbanked demographic, using proprietary credit scoring algorithms to extend unsecured lending products without physical branch networks.
Mobile banking denotes the delivery of retail and commercial financial services through native smartphone applications or responsive web interfaces, utilizing encryption protocols such as TLS 1.3 and biometric authentication tokens to secure real-time transaction authorization. The technology serves primarily to disintermediate physical branch dependency while enabling 24/7 account access, payment initiation, and credit decisioning for consumers and businesses. Account Management and Fund Transfer service types command the largest transaction volumes, though Loan Services generates disproportionate margin contribution through embedded origination fees and interest spreads. Cloud-Based deployment is accelerating fastest among neobanks and fintech challengers, while On-Premises infrastructure persists among tier-one banks subject to stringent data residency requirements.
The Federal Reserve's FedNow instant payment rails, the European Banking Authority's PSD2 strong customer authentication mandates, and India's RBI guidelines on digital lending collectively shape product roadmaps and compliance budgets across the competitive landscape. These frameworks enforce minimum security baselines while creating licensing barriers that favor capitalized incumbents over unregulated app developers. Stakeholders must monitor central bank digital currency pilot programs and real-time payment network interoperability agreements as these developments will determine which platforms retain transactional primacy versus becoming disintermediated infrastructure pipes.
Market Dynamics
API-first architecture is hardening as the default substrate for mobile banking platforms, displacing legacy screen-scraping protocols that once dominated third-party connectivity. Fiserv leverages its core banking heritage to anchor enterprise-grade processing infrastructure across North American credit unions. Revolut competes through multi-currency wallets and cryptocurrency trading modules embedded within its mobile interface. Nubank specializes in Latin America's underbanked demographic, using proprietary credit scoring algorithms to extend unsecured lending products without physical branch networks.
Growth Catalysts
- PSD2 Strong Customer Authentication Mandates:The European Banking Authority's requirements are accelerating infrastructure modernization across EU member states, forcing incumbent banks to expose payment initiation APIs to licensed third parties.
- Unified Payments Interface Adoption:India's real-time retail payment rails are compressing transaction costs for smartphone users, with rural financial inclusion programs driving first-time banking relationships through mobile-only onboarding.
- Cloud-Native Core Banking:Neobanks and fintech challengers are bypassing mainframe dependencies entirely, deploying containerized microservices that reduce time-to-market for new product features.
Market Restraints
- Data Residency Requirements:Tier-one banks in Germany, France, and Switzerland face jurisdictional constraints that prohibit full cloud migration, perpetuating on-premises infrastructure costs.
- Cybersecurity Talent Scarcity:The shortage of engineers proficient in zero-trust architecture and quantum-resistant cryptography is inflating compensation costs for platform security teams.
- Legacy Integration Complexity:COBOL-based core systems at major US and Japanese institutions create API latency that degrades real-time mobile experiences.
Strategic Opportunities
- Central Bank Digital Currency Pilots:The Federal Reserve's FedNow infrastructure and concurrent CBDC experiments in India and Brazil are creating first-mover advantages for wallet providers that integrate directly with sovereign settlement rails.
- Embedded Finance Convergence:The intersection of banking-as-a-service APIs and e-commerce checkout flows is unbundling traditional deposit-taking from transaction origination.
- Rural Underpenetration:Sub-Saharan African markets with smartphone penetration above 50 percent but formal banking access below 30 percent represent whitespace for agent-network mobile money models.
Industry Challenges
- Biometric Authentication Standardization:Fragmented implementation of FIDO2 protocols across Android and iOS ecosystems is forcing banks to maintain multiple authentication codebases.
- Third-Party Risk Management:Open banking dependencies on hundreds of API partners complicate compliance with operational resilience requirements from the UK's Prudential Regulation Authority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Banking Market |
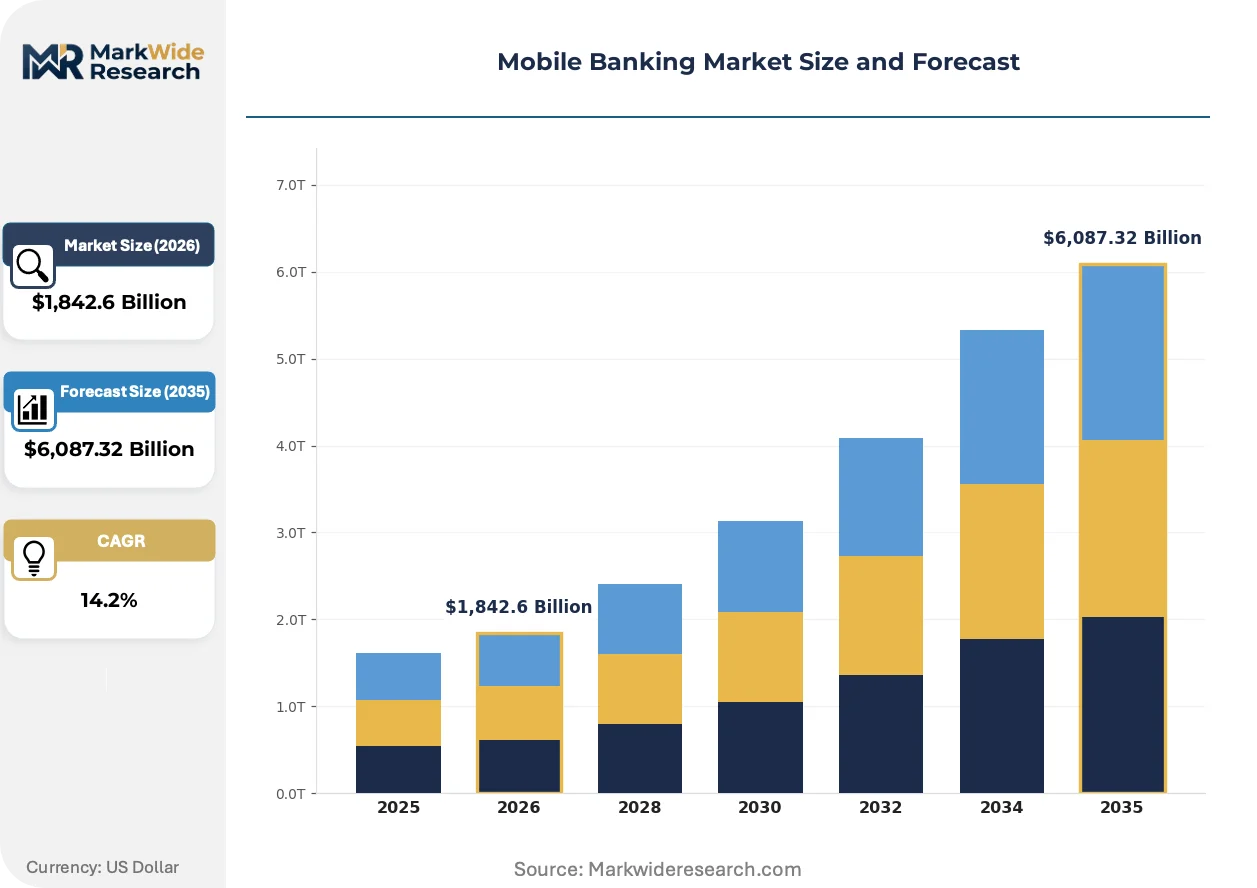
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $6,087.32 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Fund Transfer, Bill Payment, Loan Services End User: Retail Customers, Business Clients, Enterprises, Financial Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Applications Technology: Blockchain, Multi-Factor Authentication, AI Chatbots, Contactless Payments |
| Companies Covered | Adyen, Mastercard, Chime Financial, Revolut, Nubank, Fiserv, Block, Wise, Stripe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Banking Market Strategic Shifts
Tokenized payment credentials and real-time risk scoring engines are compressing the latency between transaction initiation and authorization. Platform providers are racing to embed commerce, wealth management, and identity verification within unified mobile interfaces.
Decentralized identity frameworks built on verifiable credentials are unifying KYC processes across banking, telecom, and government service providers. Neobanks in Brazil and Nigeria are adopting these standards to reduce customer onboarding friction from days to minutes. This convergence is compressing compliance costs while expanding addressable markets among documentation-scarce populations.
The European Union's Digital Operational Resilience Act is mandating granular incident reporting and third-party risk mapping for critical financial infrastructure. Banks with over EUR 10 billion in assets must implement automated threat detection and 24-hour breach notification protocols. German and Dutch institutions are consolidating vendor relationships to reduce DORA compliance complexity.
Small and medium enterprises are abandoning standalone treasury workstations in favor of mobile-first cash management dashboards integrated with accounting software. This behavioral shift is most visible in India, where UPI-enabled B2B payment volumes are displacing traditional RTGS for transactions below INR 500,000. Platform providers are responding with API suites that embed invoice financing and dynamic discounting within payment workflows.
Mobile Banking Market Segmentation
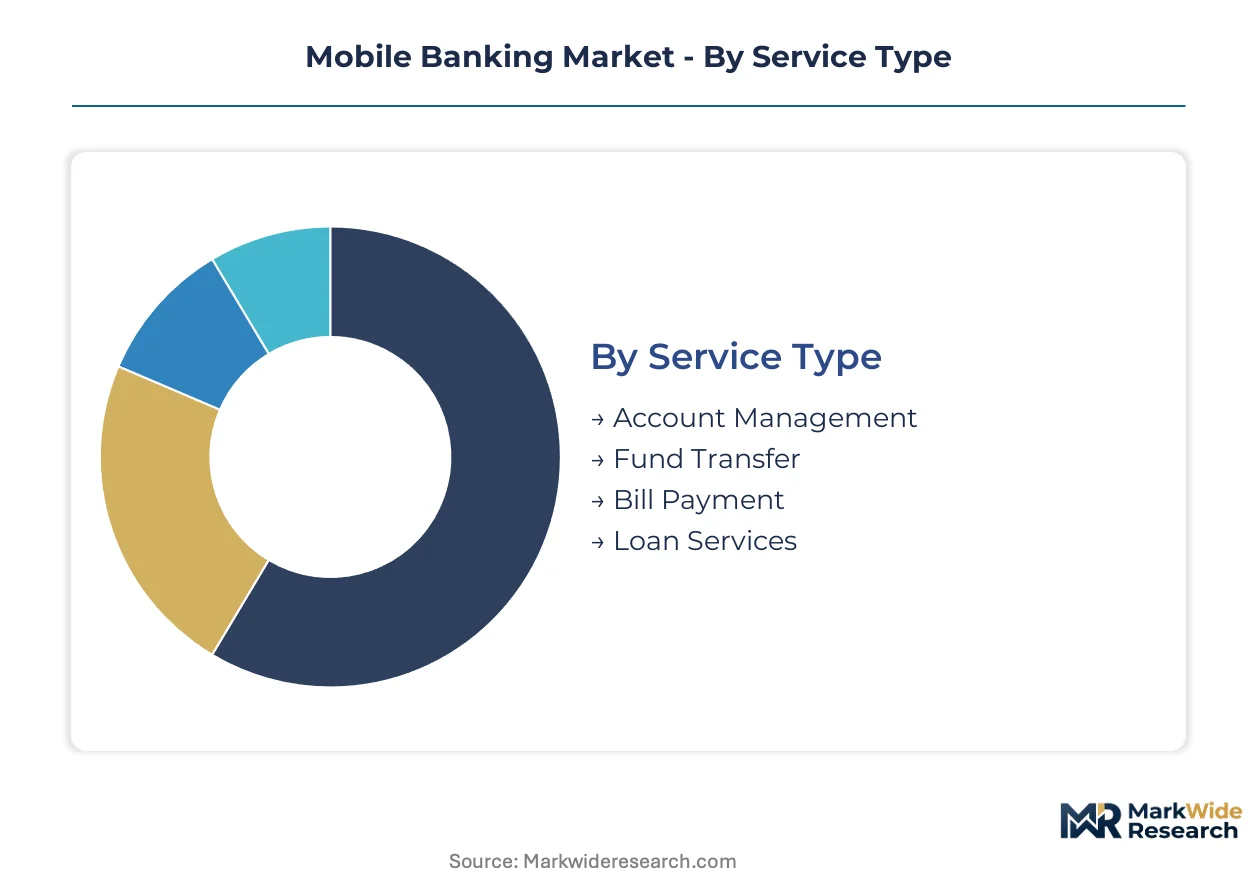
Mobile banking platforms segment across service delivery models, user sophistication levels, and infrastructure architectures that determine compliance burdens and margin structures. Each dimension shapes capital allocation decisions for platform providers and regulatory exposure for financial institutions.
Service Type:
Standardization dominates high-volume transaction processing while customization concentrates in credit decisioning workflows where proprietary algorithms create differentiation.
- Account Management:Core functionality encompassing balance inquiry, statement retrieval, and profile administration through encrypted mobile interfaces. Demand clusters among retail customers in India and Brazil where first-time digital banking relationships bypass branch infrastructure entirely. RBI guidelines on digital KYC and Brazil's PIX instant payment integration accelerate onboarding velocity for this segment.
- Fund Transfer:Real-time payment initiation across domestic and cross-border rails including UPI, FedNow, and SEPA Instant Credit Transfer. Small and medium enterprises in India are displacing traditional RTGS workflows for transactions below threshold limits, compressing processing costs while expanding transaction frequency. UPI-enabled B2B volumes are climbing fastest among business clients migrating treasury operations to mobile dashboards.
- Bill Payment:Recurring utility and subscription settlement through stored credential frameworks.
- Loan Services:Embedded origination, underwriting, and servicing for unsecured consumer and SME credit products.
Most installed capacity flows through Account Management. Expansion is steepest in Loan Services.
End User:
Customer type determines authentication rigor, with retail-facing platforms optimizing for friction reduction while enterprise deployments prioritize audit trails and multi-approval workflows.
- Retail Customers:Individual account holders accessing basic deposit, payment, and credit services through consumer-grade mobile applications. Concentration is highest in India where rural financial inclusion programs and UPI penetration drive first-time banking relationships through smartphone-only channels. PSD2 strong customer authentication mandates in the European Union force biometric token deployment for this segment.
- Business Clients:Small and medium enterprises managing cash flow, payables, and receivables through mobile-first treasury dashboards. This segment is expanding most quickly as firms abandon standalone workstation software for API-integrated accounting platform connectivity. India's GST compliance requirements and invoice financing integration accelerate adoption among SME manufacturers and trading enterprises.
- Enterprises:Large corporations with complex multi-entity cash management and cross-border liquidity needs.
- Financial Institutions:Banks, credit unions, and fintechs white-labeling or consuming banking-as-a-service infrastructure.
Transaction volume concentrates among Retail Customers. Margin contribution is highest from Business Clients.
Deployment:
Cost tier separation is pronounced, with cloud-native architectures reducing capital intensity for challengers while on-premises persistence reflects data sovereignty premiums at major institutions.
- Cloud-Based:Containerized microservices deployed across hyperscale infrastructure enabling rapid feature iteration and elastic capacity scaling. Neobanks in Brazil, Nigeria, and Southeast Asia bypass mainframe dependencies entirely, achieving time-to-market advantages for new product launches. European Banking Authority cloud outsourcing guidelines and India's RBI data localization requirements create compliance complexity for cross-border deployments.
- On-Premises:Dedicated hardware and private data centers maintained within jurisdictional boundaries to satisfy data residency mandates. Tier-one banks in Germany, France, and Switzerland perpetuate this model despite higher operational overhead, driven by national financial regulators and customer data protection statutes. The European Union's Digital Operational Resilience Act imposes granular incident reporting obligations on these installations.
- Hybrid:Workload distribution across private infrastructure and public cloud with orchestrated data flow management.
- Mobile Applications:Native iOS and Android clients or progressive web interfaces as the primary user touchpoint.
New platform launches predominantly select Cloud-Based architecture. Hybrid deployments are climbing fastest among incumbent banks modernizing legacy estates.
Technology:
Maturity gradients separate proven authentication and payment rails from emerging infrastructure layers where standardization remains contested.
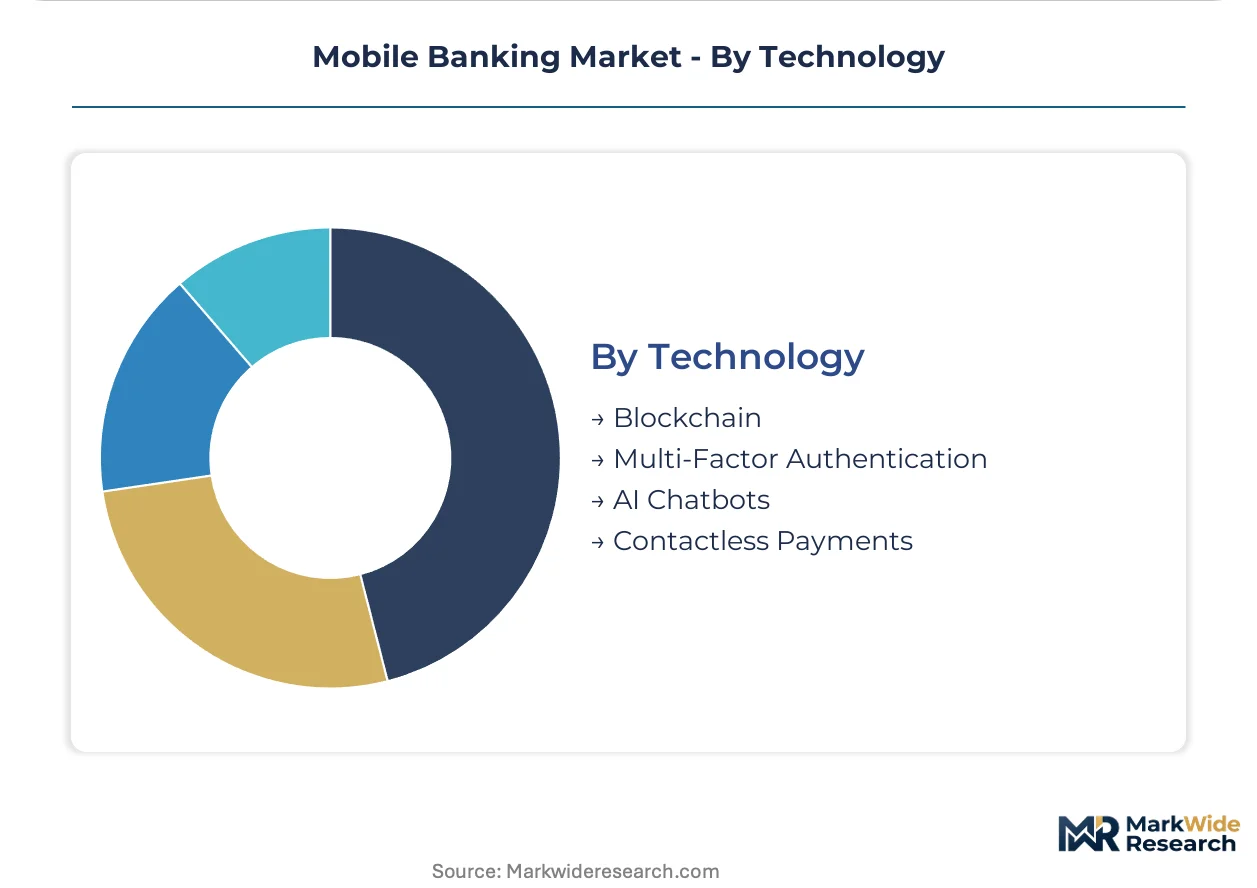
- Multi-Factor Authentication:Biometric verification, hardware security keys, and one-time password frameworks securing transaction authorization. Fragmented FIDO2 implementation across Android and iOS ecosystems forces banks to maintain multiple authentication codebases, inflating development overhead. India's Aadhaar-linked biometric verification and the European Banking Authority's PSD2 mandates accelerate deployment velocity.
- Contactless Payments:Near-field communication and tokenized credential exchange enabling physical point-of-sale transactions through mobile devices. Adoption concentrates in urban retail environments across Brazil, South Korea, and the United Kingdom where merchant terminal infrastructure supports tap-to-pay protocols. Central bank digital currency pilot programs in India and Brazil are integrating with these rails.
- Blockchain:Distributed ledger infrastructure for settlement, identity, and cross-border remittance applications.
- AI Chatbots:Natural language processing interfaces for customer service, transaction dispute resolution, and financial guidance.
Authentication traffic flows predominantly through Multi-Factor Authentication. Investment allocation is climbing fastest for Contactless Payments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's fintech corridor anchors mobile banking innovation through API infrastructure clusters serving domestic and cross-border payment rails. Regulatory mandates across multiple jurisdictions are forcing legacy system modernization while cloud-native challengers capture underbanked segments.
United States
The Federal Reserve's FedNow instant payment infrastructure and small business treasury migration drive platform adoption. NACHA operating rules and state-level money transmission licensing create compliance complexity for interstate providers. New York's financial technology cluster concentrates engineering talent for authentication and fraud detection systems.
India
RBI guidelines on digital lending and UPI-enabled B2B payment volumes accelerate SME platform adoption. The central bank's data localization requirements and prepaid payment instrument regulations shape cloud deployment architectures. Mumbai's banking headquarters and Bengaluru's technology parks host competing infrastructure development centers.
Brazil
PIX instant payment integration and CBDC pilot programs compress transaction costs for smartphone users. Banco Central do Brasil's open banking mandates force incumbent exposure of customer data APIs. São Paulo's financial district anchors neobank engineering operations targeting Latin America's underbanked demographic.
United Kingdom
PSD2 strong customer authentication enforcement and the Prudential Regulation Authority's operational resilience requirements drive infrastructure spending. The Financial Conduct Authority's sandbox programs accelerate wallet and cryptocurrency trading module deployment. London's fintech cluster concentrates regulatory technology and compliance automation expertise.
Germany
The European Banking Authority's cloud outsourcing guidelines and national data residency statutes perpetuate on-premises infrastructure among tier-one institutions. The Digital Operational Resilience Act mandates automated threat detection for critical financial infrastructure. Frankfurt's banking hub and Berlin's startup ecosystem represent divergent deployment philosophies.
Mobile Banking Market Competitive Environment
Global majors compete with regional champions across payment processing infrastructure and neobank customer acquisition. The vendor base separates into three tiers: legacy core banking providers maintaining on-premises relationships, cloud-native challengers bypassing mainframe dependencies, and payment network operators controlling settlement rails. Strategic differentiation concentrates on API ecosystem breadth, regulatory licensing coverage, and proprietary credit scoring algorithm development. Consolidation pressure intensifies through banking-as-a-service partnerships and embedded finance convergence.
Among infrastructure-focused providers, Fiserv anchors enterprise-grade processing relationships with North American credit unions. Revolut and Nubank occupy positions within the challenger bank tier, exemplifying geographic specialization strategies—European multi-currency expansion versus Latin American underbanked penetration. These three entities represent contrasting archetypes: legacy technology heritage, developed market fintech scaling, and emerging market demographic targeting.
| Leading Market Players |
|---|
| Adyen |
| Mastercard |
| Chime Financial |
| Revolut |
| Nubank |
| Fiserv |
| Block |
| Wise |
| Stripe |
| Others |
Value Chain & Pricing Dynamics
API-first architecture migration is simultaneously compressing platform development costs and redistributing supplier power toward cloud infrastructure hyperscalers and specialized authentication vendors. This technological transition rewards capitalized incumbents with scale economies while forcing smaller providers into white-label dependency relationships.
Pricing Analysis
Input-cost pass-through from cloud infrastructure fees and cybersecurity talent scarcity is reshaping platform economics. SaaS-tiered subscription models dominate, with pricing stratifying across enterprise-grade, mid-market, and developer-tier levels based on API call volume and compliance certification depth. Price erosion runs through the developer tier as open-source alternatives proliferate. Tier-one banks exhibit lowest price sensitivity due to regulatory switching costs, while neobanks and fintech challengers drive aggressive procurement negotiation.
Supply Chain Analysis
India's data localization mandates and the European Union's cloud outsourcing guidelines are fragmenting infrastructure sourcing across jurisdictional boundaries. Platform development draws from hyperscale cloud providers in the United States, specialized authentication vendors in Israel and Estonia, and core banking integration specialists in India and Brazil. Single-source vulnerability concentrates in biometric SDK providers serving multiple competing banks. Distribution runs through direct enterprise sales teams for tier-one institutions and self-service developer portals for emerging fintechs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile banking functions as a stable compounder anchored by persistent regulatory modernization cycles that force recurring infrastructure investment across financial institutions.
For Market Incumbents: Hedge against disintermediation by acquiring banking-as-a-service API specialists before challenger banks consolidate control over embedded finance distribution. Defensive consolidation should prioritize vertical integration into cloud-native core banking infrastructure to reduce hyperscaler dependency. The European Banking Authority's escalating operational resilience requirements create compliance moats that favor capitalized legacy institutions over unregulated app developers. For New Entrants and Emerging Players: Enter via agent-network mobile money models in Sub-Saharan African markets where smartphone penetration exceeds formal banking access by twenty percentage points. The most penetrable whitespace sits in rural India, where UPI-enabled B2B treasury tools for SME manufacturers remain underdeveloped. A go-to-market angle anchored in GST-compliant invoice financing integration addresses documented pain points in working capital management. For Investors and Strategic Acquirers: Valuations sit cheapest among regional core banking modernizers with captive credit union relationships and FedNow certification completion. The five-to-ten year viability window favors infrastructure providers with regulatory licensing coverage across multiple jurisdictions rather than single-market consumer apps. The signal to watch is central bank digital currency pilot program award announcements, which will determine which wallet providers retain transactional primacy versus becoming disintermediated pipes.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Broadens addressable market through PSD2-compliant payment initiation services across EU member states. |
| Biometric Authentication Certification | Accelerates customer onboarding velocity under RBI digital KYC and Brazil's PIX integration requirements. |
| Cloud-Native Core Migration | Bypasses COBOL latency constraints that degrade real-time mobile experiences at Japanese and US institutions. |
| Embedded Finance Partnership | Unbundles deposit-taking from transaction origination through e-commerce checkout API integration. |
| CBDC Wallet Development | Captures first-mover positioning for India's and Brazil's sovereign digital currency settlement rails. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with platform engineering leads, regulatory compliance officers, neobank product managers, and credit union technology executives with secondary validation. Primary inputs were cross-referenced against SEC filings, RBI circulars, European Banking Authority guidance documents, and hyperscaler infrastructure capex disclosures. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored value estimates.
Comparable-period anchoring linked projection assumptions to historical infrastructure deployment cycles across the analysis window. Segmentation modeling spanned service type, end-user sophistication, deployment architecture, and regional regulatory framework intensity. CAGRs were derived from fitted growth curves calibrated against smartphone penetration trajectories, real-time payment network adoption curves, and neobank customer acquisition cost trends. Cloud infrastructure pricing elasticity and cybersecurity talent supply constraints informed cost-side assumptions.
Inputs from regulatory filings and platform engineering disclosures were available through the study window; gaps in private neobank unit economics introduce uncertainty bands around challenger bank profitability timelines. Forecasts reflect documented assumptions regarding UPI volume trajectories, FedNow adoption velocity, and PSD2 enforcement consistency. Central bank digital currency program delays or accelerated quantum cryptography mandates could materially revise infrastructure investment requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Neo and Challenger Bank Market
Banking
Australia Neobanking Market
Banking
US Commercial Banking Market
Banking
Cardless ATM Market
Banking
Open Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
ATM Market
Banking
Southeast Asia Commercial Banking Market
Banking
Bank Management Software Market
Banking
North America Machine Learning in Banking Market
Banking
Commercial Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Retail Banking IT Spending Market
Banking
China Retail Banking System Market
Banking
Global Banking BPS Market
Banking
Global Retail Core Banking Systems Market