
 Asia-Pacific Islamic Finance Market | 2026-2036
Asia-Pacific Islamic Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Islamic Finance Market Outlook
Retail client demand is decoupling from traditional branch-based distribution across Southeast Asia. Maybank Islamic leverages its digital platform infrastructure to capture mobile-first customers in Indonesia. Bank Rakyat anchors rural cooperative networks across Malaysia's heartland states. CIMB Islamic Bank competes through cross-border ASEAN liquidity management products.
Asia-Pacific Islamic Finance encompasses Shariah-compliant financial instruments structured around asset-backed transactions, profit-sharing arrangements, and risk-sharing principles that prohibit riba (interest), gharar (excessive uncertainty), and maysir (gambling). These instruments employ ijara (leasing), mudaraba (trust financing), and wakala (agency) contracts to channel capital into trade, infrastructure, and real estate development. Sukuk issuance leads product type activity as sovereign and quasi-sovereign borrowers across the region seek alternative funding mechanisms. Retail banking services within the service type dimension sustain margin pools through recurring fee income and deposit mobilization. Corporate finance applications show the fastest structural expansion as multinationals establish Shariah-compliant treasury operations.
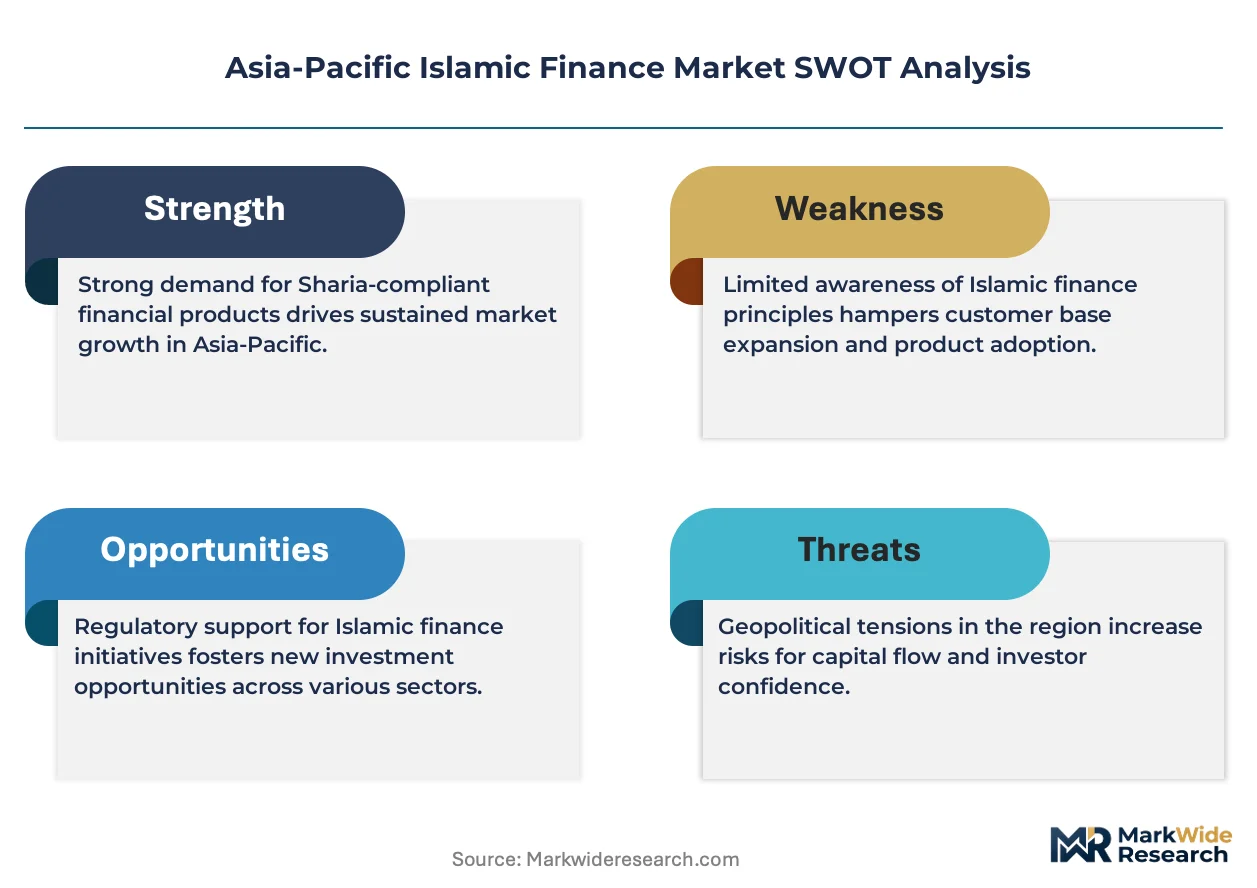
Bank Negara Malaysia, Indonesia's Financial Services Authority (OJK), and the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI) collectively govern capital adequacy, Shariah governance, and financial reporting standards across the region. These frameworks shape product design by mandating independent Shariah board oversight and asset segregation requirements. Stakeholders must monitor how digital banking licenses and cross-border regulatory harmonization initiatives redefine competitive access across ASEAN member states.
Market Dynamics
Digital banking licensing reforms across ASEAN member states are compressing distribution costs and fragmenting customer acquisition channels away from traditional branch networks. Bank Negara Malaysia's sandbox approvals have accelerated this structural shift.
Growth Catalysts
- Regulatory sandbox frameworks:Malaysia's central bank has streamlined digital Islamic banking licenses, reducing time-to-market for Shariah-compliant fintech entrants and expanding retail penetration beyond physical branch footprints.
- SME trade finance demand:Small and medium enterprises across Indonesia and Bangladesh are expanding utilization of Shariah-compliant murabaha and wakala contracts for cross-border commodity financing.
- Sovereign sukuk issuance:Quasi-sovereign borrowers in the Gulf Cooperation Council and Southeast Asia are diversifying funding mechanisms through asset-backed Islamic securities, creating liquidity depth for secondary market development.
Market Restraints
- Shariah scholar scarcity:Qualified Islamic finance jurists capable of certifying complex structured products remain concentrated in Kuala Lumpur and Dubai, creating approval bottlenecks for new instrument launches.
- Cross-border regulatory fragmentation:Divergent AAOIFI versus national Shariah board interpretations across Indonesia, Malaysia, and Bangladesh force product redesigns for each jurisdiction, elevating compliance overhead.
- Conventional banking substitution:Interest-rate arbitrage opportunities in conventional trade finance periodically divert corporate treasury demand away from Shariah-compliant alternatives during low-rate cycles.
Strategic Opportunities
- Underpenetrated rural Indonesia:Islamic cooperative networks (BMTs) outside Java's major urban centers lack digital infrastructure, creating white space for mobile-first takaful and micro-sukuk distribution platforms.
- Green sukuk convergence:Malaysia's Sustainable and Responsible Investment Sukuk Framework and Indonesia's green bond taxonomy are aligning Shariah compliance with climate finance mandates, opening sovereign ESG investor pools.
- Blockchain-based smart contracts:Distributed ledger technology combined with automated Shariah compliance oracles can compress wakala and ijara contract execution cycles from weeks to hours.
Industry Challenges
- Digital talent acquisition:Institutions competing for data engineers and UX designers capable of building Shariah-compliant core banking systems face wage pressure from conventional fintech employers in Singapore and Bangalore.
- Legacy core system integration:Established Islamic banks operating on decades-old mainframe architectures encounter friction when embedding real-time Shariah audit trails and asset segregation tracking into existing transaction processing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Islamic Finance Market |
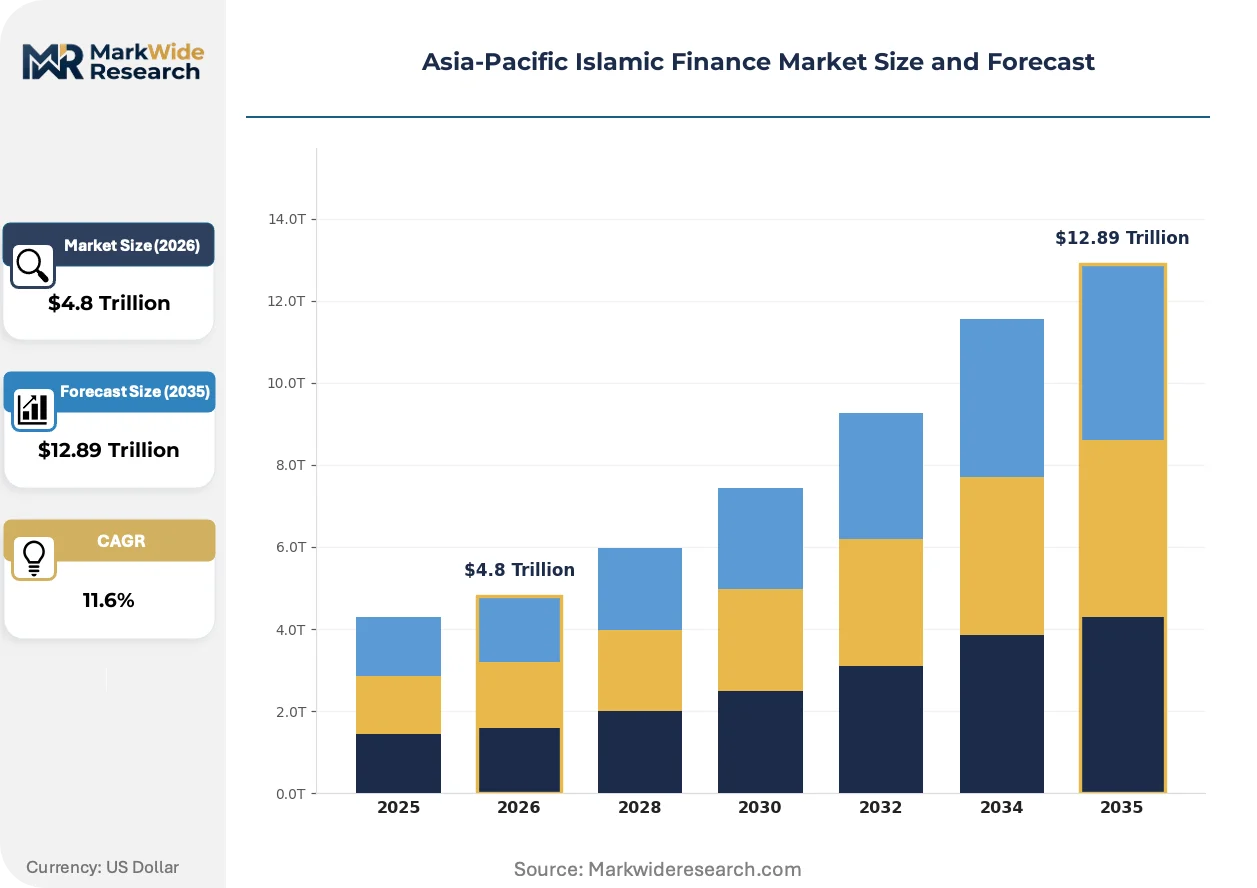
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $12.89 Trillion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Islamic Banking, Sukuk, Takaful, Islamic Investment Funds End User: Retail Clients, Corporates, Government Agencies, Non-Profit Organizations Service Type: Financial Advisory, Asset Management, Wealth Management, Retail Banking Application: Retail Finance, Corporate Finance, Trade Finance, Real Estate Financing |
| Companies Covered | Maybank Islamic, Bank Rakyat, CIMB Islamic Bank, RHB Islamic Bank, Bank Islam Malaysia, Public Islamic Bank, AmBank Islamic, MBSB Bank, Hong Leong Islamic Bank, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Islamic Finance Market Strategic Shifts
Technology convergence and regulatory harmonization are compressing product development cycles while fragmenting traditional distribution hierarchies across the Asia-Pacific Islamic finance corridor.
Application programming interface (API) orchestration layers are unifying previously siloed Shariah compliance, risk management, and customer onboarding functions into modular banking-as-a-service stacks. Neobanks in Indonesia and Malaysia are adopting these pre-certified middleware solutions to launch Islamic product suites within months rather than years. This unifying architecture is compressing capital requirements for market entry and enabling specialized niche players to compete against full-service incumbents.
Indonesia's Financial Services Authority (OJK) has issued harmonized digital banking regulations that align Shariah governance requirements with conventional fintech licensing standards. This regulatory convergence eliminates duplicate compliance layers for hybrid institutions and accelerates cross-selling between Islamic and conventional product lines. Rural cooperative banks (BPRS) across Java and Sumatra are the primary beneficiaries, gaining access to previously restricted payment system infrastructure.
Retail investors are migrating from branch-based takaful subscription toward embedded insurance distribution through e-commerce and ride-hailing super-apps. GoTo Financial in Indonesia and Grab Financial Group in Singapore have integrated Shariah-compliant term life and family takaful products into their existing wallet ecosystems. This channel shift is most visible among under-35 demographics in Greater Jakarta and Kuala Lumpur, where policy issuance through non-bank platforms now exceeds traditional agency channels.
Asia-Pacific Islamic Finance Market Segmentation
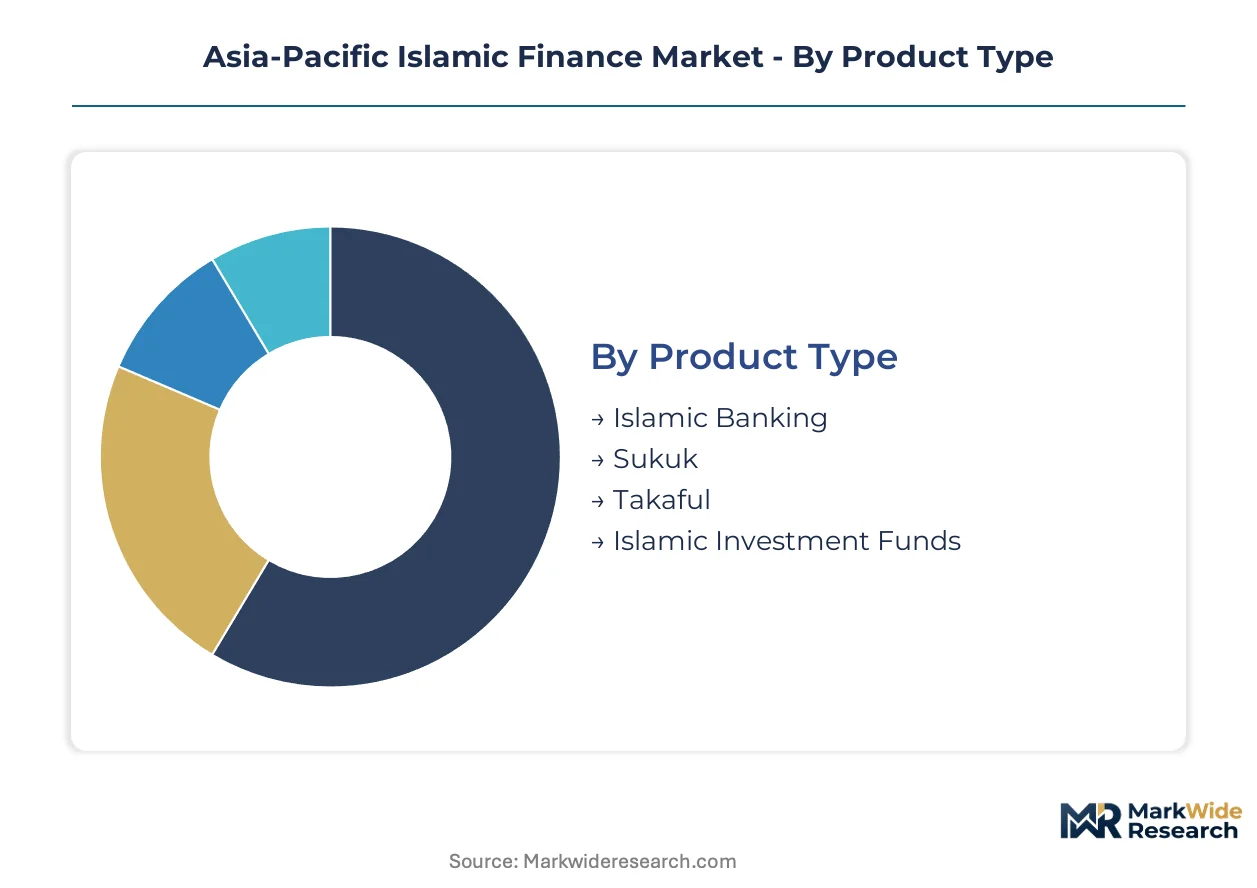
Segmentation in Asia-Pacific Islamic finance reveals how capital allocation, regulatory treatment, and customer infrastructure requirements vary dramatically across product and service dimensions. Understanding these structural differences exposes where margin pools concentrate and which segments demand transformative technology investment.
Product Type:
Capital intensity varies sharply across product categories, with sukuk issuance requiring substantial underwriting infrastructure and sovereign-grade legal frameworks while retail banking products demand distributed branch and digital platform networks.
- Islamic Banking:Deposit-taking and financing operations built on wakala and mudaraba contracts require extensive physical distribution networks across Indonesia's archipelago and Malaysia's peninsula. Rural penetration in Malaysia's heartland states and Indonesia's outer islands drives infrastructure spending.
- Sukuk:Asset-backed securities structured around ijara or murabaha contracts demand sophisticated legal documentation, independent Shariah board certification, and secondary market making capabilities. Sovereign and quasi-sovereign borrowers in Malaysia and Indonesia dominate primary issuance activity.
- Takaful:Mutual insurance structures pool participant contributions into shared risk funds governed by tabarru principles.
- Islamic Investment Funds:Collective investment vehicles screening equities and sukuk for Shariah compliance.
Most installed capacity flows through Islamic Banking. Expansion is steepest in Sukuk.
End User:
Customer sophistication and transaction scale create distinct service requirements across user categories, with government agencies demanding complex structured finance and retail clients driving volume through standardized products.
- Retail Clients:Individual consumers seeking Shariah-compliant deposits, financing, and protection products represent the broadest addressable base. Mobile-first acquisition through super-app ecosystems in Greater Jakarta and Kuala Lumpur is displacing traditional branch-based onboarding.
- Corporates:Multinational and domestic enterprises establishing Shariah-compliant treasury operations, trade finance facilities, and working capital solutions require customized structuring around commodity murabaha and wakala arrangements. Cross-border ASEAN liquidity management needs are intensifying.
- Government Agencies:Sovereign and municipal borrowers accessing alternative funding mechanisms.
- Non-Profit Organizations:Charitable entities deploying zakat and waqf assets into productive investments.
Transaction volume concentrates with Retail Clients. Value expansion is most rapid among Corporates.
Service Type:
Revenue model stability differs across service categories, with asset management generating recurring fee streams and retail banking depending on net interest margin equivalents and transaction volume.
- Financial Advisory:Shariah-compliant structuring, capital raising counsel, and merger advisory services require specialized jurist and investment banking expertise concentrated in Kuala Lumpur and Jakarta. Complex cross-border transactions involving Indonesian and Bangladeshi SME trade finance are elevating demand.
- Asset Management:Portfolio construction and administration for institutional and retail investors screening for Shariah compliance and ESG alignment. Malaysia's SRI Sukuk Framework integration with green bond taxonomies is opening sovereign ESG investor pools.
- Wealth Management:High-net-worth succession planning and estate structures.
- Retail Banking:Mass-market deposit, financing, and payment services.
Fee income stability is strongest in Asset Management. New client acquisition is expanding fastest in Financial Advisory.
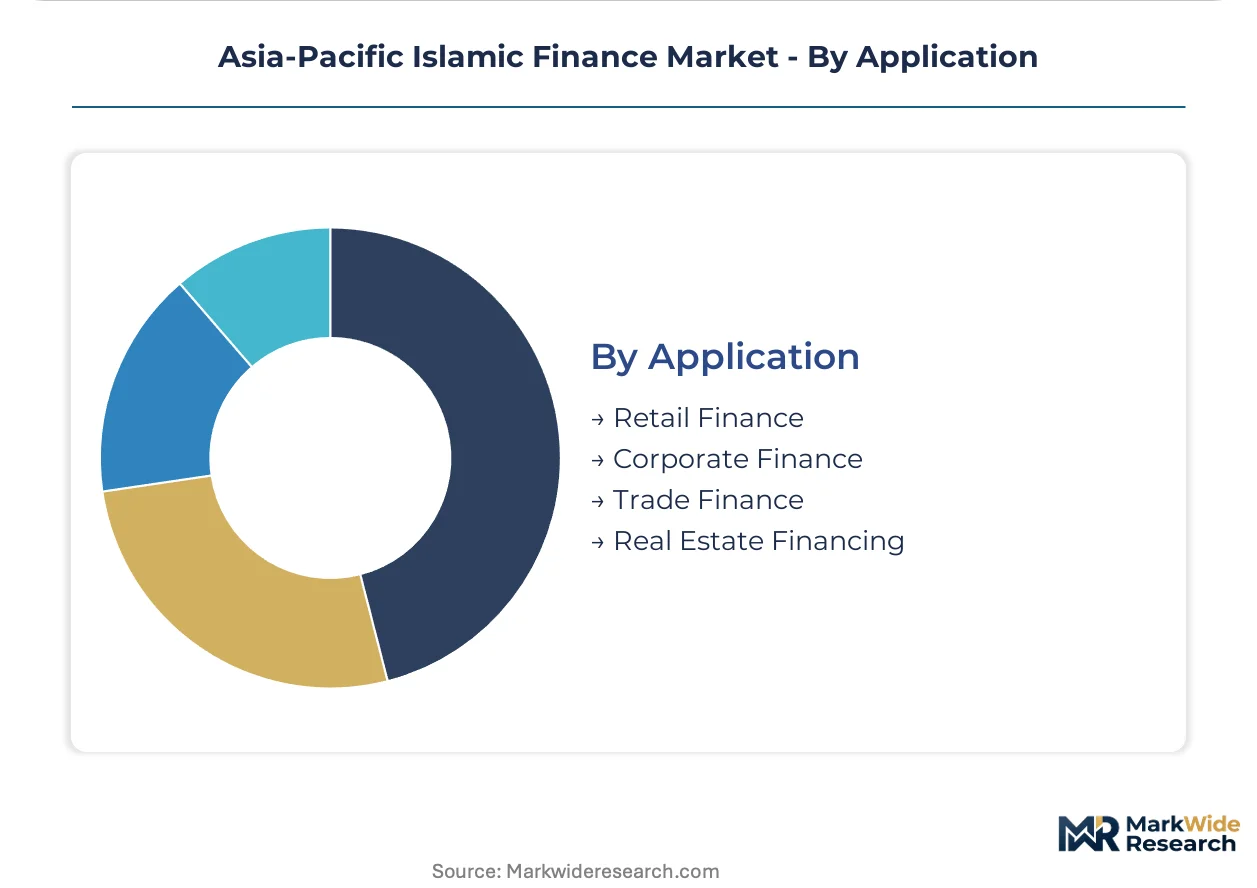
Application:
Underlying asset collateralization requirements and risk-weighting frameworks create divergent capital deployment economics across application areas, with real estate demanding physical asset backing and trade finance revolving around commodity flows.
- Retail Finance:Consumer durables, housing, and vehicle financing structured through diminishing musharaka or ijara contracts require standardized credit scoring and collateral valuation systems. Digital origination platforms in Indonesia are compressing approval cycles from weeks to hours.
- Corporate Finance:Project finance, acquisition funding, and balance sheet restructuring for enterprise borrowers employ hybrid sukuk-mudaraba structures. Infrastructure development across Indonesia's Trans-Java corridor and Malaysia's East Coast Rail Link is channeling institutional capital.
- Trade Finance:Cross-border commodity and merchandise financing.
- Real Estate Financing:Development and investment property funding.
Outstanding exposure concentrates in Retail Finance. New commitment growth is climbing the fastest in Corporate Finance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating Islamic finance licensing activity in jurisdictions with streamlined Shariah governance frameworks, as Bangladesh and Indonesia compete for capital flows that previously defaulted to Malaysian regulatory umbrellas.
Malaysia
Bank Negara Malaysia's digital banking sandbox approvals have compressed licensing timelines for Shariah-compliant fintech entrants. The Klang Valley corridor hosts the region's densest cluster of sukuk issuance infrastructure and takaful underwriting operations. Kuala Lumpur's regulatory harmonization initiatives with AAOIFI standards are positioning the city as the default jurisdiction for cross-border Islamic securities structuring.
Indonesia
OJK's harmonized digital banking regulations are eliminating duplicate compliance layers for hybrid Islamic-conventional institutions. Rural cooperative banks across Java and Sumatra are gaining access to payment system infrastructure previously restricted to full-service lenders. Greater Jakarta's super-app ecosystems are displacing traditional takaful distribution channels among under-35 demographics.
Bangladesh
Small and medium enterprises are expanding utilization of Shariah-compliant murabaha contracts for cross-border commodity financing. The country's central bank has introduced liquidity facility frameworks for Islamic banks mirroring conventional rediscount windows. Dhaka's garment export clusters are driving demand for trade finance products structured around wakala arrangements.
Singapore
The Monetary Authority of Singapore's green bond taxonomy alignment with Shariah principles is attracting sovereign ESG investor pools into Southeast Asian sukuk markets. Cross-border ASEAN liquidity management needs are intensifying among multinational treasury operations headquartered in the city-state. Singapore's wealth management infrastructure is channeling high-net-worth capital into Malaysian and Indonesian Islamic investment funds.
Asia-Pacific Islamic Finance Market Competitive Environment
Digital platform expansion dominates the current landscape as established institutions defend deposit franchises against mobile-first entrants. The market structure reflects a tiered configuration with full-service universal banks, specialized Islamic subsidiaries, and emerging neobank challengers. Three strategic archetypes define competitive positioning: branch-anchored rural networks, API-driven digital platforms, and cross-border liquidity specialists. Portfolio diversification into takaful and asset management, alongside strategic technology partnerships with fintech infrastructure providers, represent the dominant competitive moves.
Within the full-service banking tier, Maybank Islamic and CIMB Islamic Bank exemplify scale-driven competitors with integrated ASEAN footprints. Bank Rakyat occupies a distinctive position as a cooperative-structured institution anchored in Malaysia's rural heartland states. These three entities collectively represent the spectrum of distribution strategies—from digital-first customer acquisition to cooperative network penetration—that competitors must navigate.
| Leading Market Players |
|---|
| Maybank Islamic |
| Bank Rakyat |
| CIMB Islamic Bank |
| RHB Islamic Bank |
| Bank Islam Malaysia |
| Public Islamic Bank |
| AmBank Islamic |
| MBSB Bank |
| Hong Leong Islamic Bank |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed Islamic banks across Malaysia and Indonesia anchor supply concentration through their control of primary sukuk issuance infrastructure and Shariah-compliant payment rails, translating into pricing discipline that resists commoditization in retail banking products while compressing margins in standardized trade finance instruments.
Pricing Analysis
Distributor margin layers in Shariah-compliant financial services vary sharply between direct institutional placement and retail agency channels. Three-tier pricing structure across premium advisory, standard banking products, and economy microfinance tiers reflects certification complexity and relationship depth. Pricing pressure stems from digital neobanks stripping branch overhead from customer acquisition costs. Retail clients in Indonesia's outer islands show highest price sensitivity, while sovereign borrowers in Malaysia demonstrate lowest sensitivity due to regulatory preference alignment.
Supply Chain Analysis
Dual-sourcing requirements for Shariah governance expertise force institutions to qualify jurists from both Kuala Lumpur and Dubai for complex product certification. Supply concentrates in Malaysia, Indonesia, and Bangladesh for retail distribution infrastructure, with Singapore anchoring cross-border liquidity management. Raw material dependencies include Shariah scholar labor pools, regulatory sandbox approvals, and API-enabled core banking platforms. Single-source vulnerability runs through concentrated jurist expertise in key financial centers. Distribution runs through branch networks, mobile super-apps, and cooperative BMT channels across the archipelago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific Islamic finance operates as a stable compounder anchored by regulatory-mandated Shariah compliance requirements that perpetually renew demand for certified expertise and infrastructure.
For Market Incumbents: Anticipate margin compression in standardized retail products from API-enabled neobanks by deepening captive Shariah governance capabilities in-house rather than outsourcing to concentrated jurist pools. Defend deposit franchises through exclusive takaful bundling and cooperative network lock-in across Malaysia's rural heartland states. For New Entrants and Emerging Players: Begin with underpenetrated rural Indonesia outside Java's major urban centers, where BMT cooperatives lack digital infrastructure and mobile-first takaful distribution remains nascent. Capture white space through embedded finance partnerships with ride-hailing and e-commerce super-apps rather than competing on branch density. For Investors and Strategic Acquirers: Conventional ASEAN universal banks with Islamic window aspirations are the most active acquirer in this space, seeking licensed entities to bypass regulatory sandbox timelines. Target acquisition candidates with established Shariah board infrastructure and rural distribution licenses rather than pure technology plays. Watch for regulatory harmonization announcements between OJK and Bank Negara Malaysia as inflection signal for cross-border consolidation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Shariah Governance Technology Integration | Automated compliance oracles embedded in core banking systems reduce jurist bottlenecks at Bank Negara Malaysia-licensed institutions. |
| Rural Cooperative Digital Infrastructure | API-layer deployment across Indonesia's BMT networks unlocks previously unreachable micro-sukuk and takaful subscriber bases. |
| Green Sukuk Framework Alignment | Malaysia's SRI Sukuk certification convergence with Indonesia's green bond taxonomy opens sovereign ESG investor capital pools. |
| Cross-Border ASEAN Liquidity Management | Singapore-domiciled multinational treasury operations demand Shariah-compliant cash pooling across Malaysia and Indonesia jurisdictions. |
| Blockchain Smart Contract Deployment | Distributed ledger automation of wakala and ijara execution cycles compresses settlement from weeks to hours for OJK-supervised institutions. |
Study Parameters
Multiple input streams — structured interviews with Shariah board secretaries and digital banking product heads, regulatory filing analysis from OJK and Bank Negara Malaysia, and sukuk issuance database reconciliation — were combined to construct segment-level demand estimates. Primary fieldwork engaged Islamic bank treasury managers, takaful distribution heads, and fintech platform engineers across Kuala Lumpur, Jakarta, and Dhaka. Secondary validation drew from AAOIFI standards documentation, central bank sandbox approval registers, and ASEAN cross-border payment system disclosures. Bottom-up product volume builds were triangulated against top-down macroeconomic allocation models.
Historical issuance patterns were cross-referenced against panel input from institutional investors and sovereign borrowers to anchor growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, service category, end-user sophistication tier, and application area dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory event probabilities and technology adoption S-curves. Forecast inputs included Shariah scholar capacity expansion rates, digital banking license approval velocities, and super-app ecosystem penetration curves.
Caveats apply where regulatory harmonization delays, jurist supply constraints, or conventional interest rate arbitrage opportunities could materially shift the outlook. Forecasts embed assumptions around sandbox approval continuity and cross-border ASEAN liquidity framework implementation. Deviation in central bank digital Islamic banking license velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Bank Management Software Market
Banking
Africa Data Analytics in Banking Market
Banking
China Data Analytics in Banking Market
Banking
E-Banking Market
Banking
Investment Banking Market
Banking
South America Challenger Banks Market
Banking
Commercial Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Retail Banking IT Spending Market
Banking
Spain Data Analytics in Banking Market
Banking
Cybersecurity in Banking Market
Banking
Australia Neobanking Market
Banking
Bank Kiosk Market
Banking
Letter of Credit Confirmation Market
Banking
Corporate Digital Banking Market
Banking
Germany Neobanking Market