
 Letter of Credit Confirmation Market | 2026-2036
Letter of Credit Confirmation Market Size, Share, and Industry Trends Forecast 2026-2036
Letter of Credit Confirmation Market Intelligence
Singapore's trade finance hub expansion is reshaping regional letter of credit confirmation flows. HSBC leverages its correspondent banking network across Asia-Pacific to dominate confirmation origination for commodity-linked transactions. Standard Chartered anchors its competitive position through deep relationships with African and Middle Eastern issuing banks. JPMorgan Chase competes on large-ticket confirmations for North American multinational supply chains, sustaining pricing power through balance sheet scale.
A letter of credit confirmation is a binding undertaking by a second bank, known as the confirming bank, to honor the payment obligation of the issuing bank under specified documentary terms, typically governed by ICC Uniform Customs and Practice for Documentary Credits. The instrument transfers credit risk from the issuing bank to the confirming bank, requiring capital allocation against the exposure under applicable prudential rules. Confirmation services command premium pricing relative to advisory or issuance functions due to the direct payment guarantee and capital charge absorption. Large enterprise transactions generate the deepest margin pools, while small and medium transaction sizes represent the fastest-growing volume segment as digital onboarding reduces unit economics. Manufacturing verticals sustain the highest confirmation penetration rates, particularly for machinery and raw material imports where supplier credit terms remain constrained.
Basel III endgame rules from the Basel Committee on Banking Supervision are tightening risk-weighted asset calculations for trade finance exposures, directly affecting confirmation capacity and pricing across European and Asian confirming banks. The ICC Banking Commission's ongoing digital trade standards work, alongside national implementations of the UNCITRAL Model Law on Electronic Transferable Records, is reshaping documentary requirements and operational workflows. Stakeholders must monitor how regulatory capital treatment evolves relative to supply chain finance alternatives, as this calibration will determine confirmation pricing competitiveness against open account structures and bank payment obligations.
Market Dynamics
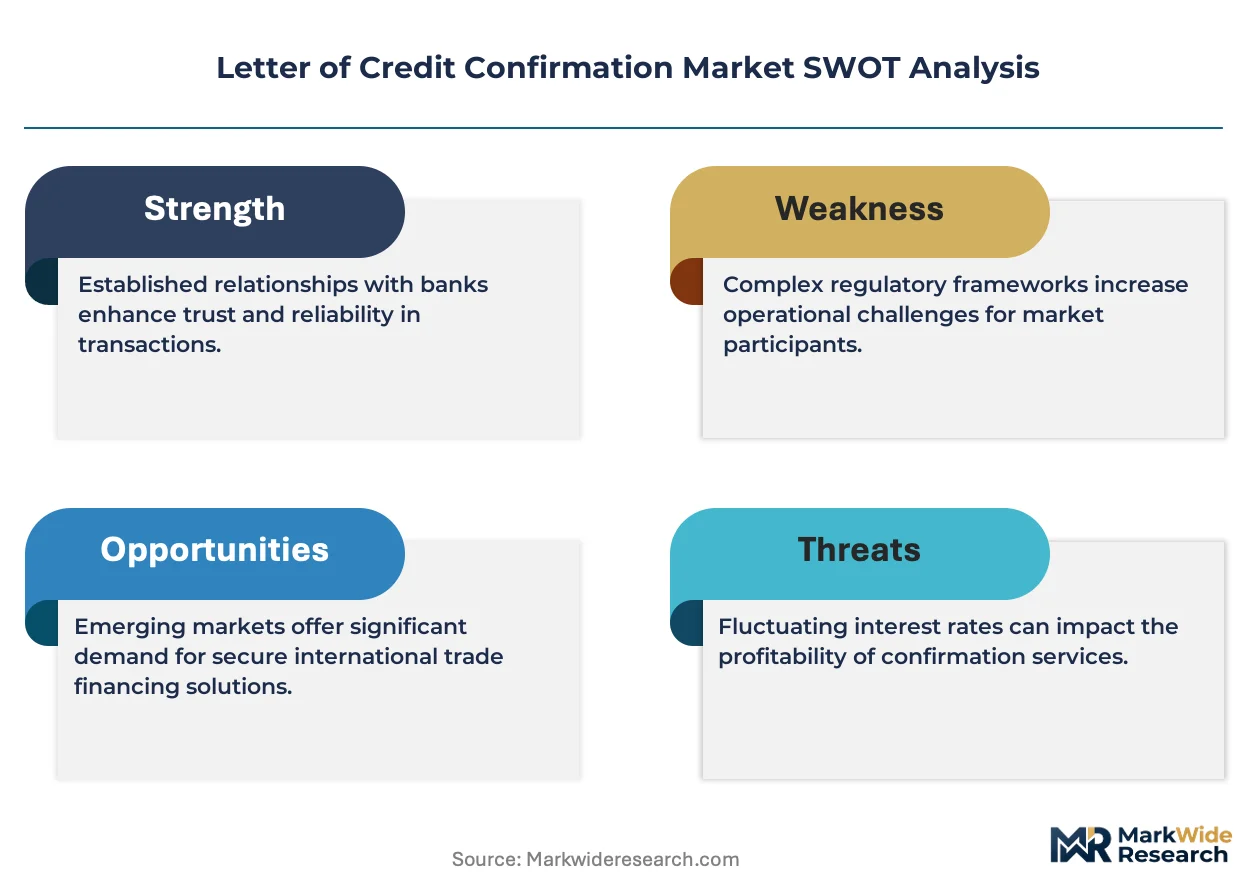
Basel III endgame capital requirements are compressing confirmation capacity at European and Asian banks, forcing pricing recalibration and selective risk appetite shifts across the trade finance ecosystem.
Growth Catalysts
- Basel III Framework Adjustments:Tighter risk-weighted asset rules for trade exposures are pushing regional banks in Vietnam and Indonesia to seek confirming bank partnerships, expanding addressable volume for international confirmers.
- Southeast Asian Manufacturing Corridors:Export-led industrialization across Vietnam, Thailand, and Malaysia generates sustained demand for confirmed letters of credit as local suppliers require payment guarantees from unfamiliar buyers.
- Commodity Trade Volatility:Counterparty risk spikes in energy and metals trading are driving traders toward confirmed instruments, particularly for transactions involving emerging market issuing banks with limited credit ratings.
Market Restraints
- Capital Charge Compression:The 100% risk weight floor under Basel III endgame rules elevates cost of funds for confirmation exposures, constraining profitability at mid-tier confirming banks.
- Concentrated Correspondent Networks:Dependency on a narrow tier of global systemically important banks for confirmation coverage creates capacity bottlenecks during periods of heightened credit stress.
- Open Account Substitution:Supply chain finance platforms and bank payment obligations are capturing transaction flow from traditional documentary credit structures, particularly in intra-regional European trade.
Strategic Opportunities
- Digital Document Standards:The ICC Banking Commission's work on electronic trade documents, coupled with UNCITRAL Model Law implementations, enables straight-through processing and operational cost reduction.
- African Trade Finance Gap:Underpenetrated confirmation coverage for intra-African trade creates expansion potential for banks with established relationships with central banks in Nigeria, Kenya, and South Africa.
- Small-Ticket Digital Onboarding:Automated KYC and document verification technologies are collapsing unit economics for SME confirmations, opening volume pools previously excluded by manual processing costs.
Industry Challenges
- Documentary Fraud Detection:Sophisticated falsification of bills of lading and commercial invoices demands enhanced verification protocols, stretching operational risk management capabilities.
- Legacy System Integration:Core banking platforms at established confirming banks require substantial modification to accommodate electronic transferable records and API-based trade finance connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Letter of Credit Confirmation Market |
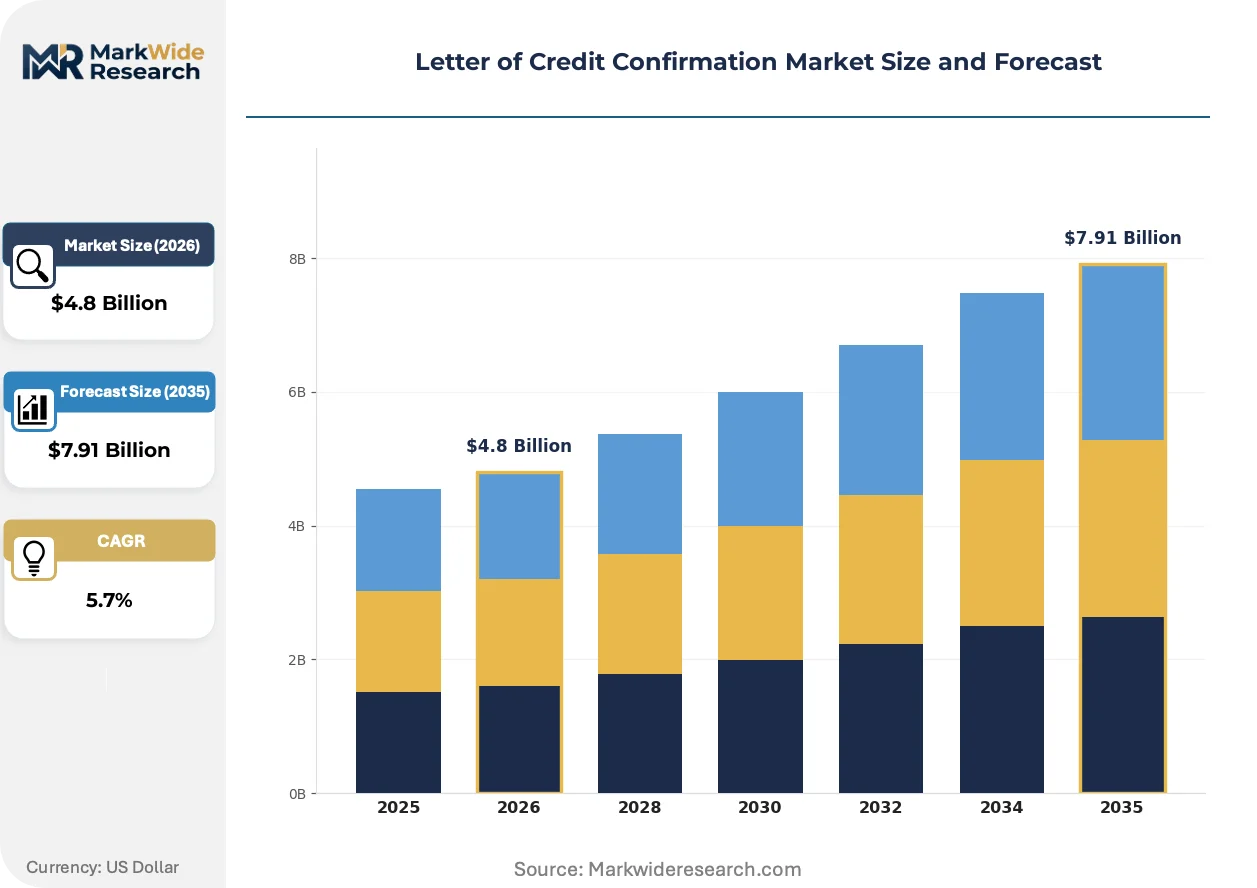
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Advisory, Issuance, Confirmation, Amendment Customer Type: Exporters, Importers, Banks, Financial Institutions Transaction Size: Small, Medium, Large, Enterprise Industry Vertical: Manufacturing, Retail, Agriculture, Technology |
| Companies Covered | HSBC, Standard Chartered, JPMorgan Chase, MUFG Bank, Bank of America, Citigroup, Mizuho Bank, Sumitomo Mitsui Banking Corporation, DBS Bank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Letter of Credit Confirmation Market Strategic Shifts & Innovations
Distributed ledger infrastructure and machine learning verification tools are reconfiguring operational workflows, while regulatory digitization mandates accelerate documentary transformation.
Blockchain-based trade finance platforms are rendering obsolete paper-based document presentation and manual examination processes. Commodity traders and large manufacturers in Singapore and Dubai are piloting smart contract-enabled confirmations, compressing settlement cycles from days to hours and eliminating discrepancies that previously triggered payment delays.
The EU's Digital Operational Resilience Act and the UK's Electronic Trade Documents Act are mandating electronic record acceptance across member jurisdictions. These frameworks compel confirming banks to restructure back-office operations, with London-based institutions accelerating API development to maintain compliance and service continuity for cross-border transactions.
Buyers in machinery and industrial equipment sectors are unbundling confirmation arrangements from broader banking relationships, selecting confirming banks on transaction-specific pricing and jurisdiction expertise rather than historical ties. German and Japanese capital goods exporters increasingly route Asian-bound shipments through Singapore-based confirmers to optimize coverage terms and reduce all-in confirmation costs.
Letter of Credit Confirmation Market Segmentation
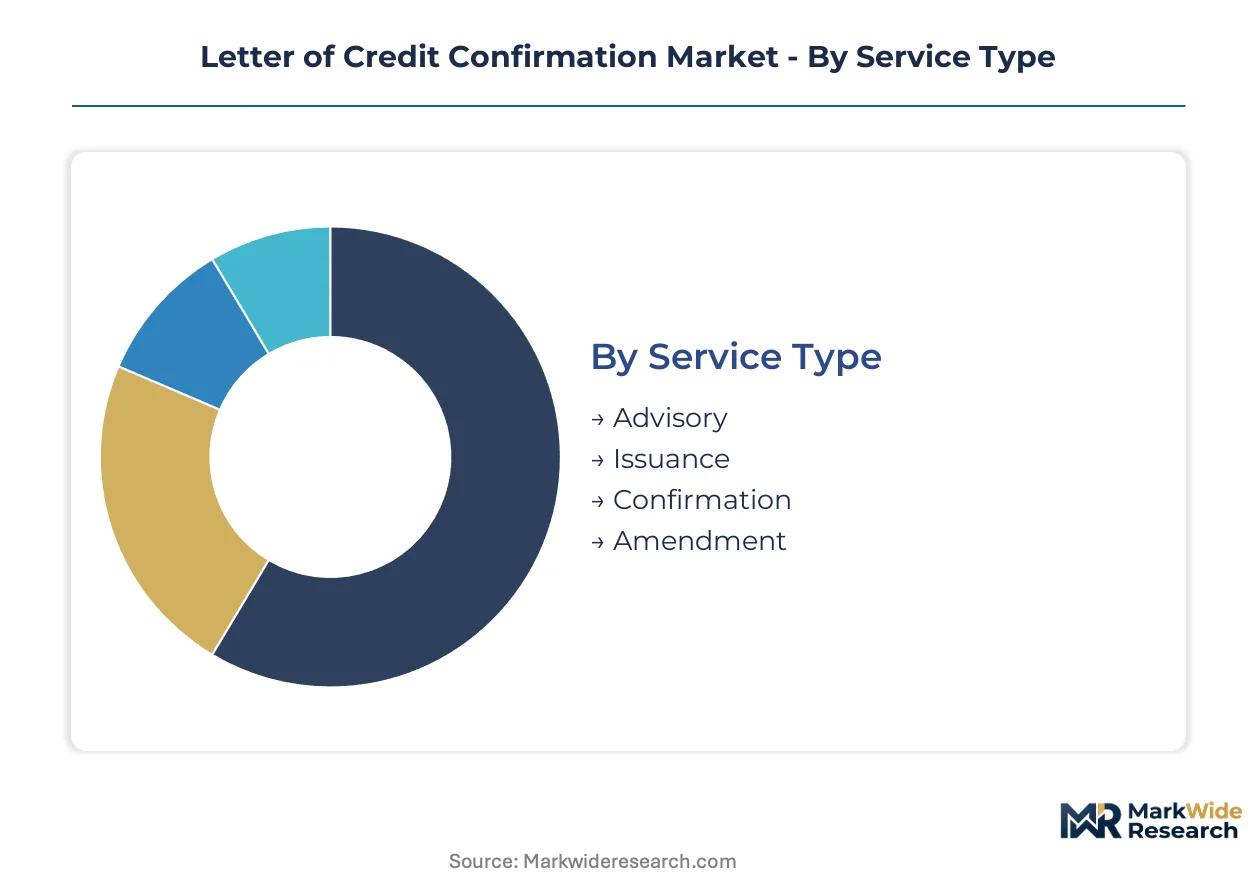
Segmentation in the letter of credit confirmation market reveals distinct operational economics and risk profiles across service tiers and customer categories. Banks calibrate capital allocation, pricing models, and relationship management intensity based on these structural divisions.
Service Type:
After-sales service intensity varies dramatically across service types, with confirmation requiring ongoing payment guarantee monitoring while advisory demands episodic consultative support.
- Confirmation:A binding payment undertaking by the confirming bank that absorbs the issuing bank's credit risk under ICC UCP rules. Demand concentrates in commodity trading corridors linking Singapore and Dubai, driven by counterparty risk spikes in energy and metals transactions involving emerging market banks.
- Issuance:The originating bank's documentary credit creation that establishes the primary payment obligation. German and Japanese capital goods exporters favor issuance bundled with confirmation arrangements to streamline supplier relationships across Southeast Asian manufacturing clusters.
- Advisory:Non-binding notification and examination services without payment guarantee. Banks in Vietnam and Indonesia leverage advisory partnerships to access international confirmation networks without bearing full capital charges.
- Amendment:Modifications to existing credit terms including tenor extensions, value adjustments, or documentary requirement changes. Processing volumes spike during commodity price volatility when traders renegotiate shipment schedules.
Confirmation holds the largest share; momentum sits with advisory as regional banks seek confirming partnerships without capital absorption.
Customer Type:
Cost tier differentiation separates premium relationship-driven exporters from transaction-priced importer segments with limited banking alternatives.
- Exporters:Suppliers requiring payment security from unfamiliar buyers, predominantly machinery and raw material sellers in manufacturing verticals. Exporters in Thailand and Malaysia drive confirmation penetration as they expand into African and Middle Eastern markets with untested counterparties.
- Banks:Financial institutions seeking confirming bank partnerships to extend payment guarantee coverage beyond their capital constraints. Vietnamese and Indonesian regional banks represent expanding demand as Basel III endgame rules compress their direct confirmation capacity.
- Importers:Buyers utilizing confirmed instruments to secure supplier credit terms when open account financing is unavailable. Importer demand clusters in capital goods procurement where supplier credit remains constrained.
- Financial Institutions:Non-bank entities including trade finance funds and insurance-backed platforms entering confirmation risk participation. This segment climbs fastest as alternative capital providers seek yield in trade finance assets.
Banks command the deepest margin pools; financial institutions are gaining share fastest through alternative capital structures.
Transaction Size:
Volume concentration shapes operational workflow design, with digital onboarding collapsing unit economics at the small-ticket end while enterprise transactions sustain relationship banking models.
- Enterprise:Large-ticket confirmations exceeding thresholds that require syndicated confirming bank participation or single-name concentration limits. Singapore-based confirmers dominate this tier for Asian-bound shipments from European capital goods exporters.
- Large:Sub-syndication scale transactions generating premium pricing through bespoke documentation and jurisdiction expertise. Large transactions sustain pricing power at HSBC and Standard Chartered through balance sheet scale.
- Medium:Mid-market confirmations benefiting from standardized documentation and streamlined examination protocols. Medium-tier volume expands as automated KYC technologies reduce onboarding friction.
- Small:SME-scale transactions previously excluded by manual processing costs. Small-ticket confirmation is expanding most quickly as API-based trade finance platforms collapse unit economics and extend coverage to previously unserved exporters.
Enterprise transactions hold the largest share; small-ticket confirmation shows the steepest expansion trajectory through digital onboarding.
Industry Vertical:
Application-specific risk profiles drive confirmation penetration rates, with manufacturing sustaining deepest coverage due to machinery import financing constraints.
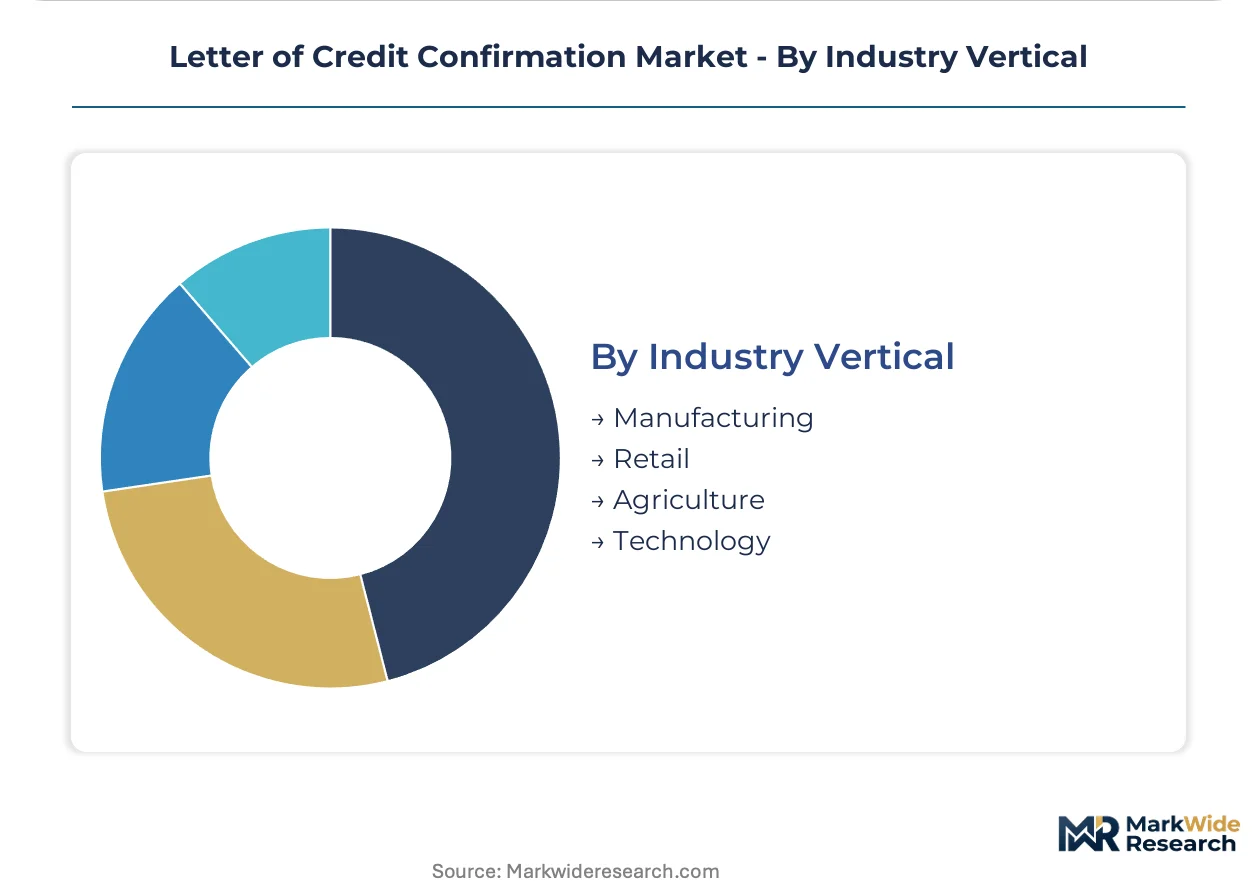
- Manufacturing:Machinery and raw material imports where supplier credit terms remain constrained and documentary credit structures dominate. Manufacturing sustains the highest confirmation penetration rates across Southeast Asian industrial corridors in Vietnam, Thailand, and Malaysia.
- Agriculture:Commodity trading flows with seasonal financing patterns and counterparty risk concentration in emerging market issuing banks. Agricultural confirmation demand spikes during harvest financing windows in grain and soft commodity exports.
- Retail:Consumer goods trade with shorter tenor requirements and higher transaction frequency. Retail confirmation volumes concentrate in apparel and electronics supply chains linking Asian manufacturers to European and North American buyers.
- Technology:Semiconductor and electronics components trade with specialized documentary requirements around quality certification and intellectual property protection. Technology vertical confirmation is climbing fastest as supply chain regionalization drives new counterparty relationships.
Manufacturing holds the largest share; technology is gaining share fastest through supply chain restructuring and new counterparty formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Singapore Port's container throughput and financial infrastructure anchor Asia-Pacific trade finance flows, with correspondent banking networks radiating confirmation capacity across manufacturing corridors.
Singapore
Commodity traders and capital goods exporters drive confirmation demand through the port's bunkering and re-export hub. The Monetary Authority of Singapore's trade finance digitization initiatives accelerate electronic transferable record adoption. Marina Bay financial district concentrates confirming bank operations serving Southeast Asian manufacturing supply chains.
Germany
Machinery and automotive capital goods exporters require confirmed instruments for Asian-bound shipments. BaFin's implementation of Basel III endgame rules compresses regional bank confirmation capacity. Frankfurt's trade finance specialists syndicate large-ticket exposures through correspondent relationships with Singapore and Dubai hubs.
United States
North American multinational supply chains generate enterprise-scale confirmation volume for raw material procurement. The OCC's prudential standards for trade finance exposures influence confirming bank risk-weighting calculations. New York correspondent banking relationships channel confirmation capacity to Latin American commodity importers.
United Arab Emirates
Dubai's commodities exchange and free zone trading entities sustain energy and metals confirmation demand. The UAE Central Bank's digital trade initiatives align with ICC electronic document standards. Jebel Ali port corridors link African and South Asian trade flows through confirming bank partnerships.
Japan
Capital goods and technology component exporters utilize confirmed structures for emerging market buyer relationships. METI's trade insurance frameworks complement private confirmation coverage for regional bank exposures. Tokyo-based megabanks syndicate confirmation risk across ASEAN manufacturing clusters.
Letter of Credit Confirmation Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in correspondent relationship management. The market structures around balance sheet scale and geographic network density, with tier-one confirmers absorbing capital charges that regional banks cannot bear. Three archetypes dominate: Asia-Pacific network hubs, European trade finance specialists, and North American balance sheet deployers. Competitive moves concentrate on correspondent network expansion and digital document platform integration.
Within the Asia-Pacific network tier, HSBC and Standard Chartered exemplify hub-and-spoke confirmation models. HSBC occupies a position spanning Singapore commodity flows and ASEAN manufacturing corridors. Standard Chartered anchors coverage for African and Middle Eastern issuing bank relationships. DBS Bank sits within the digital-native competitor archetype, leveraging Singapore's regulatory framework for electronic trade documentation.
| Leading Market Players |
|---|
| HSBC |
| Standard Chartered |
| JPMorgan Chase |
| MUFG Bank |
| Bank of America |
| Citigroup |
| Mizuho Bank |
| Sumitomo Mitsui Banking Corporation |
| DBS Bank |
| Others |
Cost & Logistics Intelligence
Correspondent banking concentration in Singapore and London anchors margin capture downstream, with confirming banks in these hubs extracting premium pricing from regional banks in Vietnam and Indonesia that lack Basel III-compliant balance sheet capacity. The capital charge absorption at confirmation origination flows through to end-user pricing tiers.
Pricing Analysis
Basel III endgame rules dictate the pricing tier structure across the letter of credit confirmation market. Three-tier pricing separates premium confirmations for commodity-linked transactions from standard manufacturing coverage and economy-tier advisory services. Price differentiation rests on capital charge absorption levels and jurisdiction risk ratings. Pricing pressure stems from open account substitution as supply chain finance platforms capture intra-regional European flow. SME importers exhibit highest price sensitivity; commodity traders with counterparty risk spikes accept premium tiers.
Supply Chain Analysis
Export control frameworks limiting technology transfer to semiconductor and capital goods sectors constrain confirming bank coverage for certain Asian-bound shipments. Geographic supply concentration centers on Singapore, Dubai, and London as primary confirmation origination hubs. Raw material dependencies include capital adequacy ratios, correspondent banking relationships, and ICC UCP documentation standards. Single-source vulnerability runs through tiered dependency on HSBC, Standard Chartered, and JPMorgan Chase networks. Distribution runs through correspondent banking partnerships with regional banks in Southeast Asian manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among Southeast Asian manufacturing exporters seeking multi-bank confirmation arrangements, fragmenting historical single-bank relationships and forcing price transparency across confirming institutions.
For Market Incumbents: Entrench correspondent network density in ASEAN manufacturing corridors before digital-native competitors capture API-based onboarding flows. Absorb incremental Basel III capital charges through balance sheet scale rather than passing through pricing that triggers open account substitution. Prioritize ICC electronic document standard integration to compress operational cost structures below mid-tier bank breakeven.
For New Entrants and Emerging Players: Build out automated KYC and document verification infrastructure to collapse unit economics in small-ticket SME confirmations. Target Vietnamese and Indonesian regional banks seeking confirming partnerships without capital absorption. Lead with advisory service relationships that convert to confirmation coverage as transaction volumes mature.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across commodity-linked confirmation segments as Basel III endgame rules tighten. Long-term viability favors institutions with diversified geographic coverage spanning Asia-Pacific, African, and Middle Eastern issuing bank relationships. Acquisition targets include digital-native trade finance platforms with API infrastructure and established regulatory licenses. Monitor ICC digital standards adoption velocity as inflection indicator for operational cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Correspondent Network Expansion | HSBC and Standard Chartered leverage Singapore hub relationships to capture ASEAN manufacturing confirmation flow. |
| Digital Document Platform Integration | DBS Bank accelerates API development to comply with Singapore MAS electronic transferable record mandates. |
| Small-Ticket Digital Onboarding | Automated KYC technologies enable coverage of previously excluded SME exporters in Vietnam and Indonesia. |
| African Trade Finance Gap Entry | Banks with Nigeria, Kenya, and South Africa central bank relationships capture underpenetrated intra-African confirmation demand. |
| Basel III Capital Optimization | Mid-tier European and Asian banks syndicate exposures through London and Singapore hub partnerships to manage risk-weighted asset constraints. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade finance association reports, and correspondent banking disclosure documents. Primary interviews engaged trade finance executives at confirming banks, documentary credit specialists at regional banks, commodity trading risk managers, and ICC Banking Commission working group participants. Secondary validation drew from Basel Committee publications, national central bank trade finance surveys, and electronic trade document implementation trackers. Bottom-up transaction volume estimates triangulate against top-down market sizing from banking association aggregates.
Forecast inputs include confirmation volume flows by corridor, Basel III capital charge evolution, and digital adoption curves for electronic transferable records. Segmentation dimensions span service type, customer category, transaction size tier, and industry vertical. CAGRs derive from regression against historical confirmation pricing and volume elasticity to counterparty risk indicators. Industry-specific inputs incorporate commodity trade volatility indices and regional bank capital adequacy trajectories across the projection horizon.
Practitioners should monitor regulatory capital treatment revisions and ICC digital standards ratification for early signals of pricing competitiveness shifts. Forecasts reflect assumptions around Basel III implementation timelines and correspondent banking network stability. Material shifts in open account substitution rates or electronic document legal recognition would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking Software Market
Banking
Banking Tax Management Software Market
Banking
Global Neobanking Market
Banking
Smart Machines in Banking Market
Banking
China Retail Banking System Market
Banking
Germany Banking As a Service Market
Banking
Singapore Data Analytics in Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
Investment Banking Market
Banking
US Banking-As-A-Service Market
Banking
Global Banking Systems Software Market
Banking
Core Banking Solutions Market
Banking
Germany Neobanking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Embedded Banking Market
Banking
Mobile Banking Market