
 Bank Kiosk Market | 2026-2036
Bank Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Bank Kiosk Market Analysis
Cloud-native software architecture is reshaping how bank kiosks receive updates and integrate with core banking systems, shifting value from hardware to platform layers. NCR Corporation leverages its enterprise software stack to control recurring revenue streams across installed bases. Diebold Nixdorf anchors North American manufacturing scale while competing on modular hardware designs. GRGBanking specializes in cash recycling technology leadership across Asian deployment environments.
A bank kiosk is a self-service terminal engineered with steel enclosures rated for IP54 outdoor durability, thermal printers, encrypted PIN pads, and cash handling mechanisms processing up to 300 notes per minute, designed to execute transactions without teller intervention. Cash deposit kiosks dominate current installed value as retail banks pursue labor cost reduction, while biometric authentication represents the fastest-growing technology segment as institutions replace card-only security models. Account opening kiosks sit at the margin-intensive frontier where identity verification workflows determine deployment economics.
The US Federal Reserve's cash access policies, the EU's GDPR biometric data rules, and India's RBI financial inclusion directives collectively shape product specifications and market access conditions across major deployment corridors. FCC certification requirements for wireless-enabled outdoor units add compliance cost layers that favor established suppliers with regulatory operations teams. Stakeholders must weigh hardware refresh timing against software subscription transitions as the primary value capture mechanism in this market.
Market Dynamics
Cloud-native software architectures are collapsing traditional hardware-centric value capture in bank kiosk deployments, forcing incumbents to rebuild recurring revenue through platform subscriptions rather than terminal sales. This structural shift reconfigures supplier-buyer power dynamics across retail banking procurement.
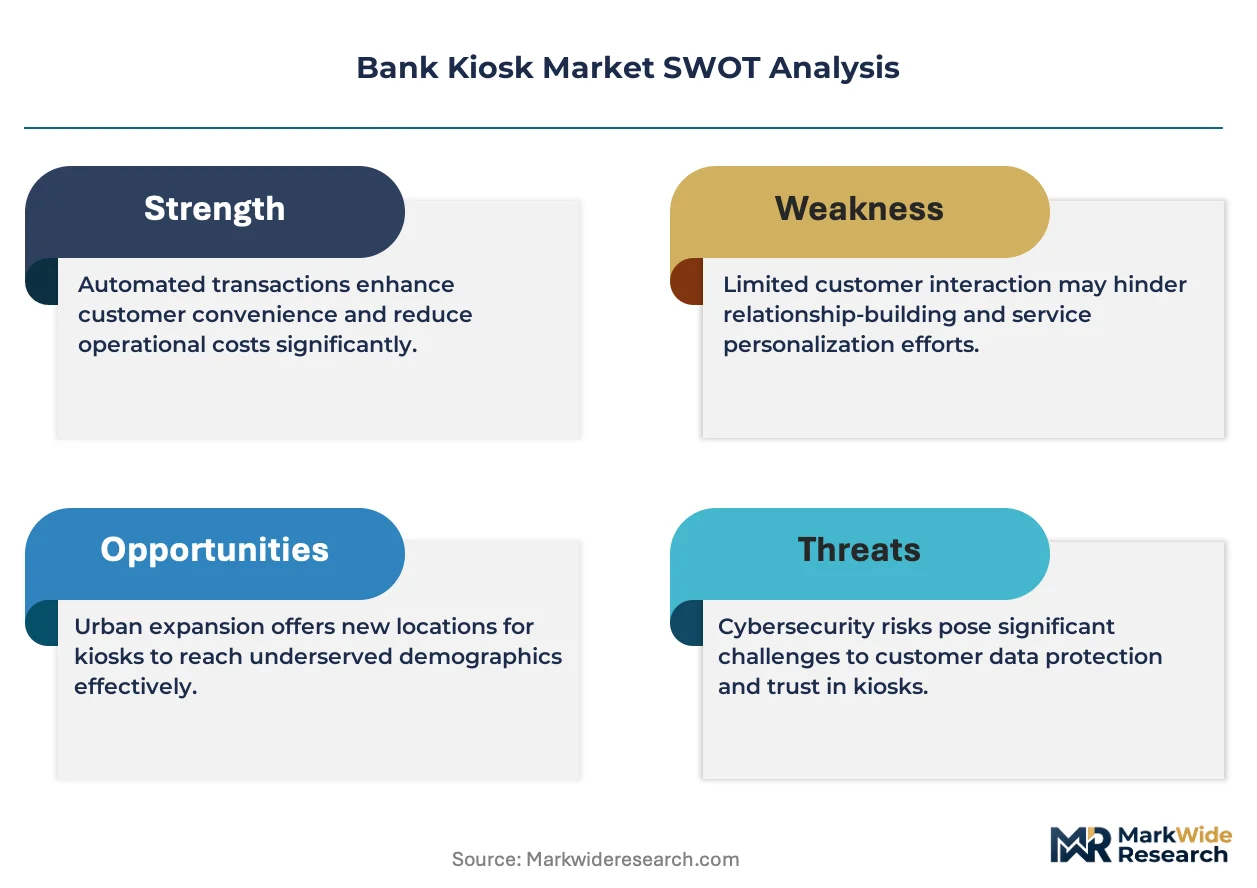
Growth Catalysts
- RBI Financial Inclusion Mandates:India's central bank directives require universal banking access, accelerating rural kiosk deployment for account opening and cash deposit functions.
- GDPR-Grade Biometric Standards:European data protection frameworks drive hardware refresh cycles as institutions replace card-only security with fingerprint and facial recognition terminals.
- Cash Recycling Technology:Advanced note validation and looped cash handling reduce branch vault operations, cutting labor costs for retail banks in high-transaction environments.
Market Restraints
- FCC Certification Burden:Wireless-enabled outdoor units face multi-month approval timelines and testing costs that favor established suppliers with dedicated regulatory operations teams.
- Steel Enclosure Input Volatility:IP54-rated chassis manufacturing depends on cold-rolled steel pricing, exposing hardware margins to commodity cycle swings.
- Core Banking Integration Complexity:Legacy mainframe architectures at tier-one banks resist API-based connectivity, delaying kiosk deployment timelines and inflating professional services costs.
Strategic Opportunities
- Indonesian Archipelago Expansion:State-owned banks target 17,000-island geography with solar-powered outdoor kiosks for unbanked populations beyond traditional branch reach.
- Video Teller Convergence:Integration of remote human assistance with self-service terminals opens premium service tiers for complex transactions.
- EU AI Act Compliance:Biometric authentication providers can capture upgrade cycles as banks preemptively deploy explainable-AI identity verification to meet forthcoming algorithmic accountability rules.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for encrypted PIN pads and cash handling mechanisms requires specialized skill sets concentrated among aging practitioner cohorts.
- Multi-Jurisdiction Certification Parallelism:Suppliers must simultaneously navigate CE marking, FCC Part 15, and BIS safety standards for cross-border deployment programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bank Kiosk Market |
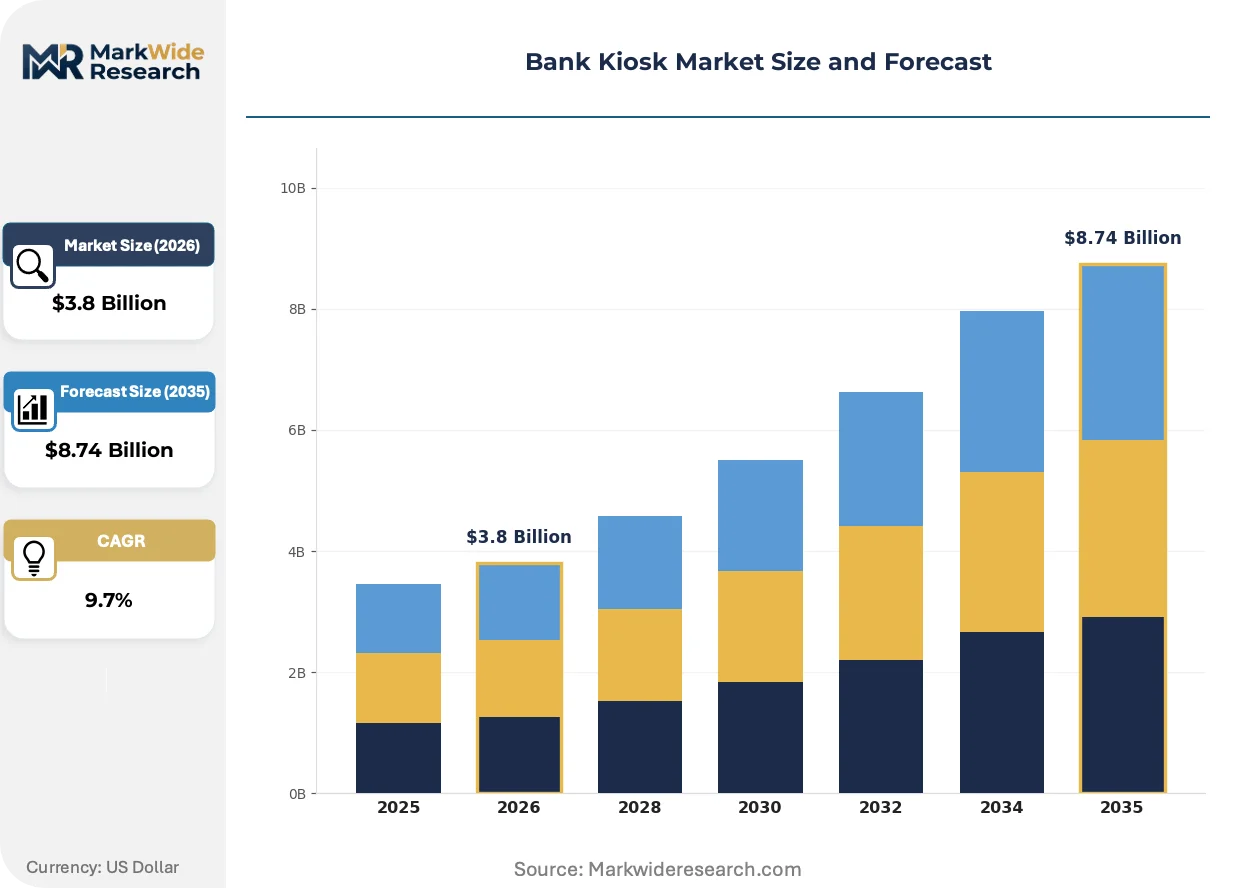
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cash Deposit Kiosk, Bill Payment Kiosk, Account Opening Kiosk, ATM Technology: Touchscreen, Biometric Authentication, Cash Recycling, Remote Monitoring End User: Retail Banks, Credit Unions, Community Banks, Online Banks Installation: Indoor, Outdoor, Mobile, Self-Service |
| Companies Covered | NCR Corporation, Diebold Nixdorf, GRGBanking, GLORY LIMITED, KAL ATM Software GmbH, Auriga SpA, Hitachi Channel Solutions, Fujitsu, Hyosung TNS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bank Kiosk Market Emerging Trajectories
Bank kiosk evolution centers on three interconnected vectors: biometric security layers replacing physical credentials, software-defined functionality decoupled from hardware refresh cycles, and deployment models shifting toward managed service outcomes rather than capital expenditure ownership.
Multimodal biometric authentication is collapsing the boundary between identity verification and transaction authorization. Fingerprint sensors combined with liveness-detection cameras now process enrollment and payment authorization in single workflows. Tier-two retail banks in Southeast Asia deploy these terminals fastest, leapfrogging card-centric infrastructure. The compression of enrollment friction is enabling account opening kiosks to operate profitably in lower-density markets previously served only by full branches.
GDPR Article 9 restrictions on special category data processing have triggered hardware redesigns across European deployments. Biometric template storage must now occur on-device with encryption keys held separately from core banking databases. Manufacturers respond with secure element integration and localized processing architectures that minimize data transit. German and French retail banks lead this specification tightening, with procurement contracts now mandating privacy-by-design certifications.
Bank procurement teams increasingly unbundle hardware acquisition from software subscription and field service agreements. Traditional capital purchase models give way to per-transaction pricing and uptime-guaranteed managed services. This reconfiguration concentrates vendor selection power among institutions with multi-thousand terminal fleets capable of justifying dedicated operational support. Indian public sector banks demonstrate this shift most visibly, with recent tenders specifying minimum availability thresholds rather than device specifications.
Bank Kiosk Market Segmentation
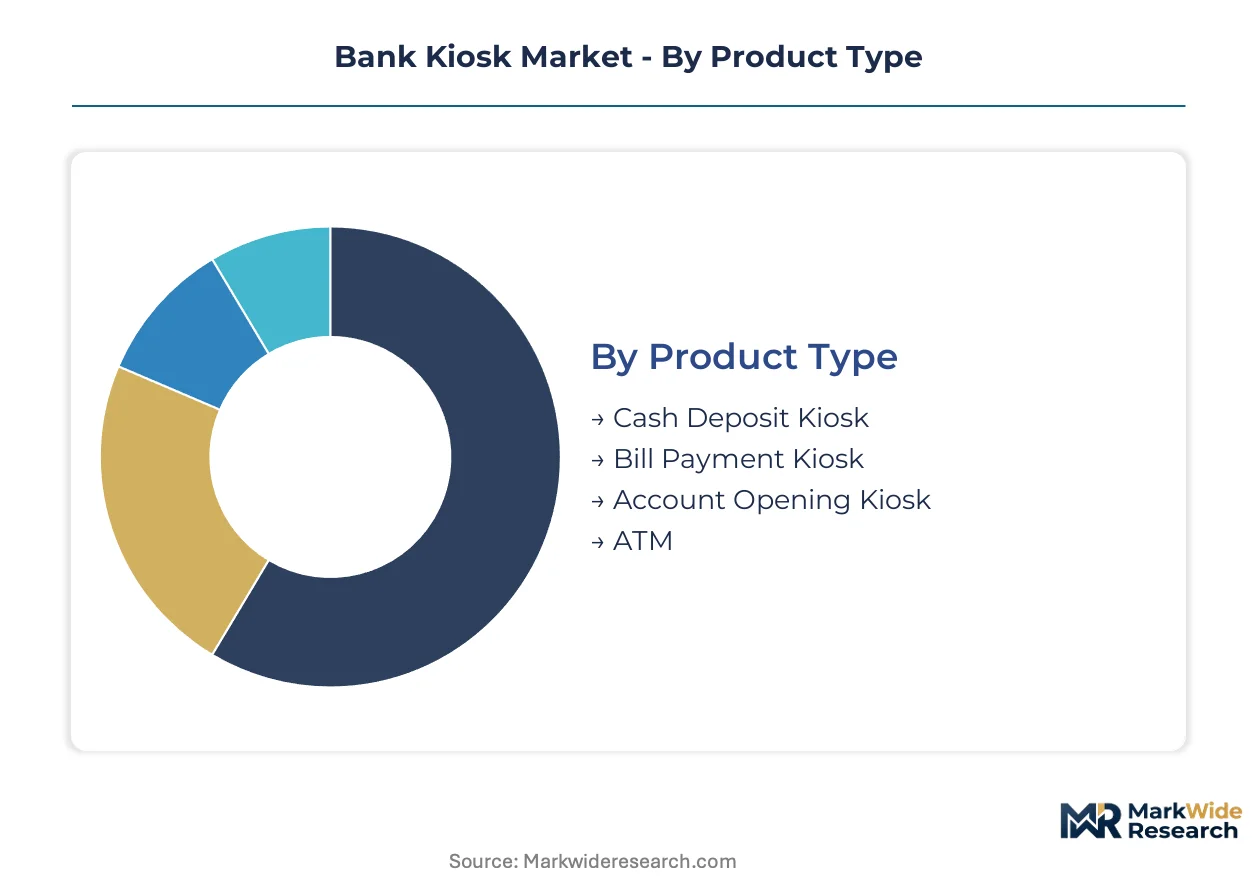
Bank kiosk segmentation reveals how hardware specifications, authentication layers, and deployment environments fragment procurement decisions across retail banking. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Cost tier differentiation separates capital-intensive cash handling systems from lower-friction service terminals, with deployment economics varying sharply by branch labor substitution potential.
- Cash Deposit Kiosk:Steel-enclosed terminals with encrypted PIN pads and note validation mechanisms processing up to 300 notes per minute. Indian public sector banks deploy these most aggressively under RBI financial inclusion mandates targeting rural unbanked populations.
- Account Opening Kiosk:Identity verification workflows integrating document scanners, biometric enrollment, and core banking API connectivity. Southeast Asian retail banks concentrate procurement here as they leapfrog card-centric infrastructure toward multimodal authentication.
- Bill Payment Kiosk:Lower-complexity terminals for utility and service remittances without cash handling mechanisms. Municipal payment corridors in Indonesian urban centers drive regional demand concentration.
- ATM:Mature withdrawal-focused infrastructure with established cash dispensing architectures. Replacement cycles now hinge on biometric upgrade compatibility rather than mechanical reliability alone.
Cash Deposit Kiosk commands the established base. The steepest expansion runs through Account Opening Kiosk.
Technology:
Application maturity varies from commoditized interface layers to emerging authentication stacks that trigger hardware refresh cycles.
- Biometric Authentication:Fingerprint sensors combined with liveness-detection cameras processing enrollment and payment authorization in unified workflows. GDPR Article 9 compliance requirements across German and French retail banks mandate on-device template storage with privacy-by-design certifications.
- Cash Recycling:Advanced note validation and looped cash handling reducing branch vault operations. High-transaction environments in Singapore and Hong Kong retail banking networks prioritize this technology for labor cost reduction.
- Touchscreen:Standardized capacitive interface layers with IP54-rated durability for indoor and outdoor deployment. Specifications now subordinate to software-defined functionality requirements.
- Remote Monitoring:Cloud-native diagnostic platforms enabling predictive maintenance and uptime guarantees. Indian public sector bank tenders increasingly specify minimum availability thresholds through managed service frameworks.
Touchscreen penetration saturates across installed bases. Biometric Authentication gains share fastest as card-only security models face regulatory displacement.
End User:
Customer type determines fleet scale, procurement centralization, and tolerance for capital expenditure versus operational expenditure models.
- Retail Banks:Multi-thousand terminal fleets with dedicated operational support justifying managed service transitions. Tier-one institutions resist API-based connectivity with legacy mainframe architectures, inflating professional services costs.
- Credit Unions:Smaller-scale deployments with shared branching networks pooling procurement leverage. Biometric upgrade cycles lag retail bank adoption timelines by several quarters.
- Community Banks:Limited branch footprints favoring lower-complexity bill payment and account opening terminals over full cash handling infrastructure.
- Online Banks:Physical presence restricted to deposit-taking and identity verification touchpoints, concentrating demand on account opening kiosks with minimal transaction processing capabilities.
Retail Banks anchor procurement volume. Online Banks expand physical footprint most aggressively as digital-native institutions add tactile verification layers.
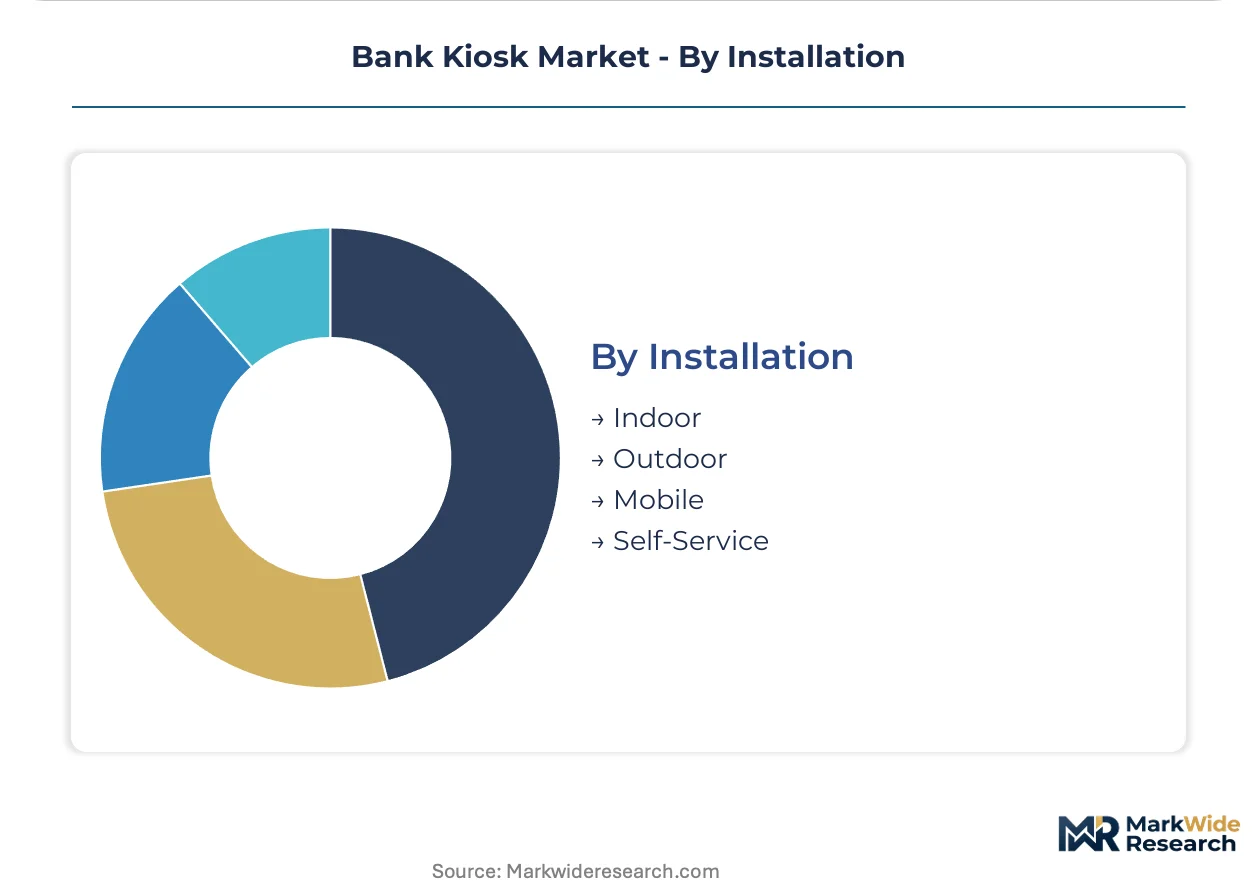
Installation:
Volume and environmental exposure dictate enclosure specifications, power requirements, and regulatory certification burdens.
- Outdoor:IP54-rated steel enclosures with thermal management and solar power compatibility for unbanked population access. Indonesian archipelago deployments across 17,000 islands drive specialized demand for off-grid operation.
- Indoor:Climate-controlled branch environments with reduced durability requirements and lower total cost of ownership. Standard procurement specifications across European and North American retail banking networks.
- Mobile:Trailer-mounted or vehicle-integrated units for temporary banking access at agricultural markets and remote community events. Indian rural financial inclusion programs pilot these configurations.
- Self-Service:Unattended operation models with remote monitoring and video teller convergence for complex transaction support. Premium service tier enablement distinguishes this category from basic automated terminals.
Indoor installations retain the dominant share. Outdoor configurations climb fastest as state-owned banks pursue geography beyond traditional branch economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail banks in India and Southeast Asia drive procurement volume, while European institutions accelerate hardware refresh cycles under biometric data regulations. State-owned banks in Indonesia and rural deployment programs across India reshape geographic demand concentration.
India
RBI financial inclusion mandates require universal banking access for rural unbanked populations. The central bank's directives accelerate deployment of account opening and cash deposit kiosks in villages below 5,000 residents. Maharashtra and Gujarat host manufacturing clusters where domestic suppliers assemble IP54-rated enclosures for pan-Indian distribution.
Indonesia
State-owned banks target financial inclusion across 17,000 islands with solar-powered outdoor kiosks. The archipelago geography demands off-grid operation capabilities beyond traditional branch economics. Java and Sumatra concentrate early procurement, with deployment expanding to Sulawesi and Papua frontier markets.
Germany
GDPR Article 9 restrictions on biometric special category data trigger privacy-by-design hardware specifications. KBA and federal data protection authorities mandate on-device template storage with encryption key separation. Frankfurt and Munich retail banking networks lead procurement of fingerprint-facial recognition multimodal terminals.
United States
FCC certification requirements for wireless-enabled outdoor units create multi-month approval timelines favoring established suppliers. The Federal Reserve's cash access policies shape deposit-taking terminal specifications. Texas and Florida community banks pilot video teller convergence for complex transaction support.
Singapore
High-transaction retail banking environments prioritize cash recycling technology for labor cost reduction. MAS regulatory frameworks accommodate biometric authentication without European-style special category restrictions. The city-state's dense urban core supports indoor deployment models with reduced durability requirements.
Bank Kiosk Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and integrated service layers. The supplier base organizes into three tiers: enterprise platform vendors with recurring revenue stacks, modular hardware fabricators with manufacturing scale, and regional specialists with cash handling technology leadership. Consolidation pressure intensifies as procurement shifts from capital expenditure to managed service frameworks. Strategic moves center on software subscription transitions and biometric authentication upgrade cycles.
Within the enterprise platform tier, NCR Corporation and Diebold Nixdorf occupy positions defined by installed base control and North American manufacturing heritage. GRGBanking represents the Asia-Pacific specialist archetype with concentration in cash recycling systems. These three anchors exemplify how supplier positioning diverges between software-centric recurring revenue capture and hardware-scale cost competitiveness.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| GRGBanking |
| GLORY LIMITED |
| KAL ATM Software GmbH |
| Auriga SpA |
| Hitachi Channel Solutions |
| Fujitsu |
| Hyosung TNS |
| Others |
Supply Flow & Price Mechanics
Cold-rolled steel price volatility determines both hardware margin compression and supplier geographic concentration in bank kiosk manufacturing. Input cost swings compress tier spreads between premium biometric-enabled terminals and standard cash-handling units, while procurement teams reweight toward suppliers with captive enclosure fabrication.
Pricing Analysis
Cost-plus contracts with cold-rolled steel indexation dominate procurement between enclosure fabricators and terminal assemblers. Pricing stratifies across premium biometric-enabled, standard cash-recycling, and economy bill-payment tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard tiers intensifies because Indian public sector banks consolidate tenders around per-transaction pricing models. Community banks exhibit highest price sensitivity due to limited fleet scale, while tier-one retail banks prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Export-control restrictions on encrypted PIN pad chipsets limit flows from US and EU suppliers to Asian assembly operations. Manufacturing concentrates in China, India, and Germany, with cold-rolled steel, thermal print mechanisms, and biometric sensor modules as critical inputs. Single-source vulnerability runs through secure element suppliers for GDPR-compliant template storage. Distribution runs through direct OEM relationships with retail banking procurement teams, supplemented by regional systems integrators in Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bank kiosk incumbents face substitution pressure from mobile banking penetration and video teller platforms that collapse the self-service value proposition. Defense requires repositioning hardware as identity verification infrastructure rather than transaction terminals.
For Market Incumbents: Harden installed base control through biometric authentication upgrade cycles ahead of EU AI Act compliance deadlines. Deepen backward integration into secure element supply to capture GDPR-mandated privacy-by-design premiums. Counter video teller substitution by embedding remote human assistance as a service tier rather than a competing channel.
For New Entrants and Emerging Players: Indonesian archipelago underpenetration offers white-space access for solar-powered outdoor kiosks beyond established branch networks. Target account opening workflows in tier-two Indian cities where RBI mandates outpace incumbent deployment capacity. Lead with managed service pricing models that shift buyer evaluation from capital expenditure to availability thresholds.
For Investors and Strategic Acquirers: EU AI Act biometric compliance deadlines reshape the acquisition landscape toward privacy-by-design certification holders. Long-term viability hinges on software subscription transitions rather than hardware replacement cycles. Monitor Indian public sector bank tender specifications for per-transaction pricing adoption as the inflection signal for managed service market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Upgrade | GDPR Article 9 compliance mandates on-device template storage with secure element integration. |
| Managed Service Transition | Indian RBI tenders specify uptime thresholds rather than device specifications, shifting value capture. |
| Cash Recycling Technology Deployment | Singapore retail banks prioritize looped cash handling to reduce branch vault labor costs. |
| Solar-Powered Outdoor Expansion | Indonesian state-owned banks target 17,000-island geography beyond traditional branch economics. |
| Video Teller Convergence | Texas and Florida community banks pilot remote human assistance for complex transaction support. |
Methodological Framework
Operator-level perspectives from retail bank procurement directors, kiosk fleet operations managers, biometric technology vendors, and enclosure manufacturing heads anchored the qualitative base. Primary fieldwork combined with secondary validation against RBI circulars, EU GDPR implementation guidance, FCC equipment authorization databases, and steel commodity pricing indices. Bottom-up deployment modeling across Indian states and Indonesian provinces triangulated against top-down market sizing from hardware shipment tracking.
Scenario-bracketing around RBI financial inclusion mandate enforcement intensity and EU AI Act biometric compliance timelines framed the analytical approach. Segmentation modeling spanned product type, authentication technology, end-user institution tier, and installation environment across the projection horizon. CAGRs derived from hardware refresh cycle analysis and software subscription transition rates, with cash recycling adoption curves and biometric upgrade penetration as industry-specific forecast inputs.
Practitioners should monitor steel commodity volatility, central bank mandate acceleration, and biometric regulatory enforcement for early signals of forecast deviation. Forecasts reflect assumptions around hardware-to-software value migration and rural deployment economics. Material shifts in GDPR biometric liability interpretation or RBI tender pricing model adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Armenia Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Payment Bank Solutions Market
Banking
Investment Banking Market
Banking
E-Banking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Open Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Singapore Neobanking Market
Banking
Cardless ATM Market
Banking
Voice Banking Market
Banking
Latin America Neo Banking Services Market
Banking
Biometric Banking Wristband Market
Banking
Global Banking Systems Software Market
Banking
Automated Teller Machine (ATM) Market