
 Banking CRM Software Market | 2026-2036
Banking CRM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Banking CRM Software Market Analysis
Data engineering talent scarcity is rotating vendor priorities toward low-code deployment models that reduce implementation friction. Salesforce Financial Services Cloud leverages pre-built wealth management templates to sustain dominance in private banking verticals. Microsoft Dynamics 365 anchors enterprise share through native integration with Azure data lakes and Office productivity suites. nCino competes by embedding CRM workflows directly into commercial loan origination pipelines, reducing context-switching for relationship managers.
Banking CRM software comprises customer relationship management platforms architected specifically for financial institutions, typically integrating core banking APIs, compliance audit trails, and real-time transaction enrichment to unify client profiles across channels. These systems process structured and unstructured data feeds to enable next-best-action recommendations, regulatory reporting, and lifetime value scoring within single-tenant, multi-tenant, or hybrid infrastructure configurations. Cloud-based deployment leads absolute revenue contribution as banks retire legacy Siebel and on-premise Oracle instances, while SaaS models capture the fastest expansion by eliminating capital expenditure approval cycles. Customer analytics represents the highest-margin segment within service types, since predictive models for churn and propensity require continuous data science investment that vendors monetize through usage-tier pricing.
The US Federal Reserve's operational resilience guidelines and the SEC's cybersecurity disclosure rules are tightening data governance requirements, forcing banks to prioritize CRM vendors with SOC 2 Type II and FedRAMP certifications. GDPR and the EU AI Act impose algorithmic transparency obligations on automated credit decisioning tools, reshaping how European banks deploy lead management scoring models. Stakeholders must weigh interoperability against regulatory fragmentation when selecting platforms that span multiple jurisdictions.
Market Dynamics
Cloud migration mandates from the EU AI Act and GDPR compliance requirements are accelerating replacement cycles among European lenders, while data engineering talent scarcity rotates vendor priorities toward low-code deployment models.
Growth Catalysts
- GDPR Algorithmic Transparency:European banks must retrofit automated credit decisioning tools with explainable AI layers, creating replacement demand for compliant CRM architectures.
- Deposit Retention Analytics:Retail banks are expanding adoption of customer analytics modules to sharpen cross-selling precision and reduce churn in competitive deposit markets.
- Unified Data-Layer Consolidation:Tier-one banks in the United States are consolidating fragmented vendor relationships around single-platform customer data infrastructures.
Market Restraints
- FedRAMP Certification Barriers:The US Federal Reserve's operational resilience guidelines restrict cloud vendor selection to providers with completed SOC 2 Type II and FedRAMP authorizations, lengthening procurement cycles.
- Core Banking Integration Complexity:Legacy mainframe APIs require expensive middleware development, inflating implementation costs for institutions with heterogeneous technology estates.
- Data Residency Fragmentation:Divergent national data localization laws across Germany, France, and Singapore force multi-tenant architecture compromises that degrade platform economics.
Strategic Opportunities
- Private Banking White Space:Wealth management segments remain underpenetrated by unified CRM platforms, with relationship managers still relying on spreadsheet-based client tracking in secondary markets.
- Real-Time Transaction Enrichment:Convergence of streaming data pipelines with natural language processing enables next-best-action recommendations triggered by live payment events.
- EU AI Act Compliance Services:Algorithmic audit documentation and bias testing tools represent adjacent revenue streams for vendors with established regulatory technology capabilities.
Industry Challenges
- Data Science Talent Scarcity:Predictive model development for churn and propensity scoring requires continuous investment in scarce machine learning engineering capacity.
- Legacy Siebel Migration Friction:On-premise Oracle instance retirements demand parallel system operation during transition windows, doubling operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking CRM Software Market |
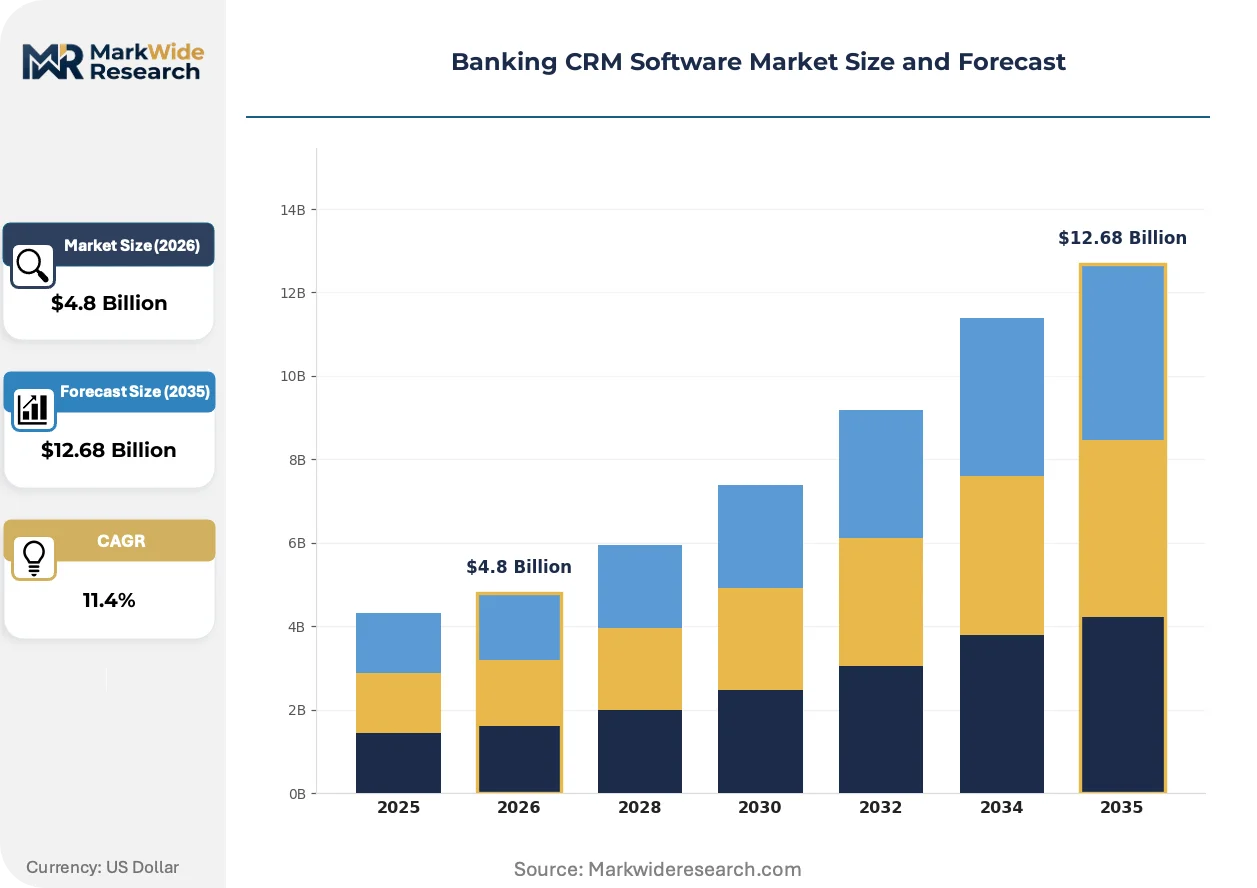
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Customer Analytics, Lead Management, Workflow Automation Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Retail Banks, Investment Banks, Credit Unions, Fintechs Functionality: Customer Support, Sales Management, Marketing Automation, Reporting |
| Companies Covered | Zoho CRM, CRMNEXT, Salesforce Financial Services Cloud, HubSpot CRM, Creatio, Microsoft Dynamics 365, Bitrix24, nCino, Maximizer CRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking CRM Software Market Emerging Trajectories
Artificial intelligence architectures are compressing decision latency in customer-facing workflows, while regulatory technology embeds compliance checks directly into operational processes.
Generative AI copilots are supplanting manual note-taking and client research tasks for relationship managers. Private banking teams at major institutions are deploying these tools to synthesize meeting preparation materials from unstructured document repositories. The technology is compressing administrative overhead and reallocating advisor capacity toward revenue-generating client interactions.
EU AI Act algorithmic transparency mandates are forcing banks to maintain audit trails for automated credit scoring models. Lenders must document training data provenance and decision logic for regulatory examination. European institutions are responding by segregating high-risk AI applications into isolated infrastructure with enhanced governance controls.
Usage-tier pricing models are displacing perpetual license structures for customer analytics modules. Tier-two banks are adopting consumption-based contracts that scale with query volume and model training frequency. This shift is most visible in the United States, where capital expenditure approval cycles have elongated and finance teams prioritize operational expenditure treatment.
Banking CRM Software Market Segmentation
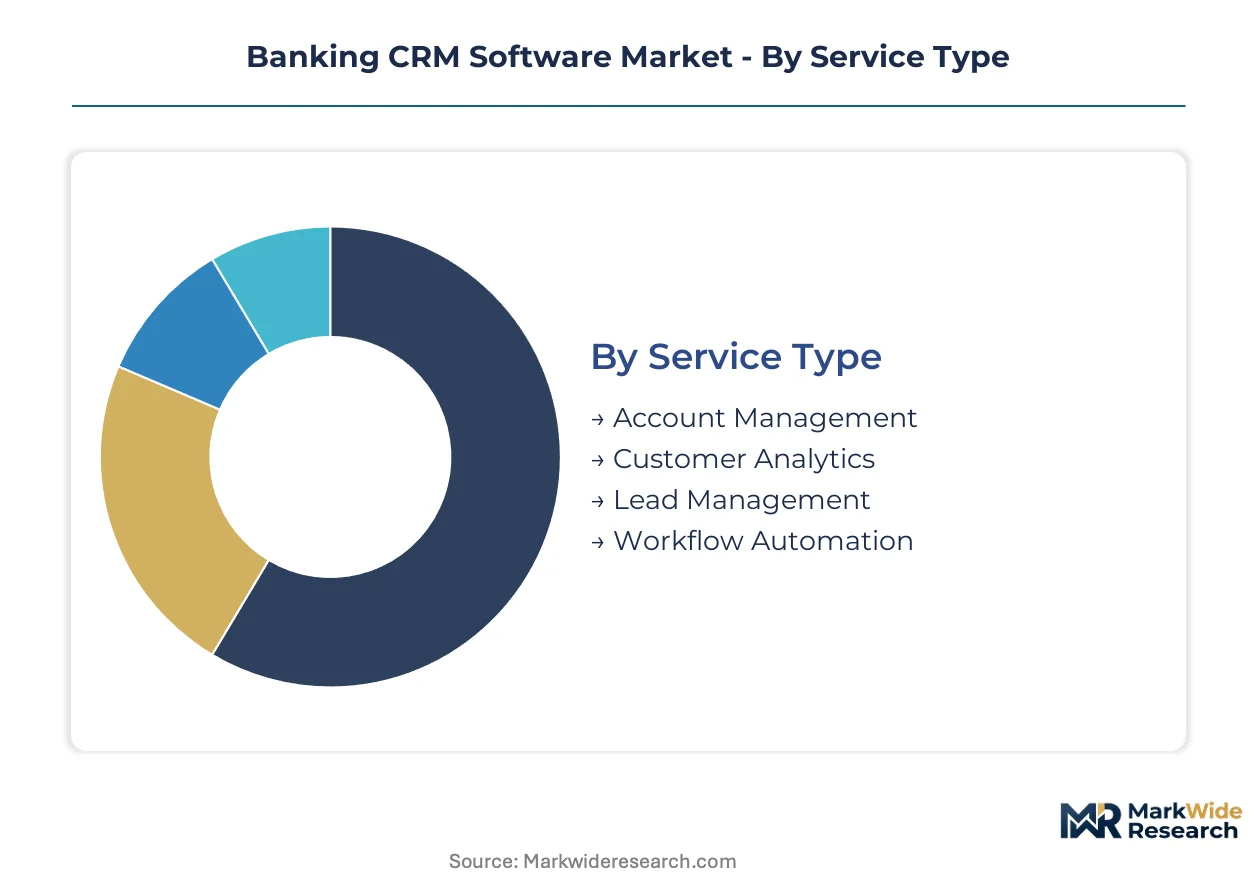
Banking CRM software segments reflect divergent infrastructure maturity across institutional tiers. Deployment preferences split sharply between legacy-dependent incumbents and cloud-native entrants. Service type concentration tracks regulatory complexity and data science investment capacity.
Service Type:
Domestic demand concentrates in compliance-heavy modules across European and North American banks, while export-led growth flows through analytics platforms serving emerging market lenders.
- Account Management:Core functionality unifying client profiles across deposit, loan, and wealth products through real-time core banking API integration. Tier-one US banks drive replacement demand as they consolidate fragmented legacy systems around unified data layers.
- Customer Analytics:Predictive modeling infrastructure for churn scoring, lifetime value calculation, and next-best-action recommendation engines. European institutions under GDPR and EU AI Act mandates retrofit explainable AI layers, accelerating module upgrades.
- Lead Management:Pipeline tracking and opportunity scoring for commercial and retail origination teams.
- Workflow Automation:Rule-based task routing and approval orchestration reducing manual processing overhead.
Account Management commands the established base. The steepest expansion runs through Customer Analytics.
Deployment:
Cost tier stratification separates capital-constrained institutions seeking operational expenditure treatment from compliance-bound entities requiring controlled infrastructure.
- Cloud-Based:Multi-tenant or dedicated instance hosting eliminating on-premise hardware maintenance and enabling elastic scaling. US tier-one banks dominate absolute revenue as they retire Siebel and Oracle legacy estates.
- SaaS:Subscription licensing with usage-tier pricing tied to query volume, user seats, or API call frequency. Tier-two US banks and European mid-market lenders adopt fastest to bypass elongated capex approval cycles.
- Hybrid:Segregated architecture placing sensitive customer data on-premise while leveraging cloud compute for analytics workloads.
- On-Premise:Single-tenant installations maintained within institutional data centers for maximum control.
Cloud-Based deployments anchor current revenue. SaaS licensing is gaining share fastest among capital-constrained institutions.
End User:
Application intensity varies by balance sheet complexity and regulatory scrutiny depth across institutional categories.
- Retail Banks:Branch network coordination and mass-market customer lifecycle management at scale. Deposit retention analytics investment concentrates in the United States where competitive pressure on funding costs intensifies.
- Investment Banks:Relationship-driven deal execution and institutional client coverage workflows. European and US bulge-bracket firms drive demand for generative AI copilots compressing administrative overhead.
- Credit Unions:Member-focused service models with constrained IT budgets favoring low-code deployment options.
- Fintechs:Greenfield implementations leveraging native cloud architecture without legacy migration burden.
Retail Banks represent the deepest installed base. Fintechs are climbing the fastest as digital-native entrants scale customer acquisition.
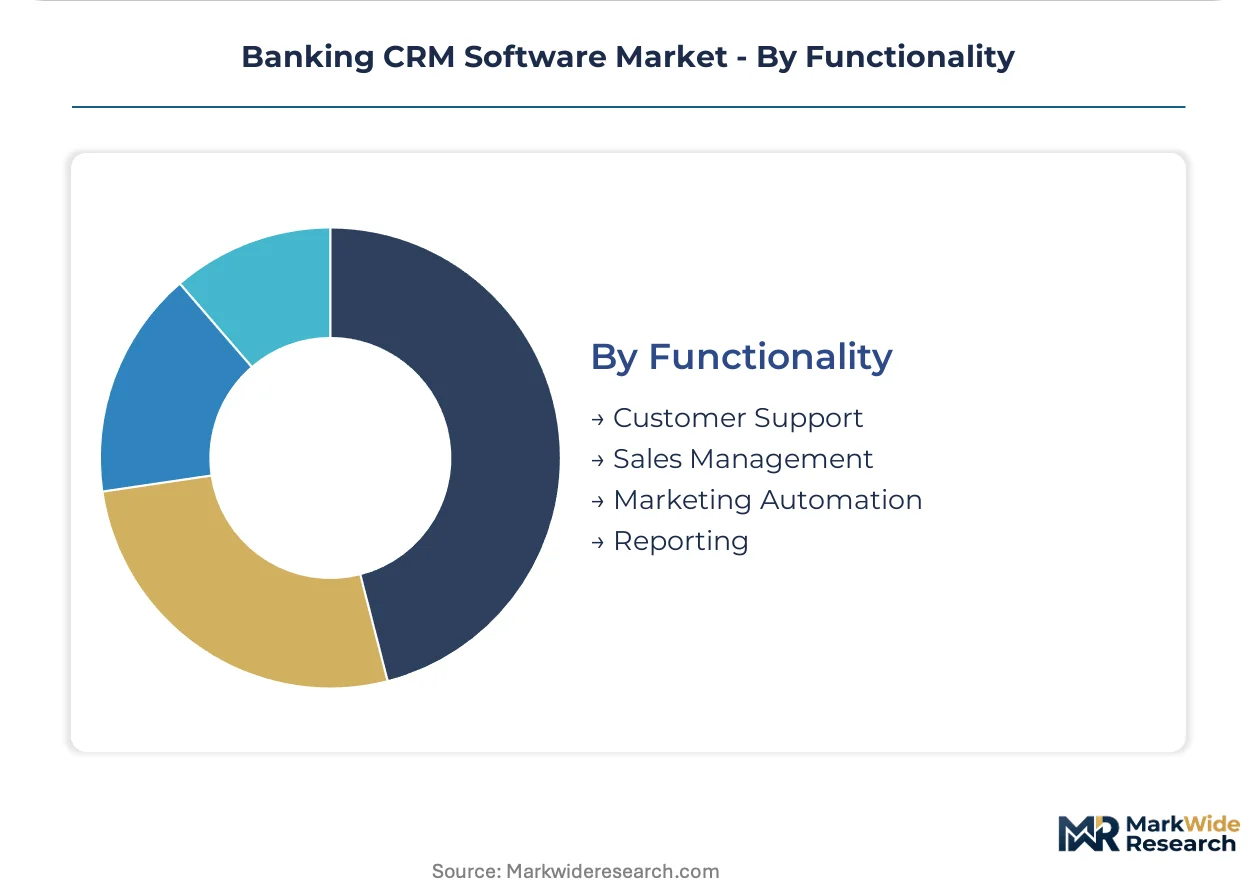
Functionality:
Customer type priorities split between revenue-generation tools and regulatory compliance infrastructure.
- Sales Management:Opportunity tracking, forecasting, and relationship manager performance analytics. Private banking verticals in Switzerland and Singapore drive premium module adoption for wealth advisor productivity.
- Marketing Automation:Campaign orchestration, segmentation, and personalized communication delivery. US retail banks expand deployment to sharpen cross-selling precision in competitive deposit markets.
- Customer Support:Case management, inquiry routing, and service level agreement tracking.
- Reporting:Regulatory submission preparation, audit trail generation, and management dashboard compilation.
Sales Management holds the largest footprint. Marketing Automation is expanding most quickly as banks prioritize revenue generation over cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States institutions prioritize unified data-layer consolidation for tier-one banks, while European lenders emphasize algorithmic transparency mandates. Asian markets diverge toward greenfield cloud-native implementations without legacy migration burdens.
United States
Tier-one banks drive vendor consolidation around single-platform customer data infrastructures. The SEC's cybersecurity disclosure rules and Federal Reserve operational resilience guidelines tighten data governance requirements. New York and San Francisco financial centers anchor demand for FedRAMP-certified cloud deployments.
Germany
GDPR compliance and EU AI Act algorithmic transparency obligations accelerate replacement cycles for automated credit decisioning tools. The KBA maintains strict oversight of cloud outsourcing arrangements for systemically important lenders. Frankfurt's banking cluster leads retrofit investments in explainable AI layers for CRM architectures.
United Kingdom
Post-Brexit regulatory divergence creates procurement complexity for institutions spanning EU and UK jurisdictions. The Financial Conduct Authority's operational resilience requirements mandate enhanced audit trail capabilities. London's fintech corridor attracts greenfield CRM implementations from digital-native entrants.
Singapore
Wealth management segments remain underpenetrated by unified platforms, with relationship managers relying on spreadsheet-based tracking. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria. Marina Bay financial district concentrates private banking CRM upgrade demand.
India
RBI guidelines on information technology governance drive formalization of customer data management practices among mid-market lenders. The PLI scheme for IT hardware indirectly supports cloud infrastructure expansion. Mumbai and Bengaluru technology corridors concentrate domestic fintech CRM adoption.
Banking CRM Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Banking CRM Software Market. Cloud hyperscalers and vertical-focused vendors compete through divergent integration strategies. Three archetypes dominate: platform-native suites with productivity suite anchoring, banking-specialized workflows embedded in lending pipelines, and modular low-code configurators. Consolidation concentrates around API interoperability capabilities and regulatory certification depth.
Within the platform-native tier, Salesforce Financial Services Cloud and Microsoft Dynamics 365 occupy positions shaped by ecosystem integration breadth. nCino represents the vertical-embedded archetype, with company nomenclature signaling specialized financial services orientation. Zoho CRM and HubSpot CRM exemplify the modular low-code segment, with naming conventions indicating broad horizontal origins adapted for banking use cases.
| Leading Market Players |
|---|
| Zoho CRM |
| CRMNEXT |
| Salesforce Financial Services Cloud |
| HubSpot CRM |
| Creatio |
| Microsoft Dynamics 365 |
| Bitrix24 |
| nCino |
| Maximizer CRM |
| Others |
Supply Flow & Price Mechanics
Usage-tier pricing contracts lock in multi-year revenue visibility for vendors while allowing tier-two US banks and European mid-market lenders to bypass elongated capital expenditure approval cycles. This structure concentrates pricing power with established platform providers holding FedRAMP and SOC 2 Type II certifications, as compliance-bound institutions face switching costs that entrench incumbent relationships.
Pricing Analysis
Long-term subscription contracts with annual escalation clauses dominate enterprise deployments, while consumption-based SaaS tiers capture fastest expansion among capital-constrained institutions. Price differentiation hinges on certification depth—FedRAMP authorization commands premium positioning—and integration complexity with legacy core banking systems. Pricing pressure stems from low-code deployment alternatives reducing implementation friction for mid-market buyers. Tier-one banks exhibit lowest price sensitivity given regulatory compliance imperatives, while credit unions and regional lenders prioritize operational expenditure treatment.
Supply Chain Analysis
Cloud infrastructure concentration in the United States, Ireland, and Singapore underwrites service delivery economics for banking CRM platforms. Vendor technology stacks draw from hyperscaler compute resources, specialized data engineering talent pools, and regulatory technology audit tooling. Single-source vulnerability runs through concentrated hyperscaler relationships, where regional data residency mandates fragment architecture economics. Distribution runs through direct enterprise sales teams for tier-one accounts and channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking CRM software sits in early-cycle expansion as cloud migration mandates from the EU AI Act and GDPR compliance requirements accelerate replacement demand among European lenders. Penetration headroom remains substantial in private banking verticals still reliant on spreadsheet-based client tracking.
For Market Incumbents: Secure FedRAMP and EU AI Act compliance certification depth as defensive moats against emerging low-code challengers. Anchor tier-one relationships through native Azure data lake and Office productivity suite integration, while embedding CRM workflows deeper into commercial loan origination pipelines to raise switching costs. For New Entrants and Emerging Players: SOC 2 Type II fast-track programs unlock procurement access to US regional banks constrained by Federal Reserve operational resilience guidelines. Target wealth management segments in Singapore and Switzerland where unified platform penetration lags. Lead with generative AI copilot differentiation compressing administrative overhead for relationship managers. For Investors and Strategic Acquirers: Vertical-embedded workflow specialists with deep lending pipeline integration represent priority acquisition archetypes as platform consolidation intensifies. Long-term viability favors vendors bridging regulatory technology capabilities with real-time transaction enrichment infrastructure. Monitor FedRAMP authorization completion rates as inflection signal for cloud vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic transparency documentation unlocks European tier-one bank procurement pipelines. |
| Real-Time Transaction Enrichment Integration | Streaming data pipeline convergence enables next-best-action recommendations triggered by live payment events. |
| Generative AI Copilot Deployment | Administrative task automation reallocates advisor capacity toward revenue-generating client interactions. |
| Core Banking API Expansion | Native integration with legacy mainframe systems reduces middleware development overhead for heterogeneous estates. |
| Private Banking Vertical Penetration | Wealth management segments in Singapore and Switzerland remain underpenetrated by unified platforms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bank CTOs, IT procurement officers, platform engineers, and regulatory technology specialists. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, Federal Reserve operational resilience guidelines, and hyperscaler capex disclosures. Bottom-up deployment model adoption curves were triangulated against top-down market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, institutional tier, service type intensity, and regional regulatory cluster. CAGRs were derived from fitted adoption curves incorporating cloud migration velocity, legacy system replacement cycles, and compliance-driven procurement patterns. Industry-specific inputs included FedRAMP authorization timelines, GDPR algorithmic transparency implementation costs, and data engineering talent scarcity indices.
Decision-makers should treat outputs as directional under sustained regulatory enforcement intensity and hyperscaler infrastructure expansion assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act implementation timelines and US Federal Reserve cybersecurity rulemakings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
UK Retail Banking Market
Banking
China Data Analytics in Banking Market
Banking
Retail Banking Market
Banking
Letter of Credit Confirmation Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
AI and Automation in Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Brazil Retail Banking Market
Banking
UK Banking as a Service Market
Banking
Smart ATM Market
Banking
Predictive Analytics in Banking Market
Banking
US Banking-As-A-Service Market
Banking
US Investment Banking Market
Banking
Machine Learning in Banking Market
Banking
North America Bank Kiosk Market
Banking
Asia-Pacific Challenger Banks Market