
 Africa Data Analytics in Banking Market | 2026-2036
Africa Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Data Analytics in Banking Market Analytics
Platform licensing revenue from core banking analytics is narrowing relative to modular cloud deployments across African financial institutions. IBM Corporation leverages its Watson analytics stack to anchor enterprise risk management contracts with tier-one banks in Johannesburg and Lagos. SAP SE competes through S/4HANA embedded analytics, sustaining long-term maintenance relationships across East African banking groups. Oracle Corporation dominates data warehouse modernization, extending Exadata footprints into Nigerian and Kenyan clearing systems.
Africa data analytics in banking encompasses the computational extraction, statistical modeling, and predictive interpretation of structured and unstructured financial data to optimize credit decisions, detect anomalous transactions, and personalize customer engagement across heterogeneous payment infrastructures. The discipline relies on real-time stream processing architectures, federated learning protocols for cross-border compliance, and API-first data mesh designs that accommodate low-latency mobile money integration. Fraud detection applications lead current deployment value, absorbing the largest share of annual bank technology budgets as real-time transaction volumes multiply across USSD and mobile wallet channels. Machine learning technology represents the fastest-expanding capability layer, displacing rules-based scoring in retail lending and treasury forecasting as GPU cloud instances become cost-accessible in Nairobi, Cape Town, and Lagos data centers.
South Africa's Financial Sector Conduct Authority enforces cloud resilience and data localization standards that shape vendor selection criteria for domestic banks. Kenya's Central Bank and Nigeria's central bank impose tiered cybersecurity frameworks and consumer data protection rules that dictate analytics architecture investments. The Central Bank of Kenya's national payment system directives further constrain cross-border data flows, forcing foreign platform providers to establish local compute presence. Stakeholders must monitor regulatory divergence between Anglophone and Francophone banking jurisdictions, as harmonized data governance remains unresolved across the African Continental Free Trade Area implementation timeline.
Market Dynamics
Cloud migration mandates from South Africa's Financial Sector Conduct Authority and Kenya's Central Bank are compressing deployment timelines for legacy infrastructure, forcing tier-one banks to accelerate modular analytics procurement while tier-two institutions face stranded asset risk.
Growth Catalysts
- Mobile banking penetration:Nigeria, Kenya, and South Africa generate the richest transaction data environments, creating natural training grounds for predictive models.
- Kenya's Central Bank directives:National payment system rules constrain cross-border data flows, compelling foreign platform providers to establish local compute presence and expand domestic hiring.
- Federated learning protocols:Cross-border compliance architectures enable banks to train models on distributed datasets without centralizing sensitive customer records.
Market Restraints
- GPU cloud cost volatility:Nairobi, Cape Town, and Lagos data centers face intermittent supply constraints that spike computational pricing for machine learning workloads.
- Data localization requirements:South Africa's Financial Sector Conduct Authority and Nigeria's central bank impose conflicting sovereignty rules that fragment analytics infrastructure investments.
- Rules-based scoring legacy:Retail lending divisions at established banks maintain embedded spreadsheet workflows that resist API-first integration.
Strategic Opportunities
- Francophone banking jurisdictions:The African Continental Free Trade Area implementation timeline creates first-mover advantage for analytics vendors establishing presence in Côte d'Ivoire and Senegal ahead of harmonized data governance.
- USSD channel analytics:Real-time stream processing architectures for feature-phone transaction networks remain underdeveloped relative to smartphone wallet infrastructure.
- Embedded analytics convergence:SAP SE's S/4HANA maintenance relationships across East African banking groups create pathways for treasury forecasting module expansion.
Industry Challenges
- API-first data mesh expertise:Banks struggle to recruit architects capable of designing low-latency mobile money integration across heterogeneous payment infrastructures.
- Exadata footprint migration:Nigerian and Kenyan clearing systems face multi-year reconfiguration timelines as Oracle Corporation extends modernization contracts.
- Cross-border compliance certification:Federated learning deployments require simultaneous approval from multiple central banks, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Data Analytics in Banking Market |
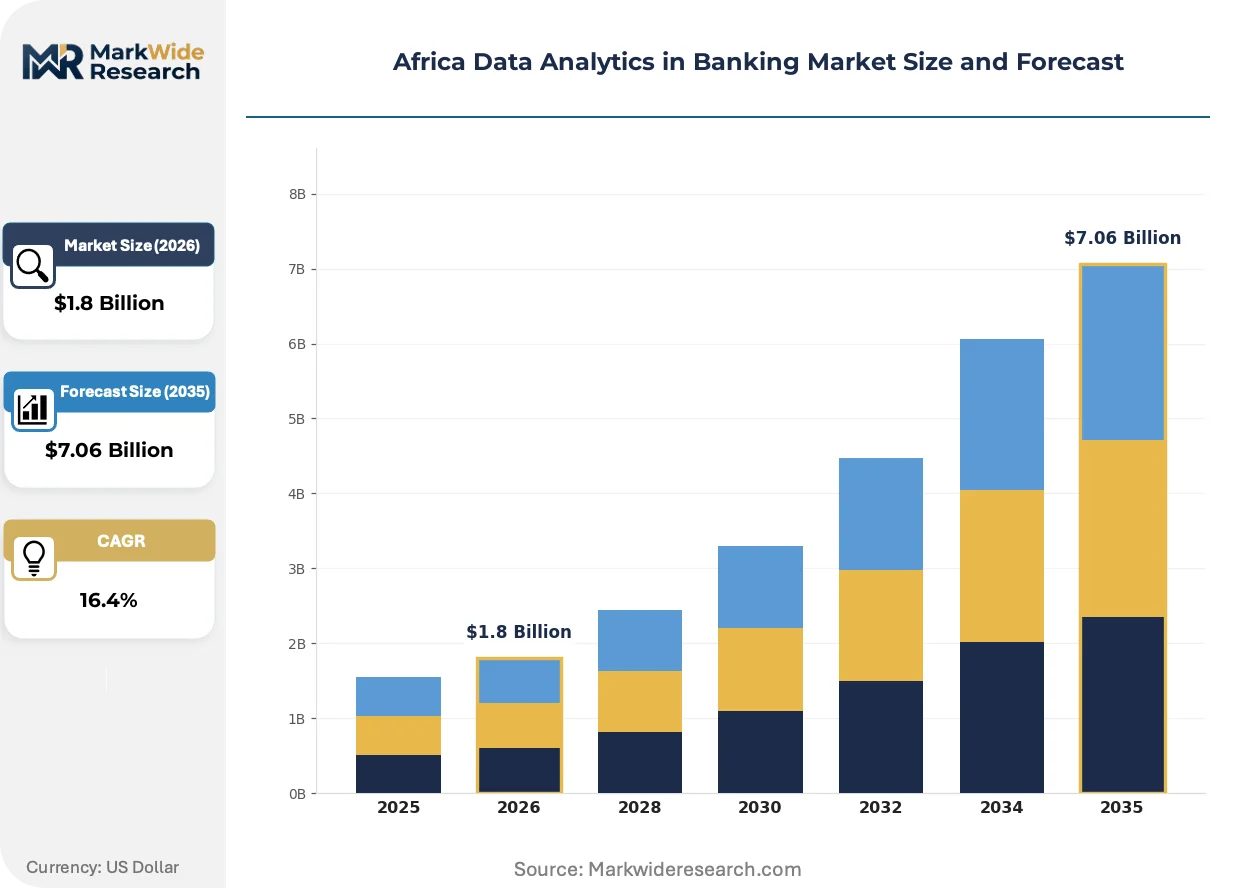
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Risk Management, Fraud Detection, Customer Segmentation, Performance Analysis Technology: Machine Learning, Big Data, Business Intelligence, Cloud Computing End User: Commercial Banks, Investment Banks, Credit Unions, Microfinance Institutions Service Type: Consulting Services, Data Insights, Training Services, Custom Solutions |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, SAS Institute, Alteryx Inc., Aspire Systems Inc., Safaricom, Standard Bank Group, FirstRand, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Data Analytics in Banking Market Evolving Landscape
Machine learning capabilities are displacing rules-based scoring across retail lending and treasury forecasting as computational infrastructure becomes cost-accessible, while regulatory fragmentation forces architectural decisions that prioritize adaptability over optimization.
Real-time stream processing architectures are collapsing the latency window between transaction occurrence and anomaly detection. Tier-one banks in Johannesburg and Lagos deploy GPU-accelerated inference engines that score mobile wallet transfers within milliseconds. This compression enables proactive fraud interruption rather than post-hoc investigation, shifting budget allocation from compliance staffing toward compute infrastructure.
South Africa's Financial Sector Conduct Authority enforces cloud resilience standards that dictate vendor selection criteria for domestic banks. The framework mandates redundant data center presence within national borders, disqualifying pure hyperscaler solutions that lack local footprint. Tier-two institutions respond by negotiating hybrid contracts that combine on-premises hardware with edge-computing nodes.
After-sales service unbundling is fragmenting traditional platform licensing arrangements. Banks now procure core analytics engines separately from implementation support, creating openings for regional systems integrators in Nairobi and Lagos. This pattern concentrates most visibly among mid-tier Nigerian institutions seeking to reduce dependence on multinational vendor maintenance contracts.
Africa Data Analytics in Banking Market Segmentation
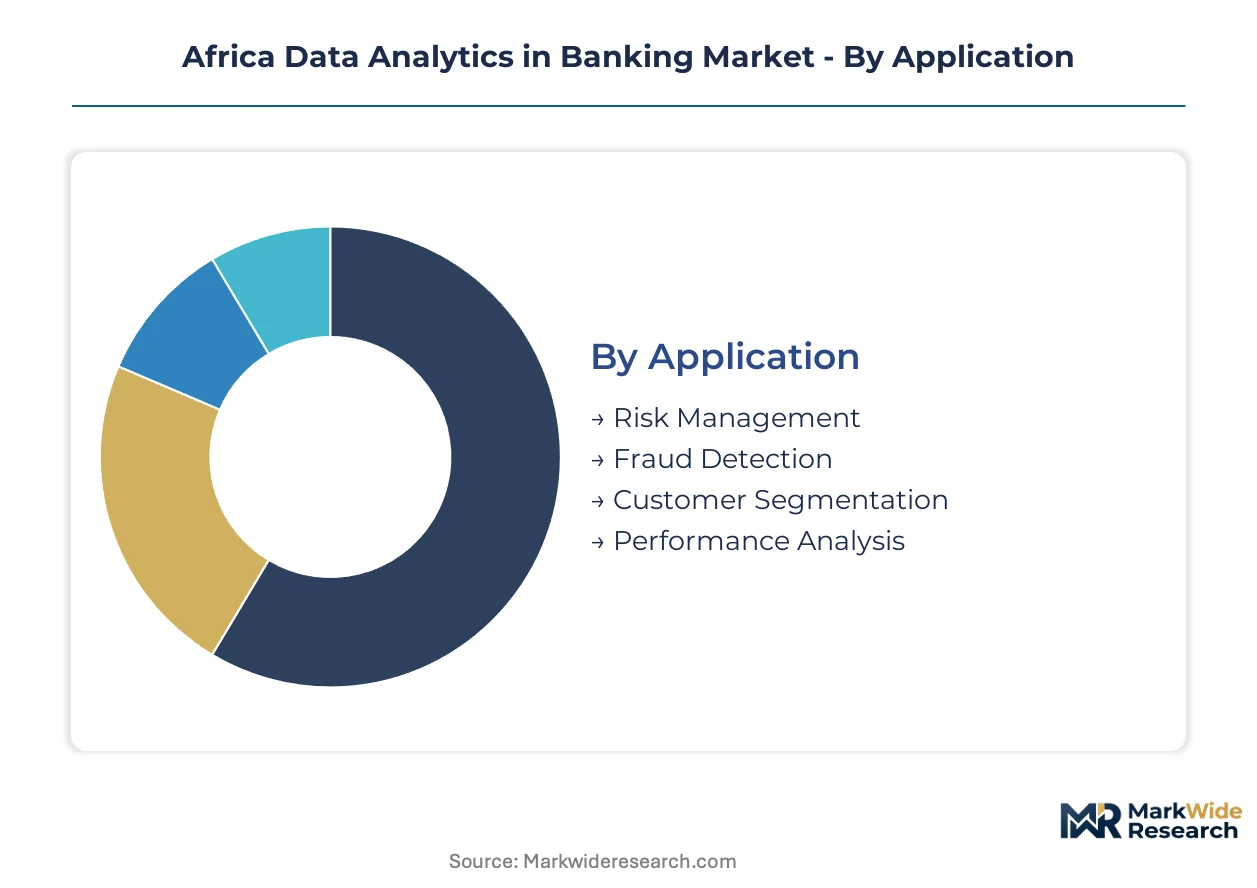
Banking analytics procurement in Africa fragments across four operational dimensions, each commanding distinct vendor relationships and deployment timelines. Understanding these segment boundaries clarifies where platform licensing yields to modular cloud contracts and which service layers absorb the bulk of technology budgets.
Application:
After-sales service intensity varies sharply across use cases, with fraud detection deployments demanding continuous model retraining support while performance analysis contracts trend toward self-service licensing.
- Fraud Detection:Real-time anomaly scoring across USSD and mobile wallet channels consumes the largest share of annual bank technology budgets. Nigerian and South African tier-one banks prioritize sub-millisecond inference latency, driving GPU-accelerated infrastructure procurement in Lagos and Johannesburg data centers.
- Risk Management:Enterprise credit scoring platforms anchor Watson analytics deployments at major Johannesburg and Lagos institutions. Regulatory pressure from South Africa's Financial Sector Conduct Authority accelerates cloud migration timelines for legacy risk engines.
- Customer Segmentation:Mobile banking penetration generates rich behavioral datasets for predictive targeting.
- Performance Analysis:Treasury forecasting modules within SAP S/4HANA sustain long-term maintenance relationships across East African banking groups.
By volume, Fraud Detection leads. By growth pace, Risk Management is climbing the fastest as regulatory mandates tighten.
Technology:
Cost tier stratification separates hyperscaler-dependent machine learning workloads from on-premises business intelligence deployments that dominate smaller institutions.
- Machine Learning:GPU cloud instances in Nairobi, Cape Town, and Lagos displace rules-based scoring across retail lending. Intermittent supply constraints spike computational pricing, compressing project timelines for tier-two banks.
- Cloud Computing:Kenya's Central Bank and Nigeria's central bank impose data localization requirements that fragment infrastructure investments. Foreign platform providers establish local compute presence to satisfy cross-border flow constraints.
- Big Data:Exadata footprint extensions into Nigerian and Kenyan clearing systems drive multi-year modernization contracts.
- Business Intelligence:Embedded spreadsheet workflows at established banks resist API-first integration.
By volume, Cloud Computing leads. By expansion trajectory, Machine Learning is gaining share fastest.
End User:
Customer type determines contract structure, with commercial banks demanding enterprise risk management suites while microfinance institutions procure modular fraud detection modules.
- Commercial Banks:Tier-one institutions in Nigeria, Kenya, and South Africa generate the richest transaction data environments for model training. Cloud migration mandates compress deployment timelines for legacy infrastructure.
- Microfinance Institutions:Feature-phone transaction networks create demand for USSD channel analytics that remain underdeveloped relative to smartphone wallet infrastructure.
- Investment Banks:Treasury forecasting applications concentrate in Johannesburg and Lagos.
- Credit Unions:Smaller data volumes limit predictive model accuracy, favoring rules-based scoring retention.
By volume, Commercial Banks lead. By untapped potential, Microfinance Institutions are expanding most quickly.
Service Type:
Margin concentration flows toward consulting engagements that bridge legacy system gaps, while data insights products face pricing pressure from self-service analytics platforms.
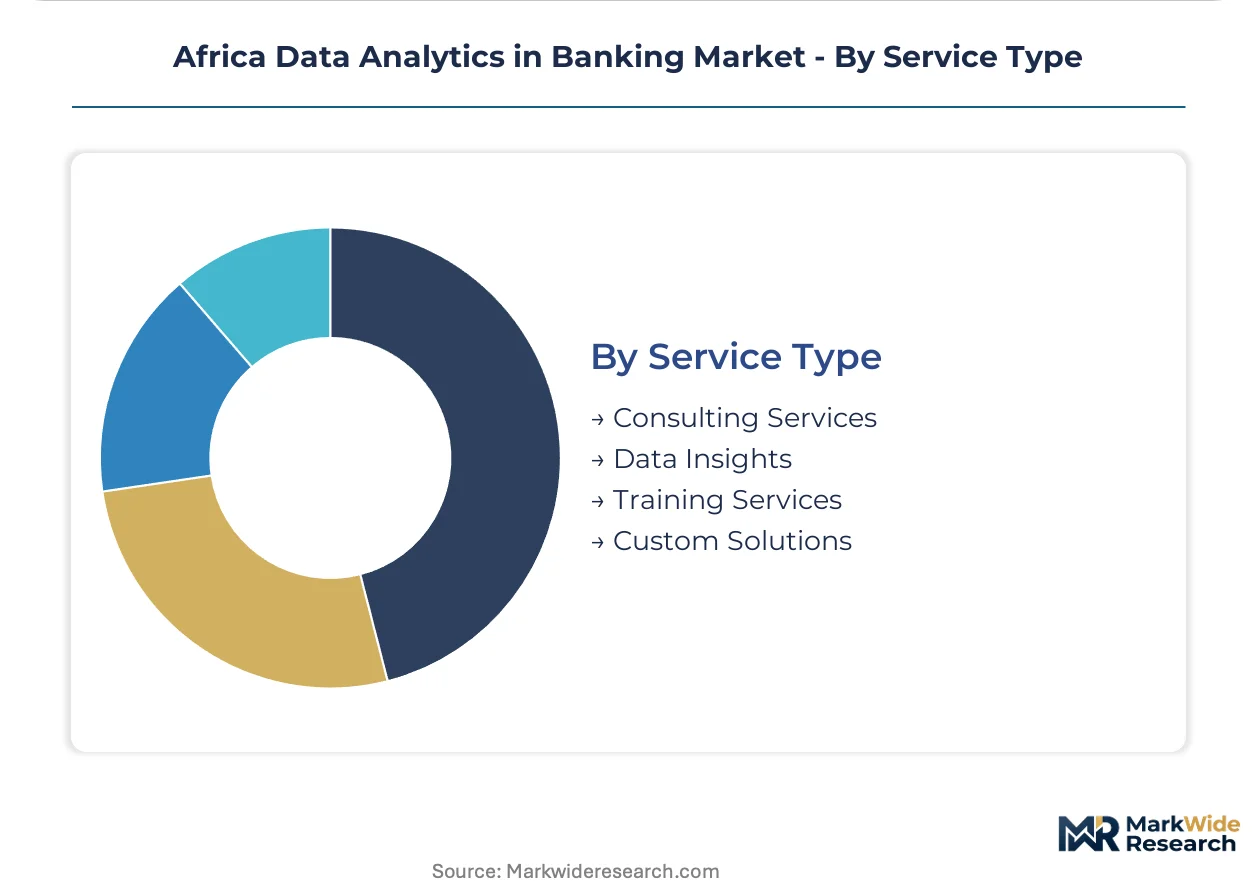
- Consulting Services:Regional systems integrators in Nairobi and Lagos capture implementation support contracts unbundled from traditional platform licensing. Mid-tier Nigerian institutions reduce dependence on multinational vendor maintenance through this pattern.
- Custom Solutions:API-first data mesh designs for low-latency mobile money integration command premium pricing. Banks struggle to recruit architects capable of spanning heterogeneous payment infrastructures.
- Data Insights:Federated learning protocols enable cross-border compliance without centralizing sensitive records.
- Training Services:Skills gaps in real-time stream processing architectures sustain demand for vendor-led capability building.
By volume, Consulting Services lead. By margin expansion, Custom Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform providers cluster compute infrastructure in Johannesburg, Lagos, and Nairobi to satisfy data localization mandates from multiple central banks. Cloud deployment timelines compress where regulatory pressure intersects with mobile banking transaction density.
South Africa
Tier-one banks in Johannesburg generate the continent's deepest transaction data pools for model training. The Financial Sector Conduct Authority enforces redundant data center presence within national borders, disqualifying pure hyperscaler solutions. Cape Town data centers host GPU-accelerated inference engines for real-time fraud scoring.
Nigeria
Commercial banks in Lagos anchor West African analytics procurement volumes, driven by mobile wallet penetration and retail credit expansion. The central bank imposes tiered cybersecurity frameworks that dictate architecture investments. Oracle Corporation extends Exadata modernization contracts into Nigerian clearing systems.
Kenya
Nairobi's status as East Africa's technology hub concentrates federated learning protocol development for cross-border compliance. The Central Bank's national payment system directives constrain cross-border data flows, compelling foreign providers to establish local compute presence. M-Pesa transaction volumes create natural training grounds for predictive models.
Côte d'Ivoire
Francophone banking groups in Abidjan present first-mover opportunities ahead of African Continental Free Trade Area harmonization. The regional central bank's data governance frameworks remain less prescriptive than Anglophone equivalents. French-speaking analytics talent pools support vendor expansion from existing West African operations.
Egypt
Cairo-based financial institutions deploy business intelligence solutions for treasury forecasting and performance analysis. The central bank's consumer data protection rules shape procurement criteria for cloud analytics platforms. Alexandria and Cairo host regional delivery centers for multinational vendors serving North African banking groups.
Africa Data Analytics in Banking Market Competitive Landscape
Enterprise software conglomerates and specialized analytics vendors split the market based on contract scale and integration depth. Tier-one banks in Johannesburg and Lagos favor comprehensive risk management suites with embedded maintenance relationships. Mid-tier institutions unbundle implementation support from platform licensing, creating openings for regional systems integrators. Consolidation pressure intensifies as cloud migration mandates compress procurement timelines.
Within the enterprise tier, IBM Corporation, SAP SE, and Oracle Corporation anchor long-term banking relationships across African financial centers. IBM leverages Watson analytics for enterprise risk management contracts. SAP sustains S/4HANA embedded analytics maintenance across East African banking groups. Oracle dominates data warehouse modernization with Exadata footprint extensions. These three exemplify the vendor archetype that bundles core platforms with multi-year service commitments.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| SAS Institute |
| Alteryx Inc. |
| Aspire Systems Inc. |
| Safaricom |
| Standard Bank Group |
| FirstRand |
| Others |
Value Network & Pricing Analysis
GPU cloud supply volatility in Nairobi, Cape Town, and Lagos data centers compresses pricing tier spreads while forcing tier-two banks toward hybrid infrastructure procurement. South Africa's Financial Sector Conduct Authority cloud resilience mandates and Kenya's Central Bank data localization rules simultaneously inflate compliance premiums and fragment supply chain configurations across the continent's three dominant banking hubs.
Pricing Analysis
South Africa's Financial Sector Conduct Authority cloud resilience mandates dictate the pricing tier structure across African banking analytics procurement. Three-tier pricing structure across premium, standard, and economy levels separates GPU-accelerated real-time inference engines from rules-based legacy scoring and self-service business intelligence modules. Price differentiation hinges on after-sales service intensity and model retraining frequency, with fraud detection deployments commanding sustained consulting premiums. Cost compression in standard-tier cloud computing subscriptions is intensifying because foreign platform providers must establish redundant local compute presence to satisfy cross-border flow constraints. Microfinance institutions exhibit highest price sensitivity due to limited transaction data volumes, while tier-one commercial banks in Johannesburg and Lagos absorb premium pricing for sub-millisecond latency guarantees.
Supply Chain Analysis
Upstream GPU and specialized AI accelerator hardware feeds from Taiwan, the United States, and China into African data center expansion. Cloud computing infrastructure draws from South African, Kenyan, and Nigerian domestic facilities, with Oracle Corporation extending Exadata footprints and IBM Corporation anchoring Watson analytics deployments. Raw material dependencies span high-bandwidth memory modules, liquid cooling systems, and redundant power generation equipment. Single-source vulnerability concentrates in NVIDIA GPU supply chains subject to intermittent allocation constraints. Distribution runs through Johannesburg, Lagos, and Nairobi technology hubs, with tier-two institutions accessing modular analytics via regional systems integrators that unbundle implementation support from multinational vendor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consulting services and custom solution development represent the fastest-expanding revenue layers, outpacing core platform licensing as African banks unbundle implementation support from traditional maintenance contracts. This service-attach dynamic creates durable recurring revenue streams for vendors capable of bridging API-first data mesh expertise gaps.
For Market Incumbents: Build switching-cost moats through embedded S/4HANA maintenance relationships and Exadata footprint extensions that resist modular displacement. Deepen vertical integration into local compute presence to satisfy Kenya's Central Bank and South Africa's Financial Sector Conduct Authority data localization mandates ahead of foreign hyperscaler competition. Defensive consolidation should prioritize acquiring regional systems integrators in Nairobi and Lagos that currently capture unbundled implementation contracts from mid-tier Nigerian institutions. For New Entrants and Emerging Players: Establish a beachhead in Francophone banking jurisdictions, specifically Côte d'Ivoire and Senegal, ahead of African Continental Free Trade Area harmonization timelines. USSD channel analytics for feature-phone transaction networks remain dramatically underpenetrated relative to smartphone wallet infrastructure, offering the most accessible white-space target. Go-to-market execution should emphasize federated learning protocol expertise that enables cross-border compliance without centralizing sensitive customer records, addressing the simultaneous approval bottleneck that extends deployment cycles for established vendors. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated platform providers with established local compute footprints. Long-term viability over the next decade hinges on capturing maintenance relationship density before cloud migration mandates fully compress procurement timelines. Acquisition target archetypes include regional systems integrators with API-first data mesh implementation capabilities and specialized fraud detection vendors with GPU-accelerated inference engine deployments. Watch central bank harmonization progress across the African Continental Free Trade Area as the critical inflection signal for cross-border scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Local Compute Presence Establishment | Satisfies Kenya's Central Bank data localization mandates while disqualifying pure hyperscaler competition. |
| Federated Learning Protocol Development | Enables cross-border model training without centralizing sensitive records across multiple central bank jurisdictions. |
| USSD Channel Analytics Expansion | Captures feature-phone transaction volumes that remain underdeveloped relative to smartphone wallet infrastructure. |
| Regional Systems Integrator Acquisition | Absorbs implementation support contracts unbundled from traditional multinational vendor maintenance relationships. |
| API-First Data Mesh Capability Building | Addresses architect recruitment gaps for low-latency mobile money integration across heterogeneous payment infrastructures. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers, enterprise risk management executives, central bank regulatory affairs specialists, and regional systems integrator principals, then refined through secondary validation. Chief information officers at tier-one Nigerian and South African banks, alongside procurement leads at mid-tier Kenyan institutions, provided deployment timeline and budget allocation perspectives. Secondary sources encompassed central bank payment system directives, financial sector conduct authority cloud resilience frameworks, customs data on GPU and server hardware imports, and SEC filings from enterprise software conglomerates with African banking exposure. Bottom-up vendor contract analysis and top-down technology spending estimates were triangulated to anchor market size calculations.
Demand-supply balance modeling across the analysis window incorporated mobile banking transaction volume trajectories, regulatory mandate implementation schedules, and data center capacity expansion disclosures from Johannesburg, Lagos, and Nairobi facilities. Segmentation dimensions spanned application type, technology layer, end-user institution category, and service type, with additional granularity around deployment model and integration complexity. CAGRs were derived from regression analysis against mobile wallet penetration curves and cloud migration mandate compliance deadlines. Industry-specific forecast inputs included M-Pesa transaction growth patterns and tier-one bank technology budget disclosures.
Sensitivities concentrate around central bank regulatory divergence, GPU supply allocation volatility, and federated learning protocol standardization delays. Forecasts embed assumptions regarding cloud resilience mandate enforcement consistency and mobile banking penetration saturation points. Cross-checking against African banking technology spending surveys and hyperscaler regional capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Investment Banking and Trading Services Market
Banking
Blockchain in Retail Banking Market
Banking
Open Banking Market
Banking
Latin America Data Analytics in Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
E-Banking Market
Banking
Commercial Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
UK Retail Banking Market
Banking
Machine Learning in Banking Market
Banking
Corporate Digital Banking Market
Banking
UK Banking as a Service Market
Banking
Letter of Credit Confirmation Market
Banking
Southeast Asia Commercial Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Corporate Banking Market