
 Retail Banking IT Spending Market | 2026-2036
Retail Banking IT Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Banking IT Spending Market Insights
Mid-tier bank consolidation across North America is repositioning procurement power toward fewer buyers with larger contract values. IBM leverages its mainframe-installed base to sustain long-term service agreements with merged entities. Oracle Corporation anchors core banking migrations through its cloud infrastructure investments, while Temenos AG competes aggressively on modular architecture for institutions shedding legacy stacks.
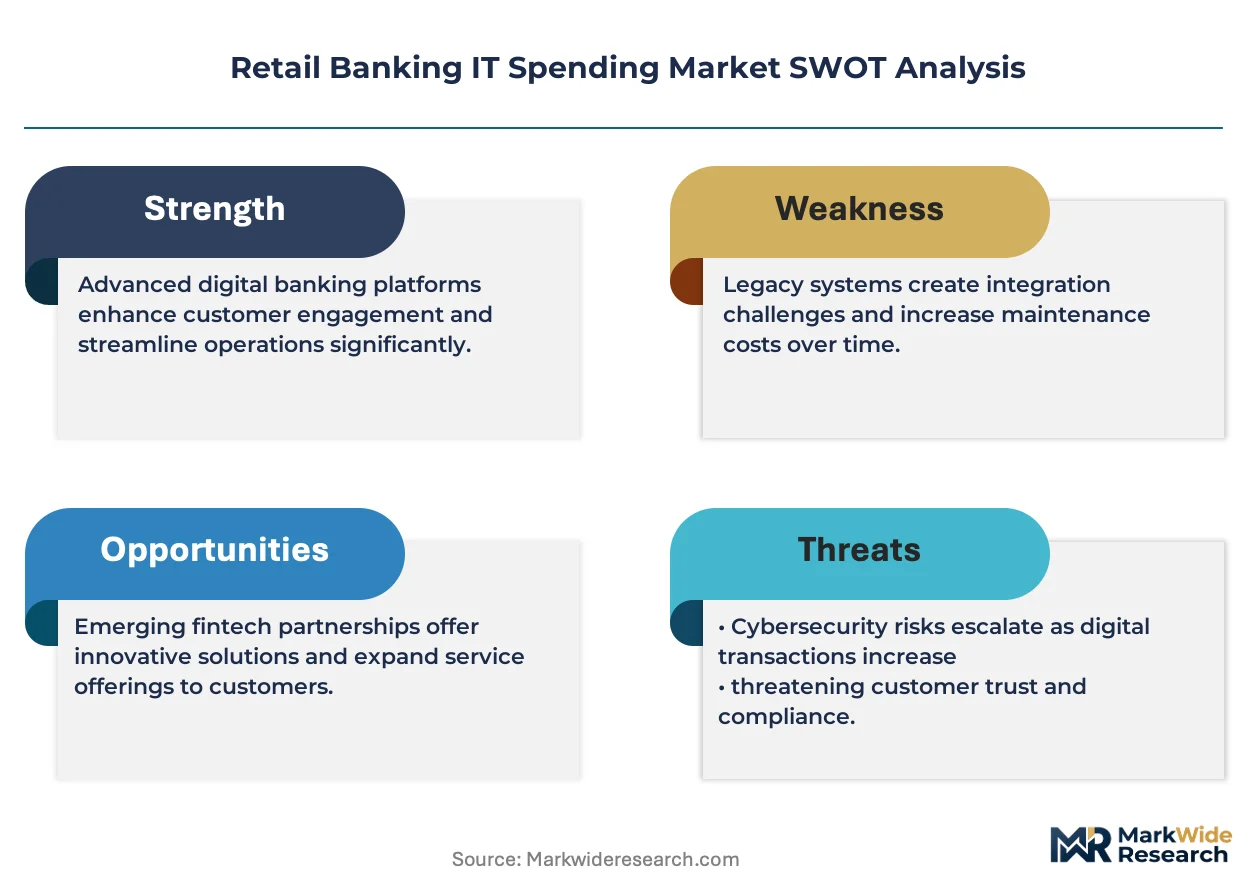
Retail Banking IT Spending encompasses technology investments by deposit-taking institutions in software, infrastructure, and services that process transactions, manage risk, and enable customer-facing digital channels. Core banking solutions typically handle real-time ledger updates across distributed databases with sub-second latency requirements for payment clearing. Fraud detection systems lead technology segment growth as real-time transaction volumes strain rule-based authentication frameworks. Hybrid cloud deployment models capture expanding margin pools as banks navigate data residency requirements while containing capital expenditure.
The European Banking Authority enforces stringent operational resilience deadlines that compel institutions to upgrade disaster recovery and third-party risk management systems. India's RBI mandates granular data localization for payment systems, redirecting infrastructure spending toward domestic cloud regions. The US Federal Reserve's FedNow instant payment network shapes demand for 24/7 liquidity management tools. Stakeholders must weigh regulatory divergence against platform standardization when allocating multi-year transformation budgets.
Market Dynamics
Real-time payment infrastructure mandates across multiple jurisdictions are forcing deposit-taking institutions to replace batch-oriented core systems with distributed ledger architectures capable of sub-second transaction processing.
Growth Catalysts
- RBI Digital-First Guidelines:India's central bank mandates cloud-native infrastructure for payment systems, redirecting capital expenditure toward domestic cloud regions and API-first middleware stacks.
- Instant Payment Networks:The US Federal Reserve's FedNow service creates demand for 24/7 liquidity management tools and real-time fraud detection systems among regional banks.
- Open Banking Mandates:European Union regulations compel incumbent institutions to expose standardized APIs, accelerating middleware upgrades and third-party integration spending.
Market Restraints
- Data Localization Requirements:India's RBI mandates granular domestic data storage for payment systems, fragmenting cloud infrastructure strategies and raising operational complexity.
- Legacy System Entrenchment:Core banking platforms running on mainframe architectures create path dependency that slows modular replacement cycles and extends payback periods.
- Skill Scarcity in Distributed Systems:Shortages of engineers proficient in real-time database management and cloud-native security constrain execution velocity for transformation programs.
Strategic Opportunities
- Hybrid Cloud Deployment Models:Banks navigating data residency requirements while containing capital expenditure are creating margin pools for vendors offering compliant multi-cloud orchestration.
- Embedded Finance Integration:Non-bank platforms in Southeast Asia require banking-as-a-service infrastructure, opening new revenue streams for core system providers.
- Operational Resilience Deadlines:The European Banking Authority's stringent disaster recovery requirements compel institutions to upgrade third-party risk management systems and business continuity platforms.
Industry Challenges
- Real-Time Fraud Detection Complexity:Rule-based authentication frameworks strain under instant payment volumes, forcing banks to rebuild risk engines without disrupting customer experience.
- Middleware Integration Friction:API exposure requirements demand seamless connectivity between legacy cores and modern digital channels, creating brittle integration points.
- Talent Competition with Technology Firms:Financial institutions face attrition of cloud engineering talent to better-capitalized technology employers, delaying transformation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Banking IT Spending Market |
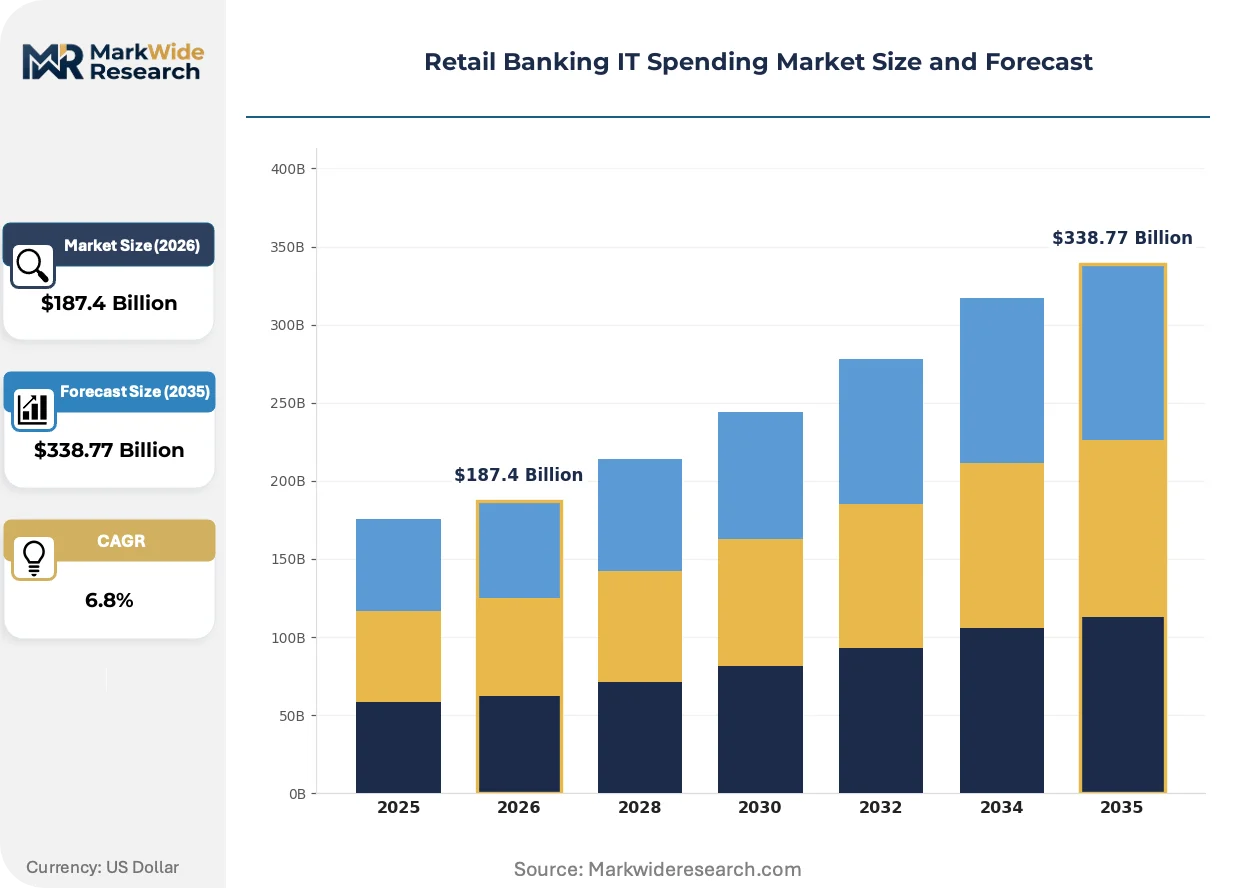
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Core Banking Solutions, Digital Payment Platforms, Fraud Detection Systems, Customer Relationship Management, Data Analytics Tools Application: Personal Loans, Mortgage Processing, Wealth Management, Credit Card Services, Deposit Management Customer Type: Individual Account Holders, Small Business Owners, High Net Worth Clients, Corporate Clients, Financial Advisors Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Software as a Service |
| Companies Covered | IBM, Microsoft, Accenture, Capgemini, Cisco Systems, Atos, CGI Inc., Oracle Corporation, Temenos AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Banking IT Spending Market Trends and Innovations
Cloud-native core banking architectures are overtaking monolithic legacy platforms as the dominant deployment paradigm, reshaping vendor competition and procurement criteria across deposit-taking institutions.
Distributed database technologies with sub-second latency capabilities are overtaking traditional relational systems for real-time ledger management. Mid-tier banks in Southeast Asia are adopting these platforms most aggressively to meet instant payment mandates. This shift is overtaking established upgrade cycles and compressing replacement timelines from decade-long horizons to three-to-five-year windows.
The European Banking Authority's operational resilience framework mandates specific recovery time objectives and third-party risk management protocols. Institutions must demonstrate independent business service continuity within strict deadlines. Banks in Germany and France are prioritizing disaster recovery automation and vendor concentration limits to achieve compliance.
Subscription-based pricing for core banking software is displacing perpetual license models among North American regional banks. Procurement teams favor operational expenditure treatment and embedded upgrade rights over capital-intensive upfront investments. This pattern is most pronounced among institutions undergoing post-merger technology consolidation.
Retail Banking IT Spending Market Segmentation
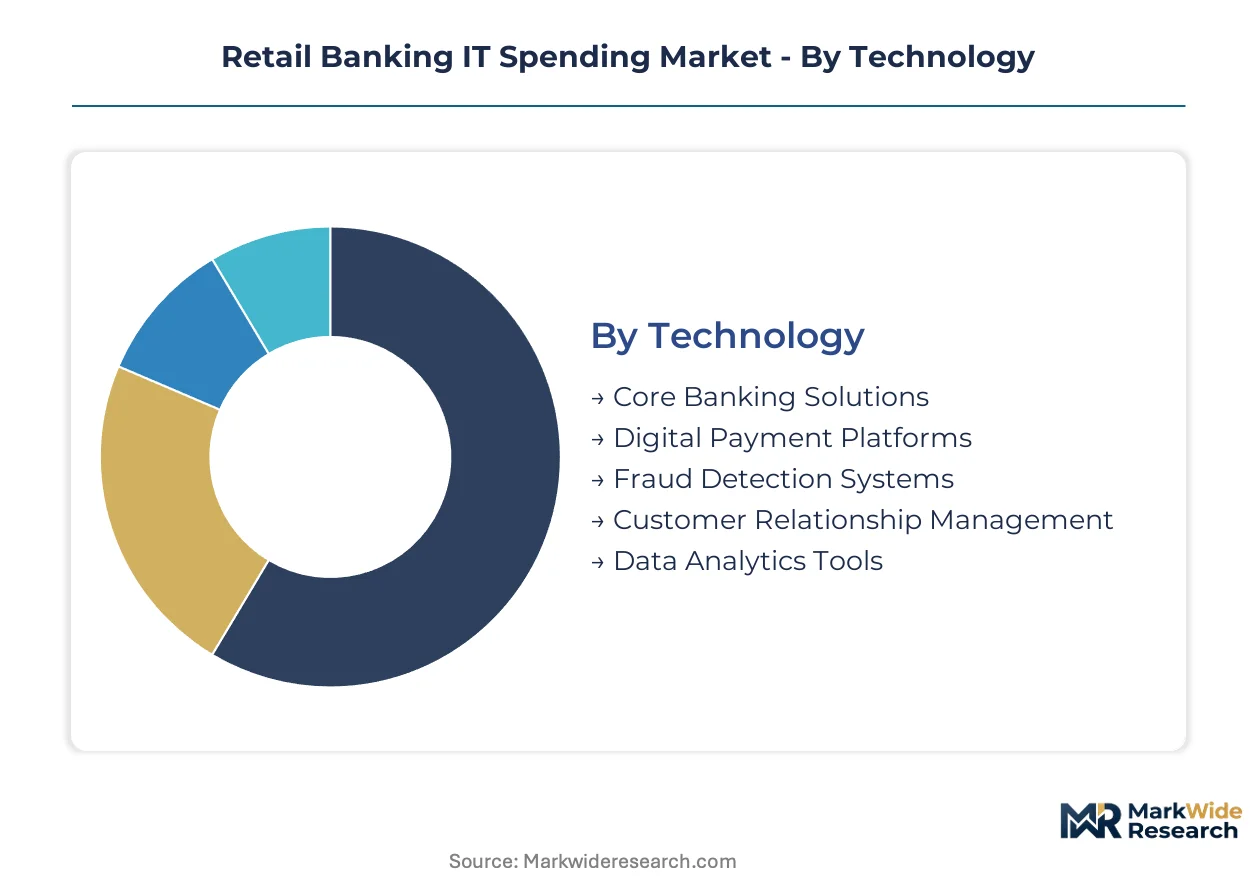
Retail banking IT spending fragments across technology stacks, customer interfaces, and infrastructure models. Procurement teams allocate budgets differently based on regulatory deadlines, legacy system age, and customer channel preferences. Understanding these segment boundaries clarifies where vendor competition intensifies and margin pools concentrate.
Technology:
Vendor capability concentrates in real-time transaction processing and risk management platforms, with infrastructure spending gravitating toward cloud-native architectures.
- Core Banking Solutions:Distributed ledger architectures handle real-time ledger updates with sub-second latency for payment clearing. Demand clusters in Southeast Asia where regional banks replace batch-oriented systems to meet instant payment mandates from monetary authorities.
- Fraud Detection Systems:Machine learning models analyze transaction patterns across digital channels to flag anomalies before settlement. North American regional banks deploy these most aggressively as FedNow volumes strain rule-based authentication frameworks.
- Digital Payment Platforms:API-first middleware stacks enable real-time fund transfers across domestic and cross-border networks.
- Customer Relationship Management:Unified data layers consolidate branch, mobile, and call center interactions into single customer views.
- Data Analytics Tools:Cloud-based warehouses aggregate transaction histories for predictive modeling and regulatory reporting.
Fraud Detection Systems absorb the bulk of installed capacity; Core Banking Solutions are expanding most quickly.
Application:
Spending intensity tracks transaction velocity and regulatory scrutiny, with high-frequency services commanding disproportionate infrastructure investment.
- Credit Card Services:Authorization engines process millions of daily transactions through neural network scoring models. Indian banks prioritize these upgrades as RBI guidelines mandate real-time fraud checks on all card-not-present transactions.
- Deposit Management:Core ledger systems track checking and savings balances across branch and digital channels with intraday reconciliation. European institutions modernize these platforms to meet EBA operational resilience deadlines for recovery time objectives.
- Personal Loans:Automated underwriting pipelines integrate credit bureau data with alternative scoring signals.
- Mortgage Processing:Document management workflows handle income verification, appraisal coordination, and regulatory disclosures.
- Wealth Management:Portfolio accounting engines calculate positions, performance, and tax implications across custody relationships.
Deposit Management captures the largest share of maintenance spending; Credit Card Services shows the steepest expansion trajectory.
Customer Type:
Segment profitability diverges sharply based on service complexity and digital engagement depth, redirecting platform development priorities.
- Individual Account Holders:Mass-market retail customers access standardized mobile and online banking through self-service channels. Indian banks target this segment with vernacular-language interfaces as RBI pushes financial inclusion through digital-first infrastructure.
- High Net Worth Clients:Affluent households receive dedicated relationship management portals with consolidated reporting across custody and lending relationships. Southeast Asian private banks invest here to differentiate against wealthtech competitors.
- Small Business Owners:Integrated cash management combines deposit accounts, payment acceptance, and working capital facilities.
- Corporate Clients:Treasury workstations manage liquidity, foreign exchange, and trade finance across multi-bank relationships.
- Financial Advisors:Practice management tools support client acquisition, portfolio construction, and compliance documentation.
Individual Account Holders generate the highest transaction volumes; High Net Worth Clients command the largest per-customer technology investment.
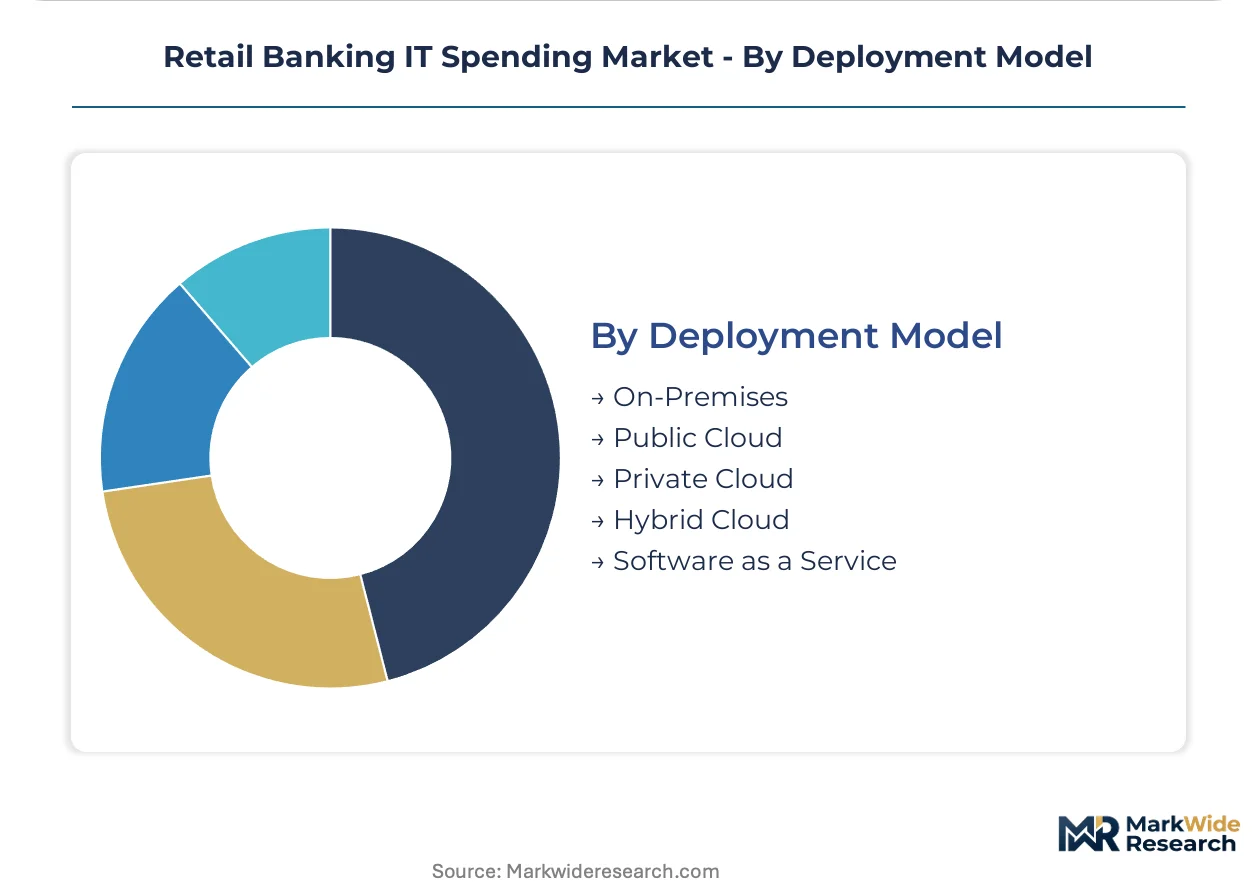
Deployment Model:
Capital expenditure treatment and data residency requirements fragment infrastructure strategies across ownership and hosting arrangements.
- Hybrid Cloud:Workload orchestration splits sensitive data processing to private infrastructure while bursting compute-intensive analytics to public regions. European banks adopt this model most aggressively to satisfy GDPR data localization while containing hardware depreciation.
- Software as a Service:Subscription pricing shifts core banking and CRM costs from capital to operational expenditure. North American mid-tier banks favor this approach during post-merger consolidation to accelerate decommissioning of redundant data centers.
- On-Premises:Self-managed data centers retain complete control over hardware, network, and security configurations.
- Public Cloud:Shared infrastructure delivers elastic compute and storage without facility ownership obligations.
- Private Cloud:Single-tenant virtualized environments replicate public cloud flexibility with dedicated resource isolation.
Hybrid Cloud dominates new procurement decisions; Software as a Service is gaining share fastest among regional banks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States institutions command the largest procurement budgets for core banking modernization, while Indian banks redirect capital expenditure toward cloud-native infrastructure under central bank mandates. Regulatory divergence across monetary authorities fragments vendor standardization strategies.
United States
FedNow instant payment adoption and regional bank consolidation drive distributed ledger procurement. The Federal Reserve shapes 24/7 liquidity management requirements. Chicago and Dallas banking clusters absorb disproportionate technology investment as merged entities rationalize redundant data centers.
India
RBI digital-first guidelines and granular data localization rules redirect infrastructure spending toward domestic cloud regions. The central bank mandates API-first middleware for payment systems. Mumbai and Bengaluru technology corridors attract vendor engineering resources for real-time core deployments.
Germany
EBA operational resilience deadlines compel disaster recovery automation investments. The European Banking Authority enforces strict recovery time objectives for critical banking services. Frankfurt's banking concentration prioritizes third-party risk management system upgrades.
United Kingdom
Open banking mandate maturity and API standardization accelerate middleware replacement cycles. The Financial Conduct Authority enforces consumer data rights through PSD2 implementation. London fintech clusters pressure incumbent institutions to expose core systems via standardized interfaces.
Singapore
Real-time payment network integration and cross-border ASEAN connectivity drive core system replacement. The Monetary Authority of Singapore mandates instant payment interoperability across member economies. The city-state's regional headquarters concentration positions vendors for Southeast Asian expansion.
Retail Banking IT Spending Market Competitive Landscape
United States technology conglomerates anchor one tier; European banking software specialists hold differentiated positions in modular core systems. Vendor competition concentrates around three strategic archetypes: mainframe-anchored service providers, cloud infrastructure platforms, and modular banking software developers. M&A activity accelerates as merged regional banks consolidate procurement toward fewer vendors with larger contract values. Technology licensing partnerships proliferate as institutions seek hybrid deployment expertise.
Within the mainframe-anchored tier, IBM leverages installed base relationships to sustain long-term service agreements. Oracle Corporation occupies a position across cloud infrastructure and core banking applications. Temenos AG exemplifies the modular architecture specialist competing for institutions shedding legacy stacks. These three anchors represent distinct competitive vectors rather than direct substitution alternatives.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Accenture |
| Capgemini |
| Cisco Systems |
| Atos |
| CGI Inc. |
| Oracle Corporation |
| Temenos AG |
| Others |
Pricing and Supply Chain Analysis
Cloud-native core banking migrations are compressing procurement timelines from decade-long cycles to three-to-five-year windows, simultaneously collapsing legacy maintenance premiums and concentrating vendor qualification around real-time performance benchmarks. This acceleration rewards suppliers with proven distributed ledger architectures while penalizing mainframe-dependent incumbents unable to demonstrate sub-second latency at competitive unit economics.
Pricing Analysis
Volume commitments separate pricing tiers, with North American regional banks commanding SaaS discounts through post-merger consolidation while Southeast Asian institutions absorb premium rates for accelerated deployment timelines. Subscription models displace perpetual licenses fastest among mid-tier banks seeking operational expenditure treatment, though data localization add-ons inflate total cost of ownership for Indian deployments under RBI mandates. Price differentiation rests on latency certification tiers and embedded disaster recovery automation. Cost compression in standard-tier core banking modules is intensifying as Temenos AG and Oracle Corporation compete for decommissioning budgets. Small business banking platforms show highest price sensitivity due to constrained IT procurement authority.
Supply Chain Analysis
Dual-sourcing requirements from merged US regional banks mandate multi-vendor qualification for critical payment infrastructure, fragmenting single-source dependencies across IBM mainframe service agreements and cloud-native alternatives. Engineering talent concentrates in India, Ireland, and Singapore, where vendor development centers cluster around monetary authority innovation hubs. Raw material dependencies span semiconductor fabrication for fraud detection accelerators, specialized database licensing for distributed ledger cores, and domestic cloud region buildouts for RBI-compliant data residency. Single-source vulnerability persists in mainframe-skilled engineering pools approaching retirement velocity. Distribution runs through systems integrators Accenture and Capgemini for complex migration programs, with direct vendor relationships dominating SaaS procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EBA operational resilience deadlines and RBI data localization mandates erect barrier-to-entry moats favoring vendors with pre-certified automation frameworks and domestic cloud infrastructure.
For Market Incumbents: Anticipate margin compression in standard-tier core banking modules as modular specialists capture replacement cycles. Defensive consolidation should prioritize API-first middleware acquisitions to bridge legacy cores with open banking exposure requirements. Vertical integration into domestic cloud regions offers pricing power against data localization mandates in India and Southeast Asia.
For New Entrants and Emerging Players: Enter via embedded finance infrastructure for Southeast Asian non-bank platforms, where banking-as-a-service demand outpaces incumbent supply capacity. White-space concentration appears in real-time fraud detection for FedNow-enabled regional banks, with API-native architectures offering the most penetrable wedge against rule-based legacy systems. Go-to-market positioning should emphasize sub-second latency certification and pre-integrated compliance automation.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by cloud infrastructure platforms seeking vertical banking expertise. Long-term viability favors vendors with hybrid deployment orchestration capabilities spanning mainframe migration and cloud-native greenfield deployment. Acquisition target archetypes include modular core specialists with proven Southeast Asian instant payment deployments. The signal to watch is FedNow transaction volume acceleration forcing regional bank procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Middleware Development | Enables EBA-mandated open banking exposure without legacy core replacement. |
| Domestic Cloud Region Expansion | Satisfies RBI data localization requirements while capturing Indian payment system procurement. |
| Real-Time Fraud Detection Acquisition | Addresses FedNow volume strain with machine learning models displacing rule-based authentication. |
| Subscription Pricing Transition | Aligns vendor revenue with North American regional bank operational expenditure preferences post-consolidation. |
| Disaster Recovery Automation Investment | Meets EBA recovery time objectives for German and French banking concentration. |
Research Methodology
Document review covered regulatory filings from the European Banking Authority, Reserve Bank of India circulars, and Federal Reserve payment system disclosures, complemented by interviews with CTOs at North American regional banks, procurement officers at Southeast Asian financial institutions, and integration specialists at major systems integrators. Secondary validation drew from SEC 10-K filings of publicly traded core banking vendors, hyperscaler capex disclosures for cloud infrastructure buildouts, and monetary authority innovation reports. Bottom-up spending estimates from individual bank technology budgets were triangulated against top-down vendor revenue attribution across deployment models.
Cross-reference between historical procurement patterns and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, customer type, application intensity, and regional regulatory cluster. CAGRs were derived from slope analysis of technology replacement cycle compression and regulatory deadline clustering. Industry-specific forecast inputs encompass FedNow adoption velocity, EBA operational resilience compliance timelines, and RBI cloud-native mandate enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement acceleration or mainframe talent pool collapse. Deviation in instant payment transaction volume growth would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
India Data Analytics in Banking Market
Banking
UK Retail Banking Market
Banking
France Data Analytics in Banking Market
Banking
Voice Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Retail Banking Market
Banking
APAC Banking-As-A-Service Market
Banking
Banking Tax Management Software Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Saudi Arabia Retail Banking Market
Banking
Global Certificate of Deposit Market
Banking
Cybersecurity in Banking Market
Banking
North America Challenger Banks Market
Banking
Latin America Neo Banking Services Market
Banking
Cloud Computing Banking Market
Banking
In Vitro Fertilization Banking Services Market