
 Open Banking Market | 2026-2036
Open Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Open Banking Market Intelligence
Retail banking's share of API traffic is rebalancing toward fintech intermediation as consumers abandon legacy portals. Plaid leverages its North American bank coverage to sustain developer ecosystem dominance. Tink anchors European account aggregation through direct bank API integrations. TrueLayer competes on payment initiation speed for e-commerce checkout flows.
Open banking denotes the practice of sharing consumer financial data between banks and authorized third parties through standardized application programming interfaces, typically RESTful APIs operating under OAuth 2.0 and FAPI security protocols. The architecture enables real-time account verification, payment initiation, and cash flow analytics without credential sharing. Account aggregation services command the deepest integration requirements and longest sales cycles, while payment initiation APIs capture the fastest transaction volume growth. Cloud-based deployment models attract mid-tier fintechs seeking elastic infrastructure, though hybrid configurations dominate among tier-one banks managing legacy core systems.
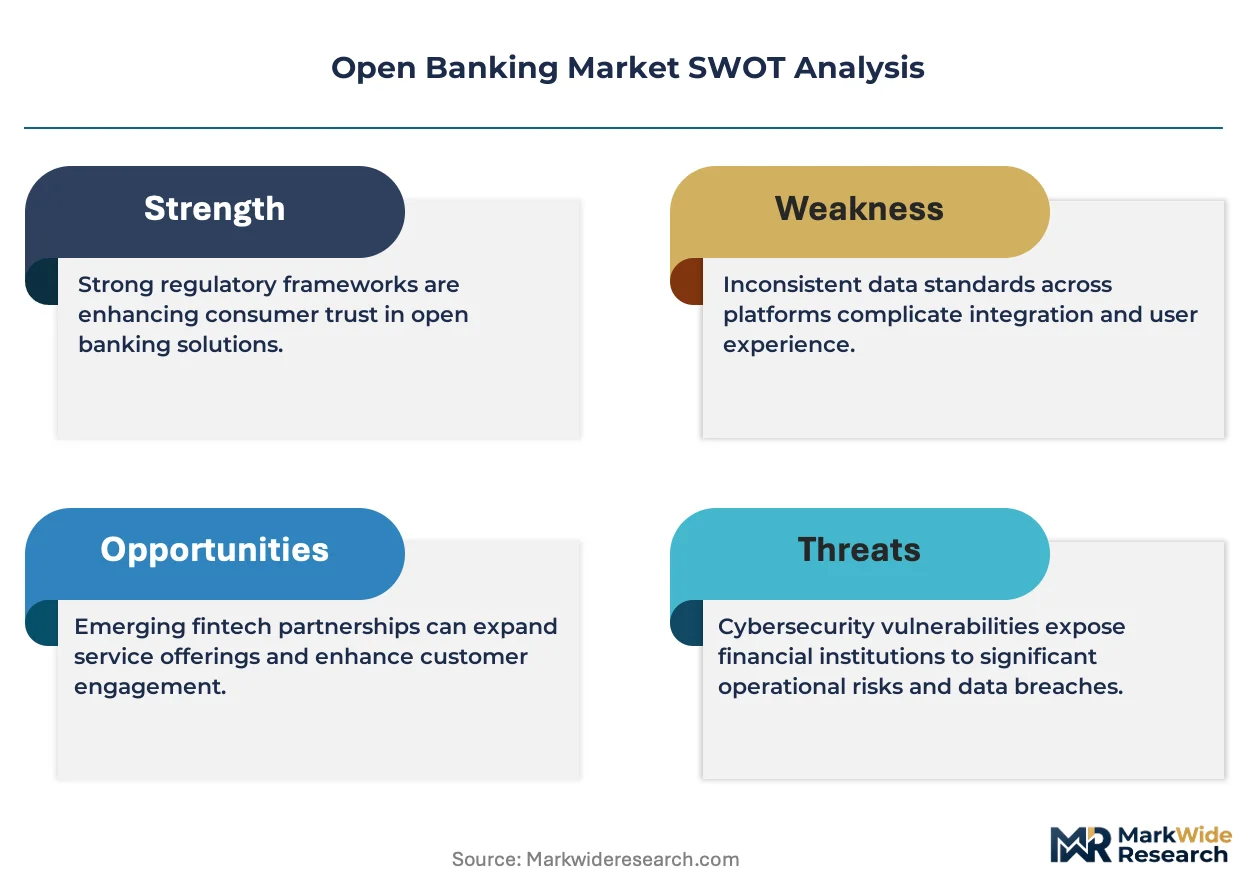
PSD2 and its forthcoming PSD3 revision in Europe, alongside the UK's Open Banking Implementation Entity standards and Brazil's Central Bank PIX open finance rules, collectively mandate API standardization, customer consent management, and strong customer authentication. These frameworks shape demand by defining liability boundaries between data holders and third-party providers, directly influencing procurement criteria for compliance services. Stakeholders must monitor divergence between regional API specifications, as fragmentation in consent granularity and data scope threatens interoperability investments.
Market Dynamics
API standardization mandates across Brazil, the United Kingdom, and the European Union are fragmenting vendor architectures while forcing banks to rebuild core infrastructure for real-time data exchange.
Growth Catalysts
- PSD3 Strong Customer Authentication:The EU's forthcoming revision mandates stepped-up identity verification protocols, compelling banks to upgrade API security stacks and creating procurement demand for compliance middleware.
- PIX Open Finance Rules:Brazil's Central Bank mandates universal API access for payment initiation and account data, accelerating third-party provider licensing and infrastructure investment.
- Real-Time Payment Rails:Instant settlement infrastructure deployment across the United Kingdom and EU markets enables transaction-level underwriting for fintech lenders, expanding addressable credit markets.
Market Restraints
- Core System Modernization Costs:Tier-one banks face nine-figure expenditures to decouple legacy mainframes from API layers, compressing near-term profit margins and delaying rollout timelines.
- Consent Management Fragmentation:Divergent granularity requirements between UK OBIE standards and EU PSD2/PSD3 specifications force vendors to maintain parallel codebases, inflating engineering overhead.
- Screen Scraping Persistence:Unregulated data aggregation via credential sharing undercuts licensed API economics, eroding pricing power for authorized providers in retail banking segments.
Strategic Opportunities
- Variable Recurring Payments:The UK's upcoming VRP mandate for non-sweeping use cases opens subscription billing and utility payment markets previously locked to card networks.
- Wealth Data Aggregation:Pension and investment account APIs remain underpenetrated relative to current accounts, offering first-mover advantages to aggregators securing asset manager partnerships.
- Merchant Acquirer Integration:Payment initiation APIs embedded directly into e-commerce checkout flows bypass traditional card acceptance infrastructure, capturing interchange economics.
Industry Challenges
- OAuth 2.0 and FAPI Engineering Scarcity:Financial-grade API security expertise concentrates among a narrow cohort of developers, inflating compensation and extending vendor onboarding timelines.
- Multi-Jurisdiction Consent Orchestration:Cross-border data flows require simultaneous compliance with GDPR, UK data protection law, and Brazil's LGPD, complicating product architecture for global fintechs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Banking Market |
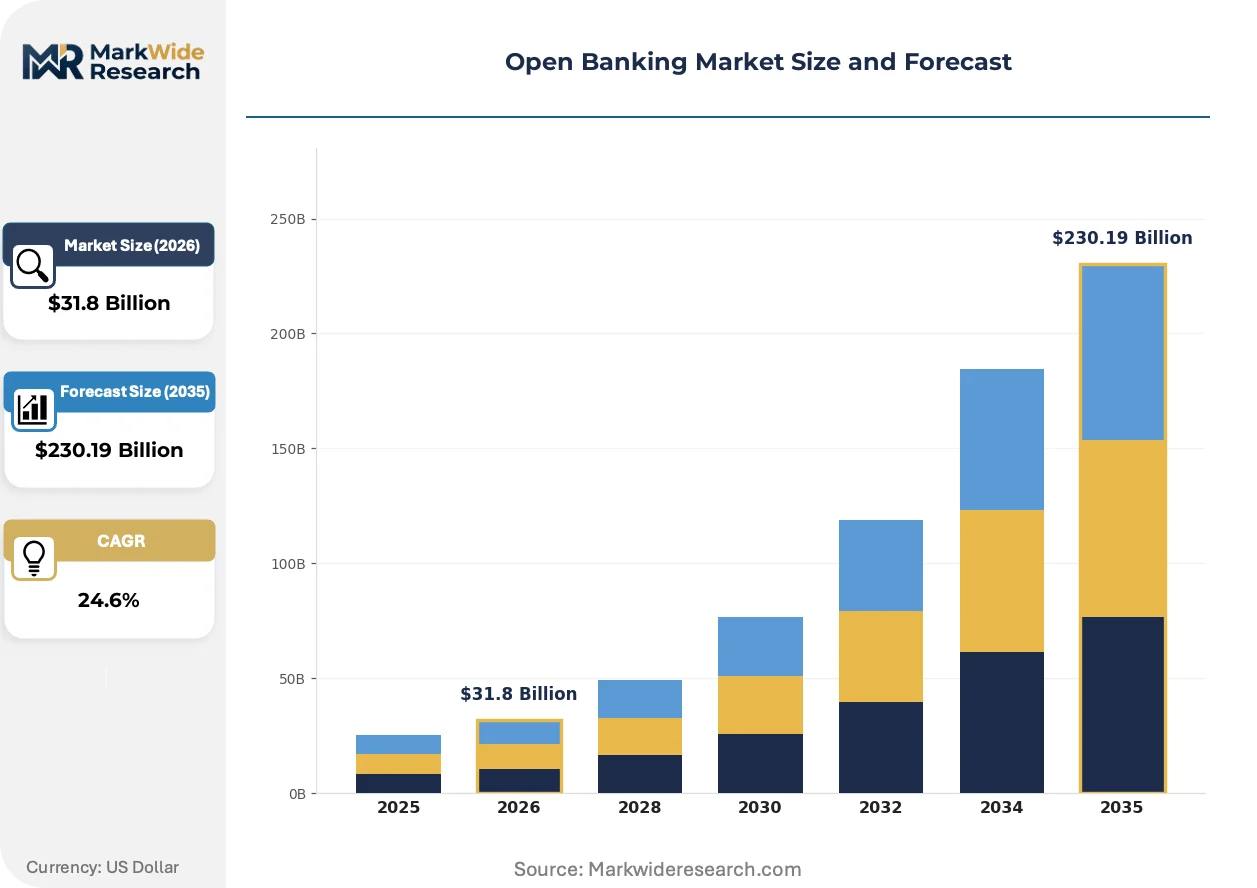
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $230.19 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Initiation, Account Aggregation, Financial Data Sharing, Compliance Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Hosted End User: Banks, Fintechs, Third-Party Providers, Consumers Technology: APIs, Blockchain, AI, Data Analytics |
| Companies Covered | Plaid, Tink, TrueLayer, Finicity, Yapily, Token.io, Worldline, Envestnet, MX Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Banking Market Strategic Shifts & Innovations
Real-time financial data infrastructure is compressing the latency between account activity and actionable insight, reshaping how lenders, merchants, and wealth managers interact with consumer financial behavior.
Financial-grade API security protocols are consolidating around FAPI 2.0 specifications, with OAuth 2.0 extensions for confidential clients becoming the baseline for bank-third-party authentication. Tier-two banks and credit unions are adopting cloud-native identity stacks to avoid in-house security engineering. This consolidation is compressing the vendor landscape for authentication middleware, favoring specialists with direct bank integration experience over generic identity providers.
The EU's Digital Operational Resilience Act imposes mandatory incident reporting and third-party risk management standards on financial entities, extending liability chains to API infrastructure providers. Banks must now audit fintech partners for operational continuity, not merely data security. Retail banking divisions in Germany and France are responding by consolidating vendor relationships and demanding contractual uptime guarantees that exceed prior service-level agreements.
Merchant checkout flows are embedding account-to-account payment initiation as a direct alternative to card-on-file arrangements, displacing interchange-dependent revenue models. E-commerce platforms in the United Kingdom are piloting one-click bank payments for subscription renewals, leveraging variable recurring payment rails. This behavioral shift is most visible in grocery and digital services verticals, where transaction frequency and low average order values amplify interchange savings.
Open Banking Market Segmentation
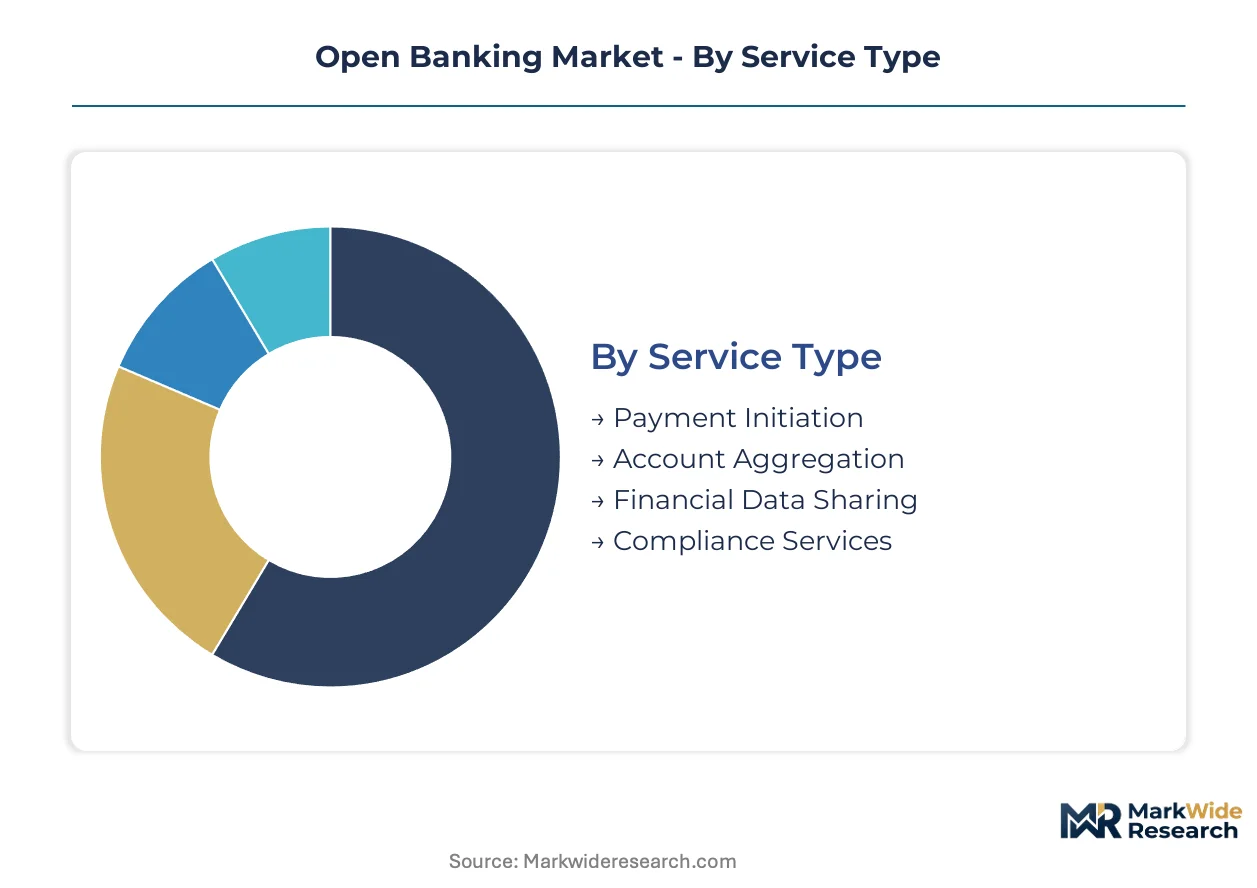
Open banking architectures fragment across multiple technical and commercial dimensions. Procurement decisions hinge on integration complexity, regulatory jurisdiction, and legacy system constraints.
Service Type:
Capital intensity varies sharply across service categories, with infrastructure-heavy segments demanding multi-year deployment timelines and specialized engineering talent.
- Payment Initiation:Real-time transaction execution APIs enable direct account-to-account transfers without card network intermediation. Demand concentrates in United Kingdom e-commerce checkout flows where merchants seek interchange cost elimination. PIX Open Finance rules in Brazil are accelerating third-party provider licensing for this segment.
- Account Aggregation:Multi-bank data consolidation services require deep API integration with legacy core banking systems. Tier-one banks in Germany and France are consolidating vendor relationships here as DORA compliance extends liability chains to infrastructure providers. This segment commands the longest sales cycles and deepest technical integration requirements.
- Financial Data Sharing:Consent-managed data exchange for underwriting and wealth analytics.
- Compliance Services:Middleware for PSD3 strong customer authentication and multi-jurisdiction consent orchestration.
Most installed capacity flows through Account Aggregation. Expansion is steepest in Payment Initiation.
Deployment Model:
Cost tier stratification separates enterprise-grade infrastructure investments from elastic consumption models favored by emerging fintechs.
- Cloud-Based:Elastic infrastructure consumption eliminates upfront data center capital expenditure. Mid-tier fintechs in the United Kingdom and Brazil are migrating here to avoid in-house security engineering for OAuth 2.0 and FAPI protocol implementation.
- Hybrid:Split architectures keep sensitive authentication workloads on-premises while routing transaction processing to cloud environments. Tier-one banks managing legacy mainframe dependencies dominate procurement here, particularly in France and Germany where operational continuity requirements are most stringent.
- On-Premises:Fully captive infrastructure for maximum data sovereignty control.
- Hosted:Managed service deployments with vendor-operated infrastructure.
Hybrid configurations retain the largest existing footprint. Cloud-based deployments are climbing the fastest among new implementations.
End User:
Application-driven procurement patterns diverge between regulated incumbents and unlicensed intermediaries seeking API access.
- Banks:Regulated data holders must rebuild core infrastructure for real-time data exchange under PSD3 and PIX mandates. United Kingdom retail banking divisions are rebalancing API traffic toward fintech intermediation as consumers abandon legacy portals.
- Fintechs:Unlicensed technology providers leverage payment initiation APIs for transaction-level underwriting and embedded finance products. Brazilian small business lenders exemplify this demand concentration.
- Third-Party Providers:Licensed intermediaries operating under open banking frameworks.
- Consumers:End beneficiaries of account aggregation and payment initiation services.
Bank procurement dominates current spending. Fintech adoption is gaining share fastest as licensing frameworks mature.
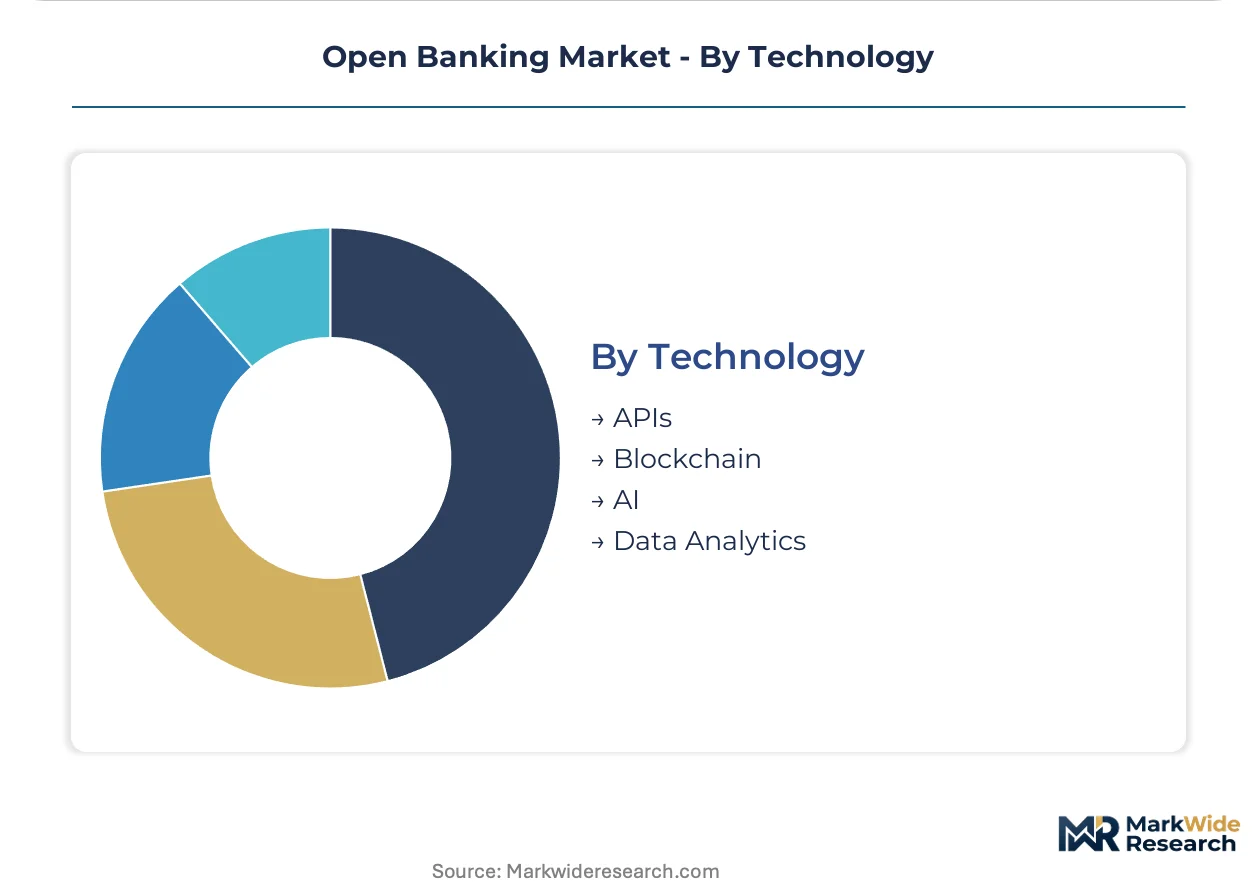
Technology:
Maturity curves separate production-ready protocols from emerging infrastructure still seeking standardization.
- APIs:RESTful interfaces operating under OAuth 2.0 and FAPI security protocols constitute the foundational technical layer. Financial-grade API security expertise scarcity is inflating compensation and extending vendor onboarding timelines across United Kingdom and EU implementations.
- AI:Machine learning models applied to cash flow analytics and transaction categorization for underwriting decisions. Demand is concentrating in fintech lender risk engines where real-time data enables expanded credit market access.
- Blockchain:Distributed ledger experiments for settlement finality and identity verification.
- Data Analytics:Behavioral pattern recognition and predictive modeling tools.
API infrastructure absorbs the majority of current investment. AI layer spending is expanding most quickly as underwriting automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence is fragmenting vendor architectures and driving infrastructure investment toward jurisdictions with the most prescriptive API mandates. Compliance cost gaps between mature and emerging frameworks are reshaping where fintechs domicile their technical operations.
United Kingdom
The Open Banking Implementation Entity's standards command the deepest third-party provider penetration worldwide. Variable Recurring Payments for non-sweeping use cases will open subscription billing markets previously locked to card networks. London's fintech cluster anchors account aggregation demand as retail banks rebalance API traffic toward licensed intermediaries.
Brazil
Central Bank PIX open finance rules mandate universal API access for payment initiation and account data. Third-party provider licensing is accelerating as small business lenders leverage transaction-level underwriting. São Paulo's financial district concentrates infrastructure deployment for real-time settlement rails.
Germany
The Digital Operational Resilience Act extends liability chains to API infrastructure providers, forcing operational continuity audits. Tier-one banks are consolidating vendor relationships and demanding contractual uptime guarantees exceeding prior service-level agreements. Frankfurt's banking cluster leads hybrid deployment adoption for legacy mainframe decoupling.
France
PSD3 strong customer authentication mandates are compelling banks to upgrade API security stacks. Retail banking divisions are responding to DORA compliance with stricter third-party risk management standards. Parisian fintechs are piloting merchant checkout flows embedding account-to-account payment initiation.
United States
Section 1033 of the Dodd-Frank Act is driving consumer financial data access rulemaking, though implementation lags European frameworks. Mid-tier fintechs are migrating to cloud-native identity stacks to avoid in-house OAuth 2.0 engineering. San Francisco and New York clusters dominate developer ecosystem investment for account aggregation services.
Open Banking Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with API infrastructure vendors commanding premium positioning against white-label middleware providers. The vendor base concentrates among authentication specialists with direct bank integration experience, while generic identity providers face compression. Three archetypes dominate: account aggregation platforms, payment initiation specialists, and compliance middleware vendors. Consolidation is proceeding through strategic partnerships for cross-border coverage and technology licensing for FAPI 2.0 protocol implementation.
Within the account aggregation tier, Plaid and Tink occupy anchor positions representing North American and European coverage archetypes respectively. TrueLayer exemplifies the payment initiation specialist model competing on transaction speed for e-commerce checkout flows. These three entities sit within a narrowing vendor landscape where financial-grade API security expertise scarcity is inflating compensation and extending onboarding timelines.
| Leading Market Players |
|---|
| Plaid |
| Tink |
| TrueLayer |
| Finicity |
| Yapily |
| Token.io |
| Worldline |
| Envestnet |
| MX Technologies |
| Others |
Cost & Logistics Intelligence
Tier-one banks in Germany and France concentrate procurement of API infrastructure and compliance middleware, anchoring contract-based multi-year licensing with strict uptime guarantees and DORA-mandated operational continuity clauses. This buyer concentration forces vendors into performance-tied pricing with penalty structures for service degradation.
Pricing Analysis
Direct-to-bank enterprise licensing dominates, with subscription tiers scaling by transaction volume and API call frequency. Price differentiation rests on FAPI 2.0 certification grade and geographic deployment scope—UK OBIE-compliant implementations command premiums over baseline OAuth 2.0 configurations. Cost compression in mid-tier fintech segments is intensifying because cloud-native identity stacks eliminate in-house security engineering needs. Emerging Brazilian third-party providers exhibit highest price sensitivity, while tier-one European banks prioritize contractual uptime over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for authentication middleware mandate multi-vendor qualification among tier-one banks, preventing single-provider dependency. Engineering talent concentrates in the United Kingdom, Germany, and the United States, with financial-grade API security expertise drawing from specialized developer cohorts. Raw material dependencies include cloud compute capacity from hyperscalers, cryptographic hardware security modules, and proprietary bank core system adapters. Single-source vulnerability persists in legacy mainframe integration specialists. Distribution runs through direct vendor-bank contracting with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open banking infrastructure procurement is shifting toward premium specifications as DORA and PSD3 mandates elevate operational resilience and authentication standards above cost minimization.
For Market Incumbents: Cement API security stack dominance through direct FAPI 2.0 protocol implementation and captive certification programs. Consolidate vendor relationships in Germany and France where DORA extends liability chains to infrastructure providers. Prioritize contractual uptime guarantees exceeding prior service-level agreements to defend against cloud-native challengers. For New Entrants and Emerging Players: Tier-two credit unions and regional banks in the United States represent the most penetrable buyer archetype, underserved by incumbent authentication specialists. Target hybrid deployment configurations for institutions managing legacy mainframe dependencies. Pursue channel partnerships with core banking system vendors for embedded API layer integration. For Investors and Strategic Acquirers: Payment processors seeking embedded finance capabilities are the most active acquirer in this space, driving consolidation around direct bank integration expertise. Long-term viability favors specialists with multi-jurisdiction consent orchestration capabilities and proven PIX or OBIE compliance track records. Monitor variable recurring payment mandate implementation velocity in the United Kingdom as inflection indicator for subscription billing market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FAPI 2.0 Protocol Certification | PSD3 strong customer authentication mandates require upgraded security stacks across EU banks. |
| Variable Recurring Payment Rails | UK non-sweeping VRP implementation opens subscription billing markets previously locked to card networks. |
| Multi-Jurisdiction Consent Orchestration | Cross-border GDPR, UK data protection, and Brazil LGPD compliance demands unified product architecture. |
| Cloud-Native Identity Stack Migration | Mid-tier fintechs avoid in-house OAuth 2.0 engineering through elastic infrastructure consumption. |
| Legacy Mainframe Decoupling | Tier-one banks rebuild core infrastructure for real-time data exchange under PIX and PSD3 mandates. |
Research Approach
Direct dialogue with bank CTOs, fintech platform engineers, regulatory compliance officers, and API infrastructure vendors grounded qualitative insights in operational reality. Secondary validation drew from European Banking Authority PSD2/PSD3 implementation reports, UK Open Banking Implementation Entity standards documentation, Brazil Central Bank PIX regulatory filings, and SEC disclosures from publicly traded financial infrastructure providers. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with regulatory-mandated transaction volume disclosures.
Bottom-up modeling aggregated individual service-type deployments across payment initiation, account aggregation, and compliance middleware segments, while top-down analysis calibrated aggregate market sizing against regulatory transaction reporting. Segmentation dimensions included service type, deployment model, end-user category, and regional regulatory framework. CAGRs were derived from fitted growth curves anchored to mandated implementation deadlines and licensing velocity. Forecast inputs incorporated PIX third-party provider licensing pace and UK variable recurring payment mandate rollout timing.
Underlying measurement precision varies by segment; payment initiation APIs carry tighter precision than emerging wealth data aggregation categories due to established transaction reporting requirements. Forecasts reflect assumptions about regulatory implementation timelines, bank core system modernization budgets, and fintech licensing velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Retail Core Banking Systems Market
Banking
Performance Bank Guarantee Market
Banking
Canada Data Analytics in Banking Market
Banking
Armenia Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
China Retail Banking System Market
Banking
Europe Banking-As-A-Service Market
Banking
Banking Software Market
Banking
Corporate Digital Banking Market
Banking
Banking CRM Software Market
Banking
Banking Credit Analytics Market
Banking
North America Bank Kiosk Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Singapore Neobanking Market
Banking
Credit Intermediation Market
Banking
ATM Market