
 UK Banking as a Service Market | 2026-2036
UK Banking as a Service Market Size, Share, and Industry Trends Forecast 2026-2036
UK Banking as a Service Market Analytics
Fintech lending platforms is recalibrating how Banking as a Service providers allocate engineering resources across the UK. Thought Machine leverages its cloud-native core banking architecture to anchor enterprise-grade deployments for tier-one distributors. Starling Bank sustains its API-first infrastructure to dominate SME banking propositions. ClearBank competes through real-time settlement capabilities that position it as the preferred banking partner for payment fintechs.
Banking as a Service denotes a licensed banking infrastructure delivered through APIs, enabling non-bank entities to embed financial products—accounts, payments, lending—within their own customer journeys without obtaining a banking charter. The architecture relies on microservices orchestration, tokenized authentication protocols, and modular ledger systems to ensure real-time transaction processing and regulatory audit trails. API Integration commands the largest service-type revenue pool by volume, while Compliance Solutions captures disproportionate margin due to Know Your Customer and anti-money laundering automation requirements. Public Cloud deployments lead on cost efficiency for startup entrants, though Hybrid Cloud configurations are gaining traction among traditional banks navigating data sovereignty constraints.
The Financial Conduct Authority enforces open banking standards and operational resilience requirements that dictate API security protocols and third-party risk management frameworks for UK Banking as a Service participants. The Prudential Regulation Authority's capital adequacy rules for e-money and payment institutions shape which providers can scale balance-sheet-dependent products. Stakeholders must monitor how the Bank of England's digital pound consultations reshape settlement infrastructure demands and competitive moats.
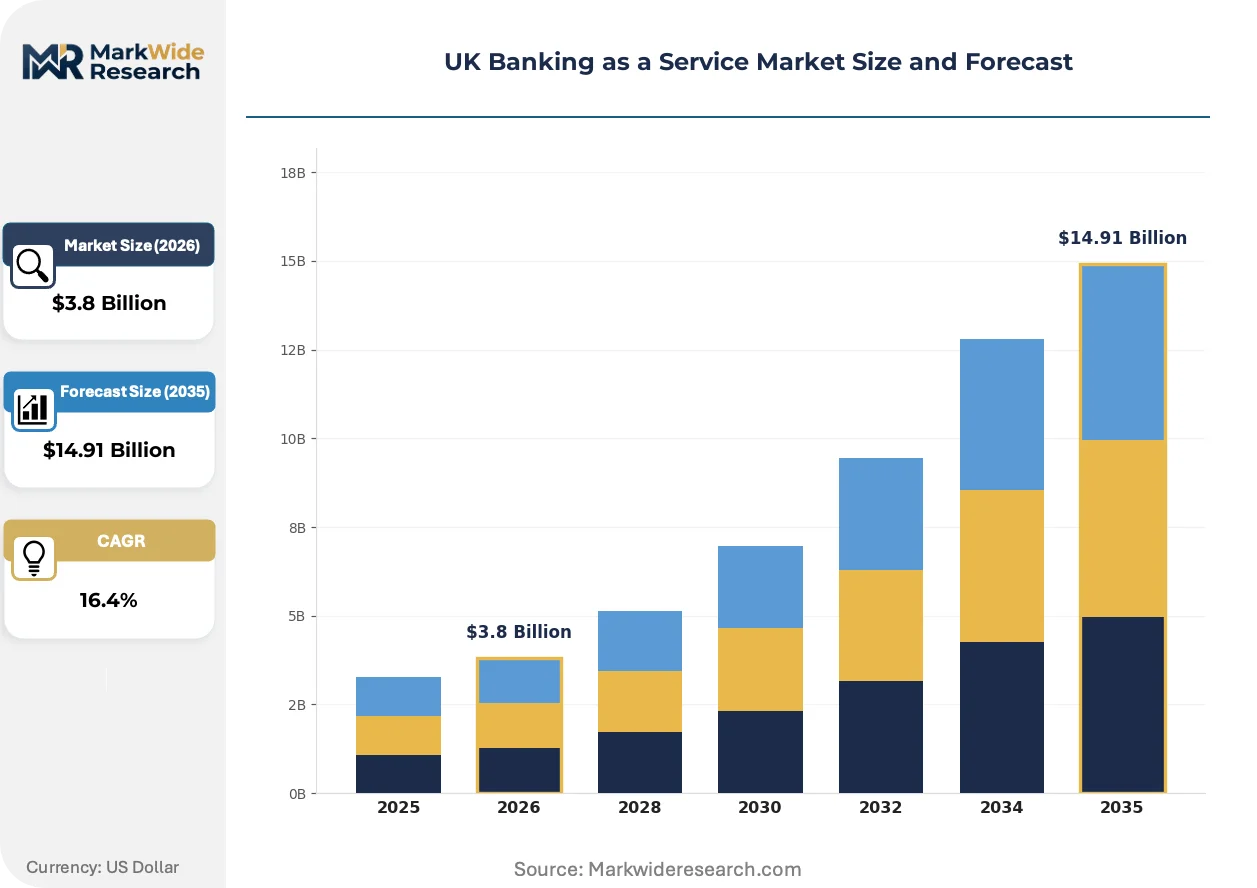
Market Dynamics
Embedded finance integration is forcing UK Banking as a Service providers to rearchitect API stacks for real-time ledger synchronization, compressing deployment timelines from months to weeks.
Growth Catalysts
- Open Banking Mandates:The Financial Conduct Authority's API standards compel incumbent banks to expose payment initiation and account information interfaces, creating fertile ground for third-party distributors.
- Neobank Proliferation:Digital-native challengers in London's fintech corridor demand modular banking infrastructure to launch lending and deposit products without charter acquisition delays.
- Real-Time Settlement Infrastructure:Faster Payments Service integration enables payment fintechs to offer immediate fund availability, differentiating BaaS propositions against batch-processing legacy systems.
Market Restraints
- Prudential Capital Requirements:The Prudential Regulation Authority's liquidity coverage ratios constrain e-money institutions from scaling balance-sheet lending products.
- Cloud Concentration Risk:Dominance of hyperscale providers in UK data centers creates single-point-of-failure exposure for BaaS platforms dependent on public cloud orchestration.
- Tokenization Complexity:Cryptographic key management for API authentication demands specialized security engineering that mid-tier distributors struggle to source.
Strategic Opportunities
- Scotland and Northern England:Regional fintech clusters outside London exhibit underpenetrated SME banking demand with lower customer acquisition costs.
- Regulatory Sandbox Access:The Financial Conduct Authority's sandbox program permits controlled testing of novel lending algorithms, accelerating product-market fit validation.
- AI-Driven Compliance Automation:Convergence of machine learning with anti-money laundering workflows reduces manual review overhead for high-volume transaction monitoring.
Industry Challenges
- API Talent Scarcity:Shortage of engineers proficient in microservices architecture and financial-grade security protocols inflates compensation costs.
- Core System Integration:Incumbent banks' COBOL-based legacy infrastructure creates friction when connecting to modern RESTful BaaS platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Banking as a Service Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Payment Processing, Compliance Solutions, API Integration Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Customer Type: Fintechs, Traditional Banks, Enterprises, Startups Technology: Blockchain, Artificial Intelligence, Machine Learning, Microservices |
| Companies Covered | Thought Machine, Starling Bank, Bankable, ClearBank, 11:FS Foundry, Solarisbank, Treezor, Railsr, Unnax, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Banking as a Service Market Evolving Landscape
Cloud-native core banking architectures are overtaking monolithic legacy systems, enabling elastic scaling and continuous deployment pipelines that match fintech velocity expectations.
Event-driven microservices is overtaking synchronous API patterns in UK Banking as a Service deployments. Tier-one distributors adopt Apache Kafka streams for real-time balance updates and transaction notifications. This architecture compresses reconciliation cycles from end-of-day batch to continuous ledger synchronization.
The Financial Conduct Authority's Consumer Duty rules reshape product governance obligations for BaaS-enabled distributors. Fair value assessments and vulnerability detection mandates flow through API contracts into distributor front-ends. Retail-facing fintechs reconfigure onboarding workflows to capture behavioral indicators for suitability scoring.
Embedded lending procurement is fragmenting across vertical SaaS platforms rather than concentrating through standalone neobanks. E-commerce and property management software vendors integrate white-label credit facilities directly. Manufacturing and logistics sectors in the Midlands demonstrate strongest uptake of invoice financing APIs embedded within enterprise resource planning systems.
UK Banking as a Service Market Segmentation
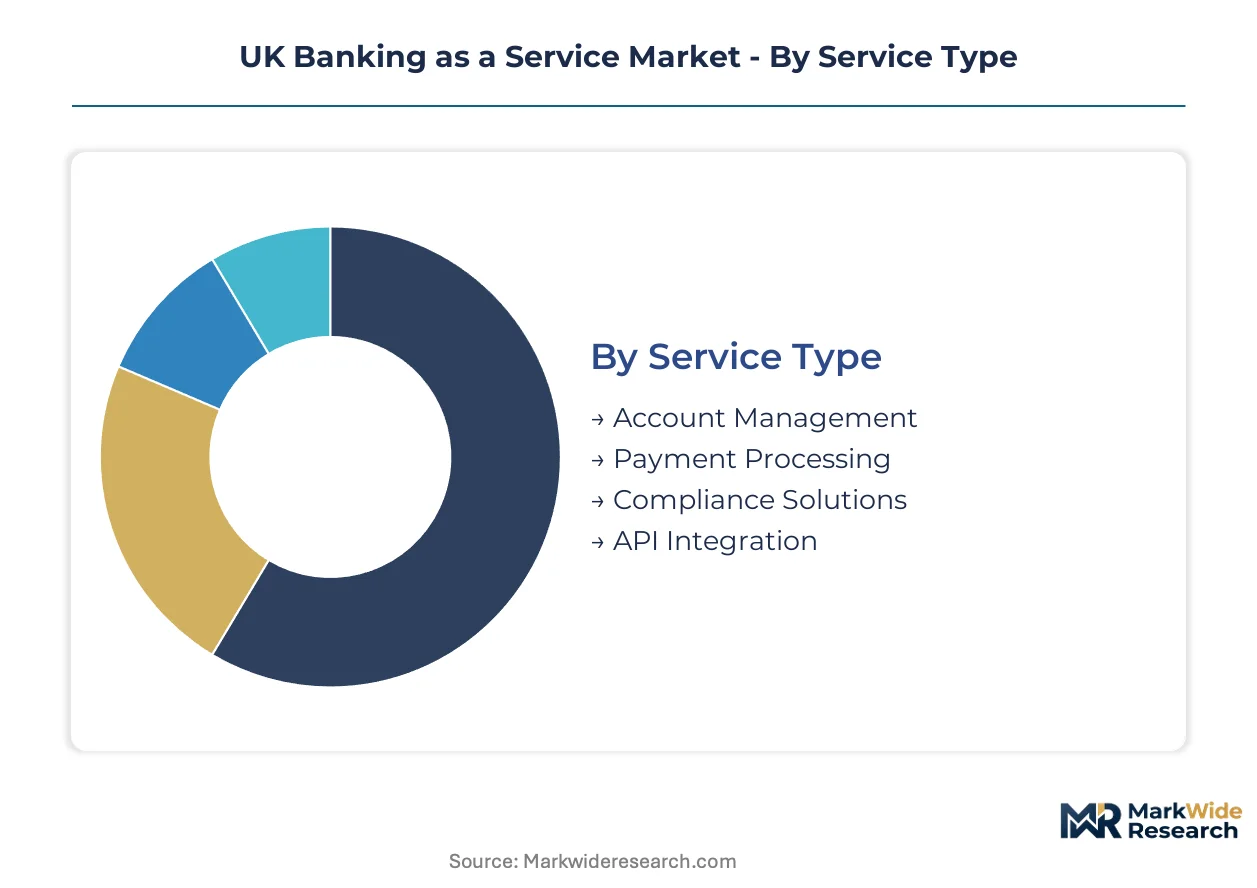
UK Banking as a Service providers calibrate infrastructure investments differently across service layers and customer profiles. Capital allocation decisions hinge on regulatory burden, cloud tenancy costs, and API throughput requirements that vary sharply by segment.
Service Type:
Capital intensity escalates most steeply for segments bearing direct regulatory liability and balance-sheet exposure.
- API Integration:RESTful and event-driven interfaces require continuous engineering investment to maintain Financial Conduct Authority-mandated security protocols. London's fintech corridor concentrates demand as neobanks compete on developer experience and sandbox velocity.
- Compliance Solutions:Automated Know Your Customer and anti-money laundering workflows demand specialized machine learning infrastructure and audit-grade data retention. The Prudential Regulation Authority's capital adequacy rules force providers to maintain redundant verification pipelines, inflating fixed costs disproportionately.
- Account Management:Core ledger operations and customer onboarding workflows.
- Payment Processing:Faster Payments Service integration and real-time settlement orchestration.
Most installed capacity flows through API Integration. Expansion is steepest in Compliance Solutions.
Deployment Model:
Cost tier differentiation separates startup-accessible public infrastructure from sovereignty-constrained hybrid configurations.
- Public Cloud:Elastic compute and storage resources minimize upfront capital for early-stage distributors. Manchester and Birmingham fintech clusters favor this model for rapid prototyping without data center commitments.
- Hybrid Cloud:Sensitive transaction data resides on private infrastructure while compute bursts to public tenancy. Tier-one banks navigating the Bank of England's operational resilience requirements drive adoption here.
- Private Cloud:Dedicated infrastructure for institutions with strict data localization mandates.
- On-premises:Legacy core banking systems requiring physical hardware control.
Public Cloud hosts the majority of active workloads. Hybrid Cloud is gaining share fastest among established financial institutions.
Customer Type:
Volume concentration and margin profile diverge sharply across buyer sophistication and charter status.
- Fintechs:API-native distributors demand modular, pay-as-you-scale pricing with minimal implementation friction. Embedded finance adoption among vertical SaaS platforms in property management and e-commerce concentrates demand in London and Edinburgh.
- Traditional Banks:Incumbent institutions modernizing through partnership rather than charter acquisition. COBOL legacy integration costs and extended procurement cycles constrain deployment velocity.
- Enterprises:Non-financial corporations embedding treasury and payment capabilities.
- Startups:Pre-revenue ventures prioritizing speed-to-market over customization depth.
Fintechs absorb the largest share of provider capacity. Traditional Banks are expanding most quickly as regulatory pressure accelerates modernization timelines.
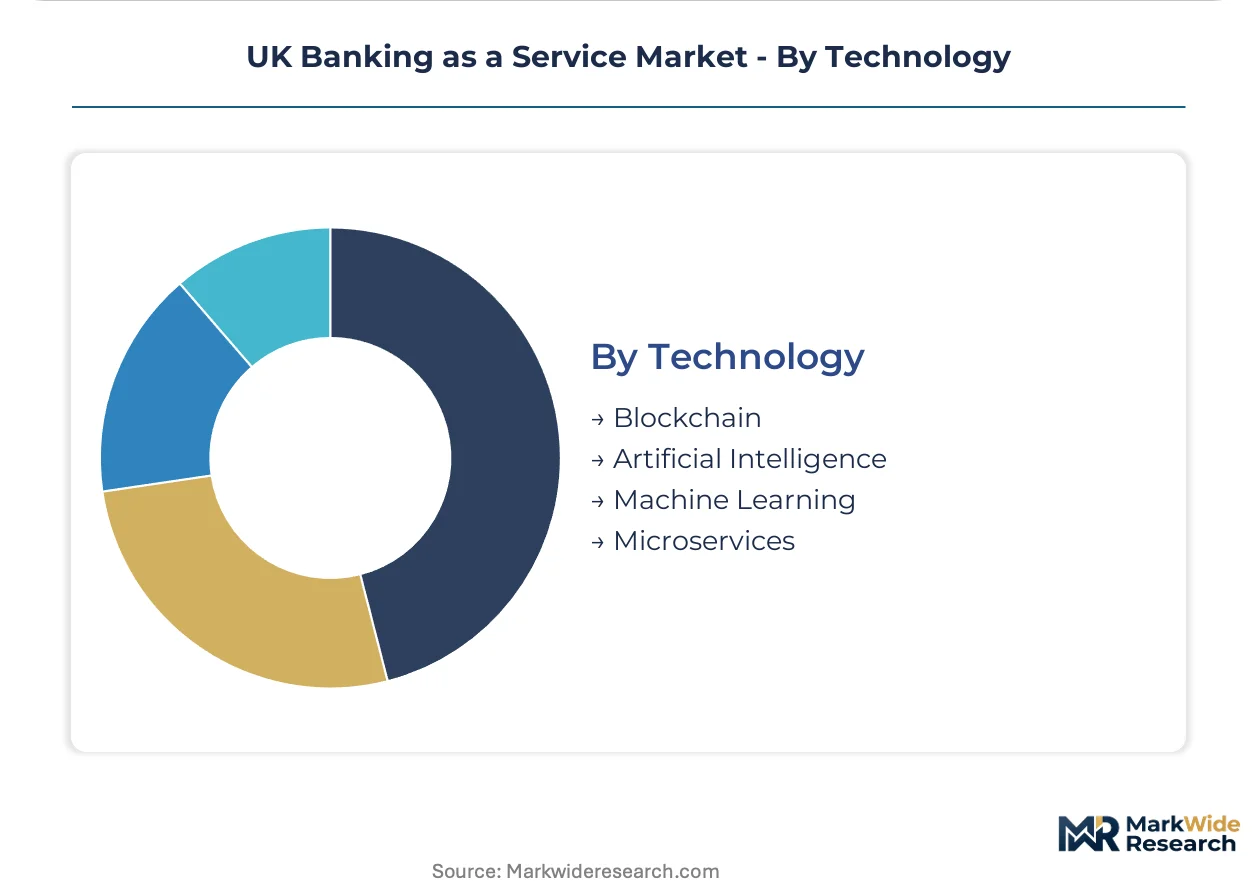
Technology:
Maturity curves separate production-grade infrastructure from experimental architectures still seeking product-market fit.
- Microservices:Containerized, independently deployable services enable continuous delivery pipelines matching fintech release cadences. Event-driven patterns using Apache Kafka streams dominate tier-one distributor stacks for real-time ledger synchronization.
- Artificial Intelligence:Natural language processing for customer service automation and predictive models for credit decisioning. The Financial Conduct Authority's Consumer Duty rules impose explainability requirements that complicate black-box deployments.
- Machine Learning:Transaction monitoring and anomaly detection for anti-money laundering workflows.
- Blockchain:Distributed ledger experiments for settlement and identity verification, limited by interoperability standards and regulatory uncertainty.
Microservices underpin the majority of production deployments. Artificial Intelligence is climbing the fastest as compliance automation demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating UK Banking as a Service capacity where compliance costs and sandbox access create asymmetric advantages. The Prudential Regulation Authority's capital rules and the Financial Conduct Authority's operational resilience mandates generate steep entry barriers that favor established clusters with regulatory proximity.
London and the Southeast
Embedded finance demand from vertical SaaS platforms drives API throughput requirements here. The Financial Conduct Authority's regulatory sandbox accelerates product-market fit validation for fintech distributors. The Square Mile and Canary Wharf host the densest concentration of tier-one BaaS providers and neobank headquarters.
Scotland
Edinburgh's established financial services heritage supplies compliance engineering talent to BaaS platforms. The Scottish government's fintech strategy offers grant funding for cloud-native infrastructure deployment. Glasgow's emerging tech corridor attracts payment fintechs seeking lower operational costs than London.
The Midlands
Manufacturing and logistics enterprises in Birmingham and Manchester drive demand for invoice financing APIs embedded within ERP systems. The Bank of England's regional engagement programs support operational resilience testing outside the capital. Manchester's fintech cluster favors public cloud deployments for rapid prototyping.
North England
Underpenetrated SME banking demand in Leeds and Newcastle generates lower customer acquisition costs for BaaS-enabled distributors. The Financial Conduct Authority's consumer duty rules flow through API contracts into regional onboarding workflows. Newcastle's emerging digital cluster specializes in compliance automation tooling.
Wales and Northern Ireland
Devolved administration incentives attract back-office functions for UK-wide BaaS platforms. Data sovereignty considerations drive hybrid cloud adoption among providers serving public sector clients. Cardiff and Belfast host growing engineering centers supporting London-headquartered infrastructure providers.
UK Banking as a Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with API-native challengers capturing fintech distributors while legacy-integrated providers serve incumbent banks. The vendor base concentrates around three strategic archetypes: cloud-native core banking architects, API-first retail banks with banking licenses, and payment-centric infrastructure specialists. M&A activity targets compliance automation capabilities, while strategic partnerships focus on Faster Payments Service integration and real-time settlement orchestration.
Within the cloud-native tier, Thought Machine exemplifies enterprise-grade core banking deployment for tier-one distributors. Starling Bank occupies a position as the dominant API-first retail bank serving SME propositions. ClearBank anchors the payment infrastructure segment through real-time settlement capabilities that attract payment fintech partnerships.
| Leading Market Players |
|---|
| Thought Machine |
| Starling Bank |
| Bankable |
| ClearBank |
| 11:FS Foundry |
| Solarisbank |
| Treezor |
| Railsr |
| Unnax |
| Others |
Value Network & Pricing Analysis
Neobank procurement preferences for modular, pay-as-you-scale API consumption are forcing Banking as a Service providers to unbundle legacy bundled pricing and absorb cloud infrastructure volatility into margin structures. This demand-side compression cascades through provider engineering resource allocation, intensifying cost discipline in compliance automation and microservices orchestration layers.
Pricing Analysis
API distributor margins compress as tier-one fintechs negotiate volume-based SaaS tiers tied to transaction throughput rather than seat licenses. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade SLA guarantees from sandbox-access prototyping rates. Pricing pressure stems from hyperscale cloud tenancy cost pass-throughs that mid-tier providers struggle to hedge. Early-stage fintech startups exhibit highest price sensitivity, while incumbent banks modernizing through partnership accept premium rates for hybrid cloud sovereignty configurations.
Supply Chain Analysis
Cloud infrastructure engineering talent scarcity in London, Edinburgh, and Manchester is constraining provider scaling velocity and inflating compensation costs for microservices architects. UK data center capacity concentrates in Slough, Docklands, and Manchester, drawing from hyperscale providers including AWS, Azure, and Google Cloud. Raw material dependencies span cryptographic hardware security modules, specialized financial-grade server components, and fiber interconnect infrastructure. Single-source vulnerability concentrates in Tier 1 cloud orchestration services. Distribution runs through direct API marketplace integrations and channel partner technical consulting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Banking as a Service market functions as a regulatory compounder where the Financial Conduct Authority's Consumer Duty implementation is accelerating demand for embedded compliance automation and real-time product governance APIs.
For Market Incumbents: Cement API-first infrastructure moats through Faster Payments Service integration exclusivity and hybrid cloud sovereignty certifications that neobank challengers cannot rapidly replicate. Incumbent banks face substitution threat from cloud-native core banking architects; defend through captive compliance engineering capacity and regulatory sandbox relationship depth. For New Entrants and Emerging Players: Capture underpenetrated SME banking demand in Leeds, Newcastle, and Glasgow where customer acquisition costs run below London benchmarks and regional fintech clusters lack mature BaaS infrastructure. Manufacturing and logistics vertical SaaS platforms in the Midlands represent the most penetrable embedded finance segment; pursue direct ERP integration partnerships rather than standalone neobank competition. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance automation specialists possessing machine learning infrastructure for anti-money laundering workflows and Financial Conduct Authority audit-grade data retention capabilities. Long-term viability hinges on providers navigating the Bank of England's digital pound settlement infrastructure consultations without balance-sheet-dependent product exposure. Watch for inflection in tier-one bank modernization procurement timelines as COBOL legacy integration costs peak.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Product Validation | FCA sandbox access accelerates novel lending algorithm deployment timelines for fintech distributors. |
| Hybrid Cloud Sovereignty Certification | Bank of England operational resilience requirements drive tier-one bank adoption of private-public infrastructure splits. |
| Real-Time Settlement Infrastructure Integration | Faster Payments Service connectivity differentiates BaaS propositions against batch-processing legacy competitors. |
| AI-Driven Compliance Automation Acquisition | Machine learning transaction monitoring reduces manual review overhead for high-volume distributor onboarding. |
| Vertical SaaS Embedded Finance Partnership | Property management and e-commerce software vendors integrate white-label credit facilities directly through API stacks. |
Research Methodology
Bottom-up fintech distributor modeling reconciled against top-down banking infrastructure capacity tracking forms the analytical core of this study. Primary interviews with BaaS platform CTOs, neobank product directors, regulatory affairs leads at authorized payment institutions, and cloud infrastructure procurement officers combined with secondary validation against Financial Conduct Authority authorization databases, Bank of England payment system operator disclosures, and Prudential Regulation Authority regulatory returns. Trade flow analysis of API integration service exports and hyperscale cloud capex deployment patterns provided supply-side triangulation.
Input-output matrices mapped API transaction volume drivers to infrastructure capacity expansion across service type, deployment model, and customer type segmentation dimensions. CAGRs derived from regression analysis of historical authorization growth rates and forward projection of embedded finance adoption curves. Forecast inputs incorporated open banking API call volume trajectories, Faster Payments Service message growth patterns, and regulatory sandbox graduation rates.
Underlying measurement precision varies by segment; API Integration and Public Cloud deployments carry tighter precision than experimental Blockchain and Private Cloud configurations. Forecasts reflect assumptions regarding regulatory sandbox access continuity, hyperscale cloud pricing stability, and tier-one bank modernization budget allocation. Material deviation in Bank of England digital pound settlement infrastructure timelines, Prudential Regulation Authority capital requirement recalibrations, or Financial Conduct Authority operational resilience enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Southeast Asia Commercial Banking Market
Banking
Cardless ATM Market
Banking
Bank Guarantee Market
Banking
Automated Teller Machine (ATM) Market
Banking
North America Bank Kiosk Market
Banking
Cloud Billing in Banking Market
Banking
Europe Neobanking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Banking CRM Software Market
Banking
United Kingdom Data Analytics in Banking Market
Banking
Banking Tax Management Software Market
Banking
Brazil Retail Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
China Bank Kiosk Market
Banking
Global Banking Systems Software Market
Banking
US Data Analytics in Banking Market