
 North America Challenger Banks Market | 2026-2036
North America Challenger Banks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Challenger Banks Market Insights
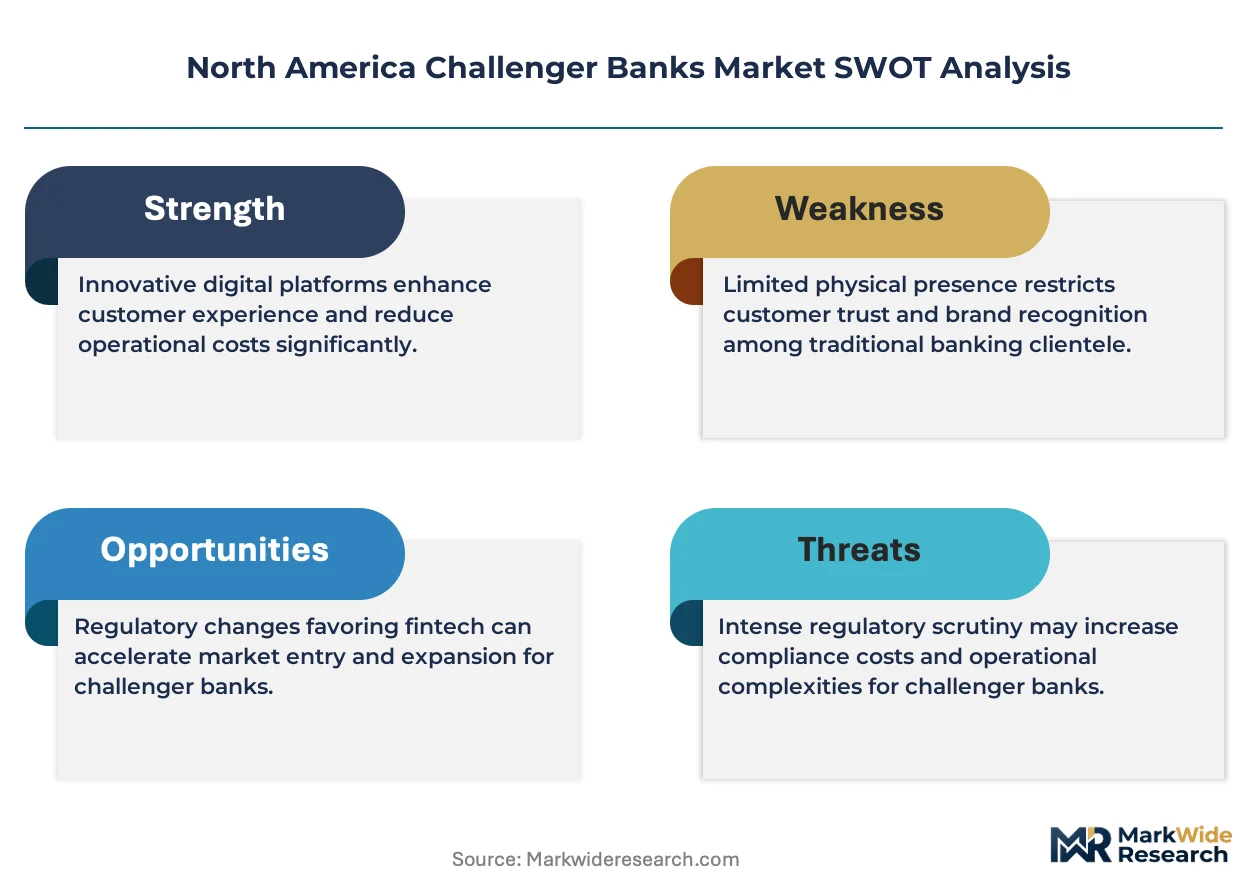
A capital-intensity divergence between branchless operators and legacy-dependent competitors is bifurcating the North America challenger bank landscape. Chime Financial, Inc. leverages its first-mover scale to dominate fee-free consumer deposit acquisition across the United States. Varo Bank, N.A. sustains a national bank charter advantage that anchors its ability to offer insured savings products directly. SoFi Bank, N.A. differentiates through integrated lending and investment verticals that extend its share of wallet among high-earning professionals.
North America challenger banks constitute digitally native, mobile-first financial institutions that operate without traditional branch networks, relying on cloud-native core banking platforms and real-time payment rails to deliver retail and commercial services. These institutions primarily serve consumers and SMEs seeking lower-cost deposit accounts, faster loan origination, and API-embedded financial management tools. Deposit accounts and payment solutions command the largest current revenue pools, while AI-based solutions represent the fastest-expanding technology segment as institutions deploy machine learning for fraud detection and personalized underwriting. Mobile banking remains the dominant delivery channel, though blockchain technology adoption is accelerating for cross-border settlement and identity verification use cases.
The Office of the Comptroller of the Currency, the Federal Deposit Insurance Corporation, and the Consumer Financial Protection Bureau collectively shape charter availability, deposit insurance eligibility, and consumer disclosure standards across the United States and Canada. State-level money transmitter licensing requirements fragment market access for new entrants seeking multi-jurisdictional operations. Stakeholders must monitor pending federal fintech charter rulings and state-level open banking mandates to anticipate which regulatory pathway will unlock the next phase of deposit growth and lending authorization.
Market Dynamics
Cloud-native core banking infrastructure is decomposing the traditional branch-based deposit acquisition model, forcing incumbent institutions to absorb technology costs while branchless operators scale customer acquisition through API-embedded distribution partnerships with payroll providers and e-commerce platforms.
Growth Catalysts
- Real-Time Payment Rails:The Federal Reserve's FedNow Service enables instant settlement for challenger bank transfers, eliminating the float advantage that legacy institutions held on ACH delays.
- SME Banking Gap:Small and medium enterprises in California and New York demand faster loan origination than branch-dependent competitors can deliver, driving account migration to digital-first platforms.
- Open Banking Frameworks:Consumer Financial Protection Bureau data-sharing rules mandate standardized API access, reducing friction for account aggregation and switching.
Market Restraints
- Charter Capital Requirements:National bank charter applicants must demonstrate tangible capital reserves that strain venture-backed balance sheets during rate volatility cycles.
- State Licensing Fragmentation:Money transmitter licenses operate on a state-by-state basis, creating compliance duplication costs for multi-jurisdictional deposit and payment products.
- Core Banking Vendor Concentration:Cloud infrastructure dependencies on three dominant providers create systemic operational risk and pricing power asymmetry.
Strategic Opportunities
- Embedded Finance Convergence:Banking-as-a-Service APIs combined with vertical SaaS platforms unlock distribution through accounting software and property management systems serving Canadian SMEs.
- Credit-Builder Products:Underbanked populations in Texas and Florida seek secured card and installment loan structures that traditional institutions underserve.
- AI Underwriting Authorization:Pending federal fintech charter rulings may permit algorithmic lending decisions without manual review requirements, compressing origination timelines.
Industry Challenges
- Cloud Engineering Talent Scarcity:Kubernetes and distributed systems expertise commands premium compensation that outpaces non-bank fintech salary benchmarks.
- Third-Party Risk Management:FDIC examination guidelines require continuous monitoring of API-dependent vendor ecosystems, stretching compliance function bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Challenger Banks Market |
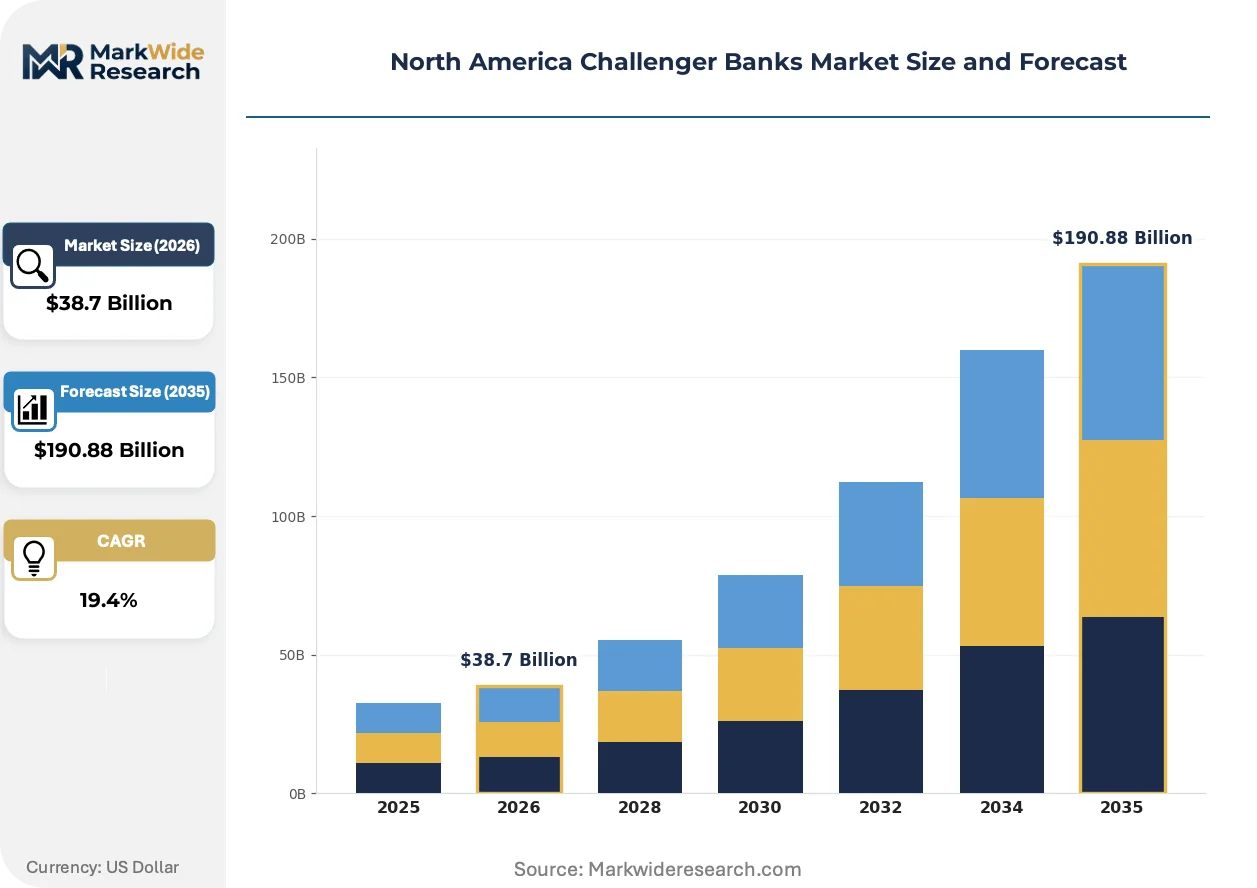
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Deposit Accounts, Loan Services, Payment Solutions, Financial Management Customer Type: Consumers, SMEs, Corporates, Freelancers Technology: Mobile Banking, Cloud Computing, AI-Based Solutions, Blockchain Technology Offering: Personal Accounts, Business Accounts, Investment Options, Savings Tools |
| Companies Covered | Chime Financial, Inc., Varo Bank, N.A., SoFi Bank, N.A., Ally Bank, MoneyLion Inc., Aspiration Partners, Inc., Current, Qapital, Inc., Dave, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Challenger Banks Market Trends and Innovations
Artificial intelligence deployment is restructuring how challenger banks acquire customers, assess credit risk, and detect fraud, compressing the cost structure gap between digital-native institutions and technology-laden legacy competitors.
Machine learning-based fraud detection is decomposing the rule-based transaction monitoring systems that dominated retail banking compliance. Mid-market challenger banks in Illinois and Pennsylvania are adopting neural network models for real-time authorization decisions. This technology compression is collapsing the fraud-loss differential that previously justified legacy infrastructure investment.
The Consumer Financial Protection Bureau's evolving fintech oversight framework is mandating clearer disclosure of algorithmic decision-making in lending products. Institutions must now document adverse action notices with specific variable weights, increasing compliance documentation burdens. High-earning professional segments in New York and California are demanding transparency into credit pricing models, forcing product architecture redesign.
Payroll-integrated savings automation is displacing standalone budgeting applications as the primary customer acquisition channel. Hourly workers in Texas manufacturing and logistics sectors prefer round-up features tied directly to wage deposits over manual transfer discipline. This behavioral shift concentrates deposit growth among employers offering earned wage access partnerships with challenger banking platforms.
North America Challenger Banks Market Segmentation
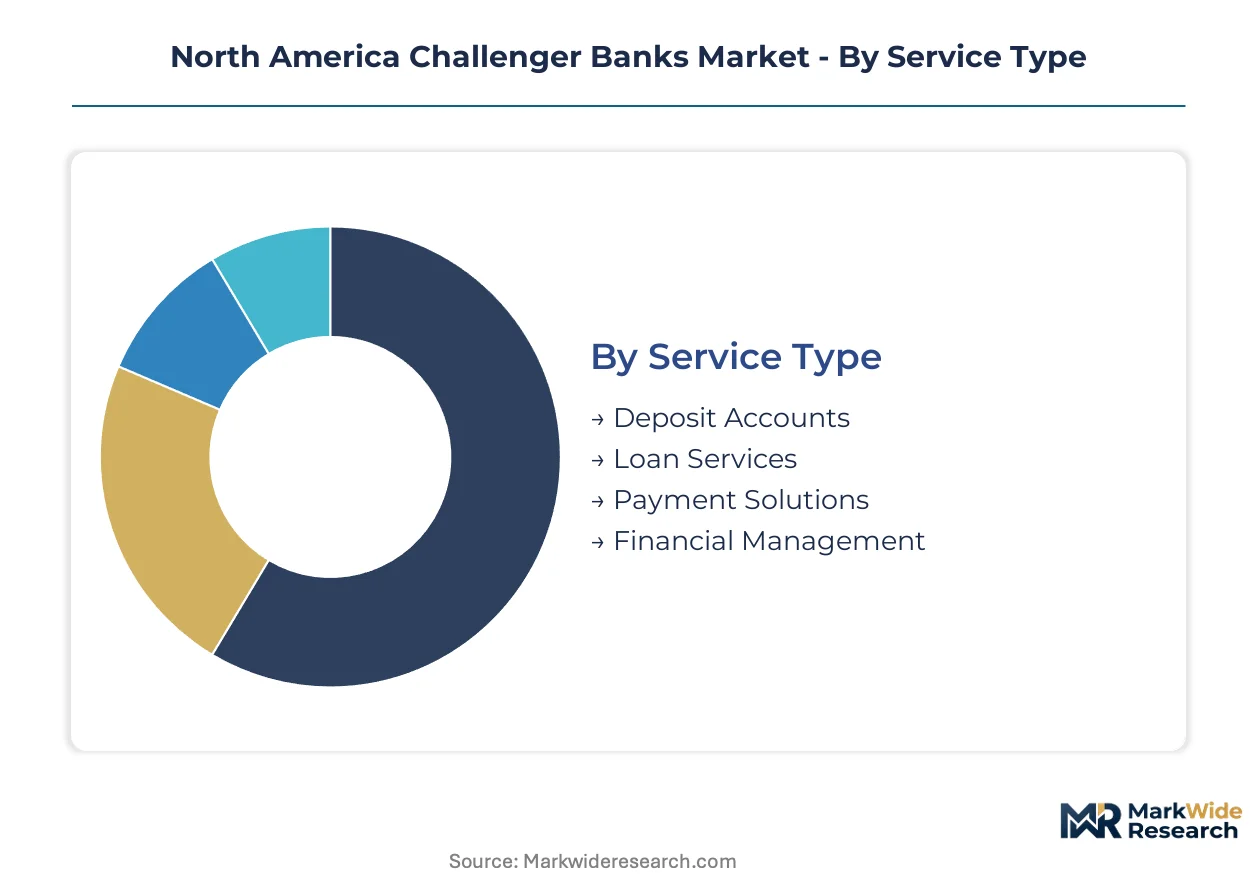
Segmentation in the North America challenger bank market reveals how digital-first institutions allocate capital across service lines and customer cohorts. Distinct technology stacks and regulatory requirements shape profitability profiles within each slice.
Service Type:
Deposit account services concentrate demand domestically across state-level markets, while payment solutions and cross-border lending capabilities increasingly serve export-oriented Canadian SMEs and US businesses with international supplier networks.
- Deposit Accounts:Core checking and savings products with FDIC insurance eligibility anchor customer acquisition in California and New York. Fee-free structures displace traditional branch-dependent models among wage-earning populations seeking reduced monthly maintenance costs.
- Loan Services:Installment lending and credit-builder products deploy alternative data underwriting for thin-file borrowers in Texas and Florida. Faster origination timelines compress the advantage held by legacy credit card issuers with manual review processes.
- Payment Solutions:Real-time transfer capabilities through FedNow integration serve domestic payroll and peer-to-peer use cases.
- Financial Management:API-embedded budgeting and savings automation tools integrate with employer wage systems.
Deposit accounts command the established base. The steepest expansion runs through payment solutions.
Customer Type:
Consumer segments drive volume through mobile-native onboarding, while SME and corporate relationships carry higher per-account revenue concentration and demand specialized treasury management APIs.
- Consumers:Individual depositors seeking fee elimination and faster fund access dominate account openings in dense urban corridors. Hourly workers in logistics and manufacturing sectors prioritize earned wage access integrations over traditional direct deposit.
- SMEs:Small and medium enterprises in California and New York demand faster loan origination and integrated accounting software connections than branch-dependent competitors deliver.
- Corporates:Larger enterprises require multi-user treasury controls and advanced API access for ERP integration.
- Freelancers:Independent contractors seek simplified tax withholding tools and irregular income smoothing products.
Consumer relationships anchor deposit scale. SME banking climbs the fastest as embedded finance partnerships proliferate.
Technology:
Mobile and cloud infrastructure represent mature deployment categories with concentrated vendor bases, while AI and blockchain implementations remain earlier-stage with higher customization requirements.
- Mobile Banking:Native iOS and Android applications serve as the primary customer interface, displacing web-first platforms. Biometric authentication and push notification features reduce friction for routine transactions among tech-savvy urban populations.
- Cloud Computing:Distributed core banking infrastructure on AWS, Azure, and Google Cloud enables elastic scaling without physical branch networks. Kubernetes orchestration demands scarce engineering talent that commands premium compensation in competitive labor markets.
- AI-Based Solutions:Machine learning models compress fraud detection and credit underwriting timelines.
- Blockchain Technology:Distributed ledger applications accelerate cross-border settlement and identity verification pilots.
Mobile banking holds the dominant share. AI-based solutions gain share fastest as regulatory clarity emerges for algorithmic lending decisions.
Offering:
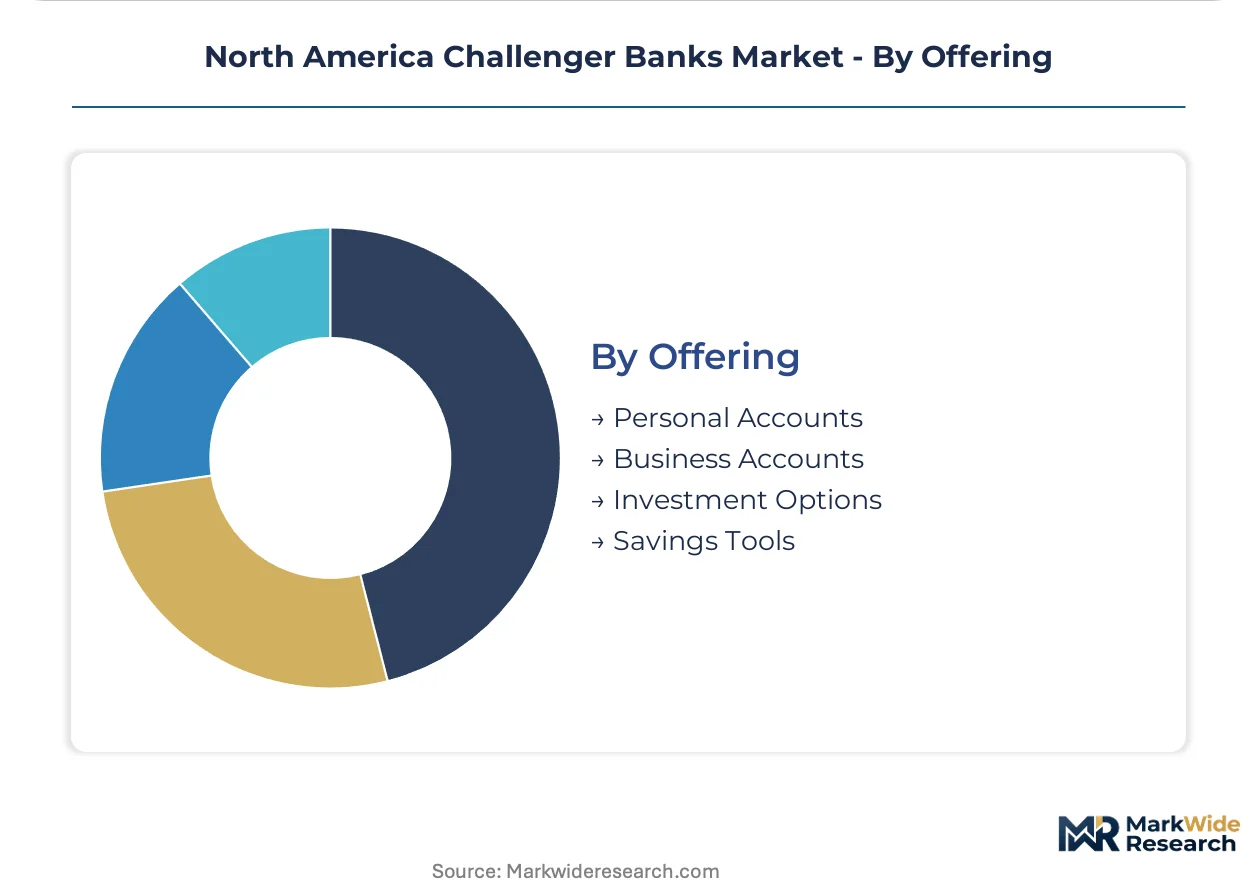
Personal account products saturate domestic markets with thin margins, while business accounts and investment verticals capture higher revenue per user through interchange and advisory fees.
- Personal Accounts:Individual checking and savings products with no minimum balance requirements drive mass-market acquisition. Chime Financial leverages first-mover scale to dominate fee-free positioning across the United States.
- Business Accounts:Commercial deposit and payment products for SMEs integrate with accounting platforms like QuickBooks and Xero. Canadian market entrants target property management and vertical SaaS distribution partnerships.
- Investment Options:Brokerage and retirement account integration extends share of wallet among high-earning professionals.
- Savings Tools:Automated round-up features and goal-based deposits compete with standalone budgeting applications.
Personal accounts generate the volume base. Business accounts expand most quickly as Banking-as-a-Service APIs penetrate vertical software platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and New York, where tech-savvy populations absorb premium digital banking features, while Texas and Florida compete on fee compression and credit-builder product penetration.
United States
The Consumer Financial Protection Bureau's evolving fintech oversight framework reshapes compliance requirements across state and federal jurisdictions. The Office of the Comptroller of the Currency governs national bank charter availability, while the Federal Deposit Insurance Corporation sets deposit insurance eligibility standards. California's dense startup ecosystem in San Francisco and Los Angeles drives account openings among high-earning professionals seeking integrated investment verticals.
Canada
Export-oriented small and medium enterprises in Ontario and British Columbia demand faster cross-border payment settlement than branch-dependent competitors deliver. Federal open banking mandates under the Department of Finance's consumer-directed finance framework standardize API access for account aggregation. Toronto's financial technology corridor anchors Banking-as-a-Service partnerships with vertical SaaS platforms serving property management and accounting software markets.
Mexico
Remittance-receiving households in Mexico City and Guadalajara seek real-time dollar-peso conversion through mobile-first platforms. The Comisión Nacional Bancaria y de Valores supervises fintech institution licensing under the 2018 Fintech Law. Northern border states concentrate demand for cross-border settlement pilots leveraging blockchain identity verification between United States payroll systems and Mexican deposit accounts.
North America Challenger Banks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America challenger bank landscape. Branchless operators scale customer acquisition through API-embedded distribution partnerships, while charter-holding institutions leverage insured deposit products to deepen primary banking relationships. The market structure bifurcates between fee-free consumer deposit specialists and integrated lending-investment platforms. Dominant competitive moves include strategic partnerships with payroll providers and embedded finance convergence through vertical SaaS integration.
Within the first-mover scale tier, Chime Financial, Inc. and Varo Bank, N.A. exemplify divergent regulatory strategies, with the former operating through partner bank arrangements and the latter holding a national bank charter. SoFi Bank, N.A. occupies a position among high-earning professional segments through integrated lending and investment verticals. These three entities represent the primary archetypes—scale-driven deposit acquisition, charter-anchored insured products, and share-of-wallet extension through financial services integration—that competitors must navigate against.
| Leading Market Players |
|---|
| Chime Financial, Inc. |
| Varo Bank, N.A. |
| SoFi Bank, N.A. |
| Ally Bank |
| MoneyLion Inc. |
| Aspiration Partners, Inc. |
| Current |
| Qapital, Inc. |
| Dave |
| Others |
Pricing and Supply Chain Analysis
Cloud-native core banking platforms displacing legacy on-premise infrastructure are redrawing supply geography toward AWS, Azure, and Google Cloud data centers while compressing pricing economics through API-embedded distribution partnerships that eliminate branch network overhead.
Pricing Analysis
The customization-premium spread separates standard mobile-first deposit accounts from configured SME treasury solutions with ERP integration. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by API access depth and after-sales service bundling. Pricing pressure stems from FedNow-enabled real-time payment commoditization. Hourly workers in logistics sectors exhibit highest price sensitivity, while high-earning professionals in New York absorb premium tiers.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning, while Ireland and Singapore host secondary data residency nodes for cross-border compliance. Raw material dependencies center on compute capacity, Kubernetes orchestration licenses, and biometric authentication modules. Single-source vulnerability concentrates in three dominant cloud providers. Distribution runs through API-embedded partnerships with payroll providers and vertical SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America challenger banking sits in early-cycle expansion as embedded finance partnerships with employer payroll systems accelerate deposit acquisition beyond traditional marketing channels.
For Market Incumbents: Fortify core deposit relationships by accelerating in-house production of AI underwriting engines, countering the origination speed advantage held by algorithmic-native entrants. Invest in FDIC examination readiness for third-party risk management, as regulatory scrutiny of API-dependent vendor ecosystems intensifies. Prioritize certification investment in state money transmitter licenses to preempt compliance fragmentation costs.
For New Entrants and Emerging Players: Earned wage access integrations for hourly manufacturing workers in Texas represent the most penetrable service-layer gap, as incumbents underserve irregular income smoothing needs. Target credit-builder products for thin-file borrowers in Florida through alternative data partnerships with property management platforms. Pursue Banking-as-a-Service distribution through vertical SaaS accounting software rather than direct consumer acquisition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed challengers holding national bank charters but subscale lending portfolios, where regulatory sunk costs create acquisition value. Five-to-ten year viability hinges on achieving primary banking status versus transactional account status. Watch pending federal fintech charter rulings as the inflection signal for algorithmic lending authorization scope.
| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Integration Completion | Real-time settlement capability eliminates legacy ACH float advantages for incumbents. |
| National Bank Charter Acquisition | FDIC insurance eligibility deepens primary banking relationships versus transactional usage. |
| Vertical SaaS Partnership | Embedded finance distribution through QuickBooks and Xero penetrates Canadian SME segments. |
| AI Underwriting Deployment | Neural network models compress fraud detection timelines below rule-based legacy thresholds. |
| Payroll API Integration | Wage deposit automation captures deposit growth among manufacturing and logistics employers. |
Research Methodology
The analysis maps deposit account services, payment solutions, loan origination platforms, and AI-based fraud detection systems, each validated through chief technology officers at cloud-native challengers, compliance officers at charter-holding institutions, and API product managers at Banking-as-a-Service providers. Primary interviews combined with secondary validation against SEC 10-K filings, FDIC call report data, Consumer Financial Protection Bureau enforcement actions, and FedNow adoption disclosures. Bottom-up account volume projections triangulated against top-down deposit market sizing.
Consistency checks validated model outputs against external benchmarks across the projection horizon, with segmentation dimensions covering service type, customer tier, technology deployment, and regulatory charter status. CAGRs derived from historical deposit growth trajectories and penetration rate assumptions. Forecast inputs incorporated FedNow rollout velocity and state-level open banking mandate progression.
Underlying assumptions cover interest rate stability, cloud vendor pricing continuity, and regulatory charter availability, with deviation risk concentrated in federal fintech charter rulings and state money transmitter enforcement shifts. Recalibration cycles align with material shifts in CFPB oversight frameworks and FedNow network participation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Automated Teller Machine (ATM) Market
Banking
Global Chatbot for Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Global Certificate of Deposit Market
Banking
Banking Smart Cards Market
Banking
Performance Bank Guarantee Market
Banking
Banking CRM Software Market
Banking
Europe Banking-As-A-Service Market
Banking
Cloud Computing Banking Market
Banking
Europe Machine Learning in Banking Market
Banking
Latin America Banking As a Service Market
Banking
Investment Banking Market
Banking
Retail Banking Market
Banking
Banking Tax Management Software Market
Banking
Cardless ATM Market
Banking
Bank Management Software Market