
 Debt Settlement Solution Market | 2026-2036
Debt Settlement Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Debt Settlement Solution Market Insights
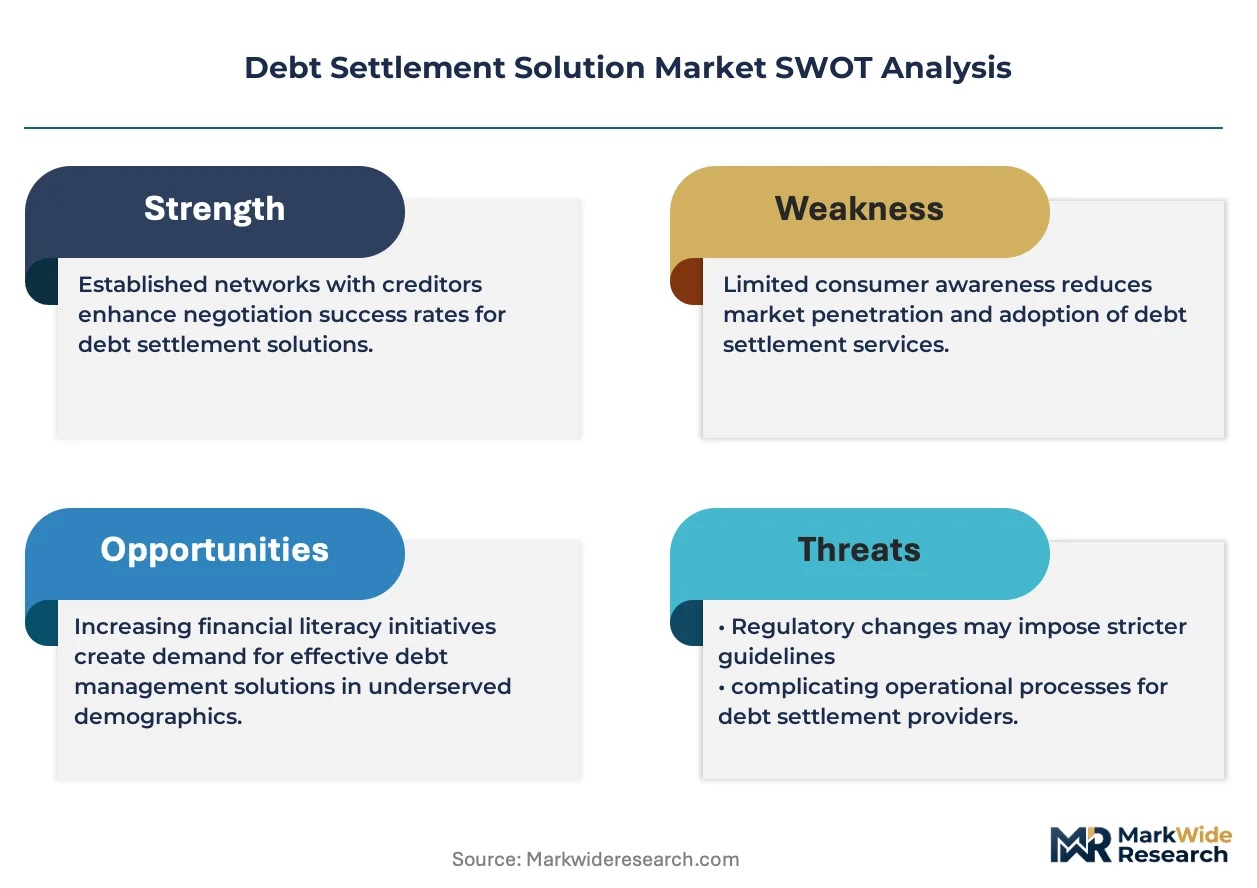
A shortage of certified debt arbitrators is unwinding service capacity across the industry. National Debt Relief leverages its licensed negotiator network to sustain volume throughput in high-delinquency corridors. Freedom Debt Relief anchors its competitive position through proprietary creditor relationship databases that accelerate settlement timelines. ClearOne Advantage specializes in hybrid coaching models that differentiate its consumer retention rates.
Debt settlement solutions encompass negotiated reduction programs where third-party intermediaries arrange lump-sum payoffs at less than full balance owed, typically charging fees of 15-25% of enrolled debt upon successful resolution. The primary commercial purpose centers on providing structured relief pathways for consumers facing unmanageable unsecured obligations while generating fee-based revenue from savings achieved. Negotiation services dominate current revenue composition due to established creditor protocols and predictable fee realization, while cloud-based deployment represents the fastest-expanding structural segment as providers migrate client dashboards and document workflows to scalable infrastructure. Software solutions within the offering dimension command premium positioning through automated creditor matching algorithms and real-time settlement tracking portals.
The Consumer Financial Protection Bureau enforces fee-timing restrictions under Telemarketing Sales Rule amendments that prohibit advance collection before settlement execution, directly constraining provider cash flow models and forcing working capital restructuring. State-level licensing regimes administered by attorneys general offices in New York, Texas, and California impose bonding requirements and disclosure mandates that shape market access thresholds for new entrants. Stakeholders must monitor evolving state preemption debates and federal pre-rulemaking signals to calibrate compliance investment against geographic expansion priorities.
Market Dynamics
The Consumer Financial Protection Bureau's Telemarketing Sales Rule amendments are forcing debt settlement providers to restructure cash flow models by prohibiting advance fee collection, fundamentally altering working capital requirements and competitive positioning across the industry.
Growth Catalysts
- CFPB Fee-Timing Restrictions:Regulatory clarity under Telemarketing Sales Rule amendments is consolidating the provider base by eliminating non-compliant operators, creating market share capture opportunities for licensed intermediaries.
- Cloud Migration:Scalable infrastructure deployment is reducing client onboarding costs and enabling real-time settlement tracking portals that accelerate consumer enrollment velocity.
- Credit Card Delinquency Concentration:Household debt-to-income stress in high-cost corridors is sustaining inbound demand for negotiated relief services among unsecured obligation holders.
Market Restraints
- Certified Arbitrator Scarcity:Limited supply of licensed debt negotiators is constraining service throughput capacity and extending settlement timelines for enrolled consumers.
- State Bonding Requirements:Attorneys general licensing regimes in New York, Texas, and California impose capital-intensive entry barriers that fragment provider geographic coverage.
- Automated Underwriting Substitution:Direct creditor hardship programs and balance transfer products are capturing marginal relief-seekers before third-party intervention.
Strategic Opportunities
- Hybrid Coaching Models:Financial wellness integration is differentiating retention rates by combining negotiation services with behavioral coaching and budget restructuring.
- Proprietary Creditor Databases:Relationship intelligence systems that accelerate settlement timelines represent defensible competitive moats against commoditized fee competition.
- State Preemption Clarity:Evolving federal-state regulatory alignment debates may streamline multi-jurisdictional operating authority for compliant providers.
Industry Challenges
- Compliance Talent Acquisition:Shortage of regulatory counsel familiar with CFPB enforcement patterns and state attorney general protocols is elevating legal overhead costs.
- Legacy System Integration:Established providers face technical debt burdens when migrating client dashboards and document workflows to cloud-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Debt Settlement Solution Market |
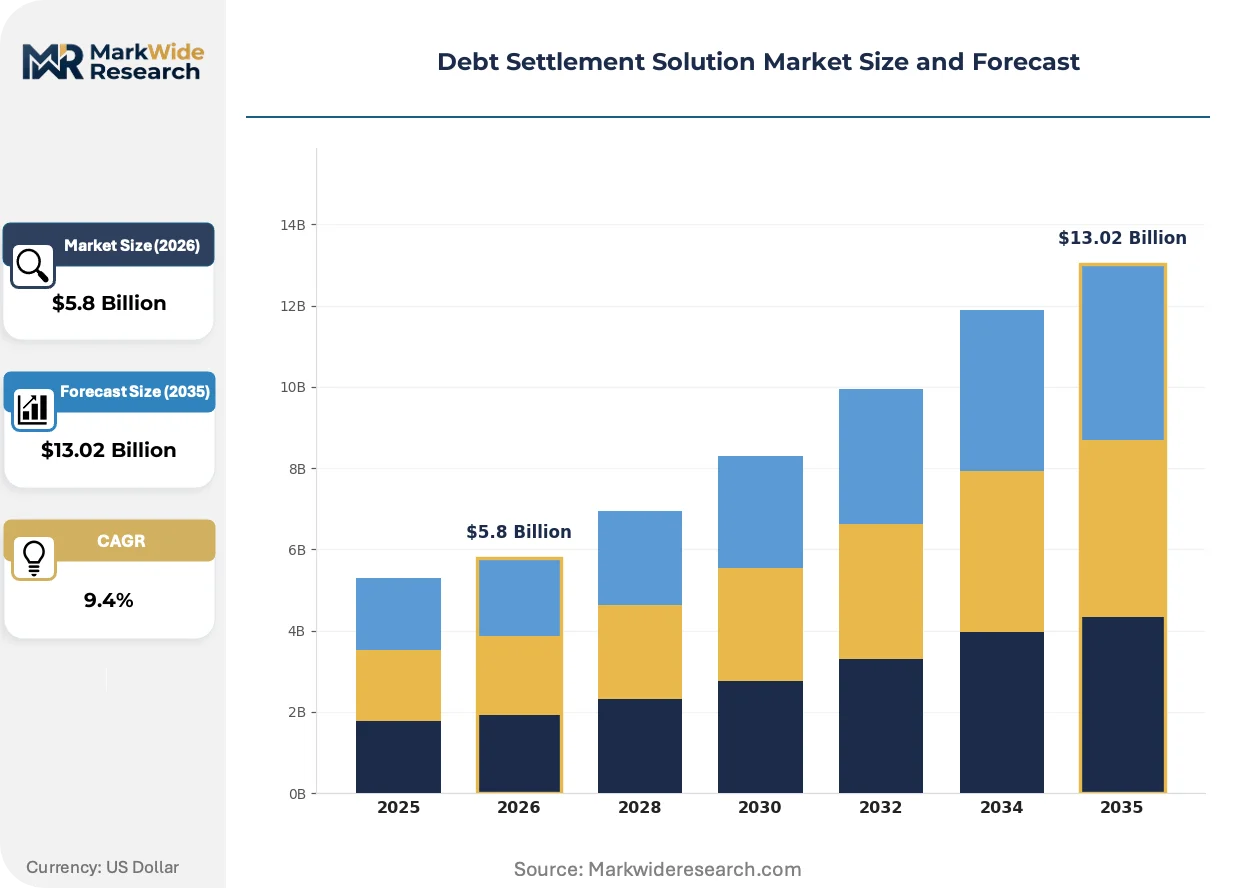
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Negotiation, Direct Settlement, Payment Plan, Legal Representation End User: Consumers, Small Businesses, Creditors, Financial Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Remote Access Offering: Consultation Services, Software Solutions, Educational Resources, Support Programs |
| Companies Covered | Freedom Debt Relief, National Debt Relief, Accredited Debt Relief, United Debt Relief, Rescue One Financial, ClearOne Advantage, DebtBlue, Guardian Debt Relief, Pacific Debt Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debt Settlement Solution Market Trends and Innovations
Automation is penetrating debt settlement operations through three converging vectors: algorithmic creditor matching, real-time consumer portals, and predictive settlement modeling. These forces are compressing negotiation cycles and elevating transparency expectations.
Automated creditor matching algorithms are supplanting manual negotiator assignment processes in high-volume enrollment operations. Mid-tier providers with five-thousand-plus active accounts are adopting these systems fastest. The technology is compressing settlement timeline variance and reducing per-case labor intensity.
The Consumer Financial Protection Bureau continues tightening fee disclosure mandates through consent order precedents and examination guidance. Providers now face mandatory savings estimates and outcome probability disclosures before consumer enrollment. The compliance investment burden falls heaviest on sub-scale operators lacking dedicated legal infrastructure.
Direct-to-consumer digital channels are displacing traditional affiliate referral networks as the primary enrollment pathway. Mobile-optimized application flows and e-signature document completion are reducing friction in the enrollment funnel. This shift is most visible among households aged thirty-five to fifty-four seeking relief from credit card obligations.
Debt Settlement Solution Market Segmentation
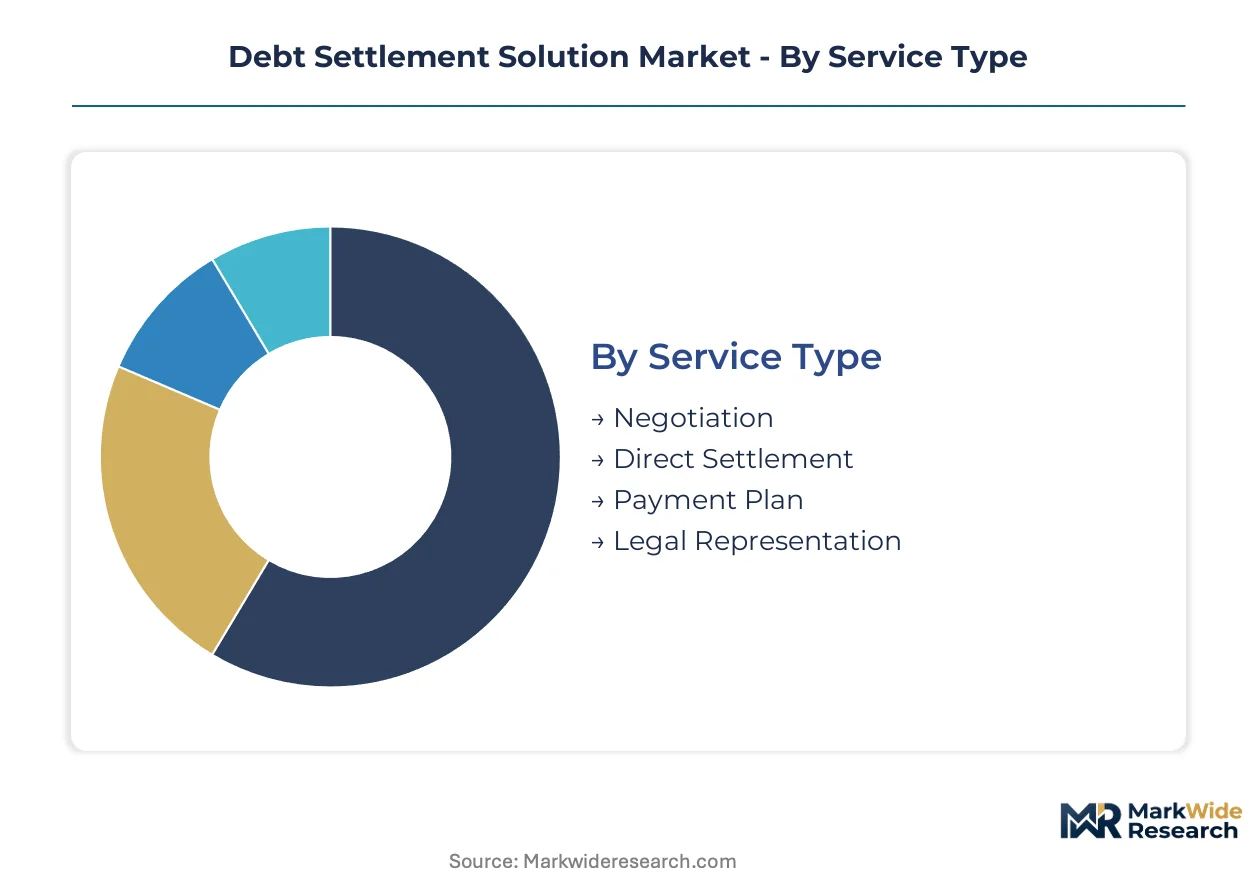
Segmentation in debt settlement solutions reveals distinct operational models and customer acquisition pathways. Service configuration and delivery infrastructure shape competitive differentiation and margin structure across provider tiers.
Service Type:
Geographic concentration varies sharply by service model, with negotiation-heavy offerings anchored in high-delinquency domestic corridors while legal representation clusters in states with aggressive creditor litigation environments.
- Negotiation:Third-party intermediaries arrange lump-sum payoffs at reduced balances, typically charging 15-25% of enrolled debt upon resolution. Demand concentrates in United States households facing credit card burdens, with CFPB fee-timing restrictions constraining provider cash flow models.
- Direct Settlement:Consumers negotiate directly with creditors without intermediary involvement, bypassing service fees entirely. This segment attracts digitally literate debtors in high-income corridors where creditor hardship portals have proliferated.
- Payment Plan:Structured installment arrangements spread reduced obligations over extended timelines.
- Legal Representation:Attorney-led negotiation and litigation defense services.
Negotiation commands the established base. The steepest expansion runs through Direct Settlement.
End User:
Customer type determines pricing architecture and retention engineering, with consumer-facing providers optimizing for enrollment velocity while institutional clients demand outcome-based fee structures.
- Consumers:Individual households seeking relief from unsecured obligations, primarily credit card and medical debt. Enrollment velocity accelerates through mobile-optimized application flows targeting households aged thirty-five to fifty-four.
- Small Businesses:Commercial entities facing trade credit and equipment financing distress. Demand clusters in service-sector corridors where pandemic-era obligations have matured into delinquency.
- Creditors:Financial institutions outsourcing recovery operations on charged-off portfolios.
- Financial Institutions:Banks and credit unions seeking white-label settlement infrastructure.
Consumers anchor volume throughput. Small Businesses represent the fastest-climbing customer tier.
Deployment:
Infrastructure choices separate legacy operators from cloud-native entrants, with capital requirements and scalability ceilings diverging sharply across deployment modes.
- Cloud-Based:Scalable infrastructure enabling real-time settlement tracking portals and automated document workflows. Providers migrate client dashboards to cloud architectures to reduce onboarding friction and accelerate enrollment velocity.
- Hybrid:Mixed on-premises and cloud infrastructure serving mid-tier providers with compliance-sensitive data residency requirements. Deployment concentrates among established operators navigating legacy system integration burdens.
- On-Premises:Self-hosted infrastructure with full data control.
- Remote Access:Thin-client configurations for distributed negotiator workforces.
Hybrid deployments retain the incumbent base. Cloud-Based infrastructure gains share fastest.
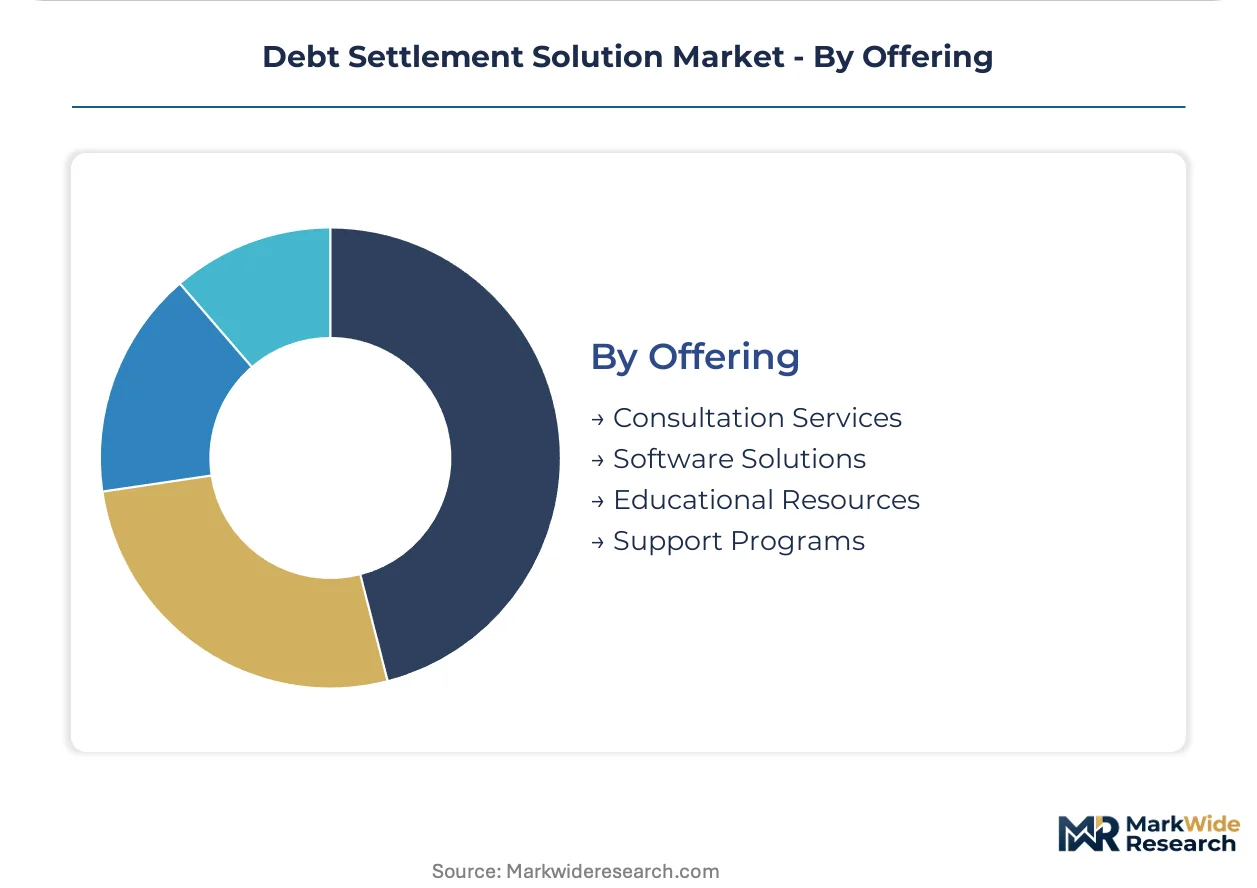
Offering:
Product architecture distinguishes fee-based service providers from technology licensors, with margin profiles and capital intensity varying substantially across offering types.
- Software Solutions:Automated creditor matching algorithms and real-time settlement tracking portals command premium positioning. Demand concentrates among mid-tier providers seeking to compress negotiation cycles and reduce per-case labor intensity.
- Consultation Services:Personalized debt assessment and enrollment counseling. Providers combine negotiation with behavioral coaching to differentiate retention rates in competitive consumer corridors.
- Educational Resources:Self-service financial literacy content and budgeting tools.
- Support Programs:Ongoing account management and post-settlement credit rehabilitation.
Consultation Services hold the revenue base. Software Solutions expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Debt settlement consumption patterns diverge sharply across geographies, with the United States exhibiting the deepest reliance on third-party negotiation intermediaries while Canada and Australia show stronger preference for direct creditor hardship programs and government-administered relief frameworks.
United States
Household credit card delinquencies and medical debt burdens drive sustained demand for negotiated relief services. The Consumer Financial Protection Bureau enforces Telemarketing Sales Rule amendments that prohibit advance fee collection, forcing providers to restructure working capital models. Service concentration clusters in California, Texas, and New York, where state attorneys general administer bonding requirements and disclosure mandates that shape market access thresholds.
Canada
Consumer insolvency filings and unsecured debt stress sustain demand for structured settlement pathways. The Office of the Superintendent of Bankruptcy oversees federally regulated insolvency proceedings that compete with private settlement services. Toronto and Vancouver anchor provider activity, where licensed insolvency trustees and credit counseling agencies operate alongside emerging digital settlement platforms.
United Kingdom
Individual voluntary arrangements and debt management plans capture relief-seeking households facing unsecured obligations. The Financial Conduct Authority regulates debt advice and insolvency practitioners through permissioning requirements and conduct standards. London and the Southeast concentrate licensed insolvency practitioner activity, while regional hubs in Manchester and Birmingham sustain mid-tier provider operations.
Australia
Personal insolvency agreements and informal debt settlements address household financial distress amid rising cost-of-living pressures. The Australian Financial Security Authority administers bankruptcy and personal insolvency agreement frameworks that interface with private settlement services. Sydney and Melbourne host the bulk of registered debt agreement administrators, with Brisbane emerging as a secondary concentration for digital-first relief providers.
Germany
Consumer insolvency proceedings under the Insolvency Code provide structured debt discharge pathways for over-indebted households. The Federal Financial Supervisory Authority oversees credit institutions and payment service providers with indirect implications for settlement intermediaries. Frankfurt and Munich concentrate legal services specializing in insolvency proceedings, while Berlin sustains a growing ecosystem of fintech-enabled debt counseling platforms.
Debt Settlement Solution Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the debt settlement market structure. The upper tier comprises full-service providers with proprietary creditor relationship databases and licensed negotiator networks that sustain volume throughput across high-delinquency corridors. The specialist tier includes hybrid coaching operators and technology-leaning platforms that differentiate through behavioral intervention models and automated settlement tracking. Strategic consolidation and cloud infrastructure migration represent the dominant competitive moves reshaping provider positioning.
Within the integrated leader tier, Freedom Debt Relief and National Debt Relief exemplify scale-driven operators with established creditor protocols. ClearOne Advantage occupies a position within the specialist tier, representing hybrid coaching models that combine negotiation services with financial wellness integration. These three companies anchor the competitive spectrum from volume-focused settlement factories to retention-optimized coaching platforms.
| Leading Market Players |
|---|
| Freedom Debt Relief |
| National Debt Relief |
| Accredited Debt Relief |
| United Debt Relief |
| Rescue One Financial |
| ClearOne Advantage |
| DebtBlue |
| Guardian Debt Relief |
| Pacific Debt Inc |
| Others |
Pricing and Supply Chain Analysis
CFPB fee-timing restrictions under Telemarketing Sales Rule amendments gate both provider licensing qualification and price differentiation simultaneously, as compliant operators command premium positioning while non-compliant competitors face forced exit or working capital restructuring that compresses their pricing flexibility.
Pricing Analysis
Success-based fee contracts dominate the market structure, with providers charging 15-25% of enrolled debt upon settlement execution rather than advance collection. Price differentiation rests on licensed negotiator network scale and proprietary creditor relationship depth, with established operators capturing premium fees while commoditized entrants compete on lower percentages. Cost compression in the mid-tier is intensifying because cloud-native platforms reduce per-case labor intensity. Small businesses show highest price sensitivity, while distressed consumers facing imminent litigation prioritize speed over fee minimization.
Supply Chain Analysis
Minimal physical inventory requirements and digital service delivery compress lead times to near-zero for cloud-native providers, though legacy operators carry technical debt burdens that extend system migration timelines. Service delivery draws from licensed debt arbitrators concentrated in the United States, with technology infrastructure sourcing from domestic cloud providers and specialized fintech development shops. Single-source vulnerability sits with certified negotiator scarcity constraining service throughput. Distribution runs through direct-to-consumer digital channels displacing traditional affiliate referral networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Debt settlement solutions function as a service-attach opportunity where ongoing financial wellness coaching and credit rehabilitation programs expand faster than core negotiation fees, creating recurring revenue layers that improve lifetime customer value metrics.
For Market Incumbents: Secure proprietary creditor relationship databases as defensive moats against automated underwriting substitution threatening marginal relief-seekers. Deepen vertical integration into hybrid coaching models combining negotiation with behavioral intervention to differentiate retention rates against cloud-native entrants. Lock in certified arbitrator pipelines through licensed training partnerships to preempt talent scarcity constraining volume throughput.
For New Entrants and Emerging Players: Differentiate on financial wellness integration targeting households aged thirty-five to fifty-four through mobile-optimized enrollment flows and real-time settlement tracking portals. White-label settlement infrastructure to financial institutions seeking outsourced recovery operations represents the most penetrable B2B entry path. Lead with outcome-based fee structures that align provider incentives with consumer savings realization.
For Investors and Strategic Acquirers: CFPB enforcement pattern clarity reshapes the acquisition landscape by elevating compliance infrastructure value and eliminating non-compliant target pools. Long-term viability centers on providers with cloud-native architectures and licensed multi-state operating authority capable of scaling across high-delinquency corridors. Watch state preemption debates as the signal indicating geographic expansion cost trajectories for platform rollups.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Migration | Reduces client onboarding friction and accelerates enrollment velocity through scalable architecture. |
| Licensed Arbitrator Network Expansion | Addresses certified negotiator scarcity constraining settlement timeline compression and service throughput. |
| Proprietary Creditor Database Development | Accelerates settlement timelines through relationship intelligence systems that defy commoditization. |
| Hybrid Coaching Model Integration | Combines negotiation services with behavioral intervention to differentiate consumer retention rates. |
| Multi-State Licensing Compliance Investment | Navigates attorneys general bonding requirements in California, Texas, and New York to unlock geographic coverage. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with debt settlement executives, licensed negotiators, CFPB regulatory counsel, and creditor recovery officers; alongside secondary validation drawing from CFPB consent orders, state attorney general licensing databases, SEC filings of publicly traded providers, and consumer insolvency filing statistics. Bottom-up enrollment volume estimates triangulated against top-down addressable market sizing across service type, deployment mode, and end-user segments.
Across the analysis window, the forecasting framework modeled revenue trajectories by service configuration, delivery infrastructure, and geographic regulatory cluster. CAGRs derived from enrollment velocity assumptions tied to household debt-to-income stress indicators and creditor collection practice intensity. Cloud adoption curves and fee-timing restriction compliance costs fed directly into margin compression modeling for provider tier stratification.
Material uncertainties — CFPB rulemaking evolution, state preemption litigation outcomes, and certified arbitrator supply elasticity — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement continuity and consumer credit cycle positioning. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Global Alternative Data Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Financial Services Application Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Banking Cloud Services Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Europe E-Invoicing Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
E-Brokerage Market
Financial Services
Silver Economy Market
Financial Services
North America Trade Finance Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Saas Escrow Services Market
Financial Services
Intermediary Service Market