
 Japan Data Analytics in Banking Market | 2026-2036
Japan Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Analytics in Banking Market Insights
Platform licensing revenue from proprietary analytics engines is tilting away from one-time implementation fees toward recurring subscription models. NTT DATA leverages its deep integration with domestic core banking systems to sustain long-term client relationships across regional and megabank tiers. MUFG anchors its competitive stance through in-house development of AI-driven risk scoring tools that reduce manual underwriting overhead. Mizuho Financial Group competes by embedding analytics directly into customer-facing mobile applications, shortening feedback loops between data generation and actionable insight.
Data analytics in banking encompasses the systematic extraction, processing, and modeling of structured and unstructured financial data to generate predictive insights, optimize decision workflows, and automate regulatory reporting at throughput rates exceeding traditional SQL-based systems. The technology serves primarily to reduce operational latency in credit adjudication, enhance detection precision in anti-money laundering surveillance, and enable dynamic personalization of deposit and lending products. Predictive Analytics and AI segments currently capture the most intensive R&D allocation as institutions pursue sub-second anomaly detection in payment networks. Fraud Detection applications lead deployment velocity, though Regulatory Compliance solutions command superior margin profiles due to mandatory refresh cycles tied to FSA rule updates. Managed Services within the service-type dimension is expanding fastest as smaller banks outsource data lake maintenance and model governance to specialized vendors rather than building captive capabilities.
Japan's Financial Services Agency (FSA), the Personal Information Protection Commission (PPC), and the Bank of Japan's FinTech Innovation Hub collectively shape market access through mandates on algorithmic transparency, cross-border data localization, and stress-testing protocols for AI credit models. METI's guidance on trustworthy AI and the JIS Q 15001 privacy management standard further constrain vendor architectures, favoring domestic providers with established compliance track records. Stakeholders must monitor evolving FSA expectations on model explainability and third-party risk management as these will determine which analytics platforms achieve procurement approval across Japan's consolidated banking sector.
Market Dynamics
Japan's megabanks are dismantling siloed data architectures under pressure from FSA explainability mandates, forcing wholesale replacement of legacy batch-processing systems with real-time streaming infrastructure that can audit algorithmic decisions at transaction speed.
Growth Catalysts
- FSA AI Explainability Guidelines:Mandatory disclosure requirements for credit-scoring algorithms are accelerating procurement of interpretable machine learning platforms across Tokyo-based retail banking networks.
- Real-Time Payment Networks:The Bank of Japan's FinTech Innovation Hub pilot programs are normalizing sub-second anomaly detection as a baseline operational requirement for payment processors.
- Regional Bank Consolidation:Post-merger integration of data lakes across Fukuoka and Osaka banking clusters is generating concentrated demand for unified analytics governance platforms.
Market Restraints
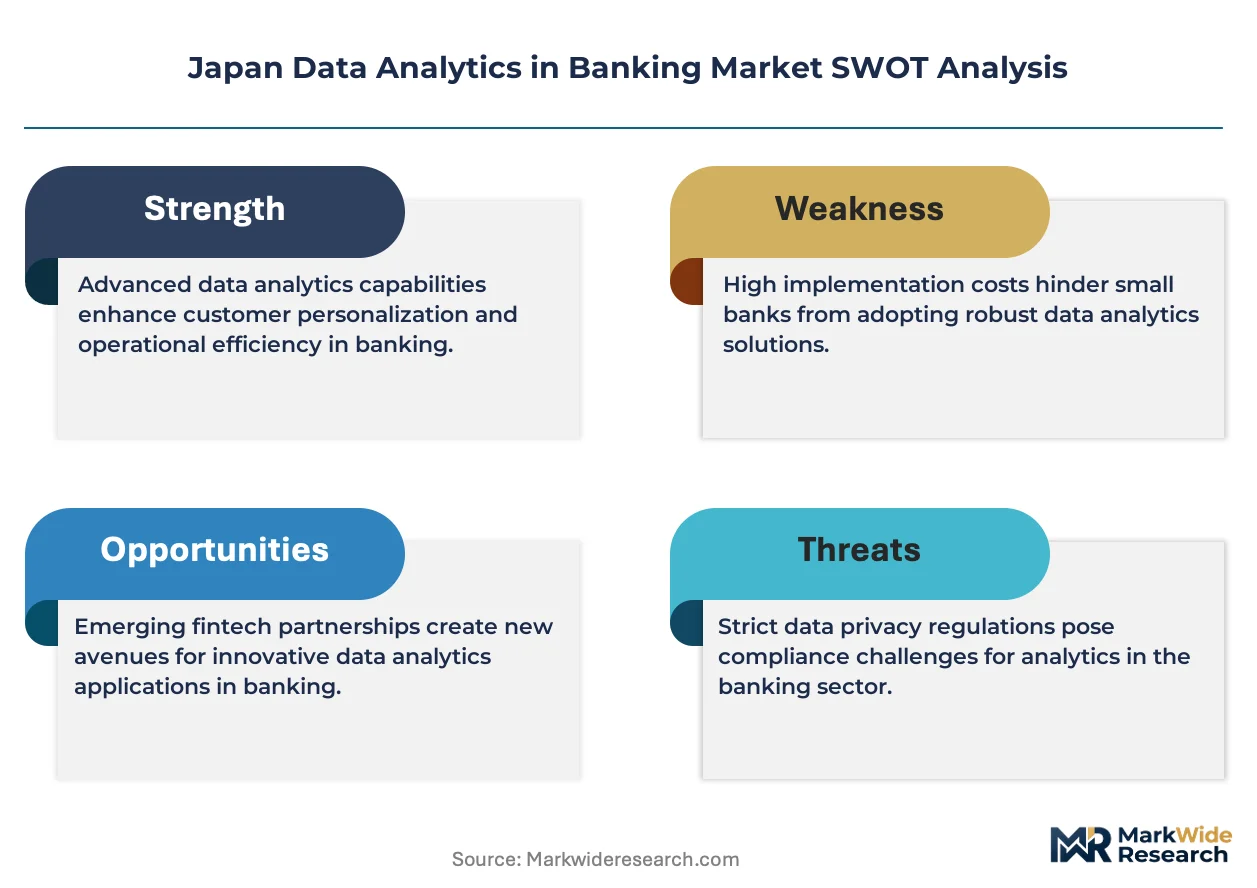
- Domestic Vendor Concentration:NTT DATA's entrenched position in core banking system integration creates switching friction for institutions seeking alternative analytics providers.
- JIS Q 15001 Compliance Burden:Privacy management certification timelines extend vendor onboarding cycles by 8-14 months, compressing effective contract windows.
- Specialized Talent Scarcity:The domestic labor pool for bilingual model risk engineers remains insufficient relative to deployment pipelines at tier-2 regional banks.
Strategic Opportunities
- Wealth Management Personalization:Untapped deployment of behavioral analytics in Hokkaido and Tohoku regional markets offers first-mover positioning ahead of megabank expansion.
- Regulatory Technology Convergence:Integration of METI trustworthy-AI frameworks with automated stress-testing protocols creates bundled compliance-analytics offerings for smaller institutions.
- Managed Services Outsourcing:Data lake maintenance and model governance functions present recurring revenue streams as regional banks abandon captive capability builds.
Industry Challenges
- Core System Modernization Complexity:Decades-old mainframe dependencies at major institutions obstruct API-native analytics integration without parallel infrastructure investment.
- Cross-Border Data Localization:PPC restrictions on offshore model training data complicate hybrid cloud deployments for institutions with international operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Analytics in Banking Market |
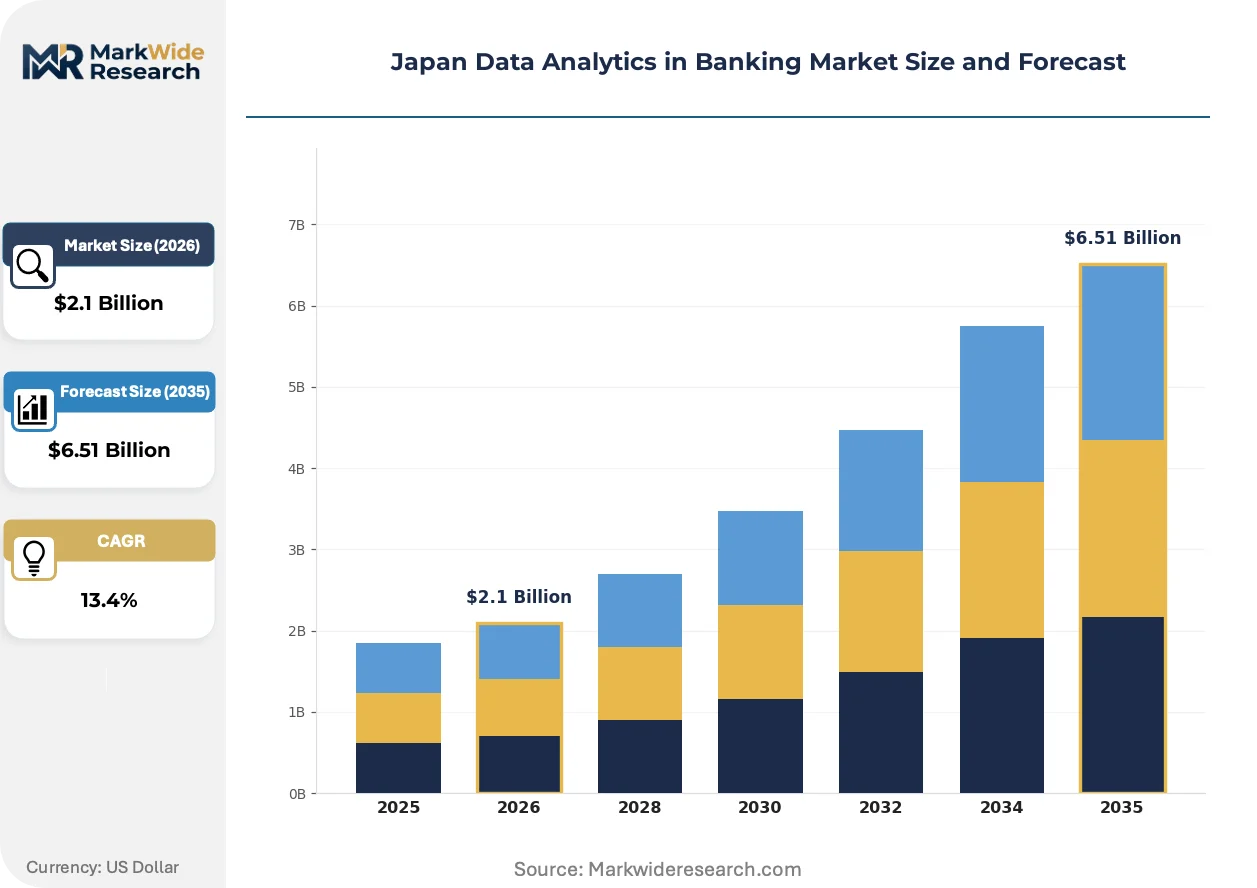
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.51 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Machine Learning, Business Intelligence, Predictive Analytics Application: Fraud Detection, Risk Management, Customer Segmentation, Regulatory Compliance Service Type: Consulting, Integration, Managed Services, Support End User: Retail Banks, Investment Banks, Credit Unions, Cooperative Banks |
| Companies Covered | NTT DATA, Finatext Ltd., SDKI Analytics, MUFG, Mizuho Financial Group, SMBC, SBI Holdings, Sumitomo Mitsui Financial Group, Resona Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Analytics in Banking Market Trends and Innovations
Three intersecting forces are compressing deployment timelines and redefining vendor value propositions across Japan's banking analytics landscape. Technology architectures are converging with regulatory mandates while buyer procurement patterns undergo structural revision.
Explainable AI (XAI) frameworks are hybridizing with traditional statistical credit models to satisfy FSA audit requirements without sacrificing predictive accuracy. Regional banks in Osaka and Nagoya are adopting these hybrid architectures faster than Tokyo-headquartered megabanks due to lighter technical debt burdens. The structural consequence is collapsing the historical trade-off between model performance and regulatory defensibility.
METI's trustworthy-AI guidance is hardening into de facto procurement standards that disqualify opaque black-box algorithms from institutional consideration. Vendors must now document training data lineage and decision-boundary logic prior to contract award. Compliance-focused solution bundles are commanding premium positioning in RFP evaluations across the consolidated banking sector.
Subscription-based platform licensing is displacing perpetual implementation contracts as the dominant commercial structure. Megabanks are unbundling analytics procurement from core system overhauls, shortening vendor selection cycles from 18-month transformations to 6-month capability pilots. This behavioral shift is most visible among institutions pursuing modular fraud detection upgrades independent of broader infrastructure refresh programs.
Japan Data Analytics in Banking Market Segmentation
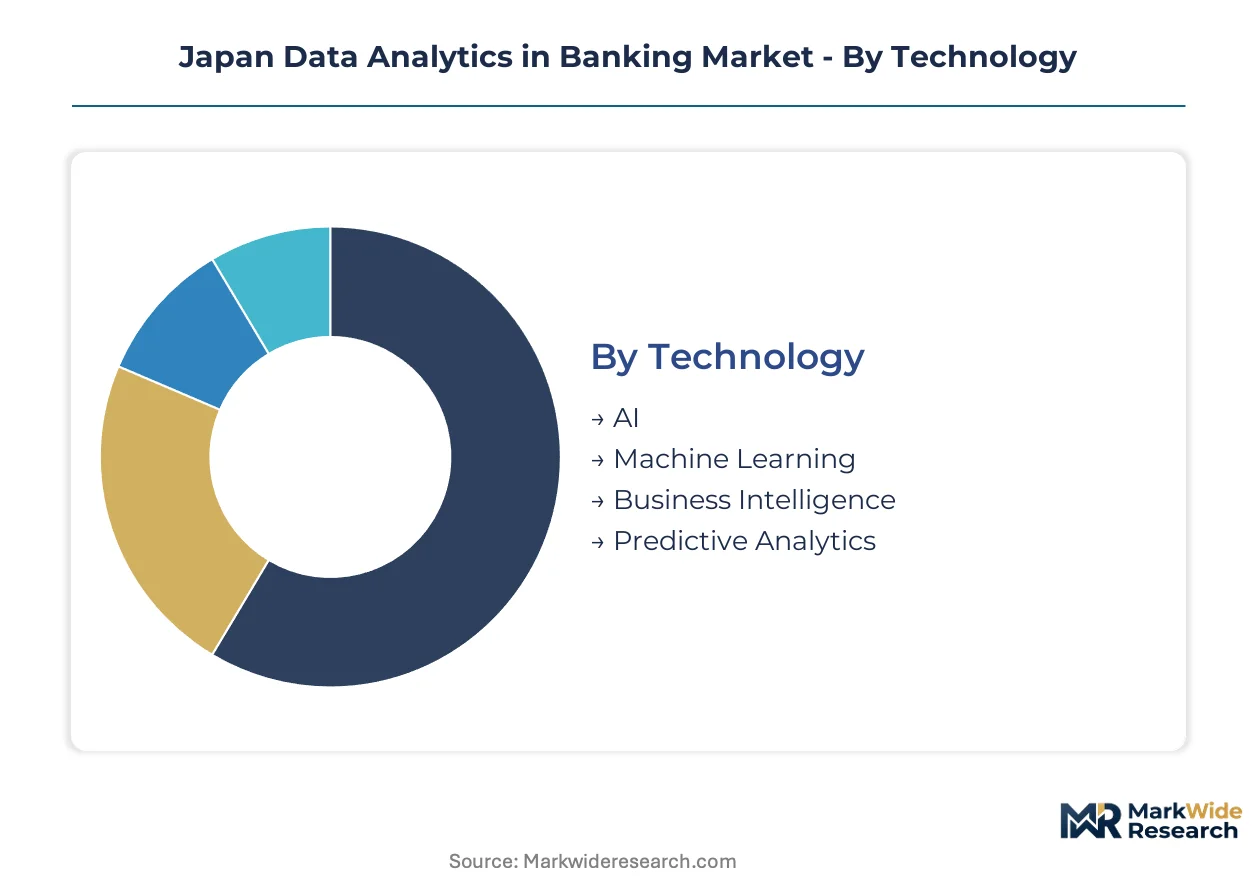
Segmentation reveals how procurement patterns diverge across Japan's banking tiers. Megabanks prioritize real-time infrastructure while regional institutions favor outsourced governance models. Understanding these fault lines exposes where vendor specialization creates durable competitive moats.
Technology:
Mature platforms dominate installed base while emerging architectures capture incremental investment cycles.
- Predictive Analytics:Statistical modeling engines process structured transaction histories to forecast credit defaults and liquidity stress scenarios. Tokyo-based retail banks deploy these systems for real-time underwriting decisions under FSA explainability mandates. The technology reduces manual adjudication latency from days to minutes.
- AI:Neural network architectures automate pattern recognition across unstructured data streams including voice logs, document scans, and behavioral biometrics. Osaka and Fukuoka banking clusters lead deployment for payment anomaly detection. Regulatory pressure for algorithmic audit trails accelerates procurement of interpretable variants.
- Machine Learning:Supervised learning pipelines refine risk scoring models through continuous feedback loops on loan performance outcomes.
- Business Intelligence:Dashboard-centric visualization tools aggregate operational metrics for executive reporting and branch-level performance management.
Predictive Analytics retains volume leadership; AI holds the steepest expansion curve.
Application:
Cost-tier differentiation separates mandatory compliance spend from discretionary innovation budgets.
- Fraud Detection:Real-time transaction monitoring systems flag anomalous payment patterns through velocity checks, geolocation cross-referencing, and device fingerprinting. Megabanks across Tokyo deploy sub-second detection as baseline infrastructure. The Bank of Japan's FinTech Innovation Hub pilots normalize this capability as operational standard.
- Regulatory Compliance:Automated reporting engines map transactional data to FSA submission formats while maintaining audit trails for model governance. Regional banks in Hokkaido and Tohoku outsource these functions to specialized vendors. Mandatory refresh cycles tied to rule updates generate recurring revenue streams.
- Risk Management:Integrated platforms quantify credit, market, and operational risk exposures through stress-testing simulations.
- Customer Segmentation:Behavioral clustering algorithms identify deposit and lending product affinity patterns for targeted marketing.
Fraud Detection commands the largest installed base; Regulatory Compliance generates superior margin profiles.
Service Type:
Customer-type stratification distinguishes between institutions building captive capabilities versus those purchasing outcomes.
- Managed Services:Comprehensive outsourcing arrangements cover data lake maintenance, model retraining, and governance documentation for institutions lacking internal technical depth. Tier-2 regional banks in Nagoya and Kobe favor this model to bypass talent scarcity constraints. Subscription structures align vendor incentives with operational uptime guarantees.
- Consulting:Advisory engagements assess legacy system readiness, define analytics roadmaps, and structure vendor selection processes. Megabanks deploy these services for parallel infrastructure planning during core system overhauls. engagements typically precede implementation contracts by 6-12 months.
- Integration:Technical services connecting analytics platforms to existing core banking systems through API development and data pipeline construction.
- Support:Ongoing maintenance contracts covering bug resolution, security patching, and user training delivery.
Managed Services is gaining share fastest; Integration captures the largest project values.
End User:
Geographic concentration patterns mirror Japan's urban economic hierarchy and banking consolidation timeline.
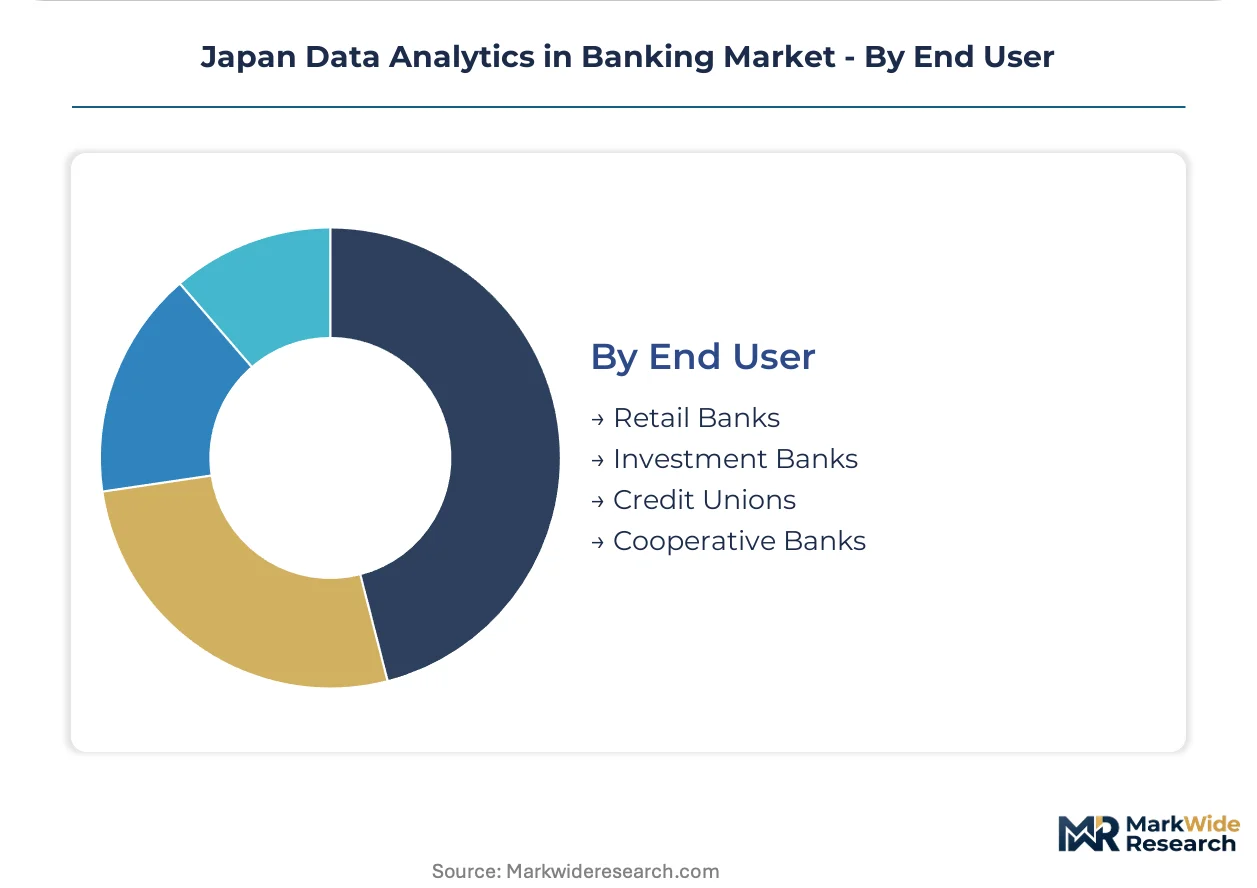
- Retail Banks:Full-service deposit and lending institutions serving consumer and small-business segments through branch networks and digital channels. Megabanks headquartered in Tokyo anchor demand for personalized wealth management platforms. Post-merger integration across Fukuoka and Osaka clusters drives unified analytics governance procurement.
- Credit Unions:Member-owned cooperative institutions with limited technical staff and constrained capital expenditure budgets. Institutions in rural prefectures prioritize compliance automation over predictive capabilities. Shared service arrangements allow collective vendor negotiations.
- Investment Banks:Securities underwriting and trading operations requiring real-time market risk analytics.
- Cooperative Banks:Agricultural and commercial cooperatives with specialized lending mandates and localized membership bases.
Retail Banks dominate absolute spending; Credit Unions present the most underserved addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Japan's banking geography. Tokyo megabanks prioritize real-time fraud detection infrastructure while regional institutions in peripheral prefectures favor outsourced compliance automation over captive analytics builds.
Kanto/Tokyo
Tokyo's megabanks anchor national demand for personalized wealth management platforms and sub-second payment anomaly detection. The Financial Services Agency's explainability mandates compel institutions to replace legacy batch systems with streaming infrastructure. Post-merger integration across the Tokyo banking cluster generates concentrated procurement of unified governance platforms.
Kansai/Osaka
Osaka's regional banking networks adopt hybrid explainable AI architectures faster than Tokyo counterparts due to lighter technical debt burdens. METI's trustworthy-AI guidance hardens into procurement standards that disqualify opaque algorithms. The Osaka-Fukuoka corridor drives demand for modular fraud detection pilots independent of core system overhauls.
Chubu/Nagoya
Tier-2 regional banks in Nagoya favor managed services arrangements to bypass specialized talent scarcity constraints. JIS Q 15001 privacy certification timelines extend vendor onboarding cycles, compressing effective contract windows. Post-consolidation data lake integration across merged institutions creates demand for outsourced model governance.
Kyushu
Fukuoka's banking cluster leads deployment of neural network architectures for payment anomaly detection across unstructured data streams. The Bank of Japan's FinTech Innovation Hub pilots normalize sub-second detection as operational baseline. Regional institutions here embed analytics directly into customer-facing mobile applications.
Hokkaido and Tohoku
Rural credit unions and cooperative banks in these northern prefectures present the most underserved addressable market. These institutions prioritize regulatory compliance automation over predictive capabilities through shared service arrangements. Behavioral analytics deployment in wealth management remains untapped, offering first-mover positioning ahead of megabank expansion.
Japan Data Analytics in Banking Market Competitive Landscape
Capability concentration sits with domestic system integrators possessing deep core banking relationships; scale advantage sits with megabank captive technology arms. The market structures around three tiers: entrenched infrastructure vendors, financial group technology subsidiaries, and emerging specialized analytics boutiques. Two competitive moves dominate: subscription-based commercial model displacement of perpetual licensing, and unbundling of analytics procurement from parallel infrastructure refresh programs.
Within the domestic infrastructure tier, NTT DATA anchors long-term client relationships through core system integration depth. MUFG and Mizuho Financial Group exemplify the captive technology arm archetype, with the former developing in-house risk scoring tools and the latter embedding analytics into mobile customer interfaces. These three entities collectively represent the competitive poles around which procurement decisions orbit.
| Leading Market Players |
|---|
| NTT DATA |
| Finatext Ltd. |
| SDKI Analytics |
| MUFG |
| Mizuho Financial Group |
| SMBC |
| SBI Holdings |
| Sumitomo Mitsui Financial Group |
| Resona Holdings |
| Others |
Pricing and Supply Chain Analysis
NTT DATA's entrenched position in domestic core banking system integration anchors upstream supply concentration, directing margin pools toward vendors with established JIS Q 15001 compliance track records and long-term client retention mechanisms.
Pricing Analysis
Long-term subscription contracts dominate procurement structures, displacing one-time implementation fees across Tokyo megabanks and regional institutions alike. Pricing stratifies across premium interpretable-AI tiers, standard predictive analytics modules, and economy-tier compliance automation bundles, with FSA explainability mandates driving tier selection. Cost compression in economy-tier managed services is intensifying because tier-2 regional banks prioritize outsourced governance over captive capability builds. Regional banks in Hokkaido and Tohoku exhibit highest price sensitivity; megabanks pursuing real-time fraud detection infrastructure show lowest sensitivity due to operational risk exposure.
Supply Chain Analysis
Japan's export-control regime on advanced semiconductor components constrains domestic access to GPU clusters essential for neural network training, forcing institutions toward hybrid cloud architectures with localized inference nodes. Supply draws from domestic system integrators, U.S.-based cloud hyperscalers, and South Korean memory component suppliers. Raw material dependencies center on high-bandwidth memory modules, specialized AI accelerators, and encrypted data storage infrastructure. Single-source vulnerability sits with NTT DATA's core banking integration layer, which gates downstream analytics platform deployment. Distribution runs through direct enterprise sales teams and specialized financial services consultancies serving the consolidated banking sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as FSA explainability mandates splinter procurement requirements across institution tiers, creating specialized niches for interpretable-AI vendors and compliance-focused managed services providers.
For Market Incumbents: Harden defensive positioning by deepening JIS Q 15001 certification moats and embedding analytics directly into customer-facing mobile interfaces before emerging boutiques capture modular fraud detection contracts. Threat vectors include specialized boutiques unbundling analytics procurement from core system overhauls. Vertical integration into model governance documentation services represents the priority lever for sustaining recurring revenue streams. For New Entrants and Emerging Players: Hokkaido and Tohoku regional markets offer the most penetrable white-space for behavioral analytics in wealth management, where megabanks have deferred expansion. Credit unions in rural prefectures present concentrated demand for shared-service compliance automation with limited incumbent penetration. A direct go-to-market angle through agricultural cooperative banking networks bypasses NTT DATA's core system integration barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed analytics boutiques possessing FSA pre-approved algorithmic transparency frameworks but lacking scale for megabank procurement cycles. Long-term viability favors platforms with demonstrated compliance refresh capabilities across multiple regulatory rule updates. The signal to watch is accelerated regional bank consolidation in Fukuoka and Osaka, which would trigger concentrated demand for unified governance platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding analytics into MUFG's core risk scoring infrastructure reduces manual underwriting latency. |
| Strategic Partnership | Alignment with Bank of Japan's FinTech Innovation Hub normalizes sub-second anomaly detection standards. |
| Geographic Expansion | Entry into Hokkaido credit unions captures underserved compliance automation demand ahead of megabank arrival. |
| Acquisition of Specialist Firm | Purchase of interpretable-AI boutiques satisfies FSA procurement standards disqualifying opaque algorithms. |
| Product Launch | Modular fraud detection pilots independent of core overhauls shorten regional bank vendor selection cycles. |
Research Methodology
Initial hypotheses were tested against primary input from chief data officers at megabanks, regional bank IT procurement leads, FSA regulatory policy specialists, and managed services vendor account executives, then refined against secondary validation from FSA guideline publications, Bank of Japan FinTech Hub pilot documentation, METI trustworthy-AI framework releases, and JIS Q 15001 certification records. Bottom-up sizing of individual institution procurement pipelines combined with top-down reconciliation against aggregate banking sector technology expenditure estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling technology type, application use case, service delivery model, and end-user tier segmentation dimensions. CAGRs were derived through regression analysis of historical procurement velocity adjusted for regulatory mandate implementation timelines. Forecast inputs incorporated FSA explainability compliance deadlines and regional bank consolidation trajectories.
Macroeconomic conditions sit as an overlay; deviation in yen-denominated technology investment cycles or cross-border data localization enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on regulatory rule refresh frequency and vendor onboarding timeline stability. Material shifts in FSA third-party risk management expectations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Machine Learning in Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Banking Wearable Devices Market
Banking
South America Challenger Banks Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
Blockchain in Banking Market
Banking
Cybersecurity in Banking Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Global Neobanking Market
Banking
Global Banking BPS Market
Banking
Retail Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
China Retail Banking System Market
Banking
Investment Banking Market
Banking
US Commercial Banking Market