
 Europe Plant Growth Chambers Market | 2026-2036
Europe Plant Growth Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant Growth Chambers Market Intelligence
Academic laboratories are collapsing into the dominant buyer archetype for European plant growth chambers, displacing smaller commercial growers who lack capital for precision climate infrastructure. Binder GmbH leverages its Tuttlingen manufacturing base to dominate German-speaking research markets. Weiss Technik GmbH anchors its position through Reiskirchen production capacity and deep relationships with Fraunhofer institutes. Conviron competes on software-integrated chamber platforms that synchronize with LIMS protocols across European university networks.
Plant growth chambers are enclosed environmental cabinets that regulate temperature, humidity, light spectrum, and CO₂ concentration within programmable parameters, typically spanning −10°C to 60°C and 20% to 98% relative humidity, enabling reproducible phenotyping for crop science. Their primary commercial purpose is to compress generational cycles for breeding programs and standardize experimental conditions across multi-site research collaborations. LED technology leads installed capacity due to spectral tunability and compliance with EU ecodesign directives, while germination chambers command premium pricing from seed companies pursuing accelerated variety development. Climate chambers with integrated F-Gas-compliant refrigeration represent the fastest-growing configuration as institutions retrofit legacy fluorinated equipment.
EMA guidelines on genetically modified organism containment, REACH substance restrictions on chamber construction materials, and the EU Green Deal carbon-border adjustments collectively elevate compliance costs for imported systems while favoring regional manufacturers with certified supply chains. The F-Gas Regulation specifically mandates phasedown of hydrofluorocarbon-based cooling, redirecting procurement toward hydrocarbon or CO₂-cooled platforms from European OEMs. Stakeholders must monitor revision timelines for the EU AI Act as automated phenotyping analytics migrate into chamber control software, since algorithmic decision-making in agricultural research may trigger forthcoming conformity assessment obligations.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale refrigeration transition across European research infrastructure, compressing replacement cycles for legacy climate chambers and redirecting procurement toward hydrocarbon-cooled platforms from regional OEMs.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Agricultural research institutes accelerate controlled-environment investments to demonstrate compliance with sustainability disclosure mandates under CSRD.
- Spectral tunability of LED arrays:Plant science programs demand programmable light recipes for reproducible phenotyping, displacing legacy fluorescent and high-pressure sodium systems.
- Seed company consolidation:Bayer and Syngenta breeding operations in the Netherlands and Germany drive premium chamber procurement for accelerated variety development cycles.
Market Restraints
- Copper and aluminum price volatility:Refrigeration coil and heat exchanger fabrication costs fluctuate with commodity markets, squeezing margins for mid-tier chamber manufacturers.
- German component supply concentration:Compressor and precision sensor sourcing clusters in Baden-Württemberg and Bavaria create geographic vulnerability for non-domestic assemblers.
- REACH substance restrictions:Chamber insulation foams and coating materials face phasedown of legacy chemical formulations, extending R&D timelines for certified alternatives.
Strategic Opportunities
- Polish and Romanian agricultural universities:Underpenetrated precision agriculture research infrastructure offers first-mover positioning for chamber vendors establishing regional service networks.
- EU AI Act algorithmic conformity:Automated phenotyping analytics embedded in chamber control software trigger forthcoming assessment obligations, creating compliance-service revenue streams.
- Cloud-based chamber telemetry:Remote monitoring platforms enable predictive maintenance subscriptions, shifting revenue from hardware sales to recurring service contracts.
Industry Challenges
- Refrigeration technician scarcity:Specialized hydrocarbon and CO₂ cooling system expertise remains concentrated among German and Danish engineering workforces, constraining installation capacity.
- LIMS protocol integration:University procurement committees demand seamless data handoff between chamber controllers and laboratory information management systems, extending sales cycles for non-integrated vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant Growth Chambers Market |
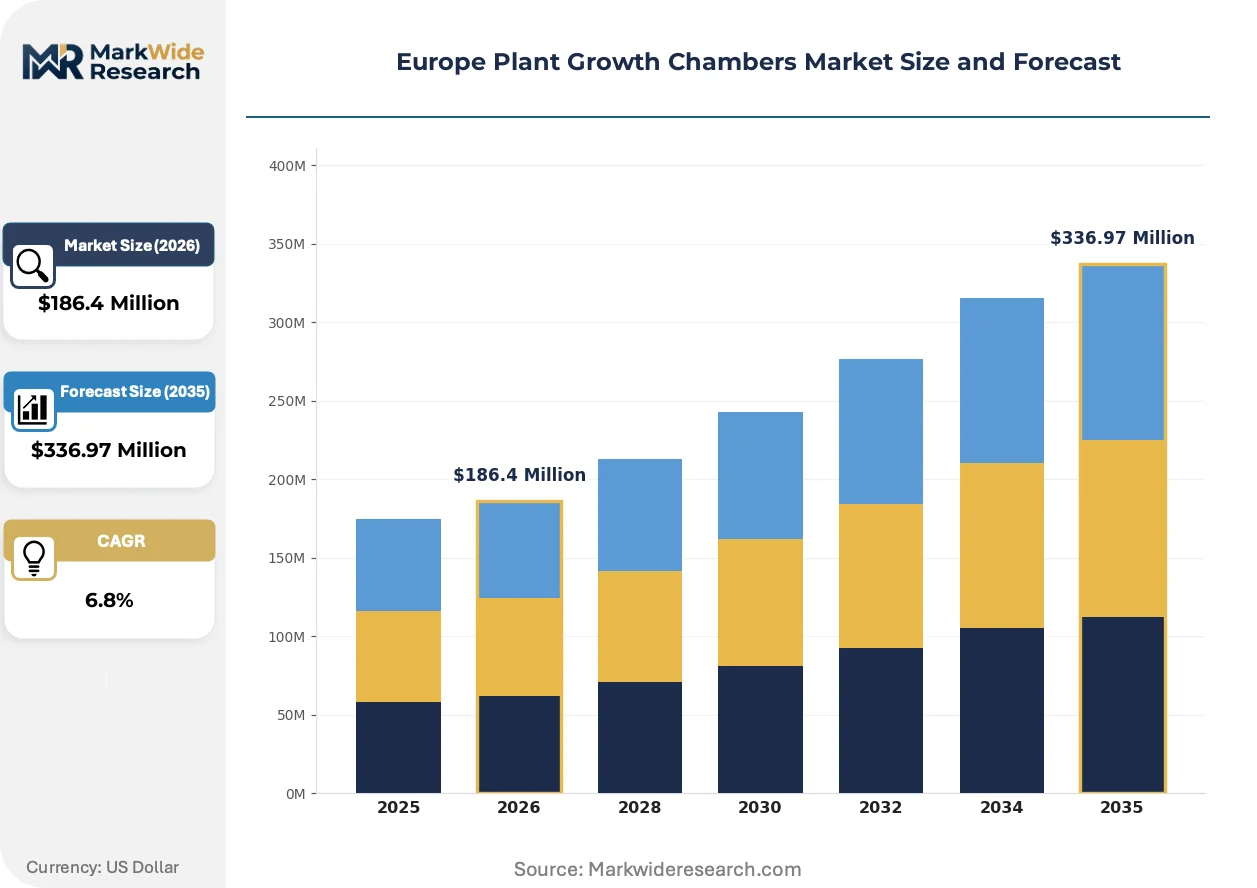
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $336.97 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Germination Chambers, Growth Chambers, Climate Chambers, Plant Propagation Systems Technology: LED, Fluorescent, High-Intensity Discharge, Others End User: Agricultural Research Institutions, Universities, Commercial Growers, Botanical Gardens Application: Plant Breeding, Research and Development, Tissue Culture, Crop Yield Optimization |
| Companies Covered | Binder GmbH, Weiss Technik GmbH, Conviron, Percival Scientific, Aralab, Memmert GmbH + Co. KG, Hettich Benelux B.V., CLF PlantClimatics GmbH, Dycometal S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant Growth Chambers Market Strategic Shifts & Innovations
LED-based illumination architectures are actively displacing legacy lighting across European plant science infrastructure, while regulatory pressure on fluorinated refrigerants accelerates platform redesign. Software-integrated phenotyping systems now synchronize experimental protocols across multi-site research collaborations.
Solid-state LED arrays with programmable spectral output are bifurcating the installed base between premium tunable systems and fixed-spectrum economy configurations. Max Planck Institutes and Wageningen University research clusters adopt full-spectrum platforms within eighteen-month refresh cycles. This technology compression is collapsing generational breeding timelines from five years to thirty-six months for major cereal programs.
The EU F-Gas Regulation mandates an eighty-percent phasedown of hydrofluorocarbon refrigerants by 2030, forcing institutional procurement committees to prioritize hydrocarbon or transcritical CO₂ cooling architectures. German Fraunhofer institutes and French INRAE facilities face accelerated replacement schedules for legacy chambers. Climate chamber OEMs with Reiskirchen or Tuttlingen manufacturing footprints capture retrofit contracts through certified regional supply chains.
Consolidated buying committees at multi-campus European universities now mandate outcome-based service agreements spanning installation, calibration, and predictive maintenance. Traditional distributor networks lose ground to direct OEM relationships with centralized procurement functions. This channel compression is most visible in Dutch and Belgian agricultural research consortia coordinating cross-border phenotyping protocols.
Europe Plant Growth Chambers Market Segmentation
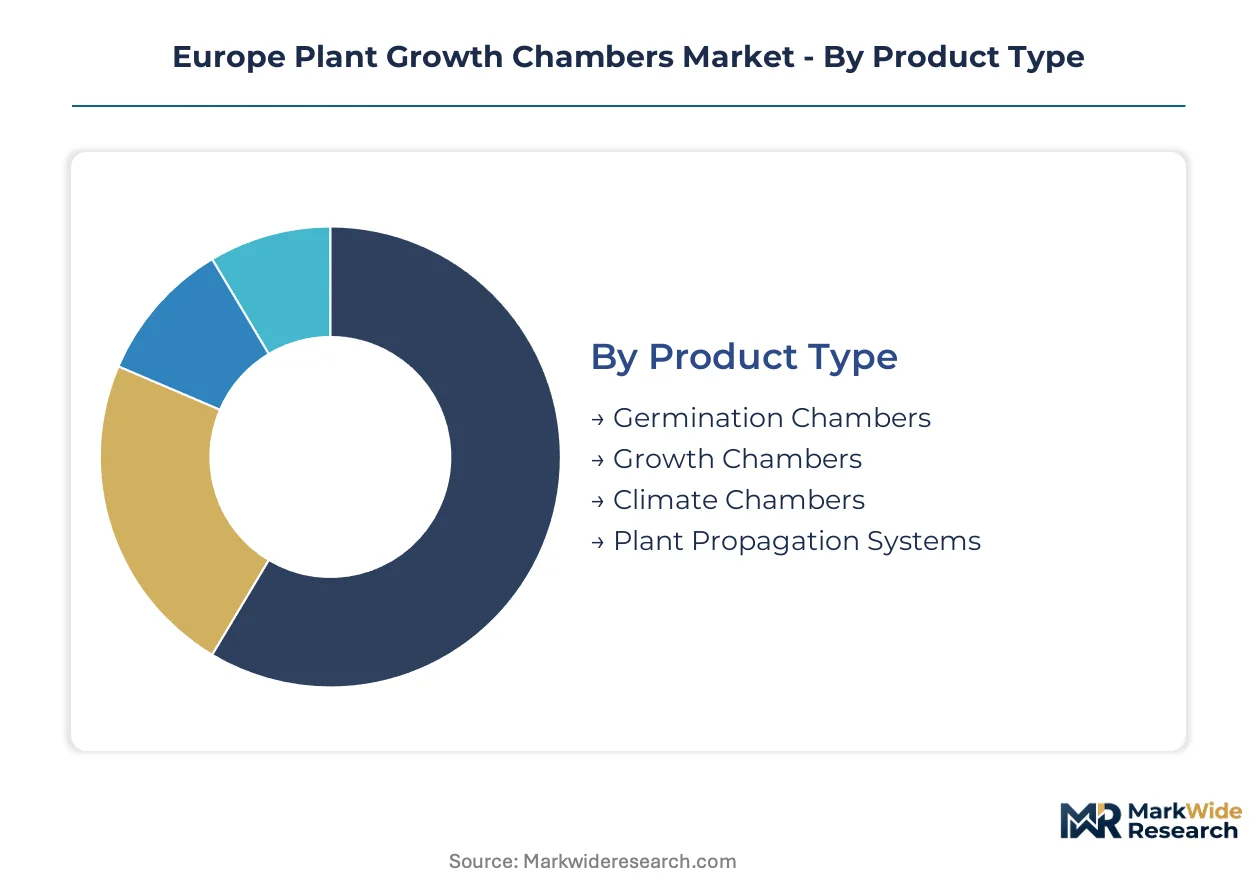
European research procurement committees segment plant growth chamber investments by environmental precision requirements and regulatory compliance tiers. Each segmentation axis reveals distinct substitution pressures as LED architectures displace legacy lighting and hydrocarbon cooling replaces fluorinated refrigerants.
Product Type:
LED-based spectral tunability is collapsing demand for fixed-environment legacy cabinets, forcing product-level substitution across German and Dutch research clusters.
- Growth Chambers:Enclosed cabinets regulate temperature, humidity, light spectrum, and CO₂ across programmable parameters from −10°C to 60°C. Max Planck Institutes and Wageningen University coordinate multi-site phenotyping protocols through these platforms, compressing generational breeding timelines.
- Climate Chambers:Integrated F-Gas-compliant refrigeration architectures with hydrocarbon or transcritical CO₂ cooling dominate Fraunhofer and INRAE retrofit schedules. REACH-certified insulation foams and coating materials extend R&D timelines for certified supply chains.
- Germination Chambers:Seed companies in the Netherlands pursue accelerated variety development through premium temperature and humidity control for early-stage propagation.
- Plant Propagation Systems:Modular configurations serve botanical gardens and commercial tissue culture operations across Belgium and France.
Growth chambers retain volume leadership; climate chambers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium tunable arrays from economy fixed-spectrum installations across European university networks.
- LED:Solid-state arrays with programmable spectral output enable reproducible light recipes for phenotyping standardization. Full-spectrum platforms refresh within eighteen-month cycles at leading German and Dutch research institutes.
- Fluorescent:Legacy installations face accelerated replacement as EU ecodesign directives elevate energy efficiency mandates for research infrastructure procurement.
- High-Intensity Discharge:High-pressure sodium systems persist in economy-tier commercial grower segments lacking capital for precision climate infrastructure.
- Others:Emerging plasma and laser diode architectures target specialized photobiology applications at niche research facilities.
LED installations command the premium tier; fluorescent retrofits dominate replacement volume.
End User:
Customer type concentration shifts procurement power toward consolidated academic buyers with centralized technical specifications.
- Agricultural Research Institutions:Fraunhofer institutes and INRAE facilities mandate F-Gas-compliant cooling and LIMS-integrated telemetry for cross-border phenotyping collaborations.
- Universities:Multi-campus buying committees in the Netherlands and Belgium negotiate outcome-based service agreements spanning installation, calibration, and predictive maintenance subscriptions.
- Commercial Growers:Capital constraints exclude smaller operators from precision climate infrastructure, collapsing this segment's procurement share.
- Botanical Gardens:Conservation-focused institutions prioritize germination chambers for rare species propagation under controlled conditions.
Agricultural research institutions anchor procurement volume; universities are expanding most quickly through consolidated tender processes.
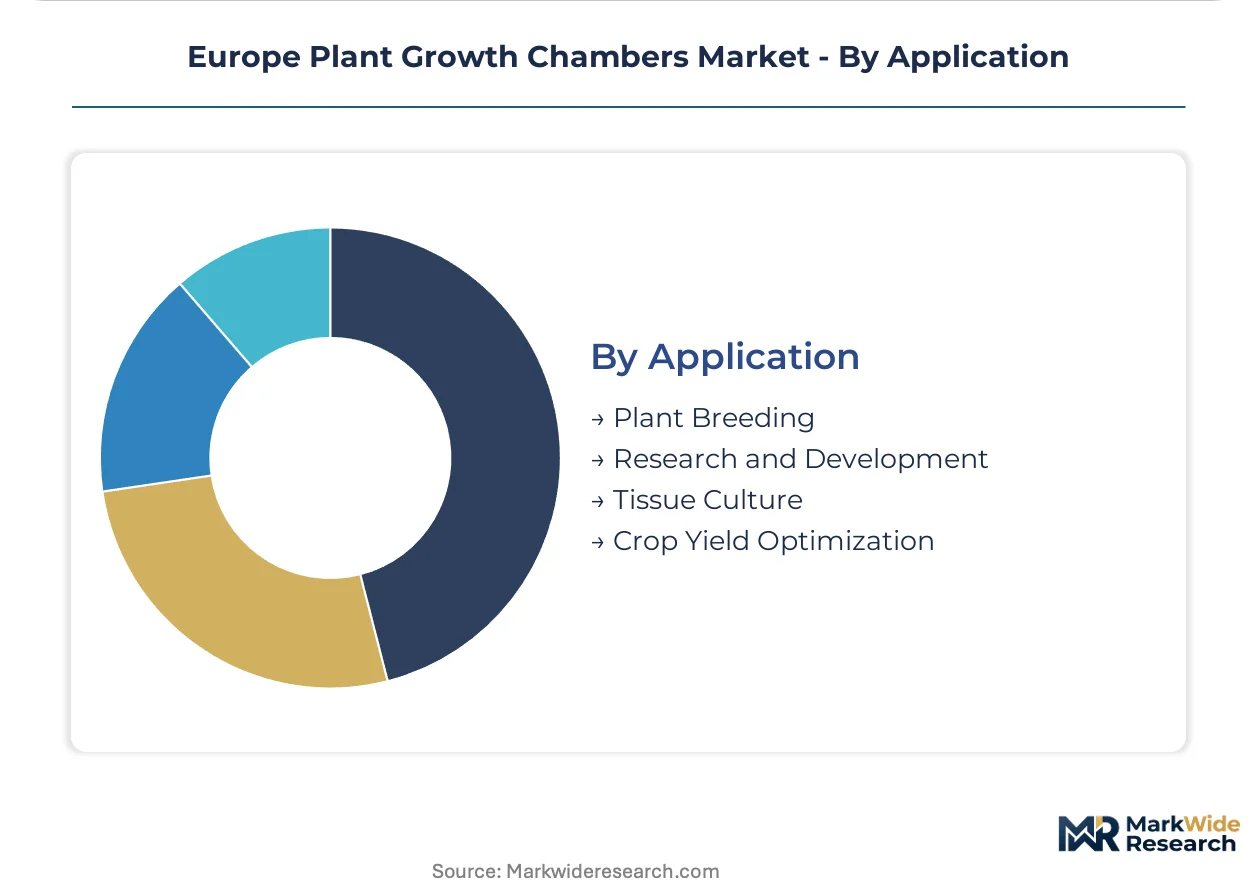
Application:
Application maturity separates established breeding programs from emerging automated phenotyping workflows subject to forthcoming EU AI Act conformity assessments.
- Plant Breeding:Bayer and Syngenta operations in Germany and the Netherlands compress variety development cycles from five years to thirty-six months through controlled-environment generational acceleration.
- Research and Development:EMA guidelines on genetically modified organism containment elevate compliance costs for chamber specifications at European agricultural biotechnology facilities.
- Tissue Culture:Botanical gardens and specialized propagation laboratories demand sterile environmental control for micropropagation protocols.
- Crop Yield Optimization:Automated phenotyping analytics embedded in chamber control software trigger algorithmic conformity obligations under revision timelines for the EU AI Act.
Plant breeding retains volume leadership; crop yield optimization gains share fastest through AI-integrated platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic laboratories concentrate procurement power across European plant growth chambers, with consolidated buying committees at multi-campus universities displacing fragmented commercial grower demand. Germany, France, and the Netherlands anchor volume, while Poland and Romania emerge as underpenetrated expansion targets.
Germany
Fraunhofer institutes and Max Planck research clusters drive premium chamber procurement for cross-border phenotyping collaborations. The F-Gas Regulation mandates hydrocarbon-cooled retrofits, compressing replacement cycles for legacy climate infrastructure. Tuttlingen and Reiskirchen manufacturing bases supply certified regional OEMs capturing institutional retrofit contracts.
Netherlands
Wageningen University coordinates multi-site breeding protocols, compressing generational timelines for Bayer and Syngenta seed operations. The EU Green Deal carbon-border adjustments accelerate controlled-environment investments under CSRD disclosure mandates. Randstad agricultural research consortia negotiate outcome-based service agreements spanning calibration and predictive maintenance.
France
INRAE facilities face accelerated replacement schedules for fluorinated-refrigerant chambers under EU F-Gas phasedown requirements. REACH substance restrictions on insulation foams extend R&D timelines for certified supply chains. Auvergne-Rhône-Alpes and Île-de-France research clusters prioritize LIMS-integrated telemetry platforms.
Belgium
Cross-border phenotyping networks with Dutch consortia drive demand for software-synchronized chamber platforms. EMA guidelines on genetically modified organism containment elevate compliance specifications for agricultural biotechnology facilities. Brussels-based procurement committees mandate seamless data handoff between controllers and laboratory information management systems.
Poland
Agricultural universities in Warsaw and Kraków represent underpenetrated precision agriculture research infrastructure. EU structural funds channel investment toward controlled-environment capacity building. Regional service network establishment offers first-mover positioning for chamber vendors targeting eastward expansion.
Europe Plant Growth Chambers Market Key Industry Players
Player mix skews toward specialized European OEMs with certified regional supply chains, creating a tiered structure where manufacturing proximity to research clusters determines contract capture. German and Benelux fabricators anchor the premium tier through Fraunhofer and INRAE relationships, while mid-tier assemblers compete on retrofit timing. Two strategic archetypes dominate: integrated platform vendors bundling software-telemetry with hardware, and component-specialist fabricators focusing on refrigeration and LED subsystem supply. Competitive moves center on direct OEM relationships with centralized university procurement functions and predictive maintenance subscription models displacing traditional distributor networks.
Among German-based fabricators, Binder GmbH and Weiss Technik GmbH exemplify the integrated-platform archetype through their Baden-Württemberg and Hesse manufacturing footprints. Conviron occupies a position representing North American-origin competition focused on software-integrated phenotyping systems. These three names illustrate how geographic certification and LIMS-protocol integration separate contract winners from distributor-dependent challengers in consolidated European tenders.
| Leading Market Players |
|---|
| Binder GmbH |
| Weiss Technik GmbH |
| Conviron |
| Percival Scientific |
| Aralab |
| Memmert GmbH + Co. KG |
| Hettich Benelux B.V. |
| CLF PlantClimatics GmbH |
| Dycometal S.A. |
| Others |
Cost & Logistics Intelligence
LED array substitution for legacy fluorescent and high-pressure sodium systems simultaneously reshapes supply geography toward German and Dutch component clusters and compresses pricing economics across premium tunable and fixed-spectrum economy tiers. Procurement committees now weight spectral programmability against total cost of ownership, redirecting margin capture toward OEMs with captive LED subsystem production.
Pricing Analysis
Technology-generation pricing gaps separate full-spectrum LED platforms from fluorescent retrofits and economy fixed-spectrum installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from copper and aluminum commodity volatility squeezing refrigeration coil fabrication costs. Commercial growers exhibit highest price sensitivity, while consolidated academic buyers prioritize LIMS integration and predictive maintenance subscriptions over unit economics.
Supply Chain Analysis
Germany anchors compressor and precision sensor production across Baden-Württemberg and Bavaria manufacturing clusters. Refrigeration coil fabrication draws from regional aluminum and copper processing, while LED array assembly centers on Dutch and German optoelectronics facilities. Single-source vulnerability concentrates in hydrocarbon cooling system expertise among German and Danish engineering workforces. Distribution runs through direct OEM relationships with centralized university procurement functions, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against modular plant propagation systems that threaten to displace enclosed climate chambers in tissue culture applications through lower capital intensity and faster deployment timelines.
For Market Incumbents: Fortify position through backward integration into LED subsystem production and hydrocarbon refrigeration certification programs. Capture Fraunhofer and INRAE retrofit cycles by accelerating F-Gas-compliant platform availability ahead of regional competitors. Channel control through direct procurement relationships with Dutch and Belgian agricultural research consortia remains essential. For New Entrants and Emerging Players: REACH-certified insulation foam fast-tracks offer entry path into climate chamber retrofits as legacy formulations face phasedown. Polish and Romanian agricultural universities represent most penetrable geography, with EU structural funds financing controlled-environment capacity building. Cloud-based telemetry subscriptions enable recurring revenue models that offset hardware margin compression. For Investors and Strategic Acquirers: The market sits at a regulatory-forced replacement phase that favors integrated platform vendors with certified regional supply chains. Long-term viability rests on software-telemetry bundling and predictive maintenance contract penetration. Watch EU AI Act revision timelines as algorithmic conformity obligations for automated phenotyping analytics signal inflection toward compliance-service revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| F-Gas-Compliant Platform Transition | Captures Fraunhofer and INRAE retrofit contracts ahead of hydrocarbon cooling mandates. |
| LED Subsystem Backward Integration | Secures spectral tunability margins against fluorescent displacement economics. |
| LIMS Protocol Integration Investment | Meets Wageningen University and Belgian consortium data handoff requirements. |
| Polish Service Network Establishment | Positions first-mover advantage in EU structural fund-financed research infrastructure. |
| Predictive Maintenance Subscription Launch | Shifts revenue from hardware sales to recurring contracts with Dutch Randstad consortia. |
Research Approach
Findings reconcile primary fieldwork against secondary review of ECHA substance restriction databases, EU F-Gas Regulation implementation reports, and agricultural research institute procurement disclosures. Primary interviews engaged chamber OEM technical directors, university procurement committee chairs, and Fraunhofer institute facility managers. Secondary validation incorporated REACH certification registries, CSRD sustainability disclosure filings, and LED component trade flow data. Bottom-up unit demand modeling triangulates against top-down research infrastructure investment tracking.
Segmentation dimensions modeled span product type, illumination technology, end-user category, and application purpose across the analysis window. Growth trajectory derivation incorporates replacement cycle compression from F-Gas Regulation mandates and spectral tunability adoption curves at Max Planck and Wageningen research clusters. Forecast inputs include hydrocarbon cooling technician availability constraints and EU AI Act algorithmic conformity timeline uncertainty.
Underlying assumptions cover F-Gas phasedown adherence schedules and copper-aluminum commodity stabilization, with deviation risk concentrated in REACH substance restriction acceleration and EU structural fund allocation shifts. Recalibration cycles align with material shifts in refrigerant regulation implementation and LED component cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
United States Plant Growth Chambers Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Spain Commercial Green House Market
Indoor Farming Technologies
Grow Tents Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
Plant Growth Chambers Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
Middle East Vertical Farming Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Aeroponics Market